
 Europe Gamma Butyrolactone Market | 2026-2036
Europe Gamma Butyrolactone Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gamma Butyrolactone Market Intelligence
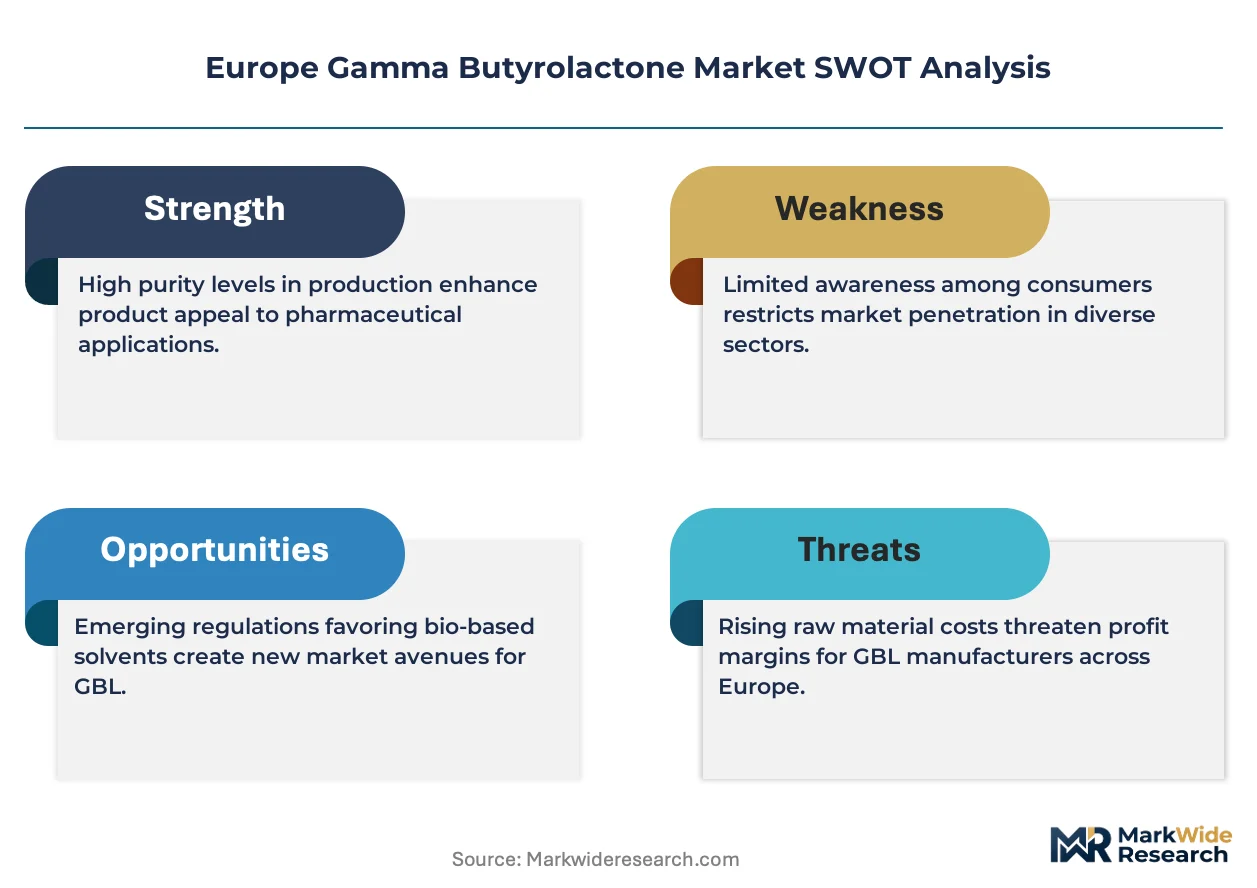
The European Gamma Butyrolactone market is consolidating around a widening split between pharmaceutical-grade purity tiers and commodity solvent grades. BASF SE leverages its integrated Ludwigshafen complex to dominate high-purity production for regulated applications. Arkema Group anchors its position through specialized BDO-GBL integration chemistry serving polymer precursor demand.
Gamma butyrolactone (GBL) is a colorless hygroscopic liquid with a boiling point of 204°C and a molecular formula C₄H₆O₂, manufactured primarily via catalytic dehydrogenation of 1,4-butanediol for use as a polar aprotic solvent and chemical intermediate. The pharmaceutical application segment leads value generation due to stringent purity requirements and validated supply chain documentation. Chemical intermediate demand sustains volume leadership through downstream N-methylpyrrolidone and pyrrolidone derivative production.
REACH registration obligations and the EU Green Deal's sustainable chemistry mandates shape product standards and market access across European manufacturing. ECHA substance evaluation protocols enforce purity thresholds that differentiate compliant suppliers from marginal operators. Stakeholders must monitor bio-based feedstock certification schemes and carbon border adjustment mechanisms to secure long-term supply contracts.
Market Dynamics
REACH substance evaluation protocols are compressing supplier margins while accelerating consolidation around integrated BDO-GBL producers with captive hydrogen supply. ECHA purity thresholds now differentiate compliant pharmaceutical-grade suppliers from commodity solvent operators facing documentation gaps.
Growth Catalysts
- Pharmaceutical-grade solvent certification:EMA-validated supply chains for active pharmaceutical ingredient manufacturing concentrate demand among REACH-registered producers with dedicated pharmaceutical facilities.
- EU Green Deal bio-based mandates:Renewable feedstock certification schemes for 1,4-butanediol precursors open procurement pathways for carbon-accounted GBL in polymer and electronics applications.
- Netherlands chemical cluster proximity:Rotterdam-Antwerp logistics corridors reduce inland transport costs for bulk pharmaceutical intermediate shipments to German and French formulation sites.
Market Restraints
- Natural gas price volatility:Steam reforming hydrogen costs for BDO dehydrogenation fluctuate with TTF benchmark movements, compressing margins at non-integrated European producers.
- Substitution by NMP alternatives:N-methyl-2-pyrrolidone replacement with dimethyl sulfoxide in certain electronics cleaning applications reduces downstream GBL offtake for NMP synthesis.
- REACH registration cost barriers:ECHA data-sharing obligations and substance evaluation fees exclude smaller commodity solvent traders from pharmaceutical-grade market access.
Strategic Opportunities
- Polish manufacturing expansion:Lower utility costs and EU structural fund access for greenfield BDO-GBL complexes serving Central European pharmaceutical growth.
- CSRD supply chain disclosure:Corporate sustainability reporting mandates create premium pricing for carbon-footprint-documented GBL in contract manufacturing organization procurement.
- Electrolytic hydrogen integration:Renewable hydrogen feedstock coupling with BDO plants enables zero-scope bio-based GBL certification for cosmetics and food-contact applications.
Industry Challenges
- Pharmaceutical validation timelines:EMA good manufacturing practice audits and supplier qualification protocols extend contract onboarding to 18-24 months for new GBL entrants.
- Legacy BDO asset retrofit costs:Catalytic dehydrogenation reactor upgrades for pharmaceutical-grade purity require capital commitments that strain mid-scale European producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gamma Butyrolactone Market |
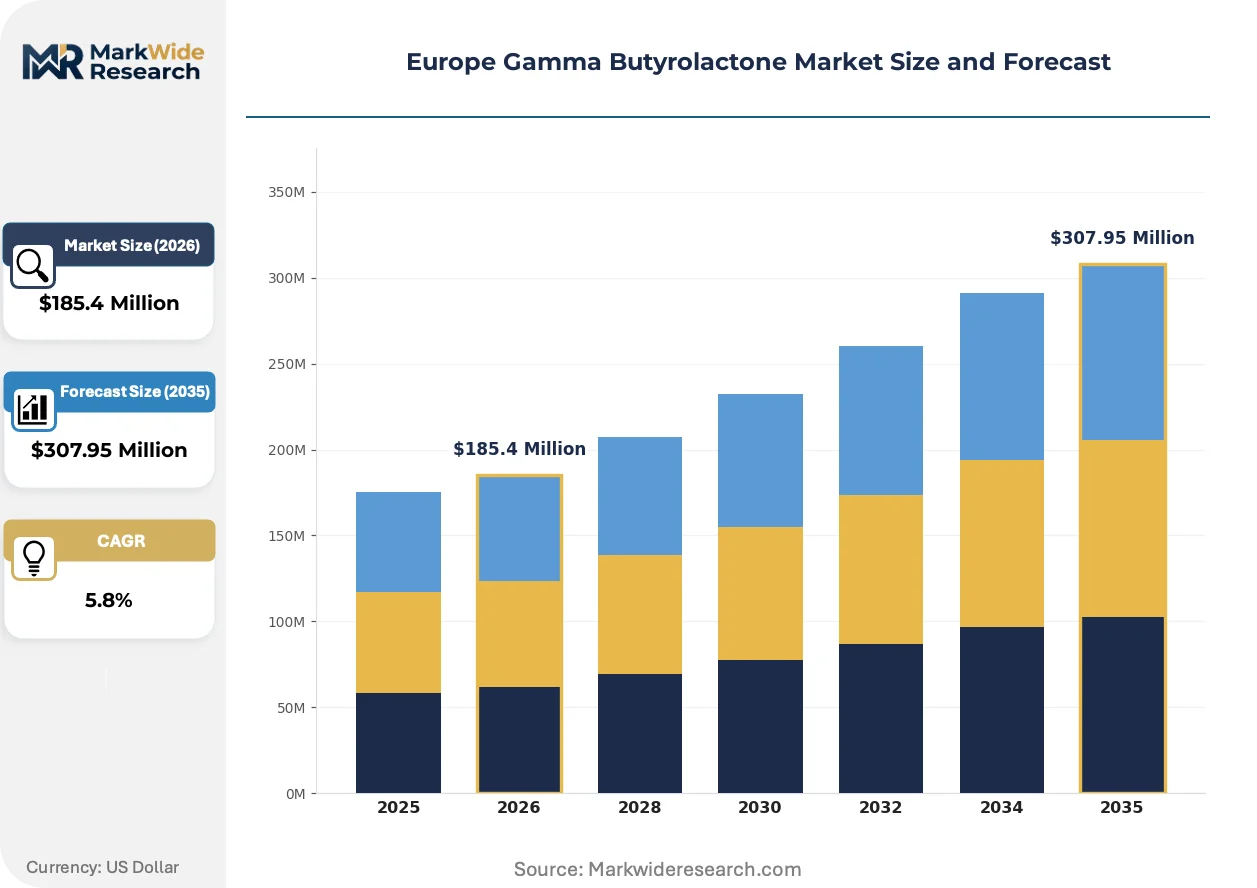
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Solvent, Chemical Intermediate, Pharmaceutical, Personal Care End User: Pharmaceuticals, Cosmetics, Food Processing, Chemicals Purity: 99%, 98%, 95%, 90% Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Ashland Global Holdings Inc, Arkema Group, BASF SE, Celanese Corporation, Lonza Group Ltd., Eastman Chemical Company, LyondellBasell Industries Holdings B.V., Novasol Chemicals, Mitsubishi Chemical Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gamma Butyrolactone Market Strategic Shifts & Innovations
Bio-based process chemistry and digital supply chain traceability are restructuring competitive differentiation in European GBL manufacturing. These shifts reward capital-intensive integrated producers while marginalizing commodity traders.
Membrane separation technology for final-stage GBL purification is decentralizing high-purity production away from centralized Ludwigshafen-scale complexes. Mid-scale Dutch and Belgian producers are adopting modular membrane units to serve regional pharmaceutical clusters without full BDO integration. This technology is compressing the minimum efficient scale for pharmaceutical-grade certification.
EU F-Gas Regulation phase-down schedules are redirecting electronics solvent demand toward GBL-based alternatives with lower global warming potential. German semiconductor fabs are qualifying GBL formulations for photoresist stripping applications previously served by perfluorinated compounds. French and Italian contract manufacturers face accelerated reformulation timelines to maintain CE-marked equipment supply contracts.
Buyer concentration among European contract manufacturing organizations is consolidating procurement through qualified supplier lists with carbon disclosure requirements. Direct long-term offtake agreements are replacing spot market purchases for pharmaceutical-grade volumes. German and Swiss pharmaceutical services firms lead this shift, demanding scope 3 emissions documentation from GBL suppliers.
Europe Gamma Butyrolactone Market Segmentation
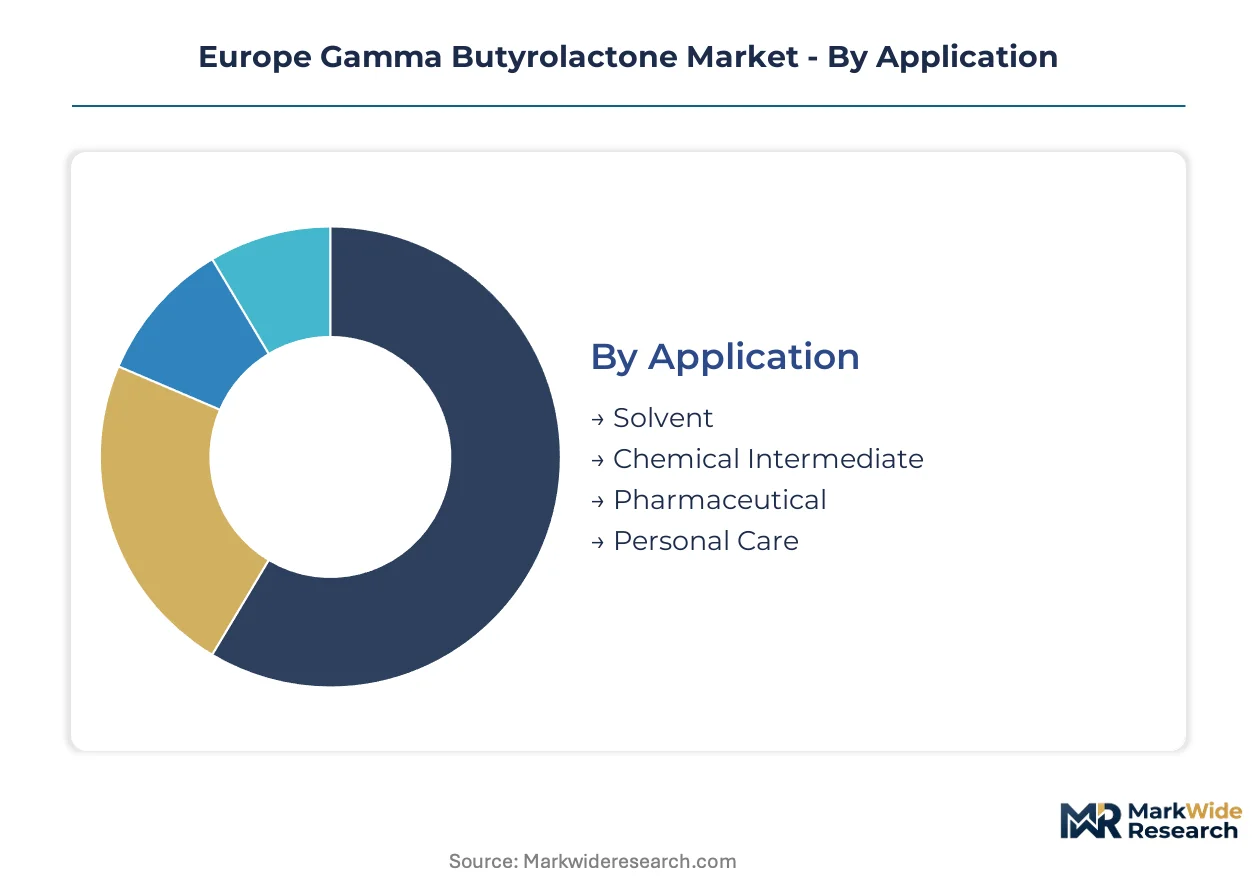
European Gamma Butyrolactone procurement patterns diverge sharply across purity tiers and application requirements. EMA validation protocols and REACH substance evaluation create rigid segmentation boundaries that determine supplier qualification and pricing power.
Application:
Replacement cycles for solvent formulations accelerate as EU F-Gas Regulation phase-downs force electronics manufacturers to abandon perfluorinated compounds. Pharmaceutical-grade certifications require 18-24 month revalidation timelines that lock end-users into qualified supplier relationships.
- Solvent:Polar aprotic solvent applications dominate volume consumption across polymer processing and electronics cleaning. German semiconductor fabs in Dresden and Munich are qualifying GBL for photoresist stripping as perfluorinated compound alternatives face regulatory phase-out.
- Chemical Intermediate:Downstream N-methylpyrrolidone and pyrrolidone derivative production sustains the largest absolute tonnage demand. Rotterdam-Antwerp logistics corridors serve this segment with bulk shipments to polymer precursor manufacturers.
- Pharmaceutical:Active pharmaceutical ingredient manufacturing demands EMA-validated supply chains with documented purity certificates.
- Personal Care:Cosmetics formulations utilize GBL as a precursor for specialty solvent systems in nail care and skin treatments.
Chemical Intermediate sits at the top of the volume ranking, with Pharmaceutical climbing the fastest.
End User:
Cost tier stratification separates validated pharmaceutical procurement from commodity chemical purchasing. Carbon disclosure mandates under CSRD are bifurcating supplier lists between documented and undocumented feedstock sources.
- Pharmaceuticals:Contract manufacturing organizations in Germany, Switzerland, and the Netherlands drive premium pricing for REACH-registered supply. EMA good manufacturing practice audits enforce supplier qualification protocols that extend contract onboarding timelines.
- Chemicals:Polymer precursor and specialty chemical manufacturers consume standard-grade volumes through Rotterdam-Antwerp bulk terminals. Natural gas price volatility compresses margins for non-integrated European producers serving this segment.
- Cosmetics:Formulators require bio-based feedstock certification for carbon-accounted GBL in premium product lines.
- Food Processing:Limited applications in food-contact packaging extraction processes face stringent EFSA purity thresholds.
Pharmaceuticals commands the steepest expansion trajectory as EMA validation requirements concentrate demand among qualified suppliers.
Purity:
Margin concentration tracks purity tier elevation, with 99% grade capturing disproportionate value share in pharmaceutical applications. Membrane separation technology is compressing minimum efficient scale for high-purity production.
- 99%:Pharmaceutical-grade specification with validated supply chain documentation for active pharmaceutical ingredient manufacturing. BASF SE's Ludwigshafen complex and specialized Dutch producers dominate this tier through integrated BDO-GBL chemistry.
- 98%:Electronics and specialty chemical applications requiring controlled impurity profiles without full pharmaceutical validation.
- 95%:Standard industrial solvent grade for polymer processing and general chemical synthesis.
- 90%:Commodity solvent tier facing margin compression from REACH registration cost barriers.
99% purity sits at the top of the value ranking, with bio-based certification variants gaining share fastest.
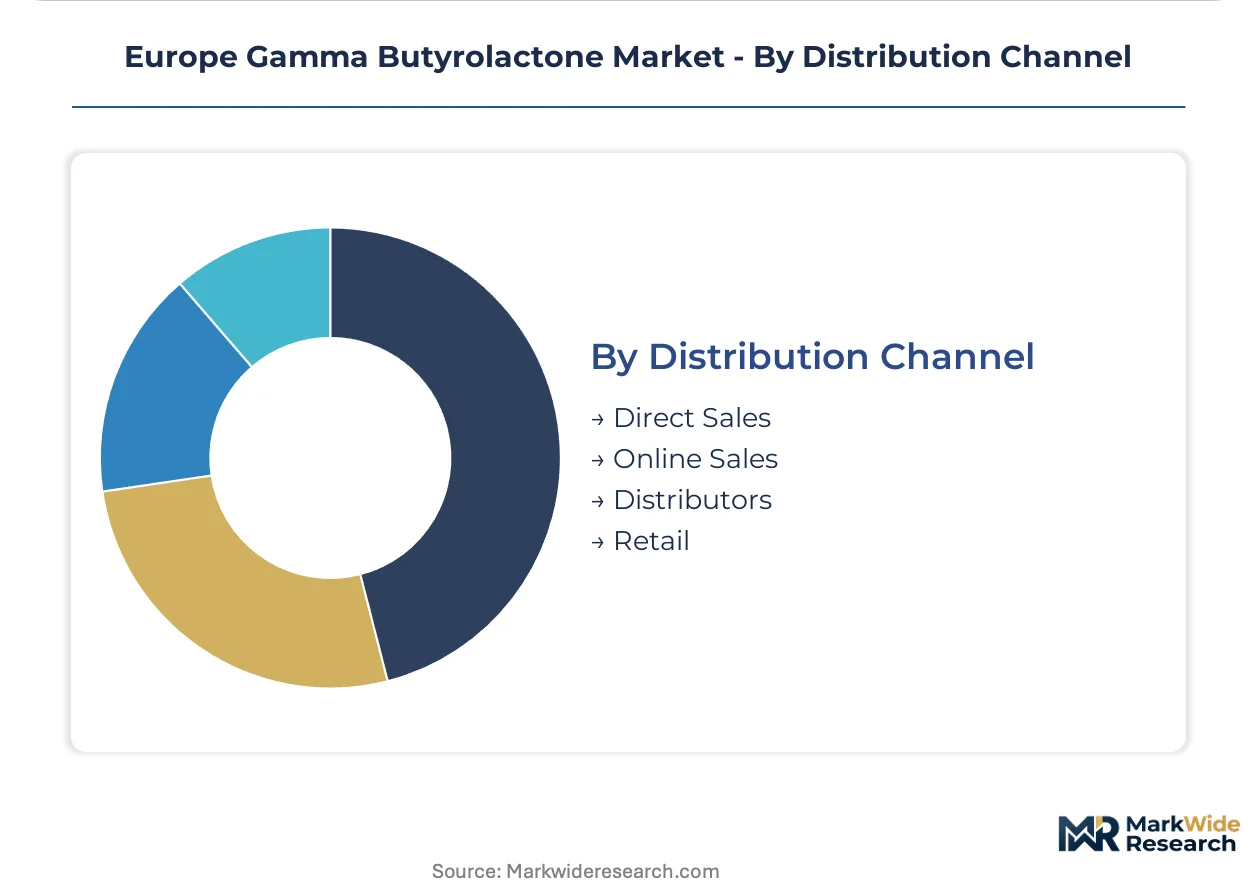
Distribution Channel:
Supply concentration favors direct relationships for pharmaceutical volumes, while commodity grades flow through distributor networks. Carbon border adjustment mechanisms are reshaping documentation requirements across all channels.
- Direct Sales:Long-term offtake agreements dominate pharmaceutical-grade procurement. German and Swiss pharmaceutical services firms demand scope 3 emissions documentation through direct supplier relationships.
- Distributors:Regional chemical distributors serve mid-scale polymer and electronics manufacturers with standard-grade volumes.
- Online Sales:Limited to small-quantity specialty chemical procurement with restricted pharmaceutical applications.
- Retail:Minimal presence confined to laboratory reagent and research chemical segments.
Direct Sales sits at the top of the value ranking, with Distributors maintaining volume leadership in standard grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters in the Rhine-Ruhr and Rotterdam-Antwerp corridors anchor European GBL production capacity. These concentrations attract integrated BDO-GBL investments from multinationals seeking REACH-compliant manufacturing bases.
Germany
Pharmaceutical contract manufacturing demand in Ludwigshafen and Leverkusen drives high-purity GBL consumption for active pharmaceutical ingredient synthesis. EMA good manufacturing practice audits enforce supplier qualification protocols that extend contract onboarding timelines. BASF SE's Ludwigshafen complex dominates pharmaceutical-grade certification through captive BDO-GBL integration.
Netherlands
Rotterdam-Antwerp logistics corridors reduce inland transport costs for bulk pharmaceutical intermediate shipments to German and French formulation sites. EU Green Deal bio-based mandates accelerate renewable feedstock certification schemes for 1,4-butanediol precursors. Mid-scale Dutch producers adopt modular membrane separation units to serve regional pharmaceutical clusters without full BDO integration.
France
Electronics solvent demand from semiconductor fabs in Grenoble and Crolles redirects GBL procurement as EU F-Gas Regulation phase-downs force perfluorinated compound abandonment. ANSM pharmaceutical oversight aligns with EMA validation requirements for imported active pharmaceutical ingredients. French contract manufacturers face accelerated reformulation timelines to maintain CE-marked equipment supply contracts.
Switzerland
Swissmedic regulatory stringency concentrates pharmaceutical-grade GBL demand among REACH-registered producers with dedicated pharmaceutical facilities. German and Swiss pharmaceutical services firms lead procurement shifts toward direct long-term offtake agreements with scope 3 emissions documentation requirements. Basel-based chemical traders coordinate carbon-accounted GBL sourcing for cosmetics and food-contact applications.
Poland
Lower utility costs and EU structural fund access attract greenfield BDO-GBL complex investments serving Central European pharmaceutical growth. ECHA substance evaluation protocols compress supplier margins while accelerating consolidation around integrated producers. Emerging manufacturing clusters near Wrocław and Poznań target German pharmaceutical supply chain integration.
Europe Gamma Butyrolactone Market Key Industry Players
Capital-heavy producers compete with asset-light distributors across purity-tiered market segments. Integrated BDO-GBL operators with captive hydrogen supply capture pharmaceutical-grade margins while commodity traders face REACH registration cost barriers. Three archetypes dominate: multinational chemical conglomerates with Ludwigshafen-scale complexes, mid-scale regional specialists with membrane purification capabilities, and asset-light distributors serving standard-grade polymer applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure renewable hydrogen feedstock agreements.
Among Germany-based chemical conglomerates, BASF SE anchors the integrated producer archetype through its Ludwigshafen manufacturing complex. Arkema Group exemplifies specialized BDO-GBL integration chemistry serving polymer precursor demand. Ashland Global Holdings Inc. occupies a position within the asset-light formulation specialist tier. These three represent distinct competitive positioning strategies: full backward integration, selective downstream integration, and formulation-focused distribution.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc |
| Arkema Group |
| BASF SE |
| Celanese Corporation |
| Lonza Group Ltd. |
| Eastman Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| Novasol Chemicals |
| Mitsubishi Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Pharmaceutical contract manufacturing organizations in Germany and Switzerland command pricing power through EMA-validated supplier qualification protocols that lock out commodity-grade competitors. Long-term offtake agreements with scope 3 emissions documentation requirements concentrate procurement among REACH-registered producers, compressing margins for distributors serving standard-grade polymer applications.
Pricing Analysis
Contract-based long-term offtake agreements dominate pharmaceutical-grade procurement, while spot-market transactions persist for commodity solvent tiers. Price differentiation hinges on EMA validation status and carbon-footprint documentation under CSRD mandates. Pricing pressure stems from natural gas cost volatility feeding into BDO dehydrogenation economics, with commodity-grade traders facing the steepest buyer price sensitivity as REACH registration costs erode competitiveness.
Supply Chain Analysis
EU Green Deal domestic-content mandates for renewable feedstock certification are reshaping sourcing patterns toward bio-based BDO precursors. Supply concentrates in Germany, the Netherlands, and Belgium, with raw material dependencies on 1,4-butanediol, catalytic hydrogen, and membrane purification equipment. Single-source vulnerability around Ludwigshafen-scale integrated complexes creates concentration risk, while Rotterdam-Antwerp logistics corridors anchor distribution through direct sales channels for pharmaceutical volumes and regional distributors for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's Gamma Butyrolactone market functions as a regulatory compounder where REACH substance evaluation protocols and EMA validation requirements continuously concentrate demand among qualified suppliers. The EU F-Gas Regulation phase-down schedule accelerates electronics solvent substitution toward GBL-based alternatives.
For Market Incumbents: Extend pharmaceutical-grade certification coverage through modular membrane separation investments at regional Dutch and Belgian sites to serve clusters without full BDO integration. Deepen backward integration into renewable hydrogen supply agreements to secure zero-scope bio-based GBL positioning against emerging Polish manufacturing entrants. For New Entrants and Emerging Players: Mid-scale cosmetics formulators in France and Italy represent an underserved buyer archetype seeking carbon-accounted GBL with bio-based feedstock certification. Target this segment through specialized small-batch membrane purification units and CSRD-compliant documentation services rather than competing head-on for pharmaceutical-grade contracts. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing BDO assets are the most active acquirer in this space, seeking membrane technology capabilities to compress minimum efficient scale. The acquisition target archetype comprises mid-scale Dutch and Belgian producers with pharmaceutical-grade membrane units but lacking captive hydrogen supply. Watch for electrolytic hydrogen project announcements at Rotterdam-Antwerp corridor sites as the inflection signal for zero-scope certification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Hydrogen | Captive electrolytic hydrogen supply enables zero-scope bio-based GBL certification for EMA-validated pharmaceutical contracts. |
| Membrane Purification Technology Deployment | Modular membrane units at Dutch sites compress minimum efficient scale for pharmaceutical-grade production without Ludwigshafen-scale BDO integration. |
| Long-term Supply Agreement with Pharma CMOs | Direct offtake contracts with German and Swiss contract manufacturers lock in premium pricing through EMA validation requirements. |
| CSRD Supply Chain Disclosure Investment | Carbon-footprint documentation capabilities capture premium procurement from sustainability-mandated pharmaceutical services firms. |
| Greenfield Manufacturing in Poland | EU structural fund access and lower utility costs position Central European sites for German pharmaceutical supply chain integration. |
Research Approach
Multiple input streams — primary interviews with plant managers and procurement leads at downstream polymer and pharmaceutical manufacturers, secondary validation through ECHA substance evaluation databases and Cefic chemical industry reports, customs trade data for BDO-GBL precursor flows — were reconciled through bottom-up and top-down triangulation. Technical R&D directors at membrane separation equipment suppliers and distribution channel partners across Rotterdam-Antwerp corridors provided operational perspective on purification economics and logistics cost structures.
Data-stream reconciliation across the projection horizon applied segmented modeling across purity tiers, application verticals, and regional production hub clusters. CAGRs were derived from demand elasticity analysis against pharmaceutical manufacturing capacity expansion and electronics solvent substitution rates under EU F-Gas Regulation timelines. Forecast inputs incorporated natural gas price volatility scenarios for steam reforming hydrogen economics and bio-based feedstock certification adoption curves.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than commodity solvent tiers due to documented EMA validation timelines and qualified supplier list concentration. Forecasts reflect assumptions around REACH registration cost trajectories and renewable hydrogen project development timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market