
 Germany Smart Healthcare Market | 2026-2036
Germany Smart Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Smart Healthcare Market Intelligence
Hospital procurement channels in Germany are reconfiguring around value-based contracting frameworks for connected medical technologies. Siemens Healthineers AG leverages its domestic manufacturing footprint to anchor large-scale imaging and diagnostics integration projects. GE Healthcare competes through specialized digital twin and AI-augmented workflow platforms tailored to German hospital networks. Abbott sustains its position via deep vertical integration into continuous glucose monitoring and cardiac rhythm management devices.
Germany smart healthcare encompasses sensor-integrated medical devices, interoperable health information systems, and algorithm-driven clinical decision tools designed to automate diagnostics, streamline care coordination, and enable remote therapeutic intervention. Systems typically incorporate FHIR-compliant data exchange protocols, edge-computing architectures for real-time vital sign processing, and machine learning models trained on anonymized German patient cohorts. Wearable devices and remote patient monitoring currently dominate hardware expenditure flows, while health analytics software captures disproportionate margin pools due to recurring licensing structures and sticky enterprise contracts. AI-enabled diagnostics represents the fastest-expanding product category as German university hospitals accelerate validation studies for regulatory clearance.
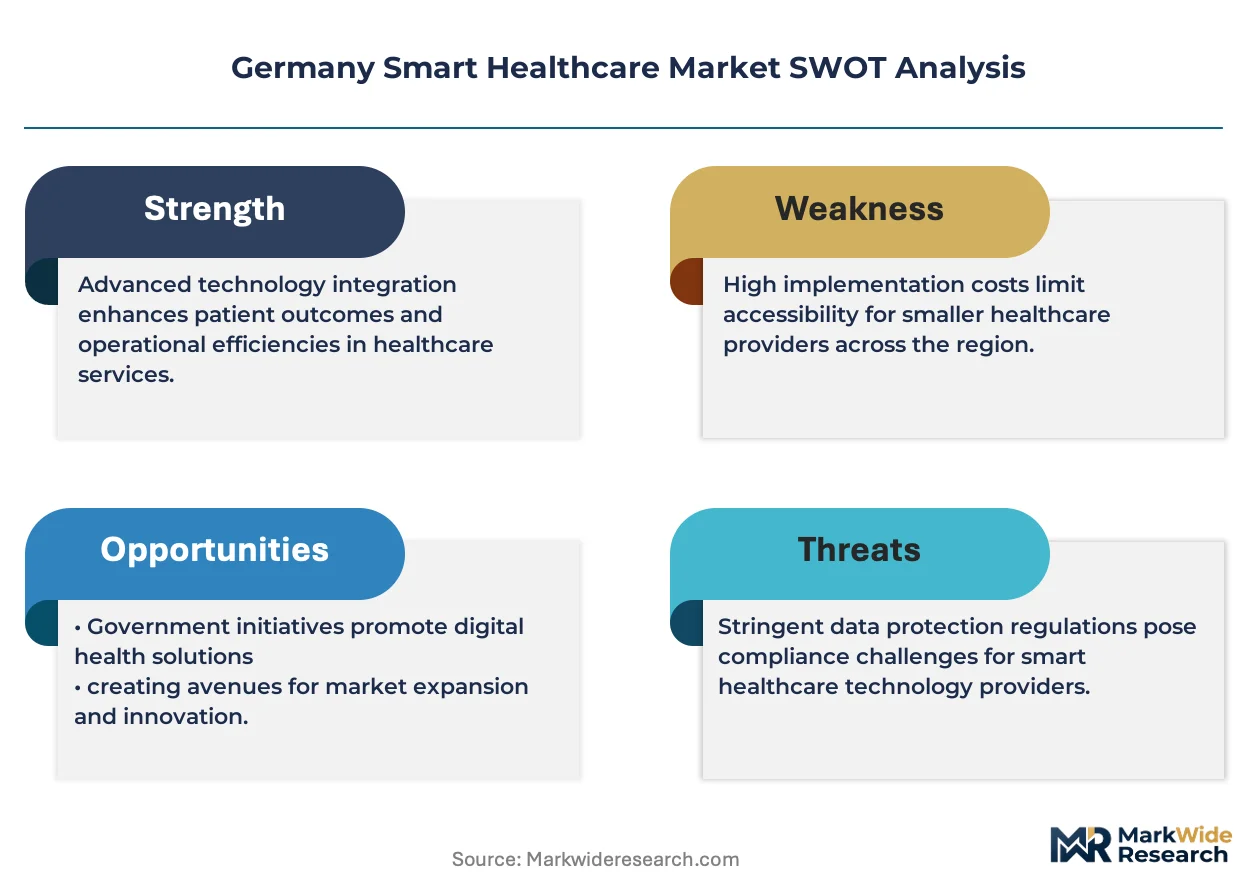
The Federal Institute for Drugs and Medical Devices (BfArM) and the Federal Office for Information Security (BSI) jointly govern software-as-medical-device classifications and cybersecurity certification requirements, creating compliance barriers that favor established domestic vendors. Germany's Digital Care Act and forthcoming European Health Data Space regulations will mandate interoperability standards that reshape procurement specifications across state hospital associations. Stakeholders must monitor BfArM's evolving fast-track pathways for digital therapeutics and position for integrated platform contracts that bundle diagnostics, monitoring, and analytics across regional care networks.
Market Dynamics
Germany's Digital Care Act reimbursement reforms are compressing provider procurement cycles and forcing hospital networks to consolidate vendor relationships around integrated platform contracts that bundle diagnostics, monitoring, and analytics.
Growth Catalysts
- Telemedicine Reimbursement:The Digital Care Act (DVG) mandates statutory health insurance coverage for video consultations and remote monitoring, accelerating provider adoption of connected care platforms across ambulatory networks.
- Chronic Disease Prevalence:Bavarian and North Rhine-Westphalian hospital systems are expanding remote patient monitoring programs to manage diabetes and cardiovascular conditions among aging populations.
- AI Diagnostics Validation:German university hospitals are accelerating clinical studies for regulatory clearance of algorithm-driven imaging and pathology tools, creating fast-track pathways through BfArM.
Market Restraints
- Cybersecurity Certification Costs:BSI technical guidelines for connected medical devices impose compliance burdens that favor established domestic vendors with dedicated regulatory affairs teams.
- Interoperability Fragmentation:Legacy hospital information systems lack FHIR-native architectures, forcing expensive middleware investments for data exchange across regional care networks.
- Semiconductor Supply Concentration:Sensor-integrated device manufacturers depend on concentrated Asian foundry capacity for MEMS components and edge-computing chipsets.
Strategic Opportunities
- European Health Data Space Alignment:Forthcoming EU regulations will mandate cross-border health data portability, positioning German vendors with existing interoperability infrastructure for platform expansion into neighboring markets.
- Elderly Care Facility Integration:Underpenetrated nursing home chains in eastern German states present white-space demand for ambient monitoring and fall-detection sensor networks.
- Digital Therapeutics Bundling:BfArM's fast-track DiGA pathway enables prescription-grade mental health and diabetes management apps to integrate with pharmaceutical reimbursement workflows.
Industry Challenges
- Clinical AI Talent Scarcity:German hospital IT departments face acute shortages of data scientists capable of validating machine learning models against local patient cohorts for BfArM submission.
- Legacy System Integration Complexity:Regional hospital associations operate heterogeneous electronic health record architectures that resist standardized API connectivity for remote monitoring data ingestion.
- CE-MDR Transition Timelines:Medical device manufacturers must recertify software-as-medical-device classifications under tightened clinical evidence requirements, compressing product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Smart Healthcare Market |
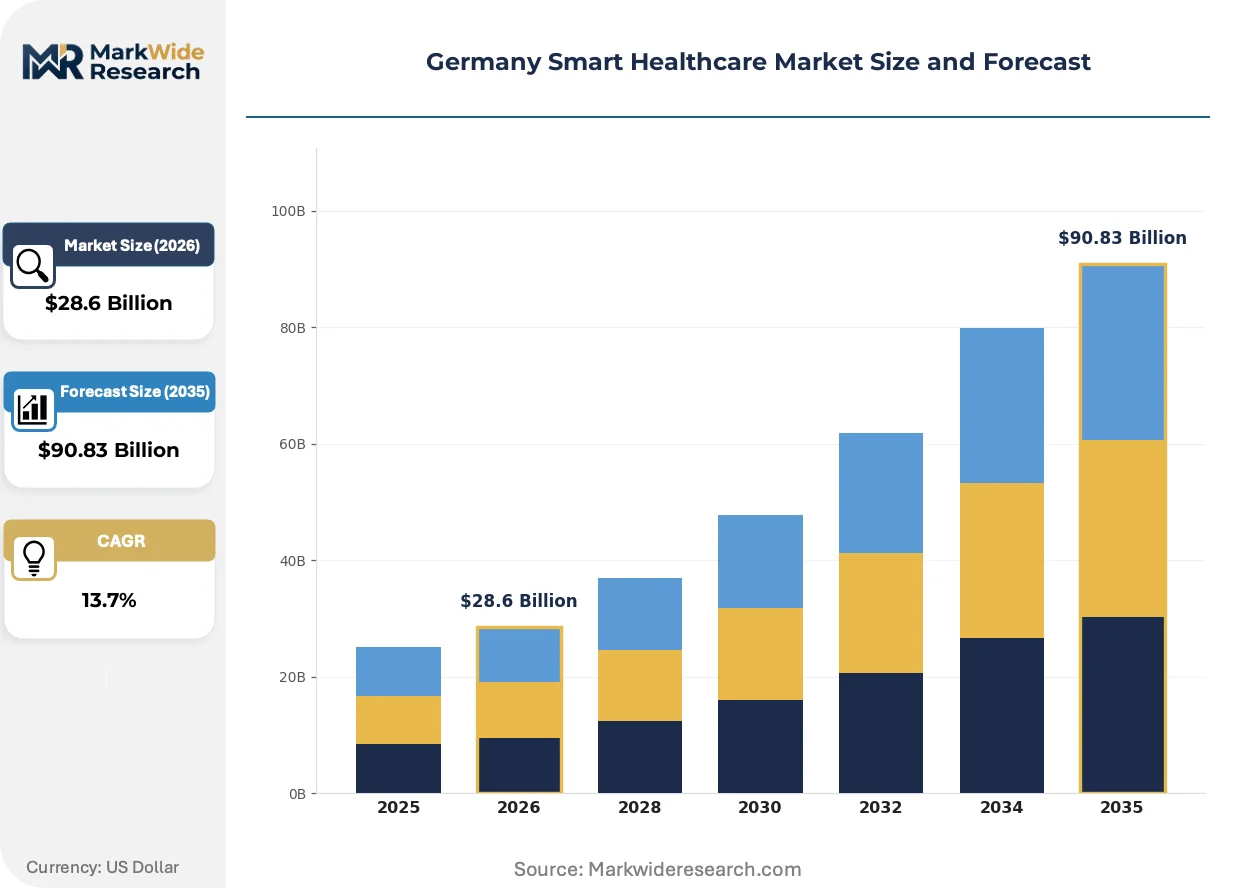
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Telemedicine Systems, Remote Patient Monitoring, Health Analytics Software, AI-Enabled Diagnostics, Digital Therapeutics Application: Chronic Disease Management, Elderly Care, Personalized Medicine, Preventive Care, Mental Health Monitoring, Rehabilitation End User: Hospitals, Outpatient Clinics, Specialty Care Centers, Diagnostic Laboratories, Home Healthcare Providers, Health Insurers Deployment: Cloud-Based, On-Premises, Hybrid Systems, Mobile Platforms, Edge Computing, SaaS Solutions |
| Companies Covered | Olympus Corporation, Cerner Corporation, Siemens Healthineers AG, InterComponentWare (ICW), Allscripts Healthcare Solutions, Inc., GE Healthcare, Resideo Technologies Inc., Ada, Abbott, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Smart Healthcare Market Strategic Shifts & Innovations
Algorithmic clinical decision tools are virtualizing diagnostic workflows across German hospital networks, compressing specialist consultation timelines and enabling point-of-care automation in previously centralized settings.
Edge-computing architectures for real-time vital sign processing are virtualizing patient monitoring infrastructure, enabling Bavarian tertiary hospitals to deploy AI-augmented triage systems at ward level rather than centralized ICU settings. Cardiology and emergency medicine departments are adopting these systems fastest, driven by nursing staff shortages and throughput pressure.
The European Health Data Space regulations are mandating interoperability standards that reshape procurement specifications across German state hospital associations. BfArM and BSI are jointly issuing technical implementation guidelines that favor vendors with pre-certified data exchange protocols, accelerating consolidation around domestic platform providers.
Hospital procurement committees are consolidating vendor relationships around multi-year platform contracts that bundle hardware, software, and analytics services. Value-based contracting frameworks now dominate RFP processes in North Rhine-Westphalia and Baden-Württemberg, replacing transactional device purchasing with outcome-linked payment structures for remote monitoring programs.
Germany Smart Healthcare Market Segmentation
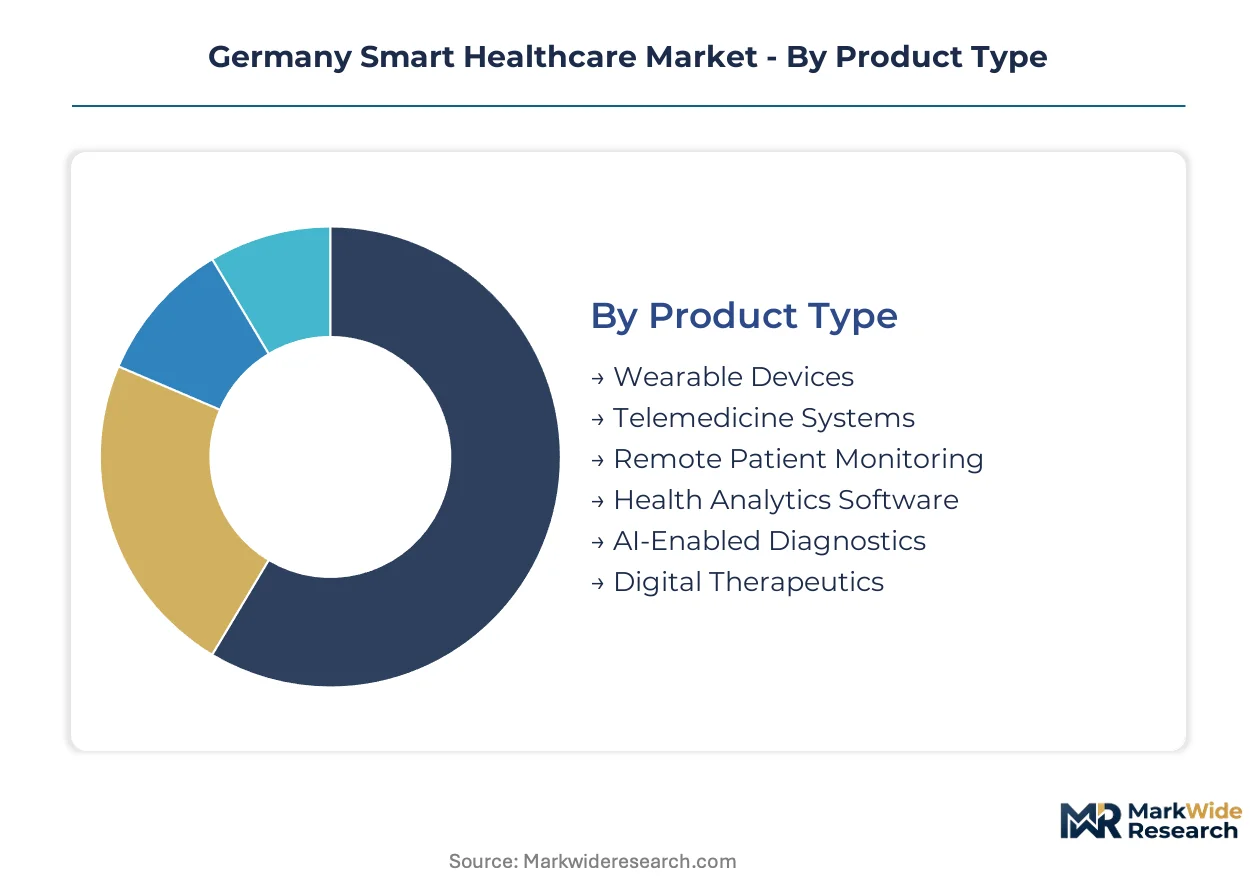
Smart healthcare markets fragment across technology maturity curves, care delivery settings, and regulatory compliance tiers. German procurement committees evaluate segments through reimbursement eligibility under Digital Care Act provisions and BfArM certification pathways.
Product Type:
Mature hardware categories coexist with emerging algorithmic platforms in German hospital procurement portfolios.
- AI-Enabled Diagnostics:Machine learning models trained on anonymized German patient cohorts automate imaging interpretation and pathology screening. Bavarian university hospitals are accelerating validation studies for BfArM fast-track clearance, compressing regulatory timelines for algorithm-as-medical-device submissions.
- Health Analytics Software:FHIR-compliant platforms aggregate multi-source clinical data for population health management and predictive risk stratification. North Rhine-Westphalian hospital networks are consolidating vendor relationships around enterprise licensing contracts that bundle analytics with remote monitoring infrastructure.
- Wearable Devices:Sensor-integrated biosensors track continuous glucose, cardiac rhythm, and activity metrics for ambulatory patients.
- Telemedicine Systems:Video consultation platforms with integrated EHR connectivity serve statutory insurance reimbursement workflows.
- Remote Patient Monitoring:Hub-and-spoke architectures transmit vital signs from patient homes to centralized nursing stations.
- Digital Therapeutics:Prescription-grade software applications for diabetes management and cognitive behavioral therapy.
Health Analytics Software handles the majority of throughput; AI-Enabled Diagnostics is climbing the fastest on share.
Application:
Chronic conditions drive volume concentration while mental health applications attract venture funding for DiGA pathway entry.
- Chronic Disease Management:Integrated care programs for diabetes, cardiovascular disease, and COPD combine remote monitoring with algorithmic treatment adjustment protocols. Hospital networks across Baden-Württemberg are expanding RPM deployments to reduce emergency department utilization among poly-chronic elderly populations.
- Elderly Care:Ambient sensor networks and fall-detection systems enable aging-in-place for nursing home residents and community-dwelling seniors. Eastern German states present underpenetrated demand for facility-based monitoring infrastructure as regional care associations consolidate procurement.
- Personalized Medicine:Pharmacogenomic data integration with clinical decision support for targeted therapy selection.
- Preventive Care:Population-level risk scoring and wellness intervention platforms for insured cohorts.
- Mental Health Monitoring:Digital therapeutics for depression and anxiety with prescription reimbursement status.
- Rehabilitation:Motion-sensing platforms for post-surgical recovery and neurological rehabilitation.
Chronic Disease Management captures the dominant revenue position; Mental Health Monitoring is expanding most quickly as DiGA approvals accumulate.
End User:
Hospital procurement committees command premium pricing power while home healthcare channels scale through insurance-integrated platform contracts.
- Hospitals:Tertiary and secondary acute care facilities deploy integrated diagnostic and monitoring platforms across cardiology, emergency medicine, and intensive care departments. Value-based contracting frameworks in North Rhine-Westphalia and Bavaria now link vendor payments to outcome metrics for remote patient monitoring programs.
- Health Insurers:Statutory health insurance funds (Gesetzliche Krankenversicherung) contract for population health analytics and digital therapeutics distribution under Digital Care Act reimbursement mandates. TK, AOK, and Barmer are consolidating vendor panels around platform solutions that demonstrate cost-offset evidence for chronic disease management.
- Outpatient Clinics:Ambulatory care practices adopt telemedicine and remote monitoring for statutory reimbursement eligibility.
- Specialty Care Centers:Cardiology, oncology, and diabetes-focused facilities deploy condition-specific monitoring protocols.
- Diagnostic Laboratories:Centralized testing facilities integrate AI-augmented pathology and imaging interpretation workflows.
- Home Healthcare Providers:Nursing services and domestic care agencies deploy patient-facing monitoring devices with centralized oversight.
Hospitals anchor procurement volume concentration; Health Insurers are gaining share fastest as reimbursement integration deepens.
Deployment:
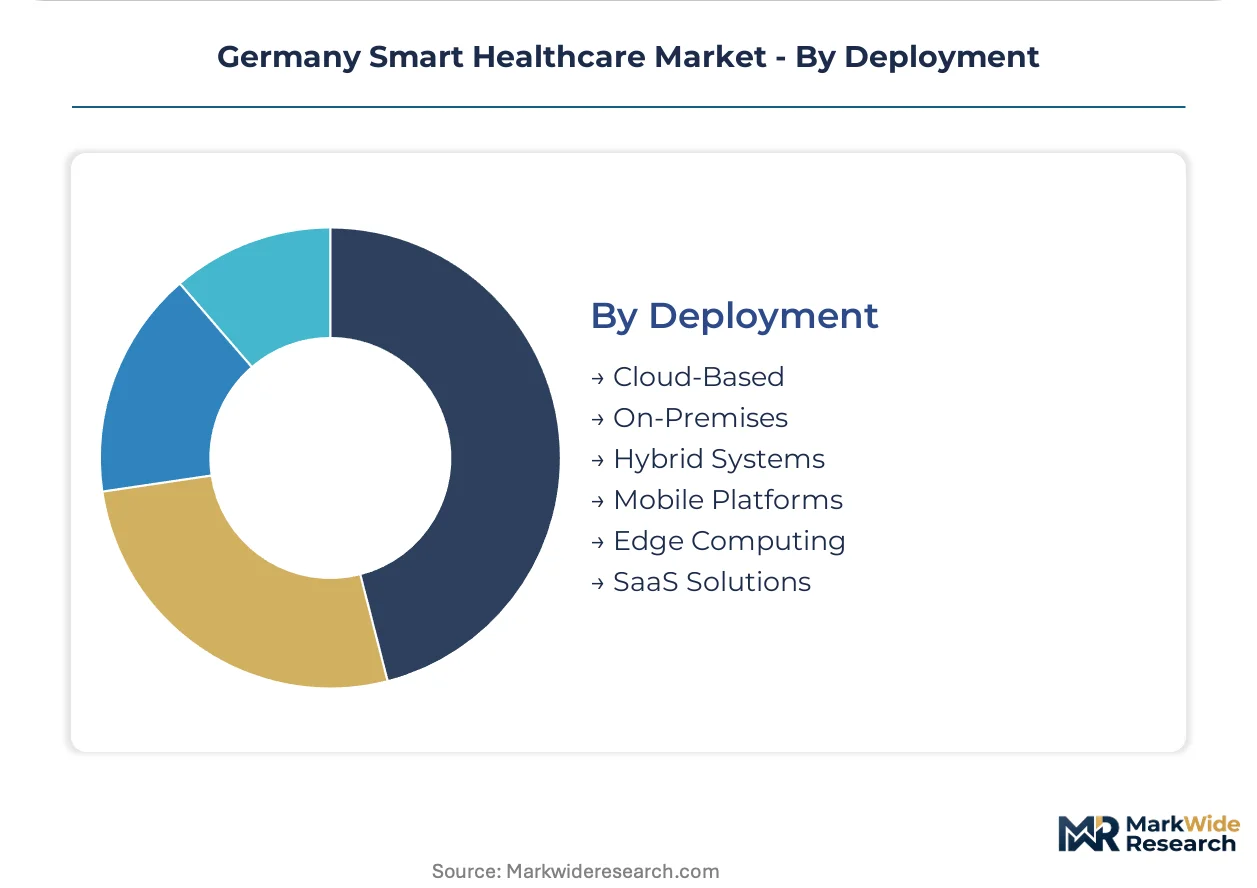
Cloud architectures dominate new procurement while edge computing addresses latency-sensitive acute care applications.
- Cloud-Based:Scalable infrastructure for health analytics, telemedicine, and multi-tenant SaaS delivery enables rapid deployment across regional hospital associations without capital-intensive on-site infrastructure. BSI cybersecurity certification requirements for cloud-hosted medical data are reshaping vendor qualification criteria toward domestic hosting providers.
- Edge Computing:Real-time vital sign processing at ward level reduces dependency on centralized ICU monitoring stations and enables AI-augmented triage in emergency departments. Siemens Healthineers and domestic systems integrators are deploying edge architectures for cardiology and emergency medicine departments facing nursing staff shortages.
- On-Premises:Legacy hospital data centers hosting sensitive patient records with direct institutional control.
- Hybrid Systems:Architectures combining local processing with cloud analytics for workload optimization.
- Mobile Platforms:Patient-facing applications for symptom reporting, medication adherence, and care team communication.
- SaaS Solutions:Subscription-licensed software delivery models with recurring revenue structures.
Cloud-Based deployment handles the majority of new contract value; Edge Computing is the steepest expansion trajectory as real-time AI applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne high-speed rail corridor and Rhine-Main logistics network anchor Germany's smart healthcare distribution infrastructure, enabling rapid deployment of connected medical devices across western hospital networks.
Bavaria
Munich's university hospital cluster drives AI diagnostics validation for BfArM fast-track clearance. The Digital Care Act reimbursement mandates accelerate telemedicine adoption across ambulatory networks in Nuremberg and Augsburg. Siemens Healthineers leverages its Erlangen manufacturing base to supply imaging-integrated platforms to tertiary facilities.
North Rhine-Westphalia
Value-based contracting frameworks now dominate procurement in Düsseldorf and Cologne hospital associations. The state's statutory health insurers consolidate vendor panels around chronic disease management platforms. Aachen's technical university feeds clinical AI talent into regional health IT departments.
Baden-Württemberg
Stuttgart's automotive electronics ecosystem supplies sensor-integrated device manufacturers with MEMS components and edge-computing chipsets. The state's elderly care associations expand ambient monitoring deployments in underpenetrated nursing home chains. Heidelberg's medical faculty accelerates digital therapeutics studies for DiGA pathway entry.
Berlin-Brandenburg
The capital's startup density concentrates digital health venture activity around prescription-grade mental health applications. Charité hospital network validates remote patient monitoring protocols for nationwide rollout. Potsdam's cybersecurity institutes support BSI certification preparation for domestic software vendors.
Hesse
Frankfurt's health insurance headquarters drive population analytics procurement for risk stratification platforms. Darmstadt's technical university supplies data scientists to hospital IT departments facing acute talent scarcity. The Rhine-Main logistics hub enables just-in-time distribution of wearable devices to home healthcare providers.
Germany Smart Healthcare Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in sensor and edge-computing supply chains. The vendor base stratifies between domestic incumbents with BfArM regulatory relationships and international entrants seeking DiGA pathway access. Two strategic archetypes dominate: imaging-integrated platform providers and continuous monitoring device manufacturers. Competitive moves center on multi-year hospital contracts bundling hardware, software, and analytics services alongside BSI cybersecurity pre-certification investments.
Within the domestic platform tier, Siemens Healthineers AG and GE Healthcare exemplify imaging-integrated system providers leveraging established hospital procurement channels. Abbott occupies a position among continuous monitoring specialists with deep integration into cardiac rhythm and glucose management workflows. InterComponentWare (ICW) represents the specialized health information systems archetype, anchoring interoperability infrastructure for regional care network consolidation.
| Leading Market Players |
|---|
| Olympus Corporation |
| Cerner Corporation |
| Siemens Healthineers AG |
| InterComponentWare (ICW) |
| Allscripts Healthcare Solutions, Inc. |
| GE Healthcare |
| Resideo Technologies Inc. |
| Ada |
| Abbott |
| Others |
Cost & Logistics Intelligence
Stuttgart's automotive electronics ecosystem anchors MEMS sensor and edge-computing chipset supply for German device manufacturers, translating concentrated component sourcing into tiered procurement power across Bavarian and Baden-Württemberg hospital networks. BSI cybersecurity certification requirements and Digital Care Act reimbursement eligibility create dual qualification gates that reshape vendor pricing authority.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates German smart healthcare procurement, with premium tiers commanding authority through BfArM fast-track certification and BSI pre-certification status. Price differentiation hinges on FHIR interoperability maturity and edge-computing latency performance, while cost compression in economy tiers intensifies because Asian foundry capacity expansion reduces sensor module costs. Statutory health insurers exhibit acute price sensitivity, whereas university hospital networks prioritize clinical validation timelines over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese foundries for MEMS fabrication and South Korean facilities for advanced edge-computing chipsets, supplemented by domestic German EMS providers for final device assembly. Raw material dependencies span silicon wafers, lithium-ion cells for wearable power systems, and specialized polymers for biocompatible sensor housings. Single-source vulnerability concentrates in 5nm and below semiconductor nodes, while distribution runs through Frankfurt-Cologne logistics corridors into regional hospital association procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's smart healthcare sector sits at a platform-economics inflection where European Health Data Space interoperability mandates will consolidate vendor relationships around integrated diagnostics-monitoring-analytics bundles. FHIR-native data exchange protocols are displacing legacy middleware architectures as the decisive ecosystem gate.
For Market Incumbents: Pre-empt DiGA pathway congestion by accelerating BfArM fast-track submissions for algorithm-as-medical-device classifications before CE-MDR transition timelines compress. Anchor multi-year platform contracts across North Rhine-Westphalia and Bavaria hospital associations to lock out emerging interoperability specialists, while investing in captive edge-computing chip design to reduce Taiwanese foundry dependency. For New Entrants and Emerging Players: Establish a beachhead in eastern German elderly care facility networks where ambient monitoring penetration remains underdeveloped relative to western states. Target nursing home chain procurement committees with fall-detection sensor bundles that integrate into existing regional care association IT infrastructure, leveraging SaaS-based deployment to circumvent capital-intensive on-premises sales cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant health IT divisions lacking BfArM regulatory affairs capabilities. Position for 5-10 year viability around vendors with pre-certified FHIR data exchange protocols and existing Gesetzliche Krankenversicherung reimbursement contracts. Monitor BfArM's evolving DiGA approval velocity as the critical inflection signal for digital therapeutics valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Submission | BfArM clearance enables prescription reimbursement through statutory health insurance funds. |
| FHIR-Native Platform Development | European Health Data Space mandates will disqualify legacy middleware-dependent vendors from procurement. |
| Edge-Computing Architecture Deployment | Real-time AI triage addresses nursing shortages in Bavarian emergency departments. |
| Regional Hospital System Partnership | Value-based contracting in North Rhine-Westphalia locks in multi-year analytics bundling. |
| BSI Cybersecurity Pre-Certification | Pre-certified data exchange protocols accelerate procurement qualification timelines. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement committee members, biomedical engineers, GPO contracts managers, and statutory health insurance fund technology directors and refined through secondary validation against BfArM regulatory filings, hospital procurement databases, CMS-equivalent German reimbursement schedules, and European Health Data Space implementation guidelines. Bottom-up demand modeling across AI-enabled diagnostics, health analytics software, and remote patient monitoring segments triangulated with top-down macro healthcare expenditure projections.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type maturity curves, deployment architecture preference, and regional reimbursement eligibility clusters. CAGRs were derived from installed base growth rates and replacement cycle compression, incorporating BfArM approval velocity and Digital Care Act reimbursement expansion as healthcare-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in German healthcare expenditure growth rates or European semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and interoperability standard adoption curves. Quarterly review of BfArM DiGA approval throughput and statutory health insurance vendor panel consolidations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market