
 Crohn's Disease Diagnostic and Therapeutic Market | 2026-2036
Crohn's Disease Diagnostic and Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Crohn's Disease Diagnostic and Therapeutic Market Outlook
The patient base for Crohn's disease management is broadening beyond academic medical centers into community hospital systems and specialized ambulatory surgery centers. AbbVie Inc. leverages its immunology franchise to sustain dominance in anti-TNF therapy despite biosimilar erosion. Takeda Pharmaceutical Company Limited anchors its position through entyvio's gut-selective mechanism, while Johnson & Johnson Services Inc. competes with Stelara's IL-12/23 blockade across both Crohn's and ulcerative colitis indications.
Crohn's disease diagnostics and therapeutics encompass serological testing, endoscopic visualization, molecular biomarker assays, and targeted immunomodulatory interventions designed to induce and maintain mucosal healing in a chronic transmural inflammatory condition. Biologics command the largest revenue pool among product types due to their superior efficacy in moderate-to-severe disease, though small molecules are gaining traction for oral convenience and lower immunogenicity risk. Injectable delivery modes still dominate hospital and clinic administration, yet subcutaneous formulations are shifting treatment location toward home care settings where patient self-management reduces infusion center burden.
The FDA's Risk Evaluation and Mitigation Strategies for biologics shape prescriber certification requirements and distribution controls, while EMA's pharmacovigilance obligations for immunosuppressants mandate ongoing safety surveillance across European markets. Health Canada's Special Access Programme provides alternative pathways for therapies not yet approved domestically, creating regulatory arbitrage opportunities for manufacturers. Stakeholders must monitor how payer consolidation in the United States and Germany's AMNOG benefit assessments reshape pricing power for novel mechanism entrants against entrenched anti-TNF standards.
Market Dynamics
FDA's accelerated approval pathways for biologics have compressed development timelines from eight years to four, forcing manufacturers to front-load clinical investments while payer consolidation in the United States erodes pricing power for novel mechanism entrants against entrenched anti-TNF standards.
Growth Catalysts
- Specialized IBD Centers:Hospital systems across the United States are expanding gastroenterology service lines to capture complex inflammatory bowel disease cases, creating dedicated referral networks that concentrate high-acuity patients.
- EMA Pharmacovigilance Framework:Ongoing safety surveillance mandates for immunosuppressants across European markets generate recurring revenue streams for post-market monitoring services and companion diagnostic platforms.
- Subcutaneous Formulation Shift:Self-administered delivery modes are electrifying home care settings, reducing infusion center burden while expanding addressable patient populations beyond clinic-dependent cohorts.
Market Restraints
- Biosimilar Erosion:Anti-TNF reference products face revenue compression as regulatory pathways in the United States and European Union accelerate interchangeable substitution at the pharmacy level.
- Input Cost Volatility:Monoclonal antibody production depends on Chinese-manufactured single-use bioreactor bags and filters, exposing supply chains to geopolitical trade friction and raw material scarcity.
- Technical Limitation:Current serological testing lacks sufficient sensitivity for early mucosal healing assessment, forcing reliance on invasive endoscopic confirmation that delays treatment optimization.
Strategic Opportunities
- Gut-Selective Mechanisms:Therapies targeting α4β7 integrin offer reduced systemic immunosuppression, creating differentiation against broad immunomodulators in pediatric and elderly populations with comorbidity burdens.
- Health Canada Special Access:The programme provides alternative pathways for therapies not yet approved domestically, enabling manufacturers to generate real-world evidence ahead of formal regulatory submission.
- Artificial Intelligence Convergence:Machine learning integration with capsule endoscopy is electrifying automated lesion detection, compressing diagnostic interpretation time while standardizing severity scoring across community and academic settings.
Industry Challenges
- Gastroenterologist Workforce Scarcity:Fellowship-trained IBD specialists concentrate in major metropolitan areas, leaving community hospital systems dependent on generalists with limited biologic initiation experience.
- REMS Compliance Burden:FDA-mandated Risk Evaluation and Mitigation Strategies require prescriber certification, specialty pharmacy lock-in, and patient registry maintenance that fragment care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crohn's Disease Diagnostic and Therapeutic Market |
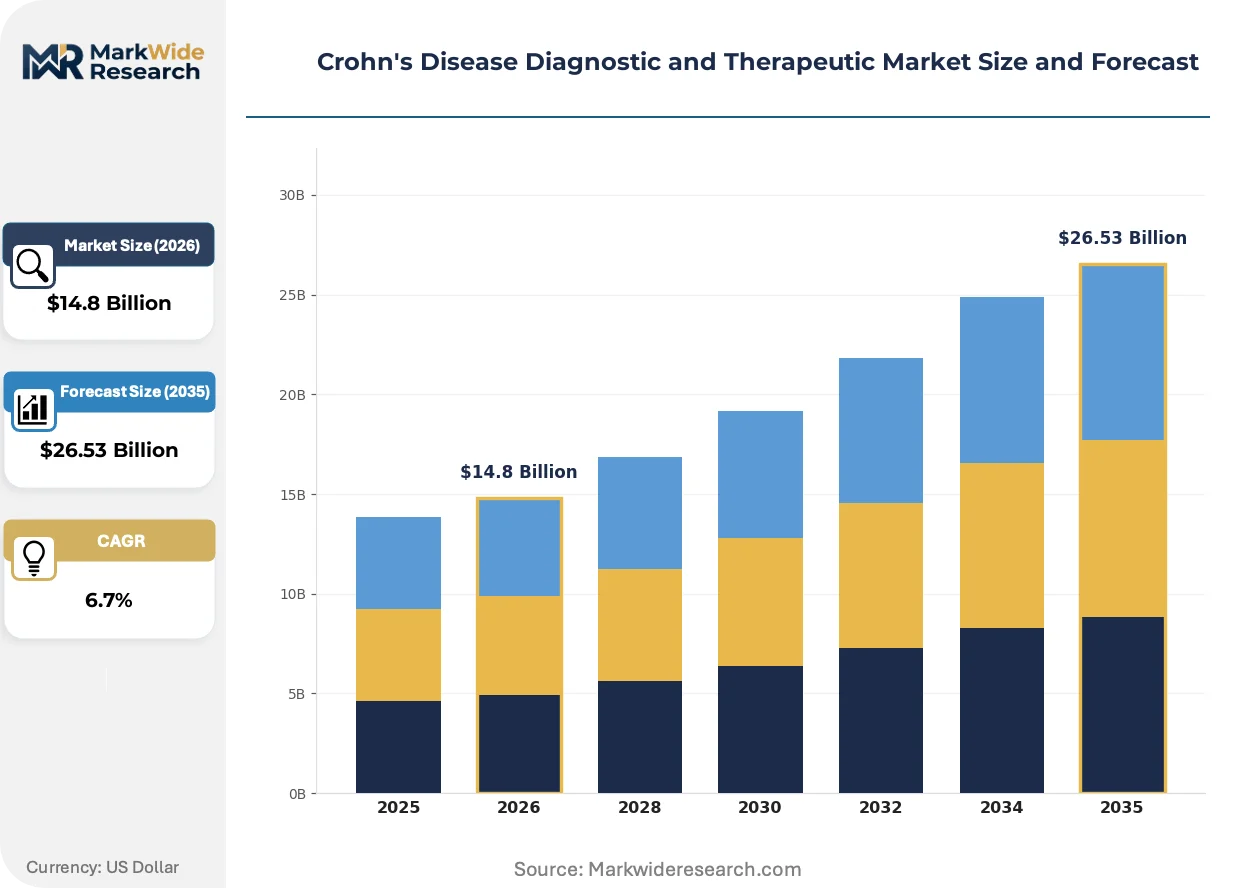
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Immunomodulators, Corticosteroids, Small Molecules Delivery Mode: Injectable, Oral, Infusion, Subcutaneous End User: Hospitals, Clinics, Home Care, Laboratories Technology: Genetic Testing, Imaging Techniques, Biomarker Analysis, Endoscopy |
| Companies Covered | AbbVie Inc., Takeda Pharmaceutical Company Limited, Pfizer Inc., Johnson & Johnson Services Inc., Ferring B.V., UCB S.A., Roche, Amgen, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crohn's Disease Diagnostic and Therapeutic Market Strategic Shifts
Oral small molecules are electrifying patient preference hierarchies, while artificial intelligence reshapes endoscopic workflows and regulatory frameworks accelerate biosimilar penetration across reimbursement tiers.
Janus kinase inhibitors are electrifying the moderate-to-severe Crohn's landscape with oral convenience that bypasses infusion center logistics. Community gastroenterologists in the United States are adopting these agents at twice the pace of academic centers, driven by patient self-management demands and reduced nursing overhead. This modality is electrifying a channel shift toward retail pharmacy distribution that threatens hospital outpatient department revenue capture.
Germany's AMNOG benefit assessment procedures now mandate comparative effectiveness evidence against existing standards within twelve months of launch. Manufacturers face compressed timelines for generating head-to-head data, with failure to demonstrate added benefit triggering reference pricing that collapses revenue per treated patient. The biologics segment is responding by front-loading real-world evidence collection through disease registries and patient support programmes.
Patient switching cycles between biologic classes have compressed from thirty-six months to eighteen as treatment-to-target protocols intensify. United States-based IBD centers of excellence now unbundle infusion services from drug acquisition, creating transparent fee schedules that expose markup variability and accelerate site-of-care migration to lower-cost ambulatory settings. This behavioral shift is most visible in Texas and Florida, where specialized ambulatory surgery centers capture infusion volume from hospital-based clinics.
Crohn's Disease Diagnostic and Therapeutic Market Segmentation
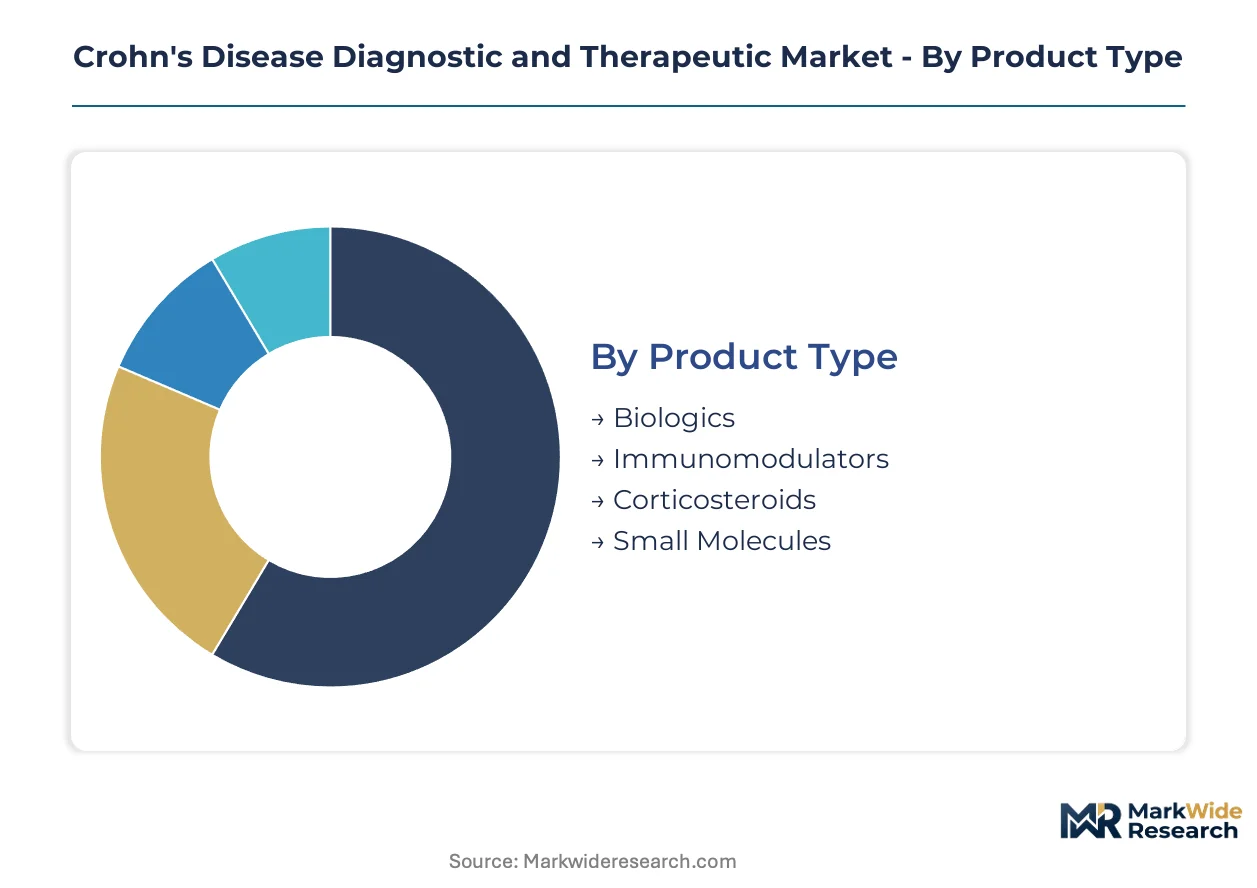
Segmentation in Crohn's disease management reveals how regulatory pathways, site-of-care economics, and patient self-administration preferences fragment commercial opportunity across divergent stakeholder incentives and reimbursement structures.
Product Type:
FDA's Risk Evaluation and Mitigation Strategies impose tiered certification burdens: biologics demand prescriber enrollment and specialty pharmacy lock-in, while small molecules face standard new drug application pathways without distribution restrictions.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-12/23, and integrin pathways dominate hospital outpatient revenue. United States IBD centers of excellence concentrate infusion volume for these agents, though subcutaneous formulations are shifting administration toward home settings.
- Small Molecules:Oral Janus kinase inhibitors bypass infusion center logistics entirely, electrifying community gastroenterology adoption at twice academic center rates. Patient preference for self-management drives retail pharmacy distribution that threatens hospital markup capture.
- Immunomodulators:Thiopurines and methotrexate serve as maintenance bridge therapy with established generic pricing.
- Corticosteroids:Acute flare management remains concentrated in emergency departments and urgent infusion protocols.
Leading the category by volume: Biologics. Expanding most quickly: Small Molecules.
Delivery Mode:
Cost tier stratification separates hospital-dependent administration from patient-directed alternatives, with reimbursement differentials driving site-of-care migration toward lower-acuity settings.
- Injectable:Intravenous formulations require certified infusion centers with nursing oversight and adverse event monitoring capability. Hospital systems in Texas and Florida unbundle drug acquisition from administration fees, accelerating volume migration to specialized ambulatory surgery centers.
- Subcutaneous:Self-administered pen and syringe formats reduce per-dose healthcare utilization costs while expanding addressable populations to patients distant from infusion infrastructure. Home care settings capture this volume through specialty pharmacy distribution networks.
- Oral:Eliminates cold chain logistics and clinical overhead entirely.
- Infusion:Remains the default for loading doses and acute intervention.
Highest reimbursement capture: Injectable. Steepest patient preference shift: Subcutaneous.
End User:
Customer type concentration varies by disease severity, with complex transmural cases requiring multidisciplinary coordination that community settings struggle to replicate.
- Hospitals:Academic medical centers and specialized IBD centers of excellence manage fistulizing disease, surgical complications, and biologic failure sequences. These institutions capture the highest per-patient revenue through bundled episode payments and clinical trial enrollment.
- Home Care:Subcutaneous formulation proliferation and remote therapeutic monitoring enable stable patients to self-administer outside clinical settings. United States payers increasingly mandate site-of-care optimization programs that steer volume away from hospital outpatient departments.
- Clinics:Community gastroenterology practices handle maintenance therapy for stable disease.
- Laboratories:Process serological and molecular biomarker assays for treatment guidance.
Revenue concentration: Hospitals. Fastest channel shift: Home Care.
Technology:
Maturity curves separate invasive gold-standard confirmation from emerging non-invasive alternatives, with regulatory validation timelines determining commercial availability.
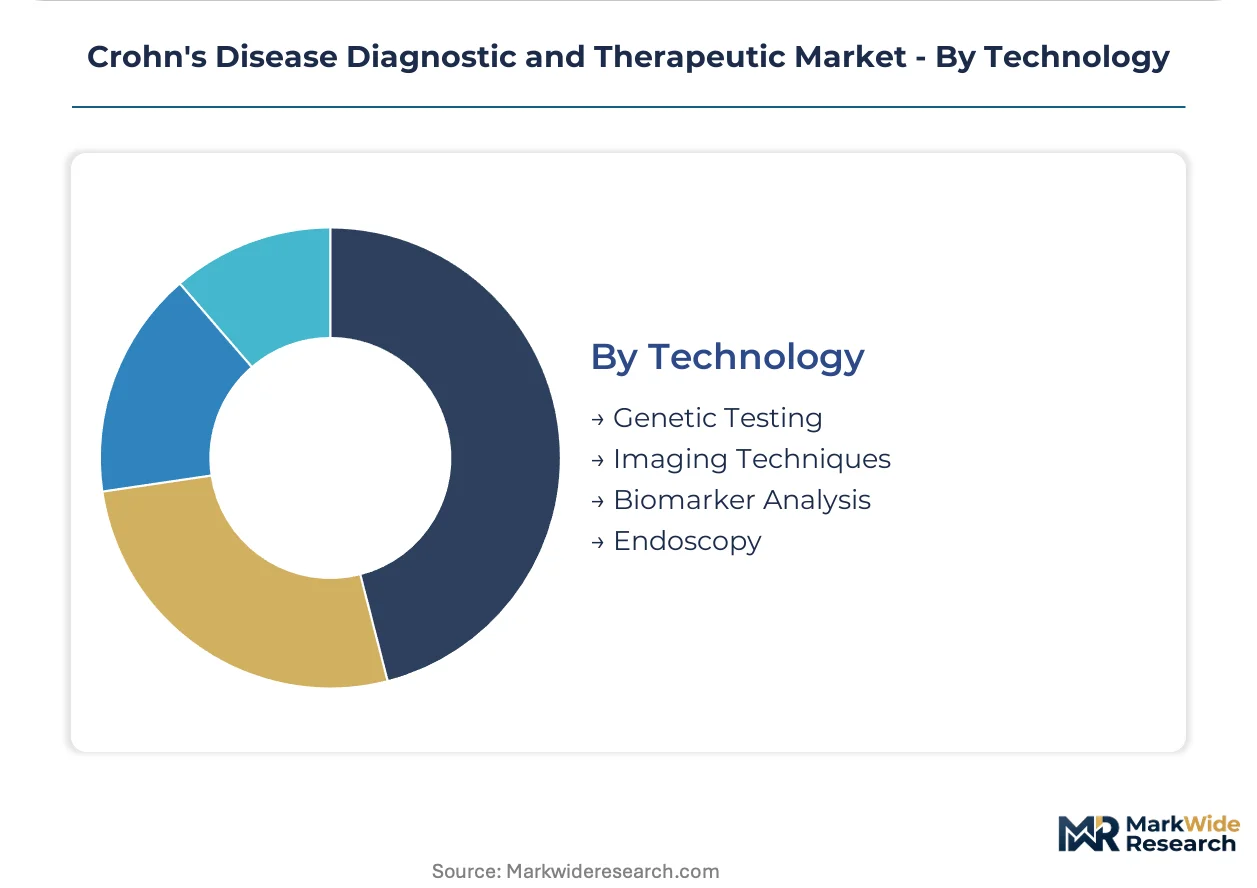
- Endoscopy:Ileocolonoscopy with histopathological assessment remains the diagnostic and treatment response benchmark. EMA pharmacovigilance frameworks mandate ongoing safety surveillance for immunosuppressed patients undergoing repeated procedures, generating recurring revenue for pathology services.
- Biomarker Analysis:Fecal calprotectin and C-reactive protein monitoring enable non-invasive disease activity tracking between endoscopic assessments. German AMNOG benefit assessments now require biomarker-stratified evidence packages for novel therapy reimbursement.
- Imaging Techniques:MR enterography and CT evaluation support transmural assessment.
- Genetic Testing:Pharmacogenomic screening guides thiopurine dosing and toxicity risk stratification.
Clinical standard: Endoscopy. Gaining regulatory traction: Biomarker Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where specialized IBD centers of excellence concentrate high-acuity patients and drive biologic utilization rates. Germany and Japan anchor European and Asian therapeutic adoption respectively, while emerging markets in India and Brazil expand access infrastructure.
United States
Hospital systems in Texas and Florida unbundle infusion services from drug acquisition, accelerating site-of-care migration to specialized ambulatory surgery centers. The FDA's Risk Evaluation and Mitigation Strategies impose prescriber certification and specialty pharmacy lock-in requirements that fragment care coordination. New York Metro and Greater Boston clusters concentrate clinical trial enrollment and IBD center of excellence designation.
Germany
AMNOG benefit assessment procedures mandate comparative effectiveness evidence against existing standards within twelve months of launch, compressing timelines for head-to-head data generation. EMA pharmacovigilance obligations require ongoing safety surveillance for immunosuppressants, generating recurring revenue for post-market monitoring services. Bavaria and North Rhine-Westphalia host the highest density of gastroenterology service line expansions.
Japan
PMDA accelerated approval pathways for biologics have compressed development timelines, enabling faster market entry for novel mechanisms. METI initiatives support domestic manufacturing capacity for monoclonal antibody production to reduce import dependency. The Kanto/Tokyo region concentrates specialized IBD treatment centers and biomarker assay processing capacity.
India
CDSCO regulatory pathways for biosimilars accelerate interchangeable substitution, expanding access to anti-TNF therapies at reduced cost points. Maharashtra and Karnataka clusters develop contract manufacturing capacity for bioreactor equipment and single-use consumables. Mumbai and Bangalore metros concentrate gastroenterology fellowship training programs and private hospital chain expansion.
Brazil
ANVISA streamlined registration for reference biologics and biosimilars reduces time-to-market for immunomodulatory therapies. São Paulo state anchors demand through concentrated health insurance penetration and specialized ambulatory care infrastructure. The Rio de Janeiro metro area expands public hospital gastroenterology service lines to capture complex inflammatory bowel disease cases.
Crohn's Disease Diagnostic and Therapeutic Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue gut-selective mechanisms and oral small molecule convenience. The vendor base stratifies across immunology franchise holders, biologic specialists, and diversified pharmaceutical conglomerates. Three archetypes dominate: anti-TNF originators defending against biosimilar erosion, integrin pathway specialists capturing pediatric and elderly populations, and JAK inhibitor entrants electrifying community gastroenterology adoption. Competitive moves concentrate on M&A for pipeline assets and strategic partnerships for companion diagnostic development.
Within the immunology franchise tier, AbbVie Inc. and Johnson & Johnson Services Inc. represent entrenched anti-TNF and IL-12/23 blockade positions respectively, while Takeda Pharmaceutical Company Limited occupies the gut-selective integrin pathway specialization. These three entities exemplify distinct mechanistic differentiation strategies against the backdrop of biosimilar compression and site-of-care migration.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Takeda Pharmaceutical Company Limited |
| Pfizer Inc. |
| Johnson & Johnson Services Inc. |
| Ferring B.V. |
| UCB S.A. |
| Roche |
| Amgen |
| Bristol-Myers Squibb Company |
| Others |
Value Chain & Pricing Dynamics
Chinese-manufactured single-use bioreactor bags and filters flow through monoclonal antibody production into tiered pricing that separates originator biologics from interchangeable biosimilars and economy-tier small molecules. This input cost pathway concentrates pricing power with manufacturers who control fermentation capacity and cold chain distribution networks.
Pricing Analysis
Volume capture concentrates in anti-TNF originators while margin compression accelerates for reference products facing interchangeable biosimilar substitution at the pharmacy level. Three-tier pricing structure across premium originator, standard biosimilar, and economy small molecule levels differentiates by certification grade and administration mode complexity. Pricing pressure stems from United States payer consolidation and Germany's AMNOG reference pricing triggers. Community hospital systems exhibit highest price sensitivity due to formulary restriction exposure, while academic IBD centers of excellence demonstrate lowest sensitivity through bundled episode payment insulation.
Supply Chain Analysis
Cold chain logistics costs for temperature-sensitive biologics anchor distribution economics, with freight expenditure representing a material share of landed cost for intravenous formulations. Manufacturing concentration rests on China, South Korea, and Ireland for single-use consumables, active pharmaceutical ingredients, and fill-finish capacity respectively. Raw material dependencies center on petroleum-derived filtration media, cell culture media components, and sterilization-grade plastics. Single-source vulnerability for bioreactor bag suppliers exposes producers to geopolitical trade friction. Distribution runs through specialty pharmacy networks for patient-directed administration and hospital purchasing organizations for infusion center delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity for monoclonal antibody production props pricing for manufacturers with captive bioreactor infrastructure, insulating originator margins against biosimilar erosion.
For Market Incumbents: Deepen vertical integration into single-use consumable manufacturing to mitigate Chinese supply chain exposure and capture input cost margin. Expand subcutaneous formulation capacity to defend against site-of-care migration threatening hospital outpatient revenue. Lock in long-term specialty pharmacy distribution partnerships before JAK inhibitor retail channel shift accelerates. For New Entrants and Emerging Players: Health Canada's Special Access Programme in Canada opens a window for generating real-world evidence ahead of formal FDA submission, enabling accelerated market entry. Target pediatric and elderly populations with comorbidity burdens where gut-selective mechanisms command premium positioning. Pursue companion diagnostic co-development with artificial intelligence-enabled capsule endoscopy platforms to differentiate against entrenched anti-TNF standards. For Investors and Strategic Acquirers: PMDA accelerated approval pathway utilization in Japan is the leading indicator that novel mechanism entrants can compress development timelines and command first-mover pricing. Focus acquisition screening on oral small molecule pipelines with phase-ready JAK inhibitors and established safety databases. Watch for FDA Risk Evaluation and Mitigation Strategies relaxation as signal of biosimilar penetration ceiling and originator margin floor convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables home care administration that bypasses hospital markup capture and expands addressable patient populations. |
| Companion Diagnostic Partnership | Integrates biomarker stratification with therapy selection to satisfy Germany's AMNOG evidence requirements. |
| Biosimilar Interchangeability Pursuit | Secures pharmacy-level substitution rights that accelerate volume capture from reference product erosion. |
| Real-World Evidence Registry Buildout | Generates head-to-head effectiveness data required within twelve months of launch for reimbursement defense. |
| Artificial Intelligence Endoscopy Integration | Compresses diagnostic interpretation time while standardizing severity scoring across community gastroenterology settings. |
Study Parameters
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from CMS Medicare data, GPO contracts, and hospital procurement databases. Bottom-up patient flow modeling and top-down revenue triangulation anchored market size estimation.
Output generation across the analysis window employed treatment line stratification, dosage form segmentation, administration route differentiation, and regional regulatory clustering. CAGRs derived from patient population growth, biologic penetration rate trajectories, and pricing elasticity assumptions specific to immunomodulatory therapy markets. Modeled inputs included biosimilar substitution velocity, site-of-care migration patterns, and subcutaneous formulation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for oral small molecule convenience would alter the outlook toward accelerated retail pharmacy distribution and compressed infusion center revenue. Forecasts reflect assumptions about regulatory pathway stability, payer consolidation velocity, and manufacturing capacity expansion timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market