
 Therapeutic Hypothermia Systems Market | 2026-2036
Therapeutic Hypothermia Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Hypothermia Systems Market Analytics
Market Context with Strategic Players
Emergency Medical Services is consolidating as a high-growth procurement channel for portable cooling platforms. ZOLL Medical Corporation leverages its established defibrillator distribution network to bundle temperature management solutions with resuscitation workflows. BrainCool AB specializes in compact, battery-powered surface cooling systems designed for pre-hospital transport scenarios. Stryker Corporation dominates hospital capital equipment purchasing through its integrated surgical and critical care portfolio.
Technical Definition and Structural Segments
Therapeutic hypothermia systems are electromechanical or passive thermal regulation devices that actively reduce patient core body temperature to 32–34°C, utilizing circulating chilled fluids, conductive surface pads, or evaporative cooling mechanisms to mitigate ischemic neurological injury. These systems serve the primary commercial purpose of improving neurological outcomes following cardiac arrest, traumatic brain injury, and perinatal hypoxic events in acute care settings. Surface Cooling Systems anchor the installed base in tertiary hospitals, while Invasive Cooling Devices capture premium margin pools in neurocritical care units requiring precise temperature control within 0.1°C. Neonatal Encephalopathy applications represent the fastest-growing segment as perinatal quality collaboratives expand therapeutic hypothermia to level II and III nurseries.
Regulatory Frame and Forward-Looking Close
The FDA's 510(k) pathway governs device clearance for surface and invasive cooling platforms, while the EU MDR's tightened clinical evidence requirements are extending certification timelines for European market access. ISO 80601-2-56 establishes international performance standards for patient thermoregulatory devices, directly influencing procurement specifications at integrated delivery networks. Japan's PMDA maintains distinct thermal safety testing protocols that create incremental compliance burdens for multinational manufacturers. Stakeholders must monitor how CMS reimbursement determinations for out-of-hospital cardiac arrest protocols reshape EMS capital allocation versus hospital-based temperature management investments.
Market Dynamics
Hospital capital allocation is pivoting toward integrated temperature management platforms as neurocritical care units consolidate diagnostic and therapeutic workflows under single vendor contracts. This procurement concentration is compressing margins for standalone cooling device manufacturers while elevating bundled solution providers.
Growth Catalysts
- Updated resuscitation protocols:The American Heart Association's revised post-cardiac arrest guidelines mandate temperature management, driving institutional adoption across emergency departments and intensive care units in the United States.
- Neonatal quality collaboratives:Perinatal networks in level II and III nurseries are standardizing therapeutic hypothermia for hypoxic-ischemic encephalopathy, expanding the addressable patient population beyond tertiary centers.
- Surface cooling maturation:Advances in conductive gel pad materials enable faster induction rates, allowing EMS transport teams to initiate cooling before hospital arrival.
Market Restraints
- Copper and semiconductor input volatility:Chiller unit production depends on precision temperature sensors and heat exchange components subject to supply chain disruptions.
- EU MDR certification extension:Tightened clinical evidence requirements for invasive cooling catheters are delaying European market entry by 12-18 months for new entrants.
- Passive cooling alternatives:Ice packs and surface evaporation methods retain cost advantage in resource-constrained settings, limiting premium system penetration.
Strategic Opportunities
- India's tertiary hospital expansion:Government-funded medical college hospitals are establishing dedicated neurocritical care units with temperature management capabilities.
- Pediatric transport applications:Miniaturized battery-powered cooling platforms address the unmet need for pre-hospital neonatal temperature control during inter-facility transfers.
- Japan's aging stroke burden:METI incentives for neuroemergency infrastructure are accelerating municipal hospital investment in invasive cooling devices for malignant cerebral edema protocols.
Industry Challenges
- Neurocritical care specialist scarcity:Board-certified neurointensivists required for protocol oversight remain concentrated at academic medical centers, constraining community hospital adoption.
- Legacy EMR integration complexity:Temperature management systems must interface with proprietary electronic health record architectures, extending deployment timelines and IT resource requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Hypothermia Systems Market |
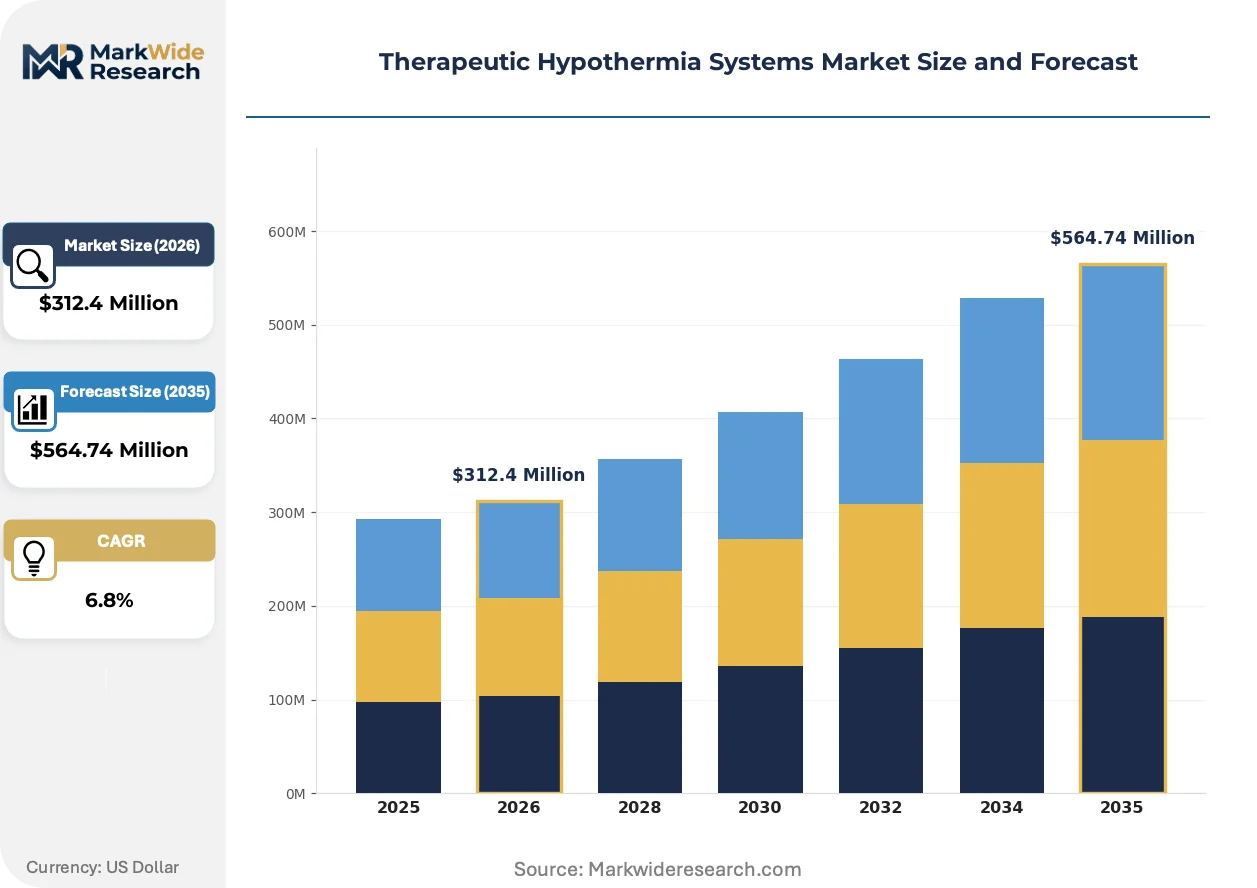
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cooling Systems, Cold IV Fluids, Cooling Caps, Invasive Cooling Devices End User: Hospitals, Emergency Medical Services, Rehabilitation Centers, Specialty Clinics Application: Cardiac Arrest, Neonatal Encephalopathy, Stroke Recovery, Postoperative Care Delivery Mode: Conventional Methods, Advanced Techniques, Portable Units, Remote Monitoring |
| Companies Covered | Asahi Kasei Corporation, BrainCool AB, ZOLL Medical Corporation, Drägerwerk AG & Co. KgaA, Terumo Cardiovascular Systems Corporation, Becton, Dickinson and Company, Belmont Medical Technologies, EM-MED Sp. z o.o., Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Hypothermia Systems Market Evolving Landscape
Electromechanical cooling architectures are converging with real-time biomonitoring, creating closed-loop systems that autonomously adjust thermal output based on patient neurological markers. This integration is redefining competitive differentiation beyond raw cooling capacity.
Phase-change material inserts are absorbing the functional role of active refrigeration in pre-hospital transport scenarios. Emergency medical services fleets in the United States are adopting these lightweight, battery-independent cooling vests for extended field operations. The technology is absorbing market share from portable chiller units by eliminating power dependency and reducing equipment weight by over sixty percent.
The EU MDR's post-market surveillance requirements are forcing invasive cooling catheter manufacturers to maintain larger clinical follow-up databases. Device sponsors must now submit annual safety reports to notified bodies, increasing regulatory compliance overhead. Neurocritical care units in Germany and France are prioritizing suppliers with established European post-market infrastructure, favoring incumbents over new market entrants.
Hospital purchasing committees are unbundling temperature management hardware from disposable consumables, creating separate vendor relationships for capital equipment and single-use surface pads. This disaggregation allows materials management departments to optimize pad sourcing through group purchasing organizations while retaining preferred chiller vendors. The pattern is most pronounced in United States integrated delivery networks consolidating supply chain decision-making at regional headquarters.
Therapeutic Hypothermia Systems Market Segmentation
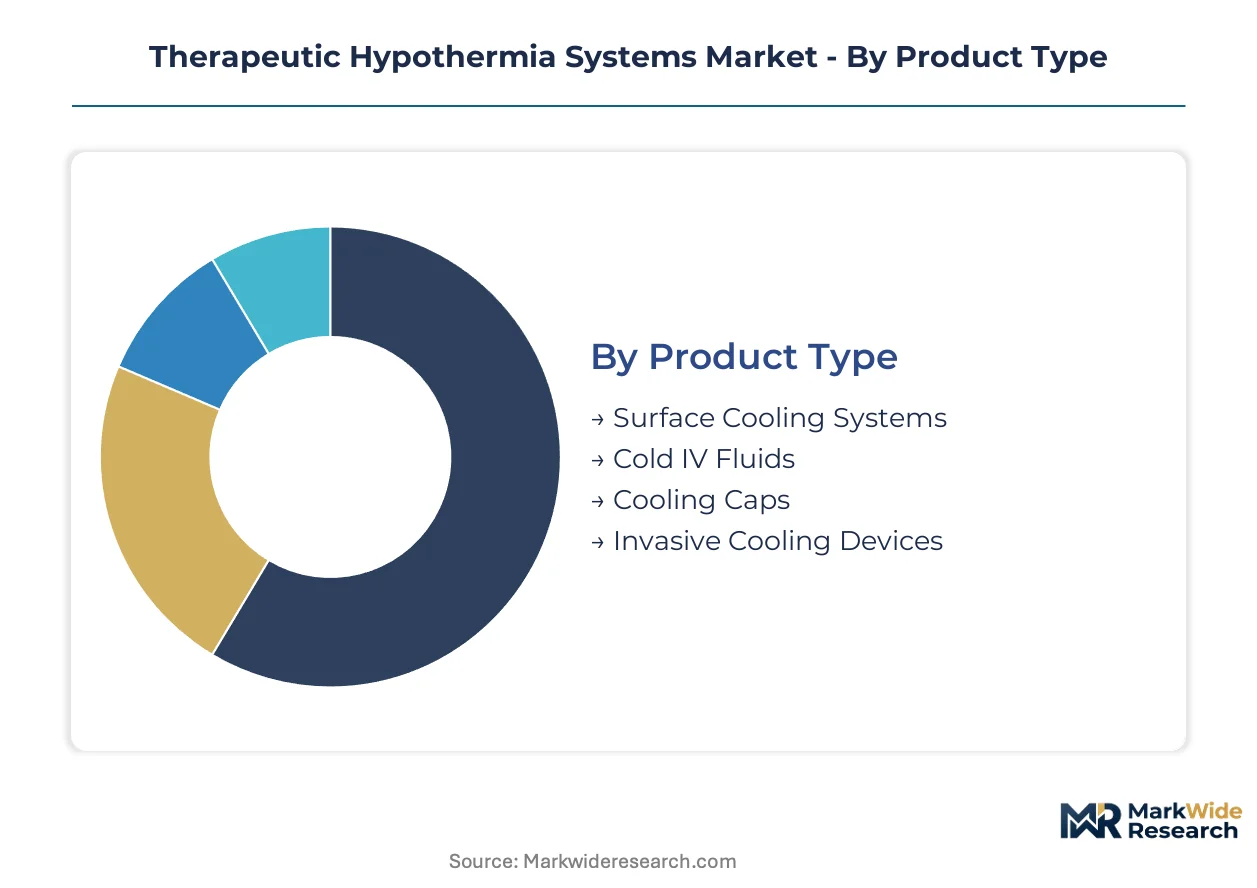
Therapeutic hypothermia systems fragment across four structural dimensions that determine procurement pathways, regulatory burdens, and clinical deployment models. Each segmentation axis carries distinct margin profiles and vendor concentration patterns that shape competitive positioning.
Product Type:
FDA 510(k) clearance governs surface and invasive cooling platforms, while cold IV fluids fall under pharmaceutical manufacturing standards. Cooling caps face additional electromagnetic compatibility testing for transport scenarios.
- Surface Cooling Systems:Conductive gel pads and circulating chilled blankets dominate tertiary hospital installations. United States academic medical centers drive replacement cycles as neurocritical care units consolidate under single-vendor contracts.
- Invasive Cooling Devices:Intravascular catheters with closed-loop temperature control deliver precision within 0.1°C for malignant cerebral edema protocols. EU MDR's tightened clinical evidence requirements extend certification timelines for new catheter entrants.
- Cold IV Fluids:Chilled saline bolus methods require no device registration but lack sustained temperature maintenance.
- Cooling Caps:Head-targeted surface systems for neonatal applications emphasize lightweight materials and battery independence.
Leading the category by volume: Surface Cooling Systems. Growing fastest: Invasive Cooling Devices.
End User:
Procurement authority concentrates differently across settings — hospitals delegate to value analysis committees, EMS operates through municipal fleet managers, and specialty clinics respond to physician preference items.
- Hospitals:Capital equipment purchasing committees bundle temperature management with broader critical care infrastructure. Integrated delivery networks in the United States centralize vendor selection at regional headquarters.
- Emergency Medical Services:Portable platform demand accelerates as municipal fire departments expand resuscitation protocols. Phase-change material vests displace active chiller units by eliminating power dependency.
- Rehabilitation Centers:Post-acute settings deploy surface cooling for neuroplasticity optimization following stroke.
- Specialty Clinics:Ambulatory surgical centers require compact units for targeted intraoperative temperature management.
Volume leader: Hospitals. Steepest expansion trajectory: Emergency Medical Services.
Application:
Clinical evidence requirements vary sharply — cardiac arrest protocols rest on randomized trial data, while neonatal indications face perinatal quality collaborative standardization.
- Cardiac Arrest:Post-resuscitation temperature management anchors the installed base. American Heart Association guideline mandates drive institutional adoption across United States emergency departments.
- Neonatal Encephalopathy:Hypoxic-ischemic encephalopathy treatment expands to level II and III nurseries as perinatal networks standardize protocols.
- Stroke Recovery:Malignant cerebral edema protocols in Japan accelerate municipal hospital investment following METI neuroemergency incentives.
- Postoperative Care:Surgical site infection prevention through perioperative normothermia maintenance offers secondary utilization.
Dominant by procedure volume: Cardiac Arrest. Climbing the fastest: Neonatal Encephalopathy.
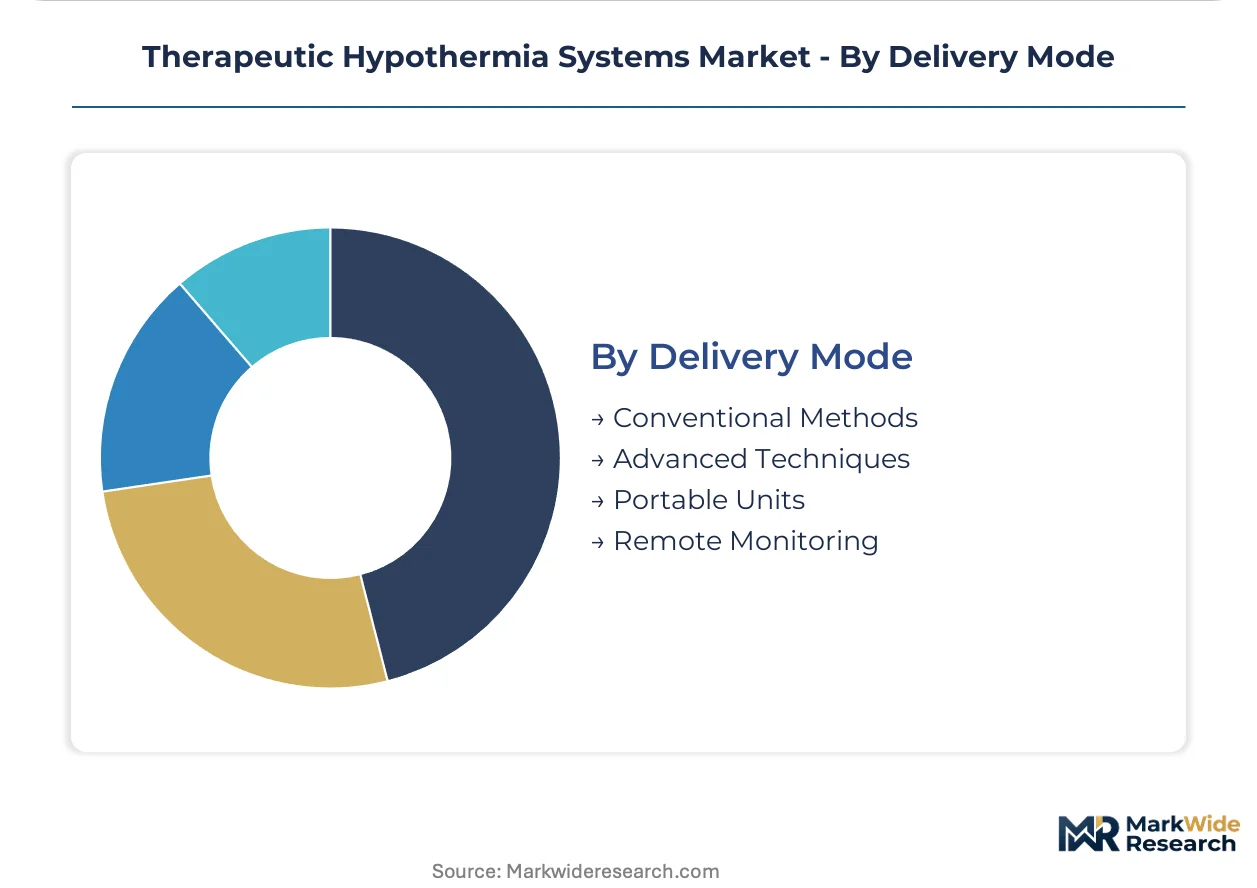
Delivery Mode:
Technology maturity separates established electromechanical platforms from emerging connectivity-enabled systems requiring cybersecurity validation.
- Portable Units:Battery-powered surface systems enable pre-hospital cooling initiation. United States EMS fleets prioritize weight reduction and extended field autonomy.
- Remote Monitoring:Cloud-connected temperature telemetry demands HIPAA-compliant data architecture and hospital IT integration.
- Conventional Methods:Ice packs and passive evaporation retain cost advantage in resource-constrained settings.
- Advanced Techniques:Closed-loop autonomous systems adjust thermal output based on real-time neurological biomarkers.
Current volume concentration: Conventional Methods. Fastest technology transition: Portable Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical device manufacturing in Malaysia and Costa Rica are concentrating temperature management production capacity for North American and Asian hospital supply chains.
United States
Academic medical centers in Boston and Baltimore are expanding dedicated neurocritical care units with integrated temperature management protocols. FDA premarket notification requirements for thermal regulation devices are extending product development cycles by 8-12 months. The Research Triangle Park cluster in North Carolina hosts contract manufacturing operations for surface cooling system components.
Germany
University hospitals in Heidelberg and Munich are standardizing invasive cooling catheter protocols for stroke recovery under EU MDR post-market surveillance mandates. The EU MDR's tightened clinical evidence requirements are delaying certification timelines for new catheter entrants by 12-18 months. The MedTech industrial corridor in Baden-Württemberg concentrates precision temperature sensor manufacturing for European device OEMs.
Japan
Municipal hospitals in Osaka and Nagoya are investing in invasive cooling devices for malignant cerebral edema protocols following METI neuroemergency infrastructure incentives. PMDA maintains distinct thermal safety testing protocols that create incremental compliance burdens for multinational manufacturers. The Kobe medical device cluster specializes in compact chiller unit assembly for domestic and export markets.
India
Government-funded medical college hospitals in Maharashtra and Karnataka are establishing dedicated neurocritical care units with temperature management capabilities. CDSCO medical device registration pathways are streamlining for Class B and C thermal regulation products under 2017 rules amendments. The Hyderabad medical technology park is attracting contract manufacturers for surface cooling pad production.
Australia
Perinatal quality collaboratives in New South Wales and Victoria are expanding therapeutic hypothermia to level II and III nurseries for neonatal encephalopathy. TGA conformity assessment procedures for active medical devices are harmonizing with EU MDR technical documentation standards. The Melbourne biomedical precinct hosts R&D operations for portable cooling platform miniaturization.
Therapeutic Hypothermia Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated critical care portfolios dominating hospital capital equipment procurement while standalone cooling vendors concentrate in EMS transport applications. The vendor base organizes into three tiers: multinational conglomerates with bundled surgical and critical care offerings; mid-cap specialists focused exclusively on temperature management; and regional fabricators supplying private-label surface pads and disposable components. Consolidation pressure is intensifying as integrated delivery networks centralize vendor selection at regional headquarters, compressing margins for standalone device manufacturers.
Among the multinational tier, Stryker Corporation and ZOLL Medical Corporation exemplify divergent strategic positioning—Stryker anchoring hospital capital equipment purchasing through integrated surgical and critical care portfolios, ZOLL leveraging defibrillator distribution networks to bundle temperature management with resuscitation workflows. BrainCool AB occupies a specialist position focused on compact, battery-powered surface cooling systems designed for pre-hospital transport scenarios. These three represent distinct competitive archetypes: conglomerate bundling, channel-integrated workflow solutions, and portable specialist engineering.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| BrainCool AB |
| ZOLL Medical Corporation |
| Drägerwerk AG & Co. KgaA |
| Terumo Cardiovascular Systems Corporation |
| Becton, Dickinson and Company |
| Belmont Medical Technologies |
| EM-MED Sp. z o.o. |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Premium invasive cooling catheters certified under EU MDR post-market surveillance mandates command three-to-four-fold markups over surface cooling pads, with this certification-performance divergence manifesting in divergent supply chain configurations: high-margin catheter manufacturers maintain captive European clinical follow-up infrastructure while commodity pad producers source through contract manufacturers in Malaysia and Costa Rica.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement scenarios from planned capital cycles, with integrated delivery networks paying premiums for 30-day delivery windows on invasive cooling platforms while municipal EMS fleets negotiate spot discounts on phase-change material vests from inventory positions. Pricing stratifies across premium, standard, and economy tiers based on temperature precision certification and after-sales service bundling. Cost compression in surface cooling pads is intensifying because group purchasing organizations are consolidating single-use consumable sourcing. Municipal fire departments exhibit highest price sensitivity, while academic medical center value analysis committees prioritize performance specifications over unit economics.
Supply Chain Analysis
Warehouse-distribution layer concentration in the Research Triangle Park cluster and the Kobe medical device hub shapes fulfillment patterns for North American and Asian hospital networks respectively. Precision temperature sensor production centers on Germany and Japan, with chiller unit assembly drawing from Mexico and Malaysia for cost-optimized configurations. Single-source vulnerability in copper heat exchange components creates exposure to commodity price swings. Distribution runs through regional medical equipment distributors holding consignment inventory at tertiary hospital loading docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as catheter manufacturers absorb post-market surveillance capabilities and surface cooling vendors capture upstream gel pad production to defend margin pools.
For Market Incumbents: Extend neurocritical care workflow bundling to preempt standalone cooling device commoditization, while securing captive supply of precision temperature sensors from Baden-Württemberg precision manufacturers to offset semiconductor input volatility. Phase-change material specialists threaten to absorb EMS transport share by eliminating power dependency.
For New Entrants and Emerging Players: Municipal fire department fleet managers represent the most penetrable procurement channel for battery-independent cooling platforms, with India's government-funded medical college hospitals offering secondary white-space for invasive catheter protocols. Position through emergency medical services distributor relationships rather than direct hospital capital committee engagement.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap temperature management specialists with established EU MDR post-market infrastructure and pediatric transport miniaturization capabilities. Long-term viability hinges on software-enabled closed-loop integration with electronic health record architectures. Watch CMS reimbursement determinations for out-of-hospital cardiac arrest protocols as the inflection signal reshaping EMS versus hospital capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Infrastructure Buildout | Annual safety report submissions to notified bodies satisfy tightened clinical evidence requirements for catheter manufacturers. |
| Pediatric Transport Miniaturization | Battery-powered cooling platforms address unmet need for pre-hospital neonatal temperature control during inter-facility transfers. |
| Hospital System Partnership | Single-vendor neurocritical care unit contracts consolidate diagnostic and therapeutic workflows under integrated portfolios. |
| Software Companion Development | Closed-loop autonomous systems adjusting thermal output based on neurological biomarkers redefine competitive differentiation. |
| Reimbursement Strategy | CMS determinations for out-of-hospital cardiac arrest protocols reshape capital allocation between EMS and hospital investments. |
Research Methodology
FDA 510(k) clearance databases, EU MDR notified body submission records, and hospital procurement contract repositories formed the secondary backbone, supplemented by primary interviews with neurointensivists, biomedical engineers, GPO contracts managers, and EMS fleet procurement officers. Bottom-up and top-down triangulation validated volume estimates across surface cooling systems, invasive cooling devices, and neonatal application segments.
Bottom-up modeling anchored forecasts in procedure volume projections and equipment replacement cycles, while top-down analysis cross-checked against neurocritical care unit expansion budgets and EMS capital allocation patterns across the analysis window. Segmentation dimensions included product type, end user setting, clinical application, and delivery mode maturity. CAGRs derived from weighted average of historical replacement cycles and protocol adoption curves, with METI neuroemergency incentives and perinatal quality collaborative standardization serving as key demand inputs.
Caveats apply where EU MDR certification timeline extensions or copper and semiconductor supply disruptions could materially shift the outlook, and decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market