
 One-Step ELISA Market | 2026-2036
One-Step ELISA Market Size, Share, and Industry Trends Forecast 2026-2036
One-Step ELISA Market Analytics
Technician shortages in clinical pathology laboratories is unwinding throughput capacity at hospital networks and reference labs. Thermo Fisher Scientific leverages its reagent manufacturing scale to supply high-volume one-step assay formats. Bio-Rad Laboratories anchors its position through instrument-reagent bundling in diagnostic laboratories. Abcam plc specializes in antibody-intensive detection systems for research workflows.
One-step ELISA denotes an enzyme-linked immunosorbent assay format where sample incubation, detection, and signal generation occur in a single operational phase without intermediate washing steps, typically employing pre-coated capture antibodies and conjugated detection reagents in dry-phase or homogeneous liquid architectures that reduce total assay time below ninety minutes. The format serves clinical diagnostics, food safety screening, and environmental monitoring applications where laboratory throughput and operator time constraints drive purchasing decisions. Reagent kits command the dominant value share within product type segmentation due to recurring purchase cycles and proprietary formulation lock-in. Chemiluminescent detection technology leads technology segmentation in revenue per test owing to superior sensitivity and dynamic range in quantitative analyte measurement.
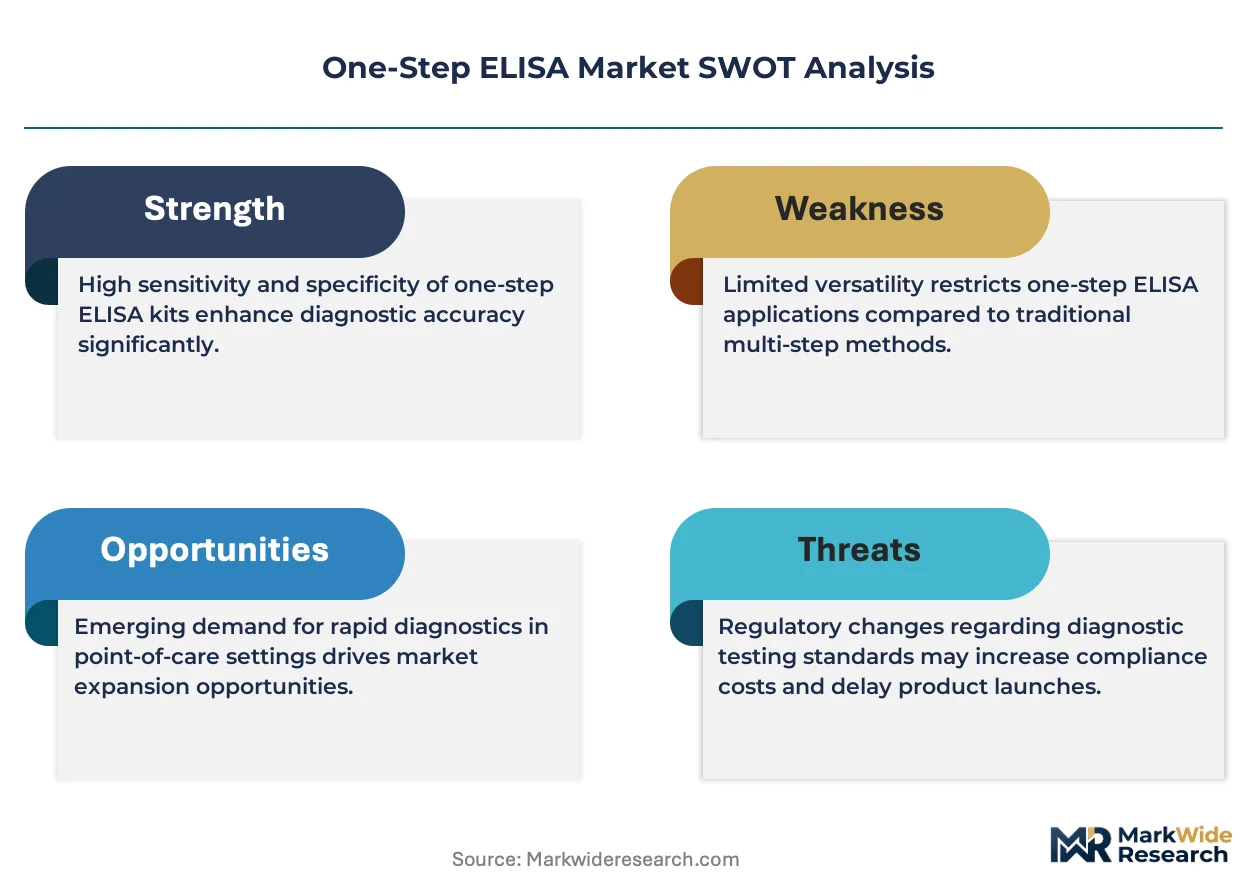
FDA quality system regulation and CLIA proficiency testing requirements shape product development priorities for US-market suppliers, while the EU In Vitro Diagnostic Regulation mandates expanded clinical evidence and post-market surveillance for CE-marked assay systems. The European Medicines Agency coordinates with notified bodies on performance evaluation standards for high-risk diagnostic devices. Stakeholders must monitor evolving premarket submission pathways as regulatory convergence between major jurisdictions accelerates compliance complexity.
Market Dynamics
Laboratory consolidation across hospital networks is compressing purchasing cycles and forcing assay suppliers to bundle reagent contracts with multi-year service agreements, reshaping vendor-client relationships from transactional to embedded partnerships.
Growth Catalysts
- CLIA-waived test expansion:FDA streamlined categorization protocols for moderately complex diagnostics enable point-of-care deployment in physician office laboratories, extending one-step ELISA reach beyond centralized facilities.
- Food safety modernization:USDA FSIS pathogen detection mandates for poultry and beef processing lines require rapid screening throughput that homogeneous assay formats deliver without dedicated wash stations.
- Microfluidic integration:Lab-on-a-chip architectures from precision medicine clusters in Munich and Heidelberg reduce sample volume requirements below fifty microliters, opening pediatric and neonatal applications.
Market Restraints
- Monoclonal antibody supply concentration:Bioreactor capacity for high-affinity capture antibodies concentrates among contract manufacturers in Switzerland and South Korea, creating input bottlenecks during demand surges.
- Cross-reactivity limitations:Single-wash elimination in one-step formats sacrifices selectivity in multiplexed panels, restricting quantitative accuracy for complex biomarker signatures in autoimmune diagnostics.
- IVDR transition friction:EU In Vitro Diagnostic Regulation performance evaluation requirements for Class C devices extend CE-marking timelines by fourteen to eighteen months versus predecessor directives.
Strategic Opportunities
- Veterinary diagnostics whitespace:Companion animal reference laboratories in Australia and Canada currently underutilize streamlined immunoassay protocols, presenting first-mover expansion potential.
- Environmental water monitoring:EPA-approved methods for algal toxin detection in drinking water sources lack rapid-format alternatives, creating regulatory tailwind for validated one-step alternatives to HPLC-MS workflows.
- Digital integration:Smartphone-readable lateral flow conjugates combined with cloud-based calibration algorithms enable decentralized result interpretation without dedicated photometric instrumentation.
Industry Challenges
- Technician certification gaps:CLIA personnel standards for high-complexity testing create recruitment friction in rural hospital laboratories where one-step formats would otherwise offset staffing shortages.
- Legacy LIS integration:Proprietary data formats from 1990s-era laboratory information systems require middleware development for seamless assay result transmission, delaying protocol adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | One-Step ELISA Market |
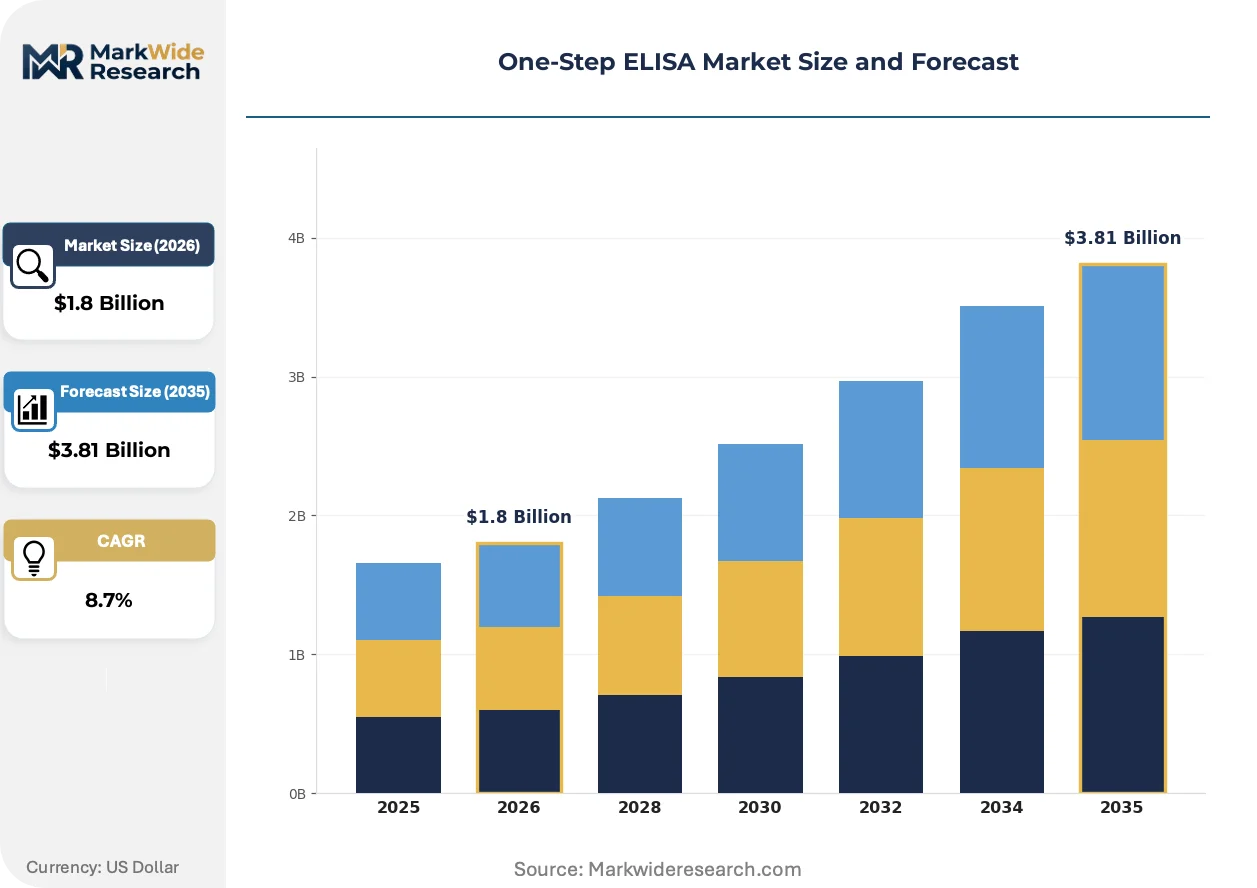
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Kits, Microplates, Assay Controls, Detection Systems Application: Clinical Diagnostics, Food Safety, Environmental Testing, Research Labs End User: Hospitals, Diagnostic Laboratories, Research Institutions, Pharmaceutical Companies Technology: Fluorescent, Colorimetric, Chemiluminescent, Electrochemical |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., Abcam plc, PerkinElmer Inc., Danaher Corporation, Merck KGaA, Abbott Laboratories, BosterBio, Abcam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
One-Step ELISA Market Evolving Landscape
Dry-phase reagent stabilization and ambient-temperature logistics are collapsing cold-chain dependencies that previously constrained assay distribution to developed-market laboratory networks.
Chemiluminescent substrate formulations are bifurcating competitive positioning between high-sensitivity quantitative platforms and cost-optimized qualitative screening tools. Academic medical centers in the United States prioritize signal-to-noise ratios below picogram-per-milliliter detection limits, while public health laboratories in Brazil and Mexico adopt simplified colorimetric alternatives for field surveillance. This technical stratification is compressing mid-tier instrument vendors between premium research-grade systems and disposable rapid-test economics.
EU In Vitro Diagnostic Regulation Article 56 performance study requirements are forcing retrospective clinical evidence collection for legacy assays previously grandfathered under IVDD directives. Manufacturers must now generate patient cohort data for conditions with low prevalence, extending time-to-market for niche biomarker panels. German notified bodies are processing submissions for infectious disease assays at half the pace of cardiovascular markers, creating geographic variation in product availability across European reference laboratories.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships at integrated delivery networks. Hospital systems exceeding two hundred beds increasingly mandate sole-source contracts for reagent categories, compressing vendor margins in exchange for volume guarantees. This concentration is most visible in the southeastern United States, where Catholic health initiatives and for-profit chains have centralized laboratory spend decisions to regional headquarters.
One-Step ELISA Market Segmentation
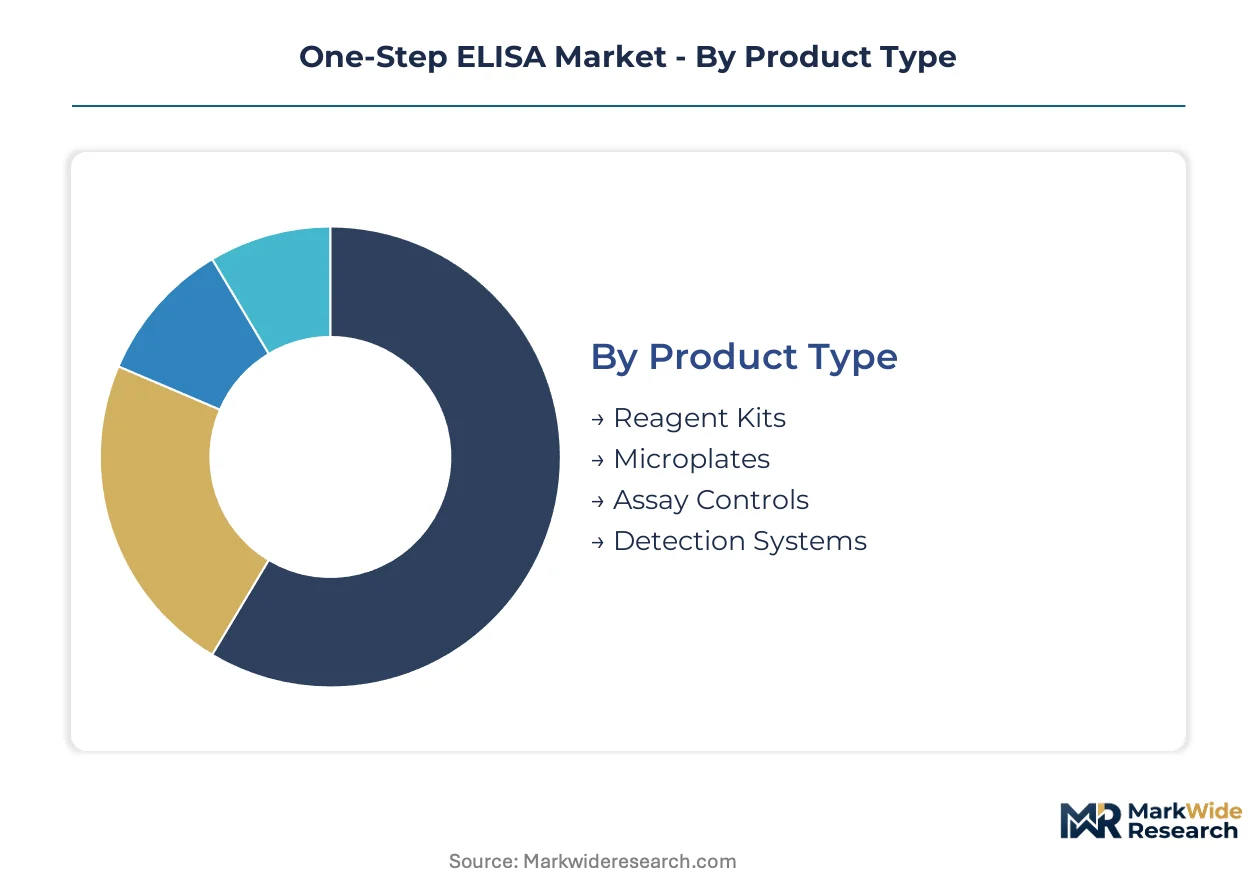
Segmentation in the one-step ELISA market reveals distinct substitution pressures across product and technology dimensions. Reagent formulations face displacement from lyophilized bead formats, while detection modalities compete on sensitivity-per-dollar benchmarks against emerging biosensor platforms.
Product Type:
Reagent Kits face the strongest substitution threat from ambient-stable dry-phase alternatives that eliminate cold-chain dependencies.
- Reagent Kits:Proprietary buffer formulations and conjugated detection antibodies packaged for single-use workflows command recurring revenue through locked-in assay protocols. Clinical diagnostics laboratories in the United States concentrate procurement through multi-year sole-source contracts that embed these kits within automated liquid handling systems.
- Microplates:Pre-coated 96-well and 384-well polystyrene surfaces with dried capture antibodies enable walk-away automation without manual pipetting steps. Germany's precision medicine corridor around Munich and Heidelberg drives specialized demand for low-binding surface chemistries in proteomics workflows.
- Assay Controls:Calibrator panels and quality control materials traceable to WHO international standards ensure analytical validation compliance.
- Detection Systems:Integrated photometric readers and smartphone-compatible lateral flow analyzers complete the assay workflow.
Reagent Kits anchors the volume base while Detection Systems gains share at the steepest rate.
Application:
Cost tier differentiation separates high-complexity reference laboratory testing from waived point-of-care deployment.
- Clinical Diagnostics:Infectious disease serology, cardiac biomarker quantification, and autoimmune panel screening in hospital core laboratories. FDA CLIA categorization protocols determine whether assays deploy in physician office laboratories or remain centralized.
- Food Safety:Pathogen detection for Salmonella, Listeria, and E. coli in poultry and beef processing environments. USDA FSIS mandate compliance drives homogeneous assay adoption without dedicated wash stations.
- Environmental Testing:Algal toxin monitoring in drinking water sources and agricultural runoff assessment.
- Research Labs:Biomarker discovery and preclinical pharmacokinetic studies in academic medical centers.
Clinical Diagnostics commands the revenue concentration while Food Safety climbs the fastest.
End User:
Customer type segmentation reflects divergent procurement authority and technical validation requirements.
- Hospitals:Integrated delivery networks exceeding two hundred beds centralize laboratory spend decisions to regional headquarters. Catholic health initiatives and for-profit chains in the southeastern United States mandate sole-source reagent contracts.
- Diagnostic Laboratories:Reference labs and hospital outreach programs prioritize throughput-per-technician metrics. CLIA personnel standards for high-complexity testing create recruitment friction in rural facilities where streamlined formats would offset staffing gaps.
- Research Institutions:Academic medical centers prioritize signal-to-noise ratios below picogram-per-milliliter detection limits for biomarker discovery.
- Pharmaceutical Companies:Preclinical and clinical trial support services require GLP-compliant assay validation.
Diagnostic Laboratories anchors the installed base while Hospitals drive the steepest expansion trajectory.
Technology:
Margin stratification separates premium quantitative platforms from cost-optimized qualitative screening tools.
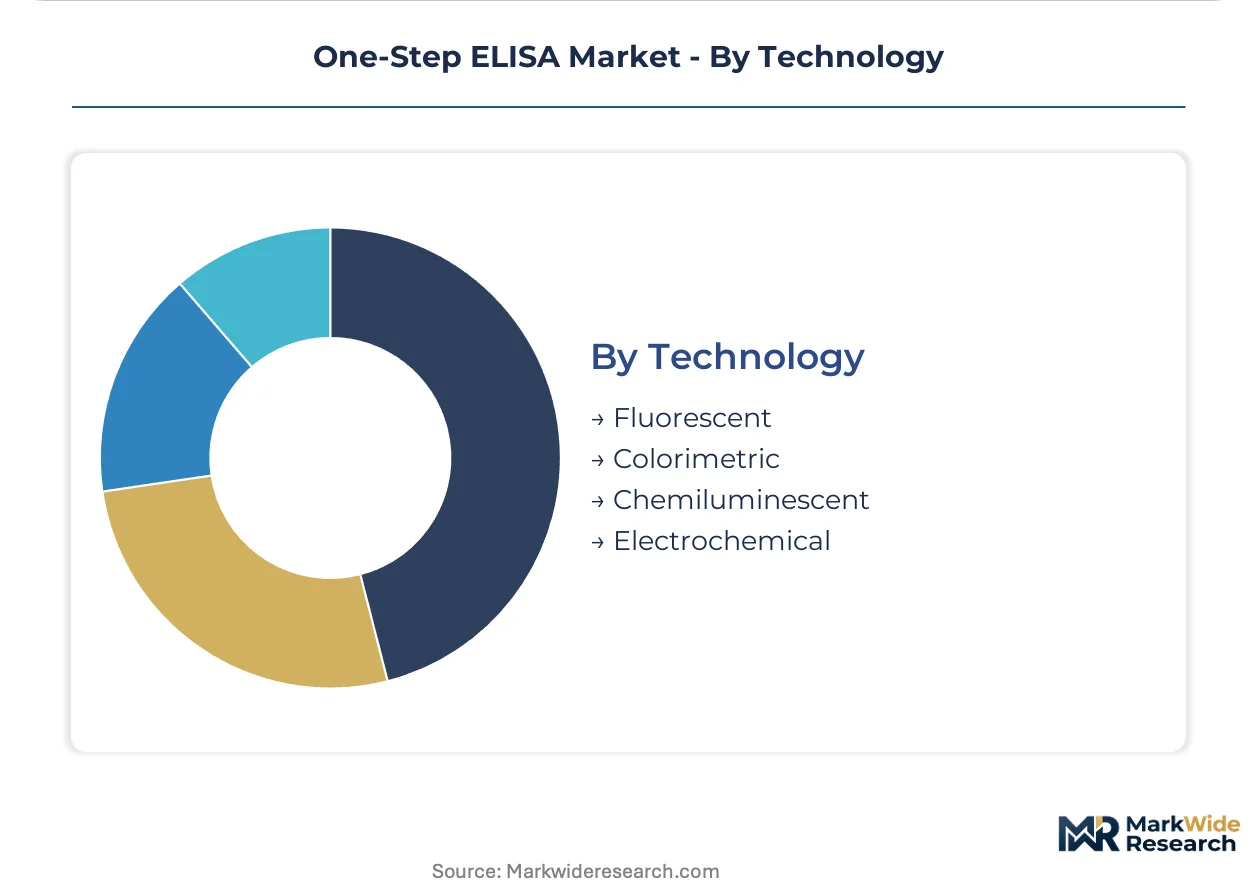
- Chemiluminescent:Acridinium ester and alkaline phosphatase substrate systems deliver superior dynamic range for quantitative analyte measurement. Academic medical centers in the United States prioritize these platforms for low-abundance biomarker detection.
- Colorimetric:Tetramethylbenzidine and horseradish peroxidase chromogenic reactions provide cost-optimized visual readout. Public health laboratories in Brazil and Mexico adopt these alternatives for field surveillance without dedicated instrumentation.
- Fluorescent:Europium chelate and quantum dot labels enable multiplexed detection in research applications.
- Electrochemical:Amperometric and impedimetric transducers integrate with lab-on-a-chip architectures for point-of-care deployment.
Chemiluminescent dominates revenue per test while Electrochemical expands most quickly through microfluidic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reagent pricing power concentrates in Swiss and German precision medicine corridors, while US hospital networks extract volume discounts through consolidated procurement. This asymmetry shapes regional vendor strategies and margin structures across diagnostic supply chains.
United States
CLIA-waived test expansion and hospital laboratory consolidation drive homogeneous assay adoption. FDA quality system regulation tightens analytical validation requirements for in vitro diagnostic submissions. The southeastern United States sees Catholic health initiatives and for-profit chains centralizing reagent spend decisions to regional headquarters.
Germany
Precision medicine clusters around Munich and Heidelberg prioritize microfluidic-integrated detection systems for low-volume applications. EU In Vitro Diagnostic Regulation mandates expanded clinical evidence for CE-marked assay systems. Notified bodies process infectious disease submissions at half the pace of cardiovascular markers, creating geographic variation in product availability.
China
Domestic bioreactor capacity for high-affinity capture antibodies scales to reduce import dependency from Swiss contract manufacturers. NMPA streamlined review pathways accelerate local assay approvals versus imported alternatives. Yangtze River Delta diagnostic manufacturers capture share in tier-two hospital laboratory procurement.
Brazil
Public health laboratories adopt simplified colorimetric formats for field surveillance without dedicated photometric instrumentation. ANVISA alignment with international standards facilitates parallel registration pathways for CE-marked assays. São Paulo reference laboratories pilot smartphone-readable lateral flow systems for decentralized result interpretation.
Japan
Academic medical centers demand signal-to-noise ratios below picogram-per-milliliter detection limits for biomarker discovery workflows. PMDA consultation procedures for novel assay platforms extend premarket timelines versus predicate device pathways. Tokyo and Osaka metropolitan hospital networks consolidate purchasing through regional medical association frameworks.
One-Step ELISA Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Consolidated procurement through group purchasing organizations compresses vendor margins in exchange for multi-year volume guarantees. Three strategic archetypes dominate: diversified life science conglomerates with reagent manufacturing scale, specialized antibody suppliers with research workflow expertise, and precision instrument-reagent bundlers. M&A activity targets microfluidic technology assets, while strategic partnerships lock in multi-year service agreements with integrated delivery networks.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify scale-driven reagent supply positions. Bio-Rad Laboratories Inc. anchors the instrument-reagent bundling archetype for diagnostic laboratory workflows. Abcam plc occupies a specialist position in antibody-intensive detection systems for research applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| Abcam plc |
| PerkinElmer Inc. |
| Danaher Corporation |
| Merck KGaA |
| Abbott Laboratories |
| BosterBio |
| Abcam |
| Others |
Value Network & Pricing Analysis
Ninety-day antibody bioreactor lead times concentrate pricing power among Swiss and South Korean contract manufacturers while compressing margins for downstream assay kit suppliers. This inventory-to-pricing linkage tightens whenever hospital group purchasing organizations consolidate procurement across integrated delivery networks.
Pricing Analysis
Configured-to-order microplate surface chemistries command substantial premiums over standard polystyrene formats. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in economy-tier colorimetric kits intensifies because public health laboratories in Brazil and Mexico prioritize field-deployable formats over laboratory-grade sensitivity. Reference laboratories exhibit lowest price sensitivity due to locked-in validation protocols, while physician office laboratories face acute budget constraints under CLIA-waived reimbursement schedules.
Supply Chain Analysis
Inventory cycles stretching fourteen to eighteen months for high-affinity monoclonal antibodies expose kit manufacturers to bioreactor capacity constraints. Supply concentrates in Switzerland, South Korea, and China's Yangtze River Delta for capture antibody production. Lyophilized reagent formulations and conjugated detection enzymes constitute critical input dependencies. Single-source vulnerability pervades specialized surface chemistry substrates. Distribution runs through diagnostic distributor networks and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated hospital networks and group purchasing organizations, fragmenting vendor pricing autonomy as two-hundred-bed systems centralize laboratory spend decisions.
For Market Incumbents: Shield proprietary reagent formulations through multi-year sole-source contracts that embed technical service agreements. Deepen backward integration into bioreactor capacity for high-affinity antibodies to offset Swiss and South Korean supply bottlenecks. Counter electrochemical biosensor substitutes by accelerating chemiluminescent sensitivity roadmaps.
For New Entrants and Emerging Players: Lead with smartphone-readable lateral flow formats targeting veterinary diagnostics whitespace in Australia and Canada. Exploit underpenetrated environmental water monitoring applications where EPA-approved rapid alternatives to HPLC-MS workflows face regulatory tailwinds. Pursue cloud-based calibration algorithms as the primary go-to-market wedge against instrument-reagent bundlers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because laboratory automation and microfluidic integration favor scaled reagent manufacturers over fragmented antibody specialists. Target precision instrument-reagent bundlers with established hospital system relationships. Monitor IVDR transition timelines at German notified bodies as the critical inflection signal for European product availability gaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Technology Acquisition | Lab-on-a-chip architectures from Munich and Heidelberg clusters reduce sample volumes below fifty microliters. |
| Multi-Year Hospital System Partnership | Sole-source reagent contracts with Catholic health initiatives and for-profit chains lock out competitors. |
| Dry-Phase Reagent Stabilization | Ambient-temperature logistics collapse cold-chain dependencies constraining distribution to developed markets. |
| CE Marking Pathway Acceleration | EU IVDR Article 56 performance studies extend timelines fourteen to eighteen months versus predecessor directives. |
| CLIA-Waived Test Expansion | FDA streamlined categorization protocols enable point-of-care deployment in physician office laboratories. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with diagnostic laboratory directors, reagent procurement managers, biomedical engineers, and regulatory affairs specialists at IVD manufacturers; and secondary validation against FDA 510(k) filings, EU IVDR submission databases, CMS Medicare laboratory fee schedules, and hospital group purchasing organization contract disclosures. Bottom-up triangulation across product segments and top-down cross-checks against macro healthcare expenditure trends anchored volume and value estimates.
Across the modeling period, forecasts integrated reagent kit replacement cycles, instrument installed base depreciation, and technology substitution curves between detection modalities. Segmentation dimensions spanned product type, application, end user, and technology tier. CAGRs derived from logistic diffusion modeling of adoption rates and price elasticity coefficients specific to clinical diagnostics procurement.
The analysis sits within stated boundaries; outcomes outside stable regulatory frameworks and continuous hospital network consolidation would require recalibration. Forecasts reflect documented assumptions regarding IVDR transition pacing and CLIA personnel standard enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market