
 Iceland Telecom Market | 2026-2036
Iceland Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Iceland Telecom Market Insights
Iceland is fragmenting its telecom infrastructure investment across multiple technology layers simultaneously. Síminn leverages its historic incumbent position to sustain nationwide fixed-line coverage. Nova competes aggressively in mobile data pricing while Míla anchors the wholesale fiber and tower backbone that rivals depend upon.
Iceland telecom encompasses the transmission of voice, data, and video services through wireless and wireline infrastructure operating across frequencies from 700 MHz to 3.5 GHz and fiber optic cables with single-mode silica cores. The primary purpose is enabling connectivity for residential consumption, enterprise operations, and public administration across a dispersed island geography. Mobile services generate the largest revenue pool though fiber optic deployment captures the fastest expansion as households upgrade from DSL. Enterprise customer segments concentrate margin where bundled cloud-based installations and SLA-guaranteed bandwidth command premium pricing.
Post and Telecom Administration in Iceland enforces the EU Electronic Communications Code while BIS-aligned standards govern equipment certification. GDPR compliance requirements shape how providers handle subscriber data and consent management. Stakeholders must monitor spectrum auction timing and wholesale access pricing decisions that will determine whether challenger brands can extend market presence beyond Reykjavik.
Market Dynamics
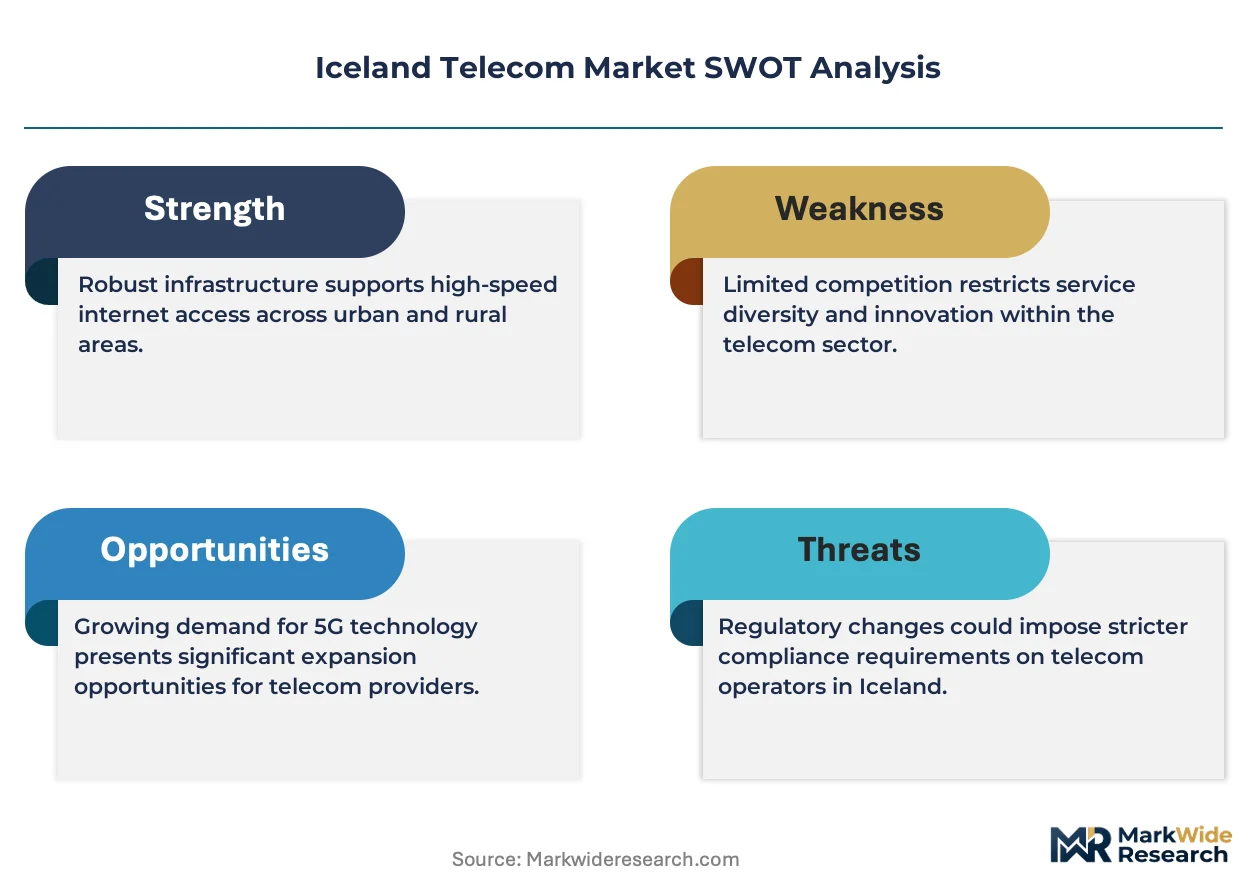
The Iceland telecom sector is restructuring around wholesale infrastructure unbundling, where Míla's fiber and tower assets now serve multiple competing retail brands rather than a single integrated operator.
Growth Catalysts
- EU Electronic Communications Code:Iceland's national regulator has implemented wholesale access mandates that lower barriers for challenger operators seeking to extend coverage beyond Reykjavik.
- Enterprise cloud migration:Icelandic businesses are consolidating voice, video, and data services onto unified platforms that require guaranteed SLA bandwidth.
- Capital region fiber density:Reykjavik's metropolitan infrastructure concentration creates demonstration effects that accelerate household upgrade decisions in surrounding municipalities.
Market Restraints
- Geographic dispersion costs:Iceland's volcanic terrain and low population density outside the capital region inflate per-subscriber deployment costs for rural fiber extension.
- Wholesale dependency:Retail operators without tower or fiber assets face margin compression when Míla adjusts wholesale pricing for backhaul and site access.
- Submarine cable concentration:International connectivity routes through Farice and Greenland Connect create single-point-of-failure risks for data transit pricing.
Strategic Opportunities
- Data center adjacency:Iceland's renewable-powered compute clusters near Keflavík generate demand for low-latency dark fiber and dedicated wavelength services.
- Smart grid integration:Landsnet's electricity infrastructure investments open shared trenching opportunities for fiber deployment in previously uneconomic corridors.
- GDPR-compliant hosting:Privacy-conscious European enterprises are evaluating Icelandic data residency for cloud workloads, driving premium connectivity demand.
Industry Challenges
- Radio frequency engineering scarcity:Specialized talent for 5G mmWave propagation modeling in Arctic conditions commands premium compensation and extends network optimization timelines.
- Legacy copper remediation:Operators must maintain parallel DSL infrastructure during fiber migration, duplicating operational expenditure without corresponding revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iceland Telecom Market |
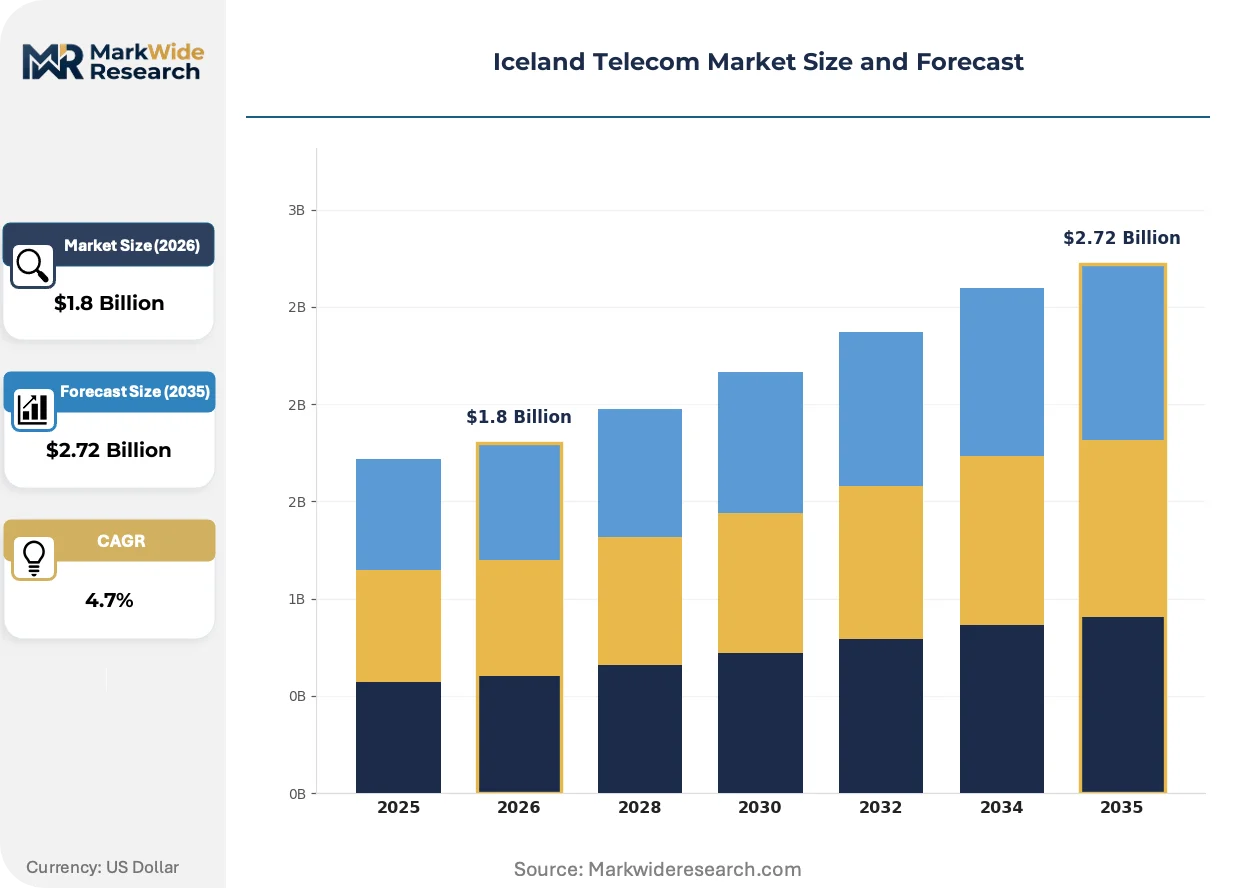
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed Broadband, VoIP Services, TV Services Technology: 4G LTE, 5G NR, Fiber Optic, DSL Customer Type: Residential Users, Small Businesses, Enterprises, Government Installation: On-premise, Cloud-based, Remote Setup, Self-installation |
| Companies Covered | Síminn, Sýn, Nova, Míla, Tengir, Hringiðan, Hringdu, 365 Media, Tal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iceland Telecom Market Trends and Innovations
Virtualization is dissolving the hardware boundaries that once separated network functions, allowing Icelandic operators to deploy services as software workloads rather than purpose-built appliances.
Open RAN architectures are virtualizing baseband processing functions that previously required vendor-locked hardware. Síminn and Nova are piloting multi-vendor radio access networks in Reykjavik test zones. This shift is virtualizing capital deployment patterns, enabling faster spectrum refarming without full hardware replacement cycles.
Post and Telecom Administration enforcement of GDPR-aligned consent frameworks is reshaping subscriber data handling protocols. Providers must now implement granular permission systems for location and usage analytics. Enterprise segments face the strictest compliance verification, with financial services and healthcare verticals demanding documented data residency guarantees.
Households are fragmenting their service procurement across multiple retail brands rather than accepting bundled packages from incumbents. Consumers are separating mobile subscriptions from fixed broadband to exploit promotional pricing arbitrage. This pattern concentrates in Reykjavik's younger demographic segments, where switching friction is lowest and digital comparison tools are most utilized.
Iceland Telecom Market Segmentation
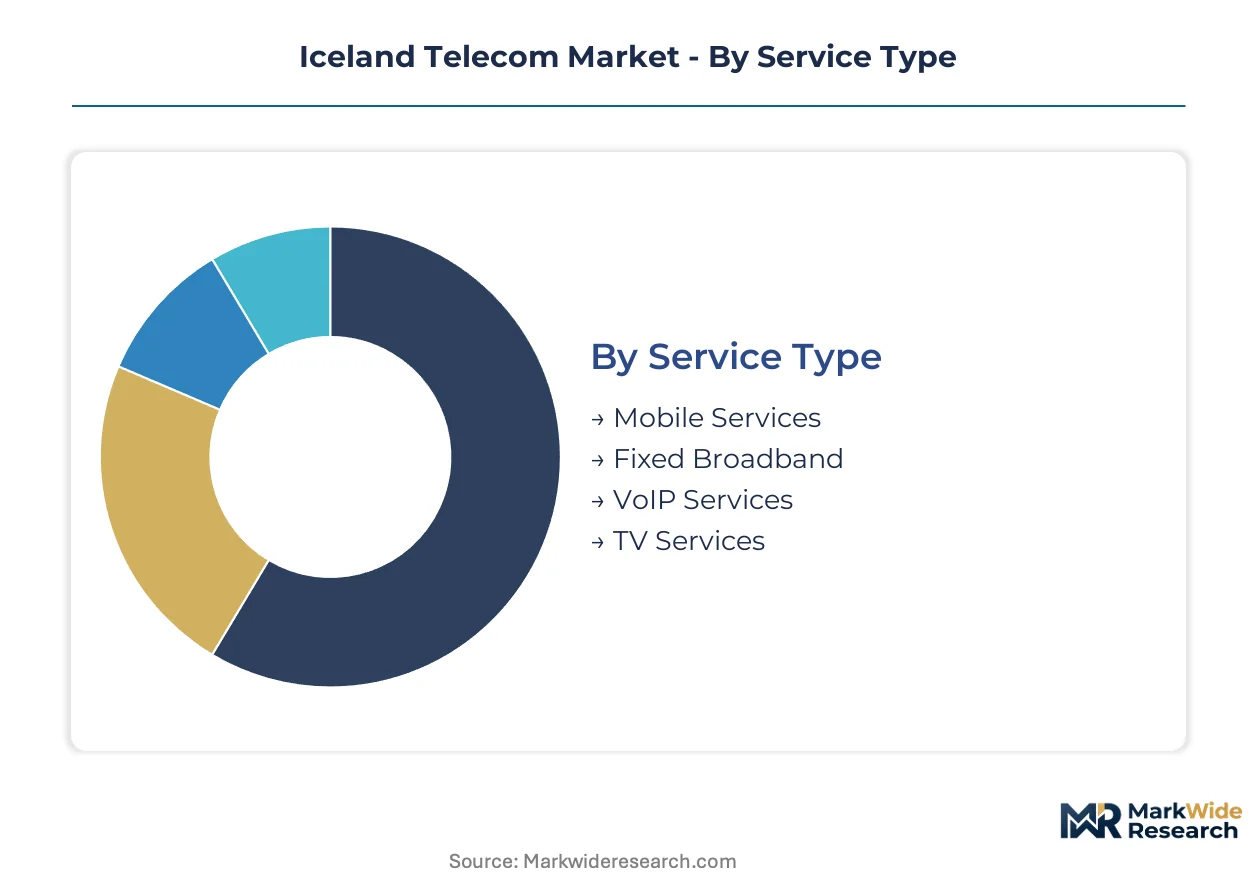
Iceland's telecom market fragments across four distinct dimensions that shape competitive positioning. Service type and technology layers determine infrastructure investment priorities, while customer type and installation mode dictate pricing flexibility and operational complexity for retail operators.
Service Type:
Service type spans the full connectivity spectrum from mobile voice to converged entertainment bundles.
- Mobile Services:Wireless voice and data transmission across 4G LTE and 5G NR networks operating in sub-6 GHz bands. Demand concentrates among younger demographics in Reykjavik and Akureyri where unlimited data plans and device financing drive subscriber acquisition.
- Fixed Broadband:Wireline internet access delivered via fiber optic, DSL, or hybrid technologies with symmetric upload-download speeds. Households in the capital region upgrade from copper to fiber most aggressively, spurred by remote work requirements and streaming bandwidth needs.
- VoIP Services:Packet-switched voice communications replacing traditional PSTN lines, often bundled with broadband packages. Small businesses in Kópavogur and Hafnarfjörður adopt cloud-PBX solutions to eliminate premise-based hardware maintenance.
- TV Services:Linear and over-the-top video distribution via IPTV, satellite, or terrestrial broadcast. Residential subscribers fragment across Síminn, Nova, and Vodafone Iceland based on exclusive sports rights and Nordic content libraries.
The dominant share belongs to Mobile Services, while Fixed Broadband is closing the gap fastest.
Technology:
Technology layers stack from legacy copper through fiber and cellular generations, each carrying different capital intensity profiles.
- 5G NR:New radio interface operating in 3.5 GHz and 700 MHz bands with massive MIMO antenna configurations. Síminn and Nova deploy 5G most densely in Reykjavik's financial district and university corridors where enterprise edge computing trials create early demand.
- Fiber Optic:Single-mode silica core cables delivering gigabit symmetrical speeds with sub-millisecond latency. Míla's wholesale fiber backbone extends furthest in Suðurnes and Vesturland, enabling retail operators to bypass last-mile construction costs.
- 4G LTE:Existing cellular infrastructure carrying majority of mobile data traffic through carrier aggregation. Rural municipalities outside the capital region remain dependent on 4G for broadband-equivalent service where fiber economics fail.
- DSL:Digital subscriber line over copper pairs with asymmetric speeds declining as fiber overbuilds progress. Legacy infrastructure persists in older Reykjavik apartment blocks and remote fishing villages awaiting trenching permits.
Fiber Optic claims the steepest expansion trajectory as Míla accelerates wholesale coverage obligations, though 5G NR deployment absorbs disproportionate regulatory attention.
Customer Type:
Customer type stratifies by organizational scale and procurement sophistication, from individual households to national agencies.
- Enterprises:Large organizations requiring SLA-guaranteed bandwidth, managed security, and unified communications platforms. Financial services firms in Reykjavik's Borgartún district demand dedicated wavelength services and GDPR-compliant data residency.
- Residential Users:Individual households and families consuming bundled connectivity and entertainment services. Price-sensitive consumers exploit promotional arbitrage by separating mobile from fixed subscriptions across competing retail brands.
- Government:National and municipal agencies procuring secure connectivity for public administration and emergency services. The Post and Telecom Administration mandates universal service obligations that cross-subsidize rural infrastructure.
- Small Businesses:Independent operators and professional services firms with standardized connectivity needs. Restaurants, retail shops, and construction trades in Akureyri and Selfoss prioritize mobile-first solutions over fixed-line investment.
Enterprises command premium pricing and longest contract terms, while Residential Users generate volume scale that amortizes network fixed costs.
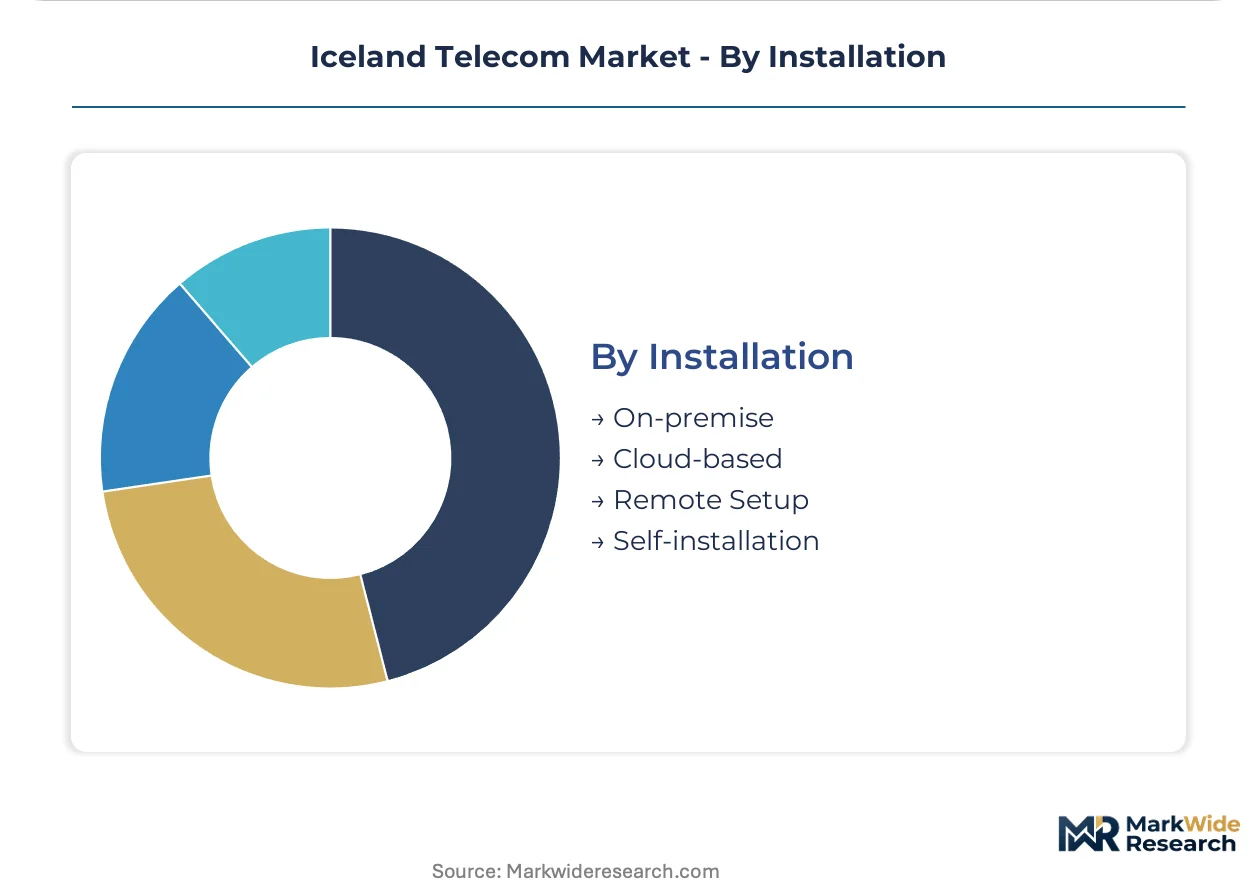
Installation:
Installation mode reflects operational trade-offs between technician dispatch costs and customer self-service capabilities.
- Cloud-based:Fully virtualized service delivery requiring no premise equipment beyond standard CPE. Enterprise VoIP and security services deploy through browser-based configuration portals, eliminating truck rolls.
- On-premise:Physical equipment installation by certified technicians with structured cabling and power backup. Legacy PBX systems and dedicated server racks in healthcare and government facilities demand hands-on commissioning.
- Self-installation:Subscriber-activated equipment with QR-code provisioning and mobile app guidance. Fiber modems and mesh Wi-Fi systems ship to residential addresses for plug-and-play deployment.
- Remote Setup:Technician-guided activation via video call without physical site visit. Small businesses in dispersed geographies receive real-time support for router configuration and network segmentation.
Cloud-based delivery is gaining share fastest as virtualization dissolves hardware dependencies, though On-premise retains necessity for regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom infrastructure investment concentrates in the capital region while wholesale fiber unbundling reshapes competitive access across Iceland's dispersed settlement pattern. Regulatory mandates from the Post and Telecom Administration enforce EU Electronic Communications Code wholesale obligations. Submarine cable landing points at Keflavík and Reykjavik anchor international bandwidth pricing.
Capital Region
Reykjavik and surrounding municipalities generate the densest subscriber base for 5G and fiber services. The Post and Telecom Administration prioritizes spectrum allocation trials in this zone. Financial services firms in Borgartún district drive enterprise demand for SLA-guaranteed wavelength services.
Southern Peninsula
Suðurnes benefits from Míla's wholesale fiber backbone extension and data center clustering near Keflavík International Airport. Landsnet's electricity grid investments enable shared trenching for fiber deployment. Renewable-powered compute facilities here generate demand for low-latency dark fiber connectivity.
West Iceland
Vesturland municipalities rely on 4G LTE for broadband-equivalent service where fiber economics fail. The national regulator's universal service obligations cross-subsidize infrastructure in this corridor. Fishing villages along Snæfellsnes await trenching permits for last-mile fiber overbuilds.
North Iceland
Akureyri anchors regional demand with mobile-first small businesses and younger demographics exploiting promotional pricing arbitrage. Wholesale access pricing decisions from Reykjavik determine whether challenger brands extend presence here. Remote agricultural and tourism operations depend on satellite backup for connectivity resilience.
Eastfjords
Seyðisfjörður and neighboring settlements face the highest per-subscriber deployment costs due to mountainous terrain and low population density. Submarine cable landing diversity through Farice routes creates single-point-of-failure risks for data transit. Seasonal tourism fluctuations complicate revenue predictability for retail operators.
Iceland Telecom Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in Iceland's wholesale-dependent structure. The market operates through a tiered configuration where historic incumbents, mobile-focused challengers, and wholesale infrastructure providers coexist under regulated access terms. Three archetypes dominate: integrated retail operators with legacy fixed-line assets, mobile-first brands competing on data pricing, and wholesale fiber/tower utilities supplying backhaul to rivals. Competitive moves concentrate on spectrum positioning for 5G services and fiber unbundling negotiations that determine retail margin structures.
Within the integrated operator tier, Síminn leverages its historic incumbent position to sustain nationwide fixed-line coverage while competing in mobile services. Nova exemplifies the mobile-first challenger archetype, competing aggressively on data pricing and subscriber acquisition in Reykjavik's younger demographic segments. Míla anchors the wholesale infrastructure tier, controlling fiber and tower assets that multiple retail brands depend upon for backhaul and site access.
| Leading Market Players |
|---|
| Síminn |
| Sýn |
| Nova |
| Míla |
| Tengir |
| Hringiðan |
| Hringdu |
| 365 Media |
| Tal |
| Others |
Pricing and Supply Chain Analysis
Reykjavik's metropolitan fiber concentration anchors pricing power for wholesale bandwidth, with Míla's infrastructure dominance translating directly into tiered retail margin structures across Iceland's dispersed settlement pattern.
Pricing Analysis
The EU Electronic Communications Code dictates the pricing tier structure through wholesale access mandates that compress retail margins for challenger operators. Three-tier pricing structure across premium SLA-guaranteed, standard residential, and economy mobile-data tiers separates enterprise contracts from household bundles. Pricing pressure stems from Nova's aggressive data pricing arbitrage in Reykjavik's younger demographics. Residential users exhibit highest price sensitivity through promotional switching, while financial services firms in Borgartún show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Submarine cable landing concentration at Keflavík dominates supply chain risk for international bandwidth, with Farice and Greenland Connect routes creating single-point-of-failure exposure for data transit pricing. Equipment sourcing draws from Finland, Sweden, and Germany for base station hardware and fiber optic components. Radio frequency engineering talent scarcity in Arctic conditions extends deployment timelines. Distribution runs through Míla's wholesale fiber backbone to retail operators who manage last-mile customer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iceland's telecom market operates as a defensive-moat story where regulatory entrenchment through universal service obligations and spectrum licensing creates sustainable incumbent advantages against challenger price competition.
For Market Incumbents: Harden wholesale infrastructure control by accelerating fiber unbundling negotiations before challenger brands consolidate rural market share. Secure 5G mmWave spectrum positions in Reykjavik's enterprise corridors to preempt Nova's mobile-first expansion. Vertical integration into data center adjacency services near Keflavík captures premium connectivity demand from renewable-powered compute clusters. For New Entrants and Emerging Players: Pursue white-space opportunities in Akureyri's mobile-first small business segment where incumbent fixed-line penetration remains lowest. Target Eastfjords municipalities underserved by fiber economics, leveraging satellite-terrestrial hybrid solutions for seasonal tourism operations. Go-to-market through remote setup capabilities eliminates technician dispatch costs in dispersed geographies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wholesale infrastructure utilities with regulated return profiles over retail operators facing margin compression. Long-term viability hinges on fiber backbone assets with contractual wholesale access obligations under EU Electronic Communications Code enforcement. Watch Míla's wholesale pricing decisions as the inflection signal for retail operator profitability trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Wholesale Fiber Unbundling | EU Electronic Communications Code mandates lower barriers for challenger retail operators beyond Reykjavik. |
| 5G mmWave Spectrum Positioning | Enterprise edge computing trials in Borgartún district create early demand for high-bandwidth services. |
| Data Center Adjacency Services | Renewable-powered compute clusters near Keflavík generate premium dark fiber and wavelength demand. |
| Smart Grid Shared Trenching | Landsnet electricity infrastructure investments open fiber deployment in previously uneconomic rural corridors. |
| GDPR-Compliant Hosting Partnerships | Privacy-conscious European enterprises evaluate Icelandic data residency for cloud workload connectivity. |
Research Methodology
Initial hypotheses were tested against primary input from network engineering directors, wholesale pricing managers, regulatory affairs specialists at the Post and Telecom Administration, and enterprise IT procurement officers at financial services firms, then refined through secondary validation against EU Electronic Communications Code implementation documents, Farice submarine cable capacity disclosures, Icelandic Competition Authority rulings, and operator spectrum auction filings. Bottom-up subscriber and revenue modeling was cross-checked against top-down market sizing from infrastructure investment tracking.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeling across service type, technology layer, customer scale, and installation mode dimensions. CAGRs were derived from infrastructure deployment trajectories and subscriber migration patterns between legacy copper and fiber platforms. Forecast inputs incorporated Míla's wholesale coverage obligations and 5G spectrum refarming timelines without specific year anchoring.
Sensitivities concentrate around regulatory enforcement intensity for wholesale access pricing and submarine cable route diversification decisions. Forecasts reflect documented assumptions about enterprise cloud migration velocity and household upgrade timing from DSL. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Russia Telecom Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
5G Connections Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
Cellular Modem Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Bahrain Telecom Market
Telecommunications
Indonesia ICT Market
Telecommunications
LTE Base Station System Market