
 Medical 5G Market | 2026-2036
Medical 5G Market Size, Share, and Industry Trends Forecast 2026-2036
Medical 5G Market Insights
Network slicing is tilting the architecture of medical 5G deployments from generic broadband toward guaranteed quality-of-service lanes for critical care. Ericsson leverages its radio access network portfolio to anchor European hospital networks requiring ultra-reliable low-latency connectivity. Huawei Technologies dominates integrated baseband and antenna systems across Asia-Pacific health corridors, while Cisco Systems specializes in secure edge routing that sustains HIPAA-compliant data paths between ambulances and emergency departments.
Medical 5G encompasses dedicated wireless infrastructure, clinical endpoints, and orchestration software operating in licensed and unlicensed spectrum bands to deliver sub-10 millisecond latency for real-time diagnostic and interventional workflows. Its primary purpose is to enable synchronous remote procedures, continuous patient monitoring, and AI-augmented clinical decision support without wired tethering. Network Infrastructure commands the largest capital allocation as hospitals replace legacy Wi-Fi backbone with 5G-ready distributed antenna systems. Edge Computing within the technology dimension is attracting disproportionate R&D investment because surgical robotics and AR-guided interventions require localized processing to meet latency thresholds that cloud-only architectures cannot satisfy.
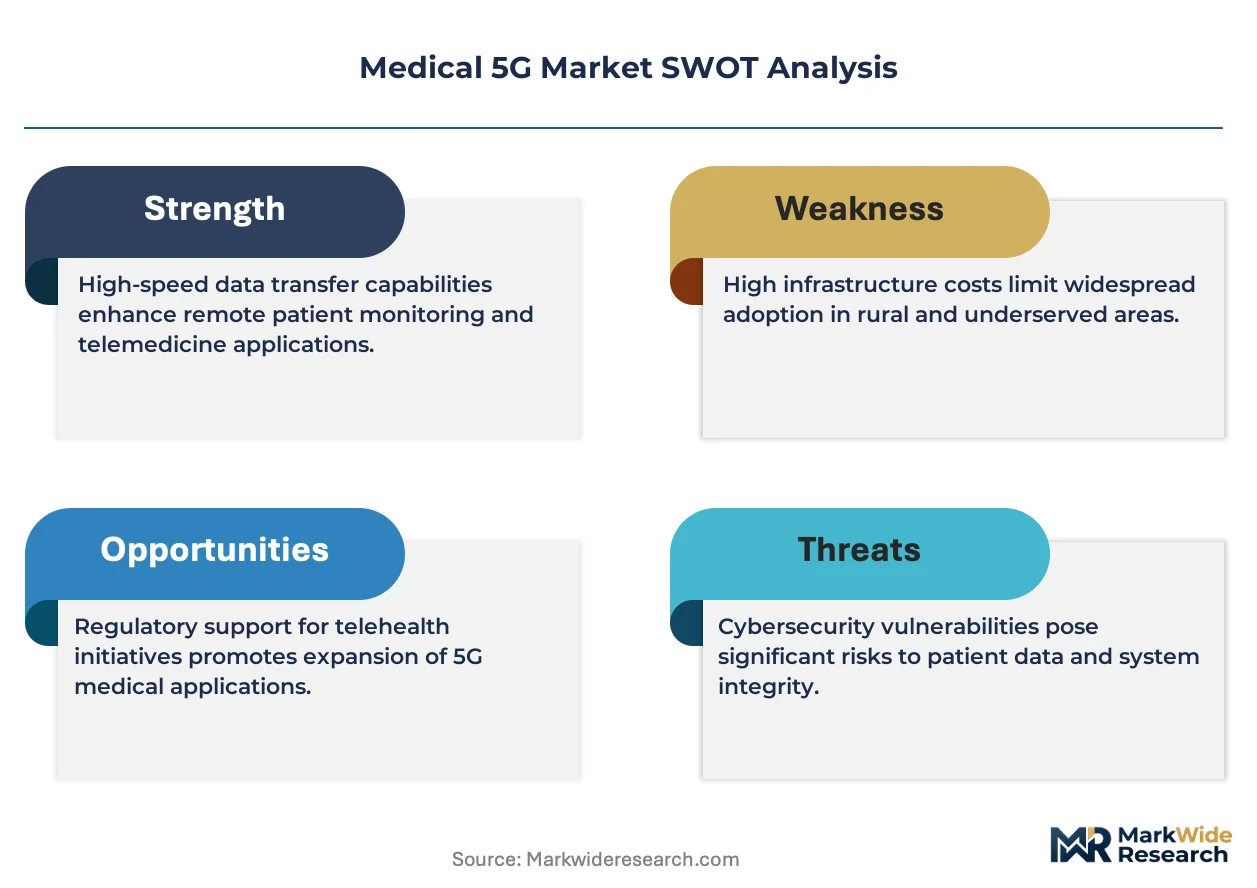
FDA cybersecurity premarket guidance, FCC Part 96 Citizens Broadband Radio Service rules, and HIPAA Security Rule enforcement collectively determine which hardware and software configurations qualify for institutional procurement in the United States. EMA medical device regulation and CE marking under the EU Radio Equipment Directive shape parallel compliance pathways for vendors seeking European hospital contracts. Stakeholders must monitor spectrum auction outcomes and health-specific network slicing standards as these decisions will determine which technology stacks achieve preferential reimbursement status from national health systems.
Market Dynamics
Network slicing is restructuring capital deployment across hospital infrastructure, forcing vendors to guarantee latency thresholds rather than bandwidth quotas. This architectural pivot rewards suppliers capable of isolating mission-critical traffic from consumer-grade data flows.
Growth Catalysts
- FCC Part 96 CBRS Rules:The United States allocated 150 MHz of shared spectrum specifically for private enterprise networks, enabling hospitals to deploy dedicated 5G without acquiring costly exclusive licenses.
- Remote Surgery Workflows:Tertiary care centers in Germany and China are commissioning telesurgical suites that demand sub-10 millisecond connectivity, pulling specialized network infrastructure into operating theaters.
- AI-Augmented Diagnostics:Edge computing nodes processing real-time imaging data require guaranteed quality-of-service lanes that legacy Wi-Fi cannot provision, accelerating 5G-native equipment replacement cycles.
Market Restraints
- Radio Frequency Component Concentration:Gallium nitride semiconductors for high-frequency base stations concentrate among a handful of Asian foundries, exposing equipment vendors to single-source supply risk.
- HIPAA Security Rule Friction:Encryption and access control mandates for protected health information add 18-24 months to device certification timelines, compressing vendor margins on accelerated product roadmaps.
- Millimeter Wave Propagation Limits:28 GHz and 39 GHz signals attenuate rapidly through hospital infrastructure, requiring dense distributed antenna system deployment that multiplies physical layer costs versus sub-6 GHz alternatives.
Strategic Opportunities
- Rural Hospital Connectivity Gaps:Community health systems in the United States lack fiber backhaul, creating demand for fixed wireless access solutions that bypass terrestrial infrastructure entirely.
- EU Medical Device Regulation Convergence:The MDR's software-as-a-device classification creates a unified compliance pathway for 5G-connected monitoring platforms across 27 member states.
- Ambulance-to-OR Continuity:Pre-hospital emergency networks integrating paramedic telemetry with trauma bay preparation represent an untapped application segment requiring mobile edge computing architectures.
Industry Challenges
- Radio Frequency Engineering Talent Scarcity:Hospital IT departments lack expertise in propagation modeling and interference mitigation, forcing reliance on vendor-managed service contracts that erode operational autonomy.
- Legacy PACS Integration Complexity:Picture archiving and communication systems built on DICOM standards require protocol gateways to interface with 5G-native imaging modalities, introducing latency and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical 5G Market |
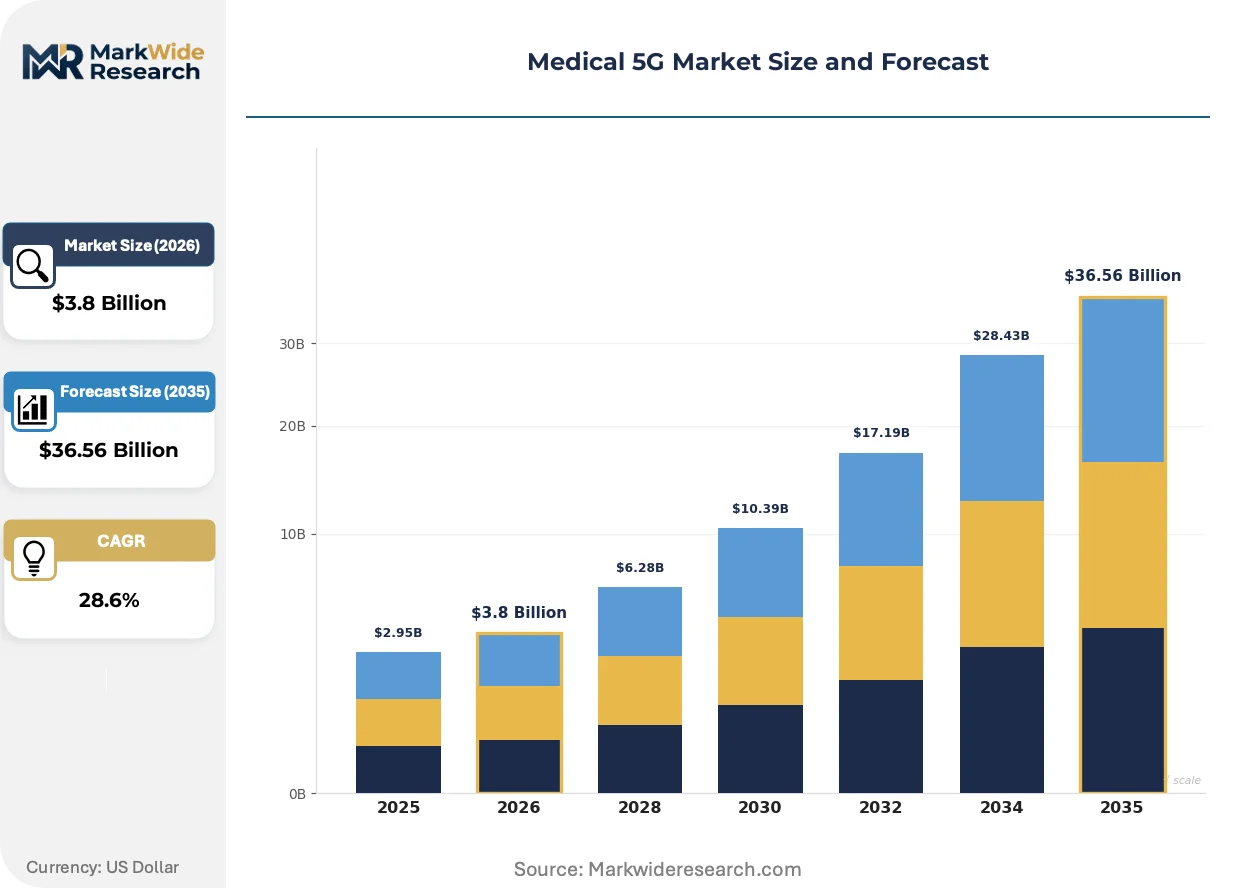
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Infrastructure, Devices, Software Solutions, Communication Systems Application: Telemedicine, Remote Monitoring, Surgery Assistance, Emergency Response End User: Hospitals, Clinics, Home Care Providers, Research Facilities Technology: Network Slicing, Edge Computing, Data Analytics, IoT Integration |
| Companies Covered | AT&T, Verizon, China Mobile Limited, Ericsson, Cisco Systems, Nokia, Huawei Technologies, T-Mobile, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical 5G Market Trends and Innovations
Medical 5G infrastructure is converging with software-defined networking principles, collapsing hardware-defined boundaries between clinical and administrative traffic management. This convergence is compressing vendor differentiation toward orchestration-layer capabilities.
Open RAN architectures are virtualizing baseband processing functions that historically ran on proprietary hardware stacks. Academic medical centers in the United States and university hospitals in Germany are piloting disaggregated radio access networks that separate signal processing from antenna units. This virtualization is enabling multi-vendor interoperability that challenges Ericsson's and Huawei's integrated equipment dominance.
The FDA's 2023 cybersecurity premarket guidance mandates software bill of materials disclosure and vulnerability scanning protocols for networked medical devices. Equipment vendors must now embed over-the-air update capabilities and cryptographic identity modules into 5G-connected endpoints. Surgical robotics manufacturers face the steepest compliance burden, as their devices fall under both device and software regulatory pathways.
Hospital procurement departments are consolidating network infrastructure decisions under single chief digital officers, eliminating siloed IT and biomedical engineering purchasing channels. This concentration favors vendors offering end-to-end managed services over component suppliers. The United States exhibits the most pronounced consolidation, with integrated delivery networks centralizing 5G deployment across dozens of affiliated facilities.
Medical 5G Market Segmentation
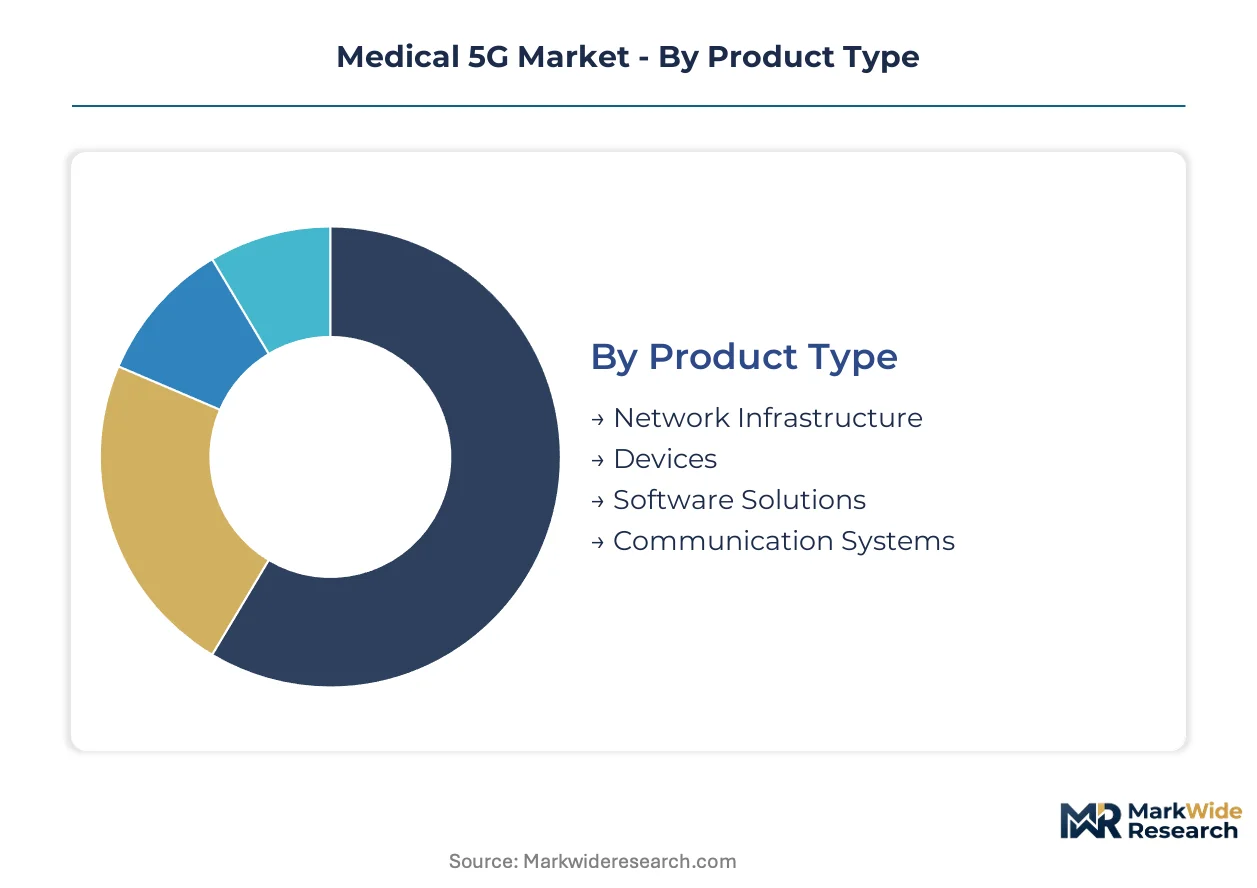
Medical 5G procurement cycles vary dramatically across hardware, software, and service layers. Network infrastructure commits capital for 7-10 year depreciation schedules, while software refresh cycles compress to 18-24 months under FDA cybersecurity mandates. Understanding these divergent timelines helps vendors align R&D pipelines with institutional budgeting rhythms.
Product Type:
Replacement velocity separates this category into long-cycle hardware anchor investments versus rapidly iterating software layers that hospitals refresh under regulatory pressure.
- Network Infrastructure:Distributed antenna systems, small cells, and baseband units constitute the physical layer requiring structural installation. Hospital construction timelines in the United States, China, and Germany concentrate demand for this segment as new facilities incorporate 5G-native designs from groundbreaking.
- Software Solutions:Orchestration platforms, network management systems, and security middleware update continuously to address FDA premarket cybersecurity guidance. Academic medical centers in the United States drive disproportionate procurement here as they pilot multi-vendor Open RAN architectures.
- Devices:Clinical endpoints including 5G-connected imaging modalities and patient monitoring hardware.
- Communication Systems:Interoperability gateways bridging legacy DICOM-based PACS with 5G-native data flows.
Network Infrastructure anchors the volume base while Software Solutions gains share at the steepest rate.
Application:
Latency tolerance thresholds determine which use cases justify premium 5G deployment versus legacy Wi-Fi continuation.
- Surgery Assistance:Telesurgical suites and AR-guided interventions demand sub-10 millisecond connectivity that only network slicing can guarantee. Tertiary care centers in Germany and China commission these capabilities as competitive differentiators for complex procedure referrals.
- Telemedicine:Synchronous video consultation and remote diagnostic workflows represent the highest-volume deployment segment. Hospital systems across the United States scale these implementations under value-based care contracts that penalize readmission.
- Remote Monitoring:Continuous telemetry for chronic disease management through wearable and implantable sensors.
- Emergency Response:Ambulance-to-OR continuity systems integrating pre-hospital data with trauma bay preparation.
Telemedicine commands installed base leadership while Surgery Assistance expands most quickly as latency-dependent procedures proliferate.
End User:
Capital intensity and technical sophistication create distinct procurement patterns across institutional categories.
- Hospitals:Integrated delivery networks in the United States consolidate 5G decisions under chief digital officers, eliminating siloed IT and biomedical engineering purchasing channels. These institutions command the largest capital allocations as they replace legacy Wi-Fi backbone with 5G-ready distributed antenna systems.
- Home Care Providers:Fixed wireless access solutions bypass fiber infrastructure gaps in rural United States community health systems. Medicare reimbursement for remote patient monitoring accelerates equipment deployment in this segment.
- Clinics:Outpatient facilities with constrained IT budgets pursuing shared network services.
- Research Facilities:Academic medical centers piloting Open RAN disaggregation and multi-vendor interoperability.
Hospitals dominate current procurement volume while Home Care Providers show the steepest upward trajectory as reimbursement shifts toward community-based models.
Technology:
Architectural maturity separates proven deployment layers from emerging capabilities still standardizing.
- Network Slicing:Isolation of mission-critical traffic from consumer-grade data flows enables guaranteed quality-of-service lanes. European hospital networks under EMA medical device regulation increasingly require this capability for connected surgical equipment.
- Edge Computing:Localized processing nodes address latency thresholds that cloud-only architectures cannot satisfy for surgical robotics and real-time imaging AI. R&D investment concentrates disproportionately here as vendors compete for trauma bay and operating theater placement.
- Data Analytics:Clinical decision support algorithms processing streaming telemetry.
- IoT Integration:Sensor aggregation platforms for environmental monitoring and asset tracking.
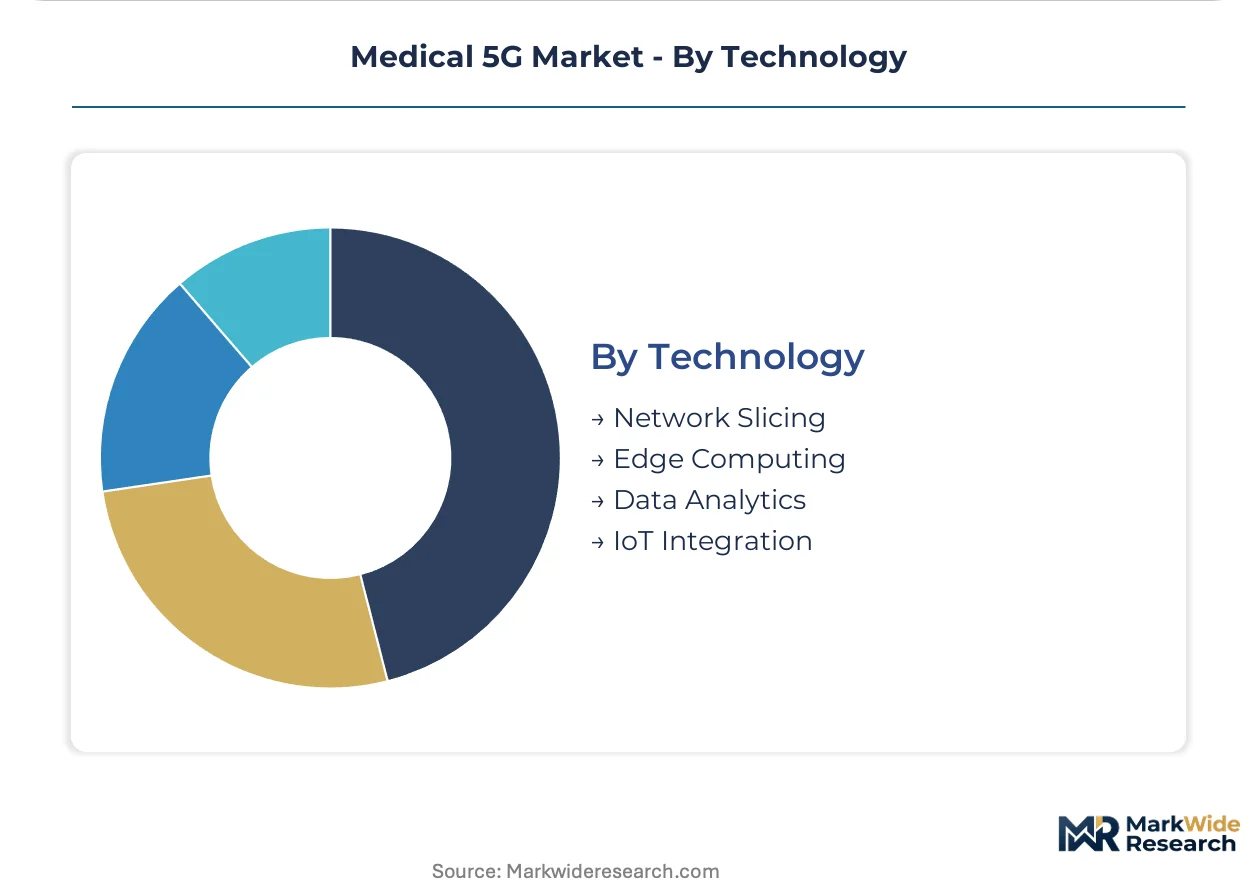
Network Slicing provides the foundational capability base while Edge Computing climbs the fastest as latency-dependent applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows in medical 5G tilt toward net-importing health systems in advanced economies, while component manufacturing concentrates in Asian semiconductor foundries. Spectrum policy divergence is fragmenting deployment standards across major markets.
United States
Hospital construction cycles in Texas and Florida are integrating 5G-native distributed antenna systems from groundbreaking. FCC Part 96 CBRS rules allocated 150 MHz of shared spectrum specifically for private enterprise networks. The Mayo Clinic in Rochester anchors telesurgical pilot programs requiring sub-10 millisecond connectivity guarantees.
Germany
Tertiary care centers in Bavaria and North Rhine-Westphalia commission telesurgical suites as competitive differentiators for complex procedure referrals. EMA medical device regulation and CE marking under the EU Radio Equipment Directive shape compliance pathways for connected surgical equipment. The Charité hospital network in Berlin pilots Open RAN disaggregation for multi-vendor interoperability.
China
MIIT spectrum allocation for healthcare corridors accelerates hospital digitization programs in the Yangtze River Delta and Pearl River Delta. NMPA medical device cybersecurity requirements mandate software bill of materials disclosure for networked clinical endpoints. Shanghai Jiao Tong University Affiliated Hospitals deploy integrated baseband and antenna systems for real-time surgical robotics.
Japan
METI funding for smart hospital infrastructure targets aging population care models in Kanto and Kansai regions. PMDA guidance on 5G-connected monitoring devices creates accelerated approval pathways for remote patient telemetry. The University of Tokyo Hospital cluster advances edge computing nodes for AI-augmented diagnostic imaging.
United Kingdom
NHS England digitization programs concentrate 5G procurement in London and Greater Manchester integrated care systems. MHRA post-Brexit medical device regulations maintain alignment with EU MDR standards for network-connected equipment. The Francis Crick Institute partners with university hospitals on 5G-enabled surgical training networks.
Medical 5G Market Competitive Landscape
On the supply side, the industry is consolidating around integrated equipment vendors capable of delivering end-to-end managed services rather than component suppliers. Tiered competitive positioning separates radio access network specialists, secure edge routing providers, and cloud-native orchestration platforms. Dominant competitive moves include strategic partnerships between telecom operators and surgical robotics manufacturers, plus geographic expansion through hospital system managed service contracts.
Within the integrated infrastructure tier, Ericsson and Huawei Technologies exemplify divergent geographic strongholds shaped by regulatory barriers rather than technical differentiation. Cisco Systems occupies a position bridging enterprise networking heritage with HIPAA-compliant healthcare specialization. Nokia represents European alternative sourcing for health systems seeking vendor diversification beyond dominant Asian and North American suppliers.
| Leading Market Players |
|---|
| AT&T |
| Verizon |
| China Mobile Limited |
| Ericsson |
| Cisco Systems |
| Nokia |
| Huawei Technologies |
| T-Mobile |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride semiconductor foundries in Taiwan and South Korea concentrate upstream supply for 5G baseband units, anchoring margin pools with integrated equipment vendors rather than hospital procurement departments. This concentration forces pricing power toward radio access network specialists capable of guaranteeing sub-10 millisecond latency through captive component sourcing.
Pricing Analysis
Hospital systems and integrated delivery networks anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle network slicing guarantees with managed security services for telesurgical suites, while economy tiers serve rural fixed wireless access deployments. Cost compression in mid-tier edge computing nodes intensifies as Open RAN virtualization commoditizes baseband processing. Research facilities and academic medical centers exhibit lowest price sensitivity, prioritizing multi-vendor interoperability over unit economics.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements between Asian component foundries and European equipment vendors. Manufacturing concentrates in Taiwan, South Korea, and mainland China for gallium nitride semiconductors, baseband processors, and antenna arrays. The supply chain draws from rare earth elements for high-frequency substrates and specialized ceramics for thermal management. Single-source vulnerability in 5-nanometer chip fabrication creates exposure to geopolitical export restrictions. Distribution runs through telecom operator partnerships and direct hospital system managed service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States, where single chief digital officers now control 5G procurement across dozens of affiliated facilities. This fragmentation of vendor access demands strategic repositioning across stakeholder archetypes.
For Market Incumbents: Harden network slicing orchestration capabilities against Open RAN disaggregation threats from academic medical center pilots. Deepen backward integration into gallium nitride semiconductor sourcing to offset foundry concentration risk. Prioritize FDA premarket cybersecurity certification investments to compress 18-24 month approval timelines that erode margins on accelerated product roadmaps. For New Entrants and Emerging Players: Rural United States community health systems lacking fiber backhaul present the most penetrable white-space for fixed wireless access solutions. Ambulance-to-OR continuity systems integrating pre-hospital telemetry with trauma bay preparation offer a second entry vector. A software-defined networking go-to-market angle bypasses capital-intensive hardware installation barriers that favor incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed telecom infrastructure specialists seeking hospital vertical exits. Long-term viability across the analysis window hinges on reimbursement pathway alignment with Medicare remote patient monitoring policies. Watch FCC spectrum auction outcomes and health-specific network slicing standards as inflection indicators for preferential procurement status.| Strategic Initiative | Industry Significance |
|---|---|
| Network Slicing Certification | FDA premarket guidance validates guaranteed latency lanes for telesurgical equipment. |
| Open RAN Disaggregation | Virtualized baseband processing challenges Ericsson and Huawei integrated dominance. |
| Edge Computing Node Deployment | Localized processing meets surgical robotics latency thresholds cloud architectures cannot satisfy. |
| Hospital System Partnership | Mayo Clinic telesurgical pilots establish reference architectures for tertiary care networks. |
| CBRS Spectrum Utilization | FCC Part 96 rules enable private 5G deployment without exclusive license acquisition costs. |
Research Methodology
A standing panel of hospital chief digital officers, biomedical engineers, GPO contracts managers, and FCC regulatory specialists provided ongoing calibration throughout the study. Primary interviews with integrated delivery network procurement committees combined with secondary validation against FDA 510(k) filings, FCC spectrum auction records, hospital construction permit databases, and EMA medical device registration data. Bottom-up equipment shipment tracking and top-down health system IT budget analysis enabled triangulation across independent estimation approaches.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling volume and value outputs through sensitivity testing on spectrum allocation timing and reimbursement policy shifts. Segmentation dimensions included network infrastructure tier, latency-critical application type, end-user capital intensity, and geographic regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and hospital construction pipeline tracking, with edge computing R&D investment flows and Open RAN pilot expansion rates serving as key forecast inputs.
Practitioners should monitor FCC Part 96 rule modifications, EMA MDR enforcement patterns, and NMPA cybersecurity disclosure mandates for early signals of procurement qualification changes. Forecasts reflect documented assumptions on hospital digitization program funding continuity and spectrum auction participation rates. Macroeconomic contraction affecting health system capital expenditure, regulatory restriction on Asian component sourcing, or breakthrough satellite connectivity alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Promotional Sms Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
5G Core Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Norway Telecom Market
Telecommunications
Indonesia Telecom Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Prepaid Communication Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Cloud PBX Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Managed M2M Services Market