
 Canada Hosted PBX Market | 2026-2036
Canada Hosted PBX Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Hosted PBX Market Outlook
Enterprise-grade SLA tiers with sub-50ms latency guarantees and 99.999% uptime commitments is unwinding the Canada Hosted PBX Market away from basic VoIP resale toward managed communications platforms. RingCentral leverages its native Canadian data center footprint to anchor compliance-sensitive deployments in regulated industries. Cisco Systems dominates enterprise routing integration, while Mitel Networks Corporation sustains channel density through carrier and MSP partnerships.
A hosted PBX system delivers private branch exchange functionality via cloud infrastructure, routing voice calls through SIP trunking protocols over IP networks with centralized management dashboards eliminating on-site PBX hardware. Cloud-based deployment leads volume as Canadian organizations shed capital-intensive on-premise legacy systems, while unified communications services capture expanding margin pools by bundling messaging, video, and voice into per-seat subscriptions. AI-driven features within technological integration represent the fastest-growing attach category as vendors embed real-time transcription and predictive routing.
CRTC wholesale access obligations shape competitive dynamics by mandating incumbent network unbundling, while ISED cybersecurity certification requirements for critical infrastructure operators filter vendor eligibility. Health Canada and provincial privacy commissioners enforce HIPAA-aligned protections under PIPEDA and provincial health privacy statutes, elevating demand for Canadian-sovereign data residency. Stakeholders must weigh whether to build in-house AI voice capabilities or partner with specialists as conversational automation becomes a standard procurement criterion.
Market Dynamics
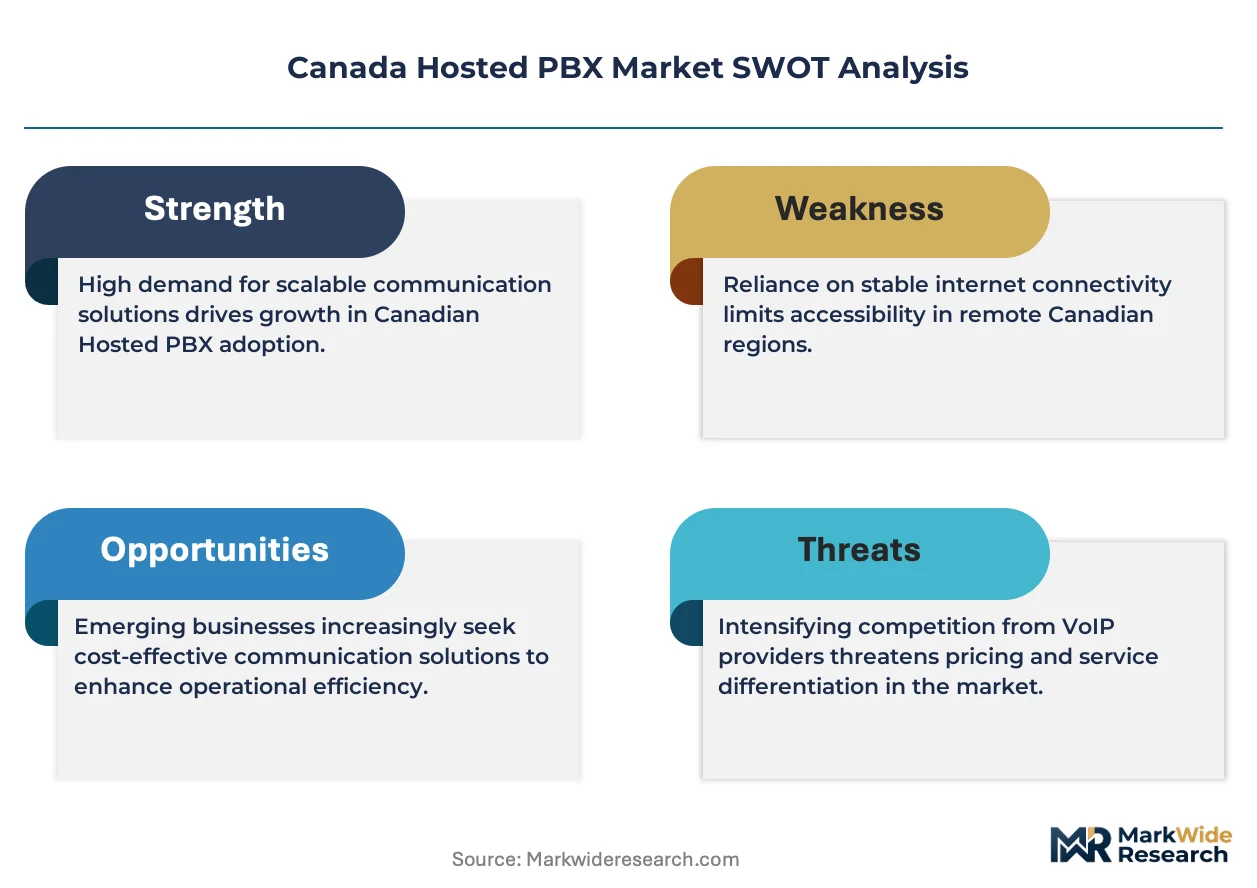
The Canada Hosted PBX Market is being restructured by CRTC wholesale access obligations that compel incumbent carriers to unbundle last-mile infrastructure, accelerating competitive entry by managed service providers and eroding legacy copper-line dominance in enterprise voice.
Growth Catalysts
- CRTC wholesale access rules:Mandated network unbundling lowers barriers for alternative carriers to deploy SIP trunking services across Ontario and Quebec, expanding addressable market for multi-tenant hosted platforms.
- Healthcare digitization:Provincial health privacy commissioners enforce PIPEDA-aligned data residency requirements, driving clinics toward Canadian-sovereign cloud voice infrastructure with centralized compliance dashboards.
- AI voice integration:Real-time transcription and predictive call routing are becoming standard procurement criteria, forcing vendors to embed conversational automation or risk disqualification from RFPs.
Market Restraints
- Legacy system entrenchment:Decades-old copper-line investments in Atlantic Canada and rural Quebec create switching friction, delaying cloud migration timelines for cost-sensitive municipal and education verticals.
- ISED cybersecurity certification:Critical infrastructure operators face vendor eligibility filters that exclude smaller hosted PBX providers lacking resources to achieve federal security accreditation.
- Latency sensitivity:Sub-50ms SLA guarantees require edge computing deployments that concentrate capital requirements in Greater Toronto Area data centers, limiting geographic service parity.
Strategic Opportunities
- Western Canada expansion:Calgary and Vancouver enterprise corridors show underpenetrated hosted PBX adoption relative to Toronto, presenting first-mover advantages for providers with Alberta and British Columbia data center presence.
- Vertical AI specialization:Convergence of voice analytics with electronic health record systems creates white space for healthcare-specific conversational platforms with diagnostic coding integration.
- MSP channel development:Carrier and managed service provider partnerships offer distribution leverage beyond direct enterprise sales, particularly for mid-market manufacturing clusters in Hamilton and Kitchener-Waterloo.
Industry Challenges
- Interoperability complexity:Integration with existing Cisco routing infrastructure and Mitel on-premise systems demands specialized engineering talent scarce outside Toronto and Ottawa technology corridors.
- Compliance timeline compression:Provincial health privacy statute variations across Ontario, British Columbia, and Alberta force vendors to maintain parallel certification tracks, inflating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Hosted PBX Market |
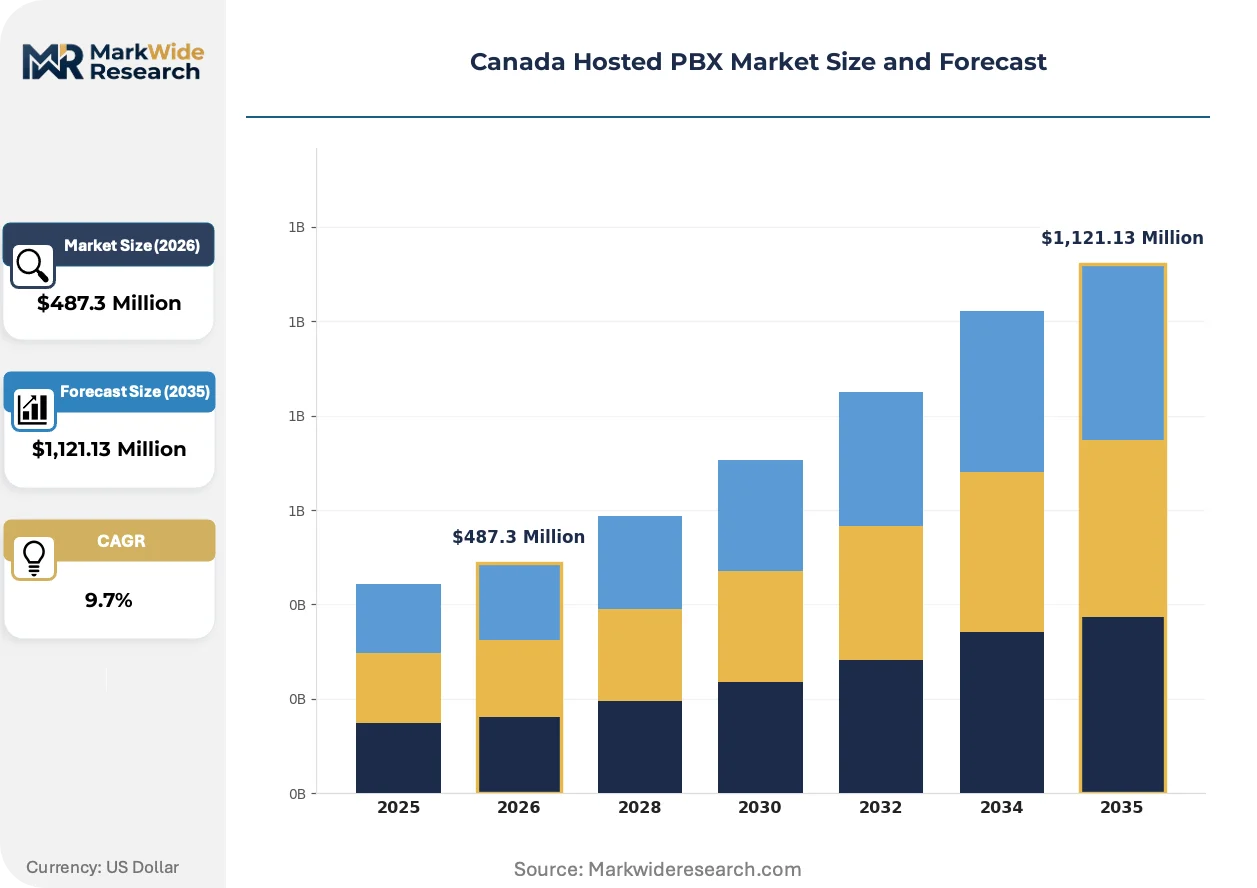
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Virtual User Type: Small Businesses, Medium Enterprises, Large Corporations, Startups Service Type: VoIP Services, Unified Communications, Call Center Solutions, IVR Systems Technological Integration: WebRTC, SIP Trunking, Collaboration Tools, AI-Driven Features |
| Companies Covered | 8x8, AT&T, RingCentral, Zoom, 3CX, Nextiva, Cisco Systems, Verizon Communications, Mitel Networks Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Hosted PBX Market Strategic Shifts
Voice infrastructure is converging with artificial intelligence and edge computing, compressing deployment architectures while elevating performance guarantees. Canadian regulatory frameworks are simultaneously mandating infrastructure access and security certification, filtering vendor participation.
Edge-based session border controllers are miniaturizing voice processing functions, distributing call routing intelligence closer to enterprise premises. Financial services firms in Toronto's Bay Street corridor are adopting these compact appliances to satisfy sub-50ms latency requirements for trading floor communications. This distributed architecture is miniaturizing the traditional centralized PBX model, enabling smaller regional data centers to compete with hyperscale facilities on performance metrics.
ISED cybersecurity certification requirements for critical infrastructure operators are tightening vendor eligibility, particularly for energy and transportation sector deployments. The framework mandates sovereign data residency and encryption standards that disqualify non-compliant hosted providers from federal and provincial procurement processes. Utilities in Ontario and Alberta are responding by pre-qualifying only domestic data center operators with existing certification, reshaping competitive dynamics toward compliance-heavy incumbents.
Subscription bundling is displacing standalone voice procurement as Canadian enterprises consolidate communications spend under unified communications-as-a-service contracts. Mid-market professional services firms in Ottawa and Montreal are leading this consolidation, demanding per-seat pricing that encompasses messaging, video, and voice with single-vendor accountability. This preference shift is most visible in legal and accounting verticals where IT headcount constraints favor outsourced platform management over in-house telephony expertise.
Canada Hosted PBX Market Segmentation
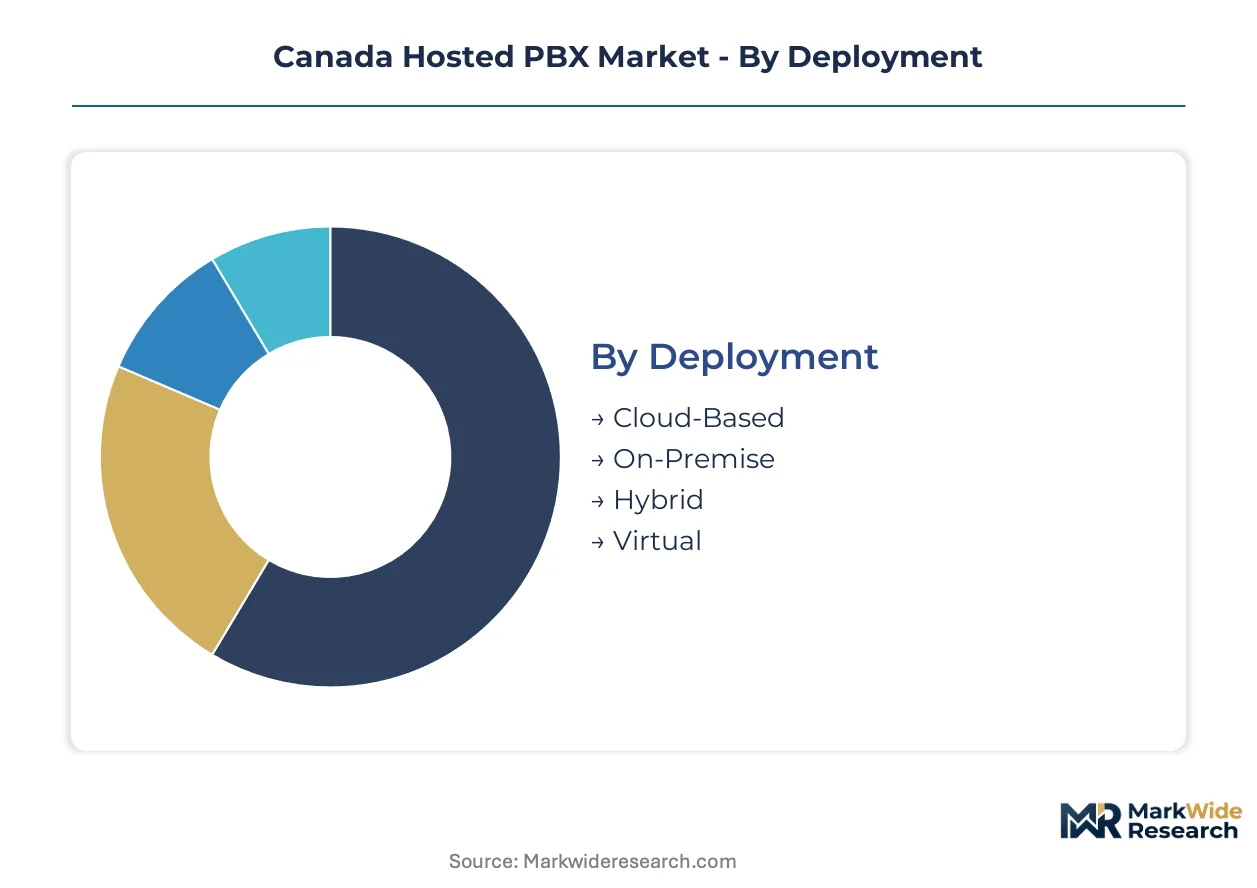
Hosted PBX segmentation reveals divergent margin profiles across deployment architectures and customer tiers. Cloud-based platforms command recurring revenue premiums while AI integration layers capture expanding attach rates in regulated verticals.
Deployment:
Margin pools concentrate in cloud-native architectures that eliminate capital expenditure friction for Canadian enterprises.
- Cloud-Based:Fully managed voice infrastructure delivered via Canadian data centers with centralized dashboards and automatic software updates. Ontario healthcare clinics and financial services firms in Toronto's Bay Street corridor drive concentrated demand for Health Canada-compliant sovereign data residency.
- On-Premise:Legacy hardware installations retaining voice switching equipment at customer premises. Atlantic Canada municipal governments and rural Quebec school boards maintain these systems due to switching friction and sunk copper-line investments.
- Hybrid:Split architectures preserving on-site survivability while leveraging cloud trunking for cost optimization. Manufacturing clusters in Hamilton and Kitchener-Waterloo favor this model for plant-floor reliability requirements.
- Virtual:Software-defined PBX instances running on customer-managed virtual infrastructure. Mid-market professional services firms in Ottawa deploy these for customization control without hardware maintenance burdens.
The dominant share belongs to Cloud-Based deployments, while Hybrid configurations are closing the gap fastest among risk-averse industrial verticals.
User Type:
Customer scale determines service complexity tiers and support infrastructure requirements across Canadian markets.
- Small Businesses:Sub-50 seat deployments prioritizing per-seat pricing simplicity and rapid provisioning. Greater Toronto Area professional services firms and Vancouver retail chains represent concentrated demand for standardized UCaaS bundles.
- Medium Enterprises:50-500 seat organizations requiring customized routing rules and departmental analytics. Calgary energy sector suppliers and Montreal legal partnerships drive demand for compliance-integrated platforms.
- Large Corporations:Multi-location enterprises with 500+ seats demanding geographic redundancy and dedicated account management. National banks and telecommunications operators anchor this tier with complex integration requirements.
- Startups:High-growth technology ventures prioritizing scalable seat licensing and API extensibility. Vancouver and Toronto technology corridors concentrate demand for usage-based pricing models.
Medium Enterprises generate the highest margin per seat, though Large Corporations are expanding contract values fastest through unified communications consolidation.
Service Type:
Revenue composition shifts from standalone voice toward bundled communications platforms with embedded collaboration.
- VoIP Services:Basic SIP trunking and call termination without advanced feature layers. Price-sensitive municipal and education verticals in Atlantic Canada sustain residual demand for this stripped-down offering.
- Unified Communications:Integrated messaging, video conferencing, and voice under single-vendor accountability. Ottawa and Montreal professional services firms lead procurement of these consolidated subscriptions.
- Call Center Solutions:Omnichannel routing, workforce management, and real-time analytics for customer service operations. Toronto financial services and Vancouver e-commerce operations drive specialized deployment demand.
- IVR Systems:Automated voice response with natural language processing for self-service routing. Healthcare clinics across Ontario adopt these for appointment scheduling and prescription refill workflows.
Unified Communications holds the dominant revenue position, while Call Center Solutions are climbing the fastest as AI-powered analytics become standard procurement requirements.
Technological Integration:
Integration depth separates commodity voice providers from platform specialists commanding premium positioning.
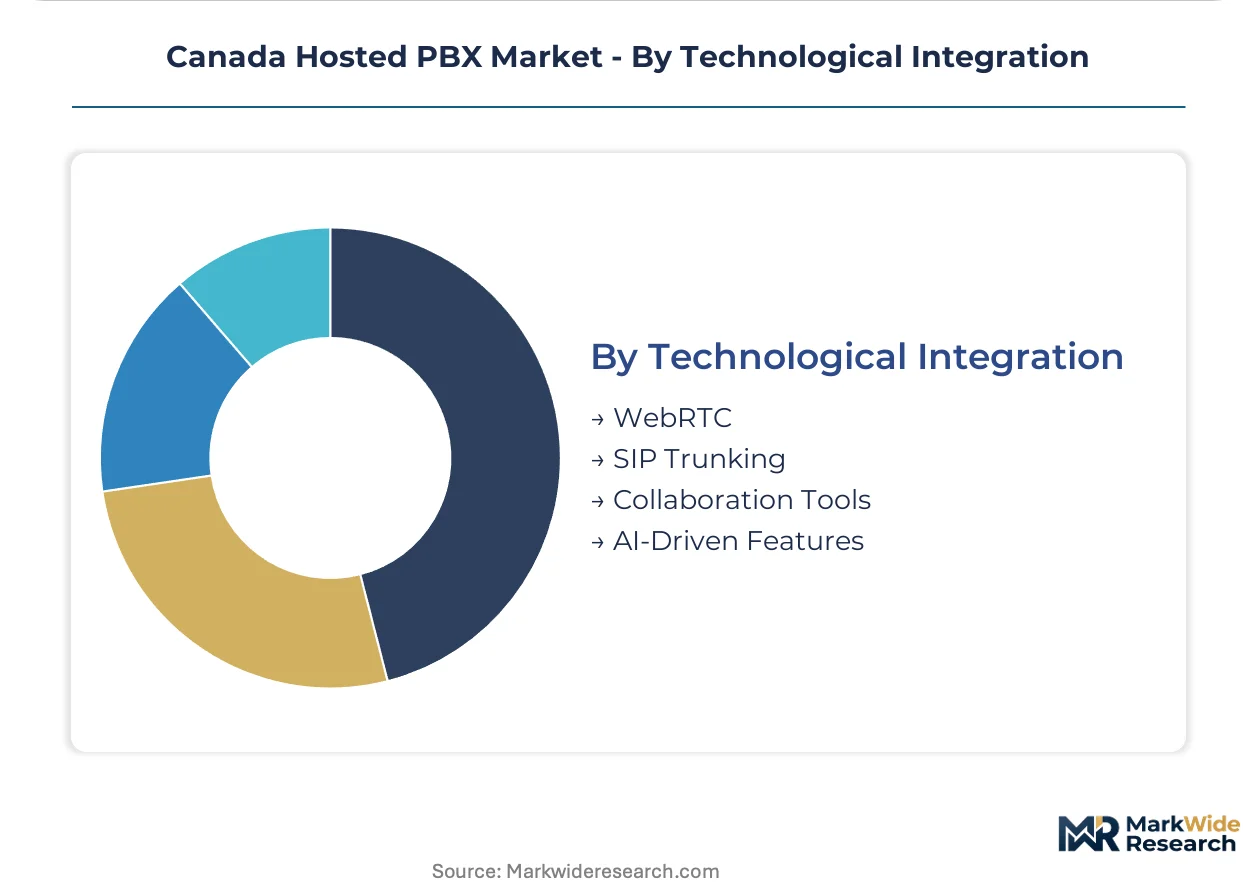
- WebRTC:Browser-based real-time communication eliminating client software installation. Startups and distributed professional services firms prioritize this for rapid user onboarding without IT intervention.
- SIP Trunking:Session Initiation Protocol connectivity bridging legacy PBX hardware to IP networks. Hybrid deployment customers in manufacturing and logistics verticals require this for incremental cloud migration.
- Collaboration Tools:Persistent chat, file sharing, and project workspaces embedded within voice platforms. Knowledge-intensive sectors including legal, accounting, and consulting drive attach rate expansion.
- AI-Driven Features:Real-time transcription, sentiment analysis, and predictive routing algorithms. Healthcare and financial services procurement teams now mandate conversational automation as baseline eligibility criteria.
AI-Driven Features command the steepest expansion trajectory, while SIP Trunking retains volume leadership as the foundational connectivity layer for hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hosted PBX infrastructure concentrates in Ontario data centers serving Greater Toronto Area enterprise density, while western provinces and Atlantic Canada present divergent adoption timelines shaped by regulatory and industrial profiles.
Ontario
Financial services firms on Bay Street and healthcare clinics across the province drive cloud voice migration toward Canadian-sovereign data residency. Health Canada and provincial privacy commissioners enforce PIPEDA-aligned protections that elevate compliance-sensitive procurement. Toronto's technology corridor anchors multi-tenant hosted deployments with sub-50ms latency guarantees.
Quebec
Montreal legal partnerships and professional services firms consolidate communications spend under unified communications-as-a-service contracts. CRTC wholesale access rules mandate incumbent network unbundling that lowers barriers for alternative carriers deploying SIP trunking. Manufacturing clusters in Hamilton and Kitchener-Waterloo favor hybrid architectures for plant-floor reliability.
Alberta
Calgary energy sector suppliers demand compliance-integrated platforms with geographic redundancy for multi-location operations. ISED cybersecurity certification requirements filter vendor eligibility for critical infrastructure operators in the province. Edmonton and Calgary enterprise corridors show underpenetrated hosted PBX adoption relative to Toronto, presenting first-mover advantages.
British Columbia
Vancouver technology startups prioritize scalable seat licensing and API extensibility for usage-based pricing models. Provincial health privacy statute variations force vendors to maintain parallel certification tracks, inflating operational overhead. Vancouver e-commerce operations drive specialized demand for AI-powered call center analytics and omnichannel routing.
Atlantic Canada
Municipal governments and rural school boards maintain legacy copper-line systems due to switching friction and sunk infrastructure investments. Decades-old hardware creates delayed cloud migration timelines for cost-sensitive education and public sector verticals. Halifax represents the primary concentration for any hosted PBX penetration in the region.
Canada Hosted PBX Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Canada Hosted PBX Market. Enterprise-grade SLA tiers with 99.999% uptime commitments separate managed communications platforms from basic VoIP resale operations. Three strategic archetypes dominate: cloud-native platform specialists with Canadian data center footprints, legacy telecom incumbents leveraging wholesale access obligations, and channel-centric vendors sustaining density through carrier and MSP partnerships. Competitive moves concentrate on geographic expansion into underpenetrated western provinces and vertical AI specialization for healthcare-specific conversational platforms.
Among cloud-native platform specialists, RingCentral anchors compliance-sensitive deployments in regulated industries through its native Canadian data center presence. Cisco Systems occupies a position exemplifying enterprise routing integration dominance, while Mitel Networks Corporation sits within the channel-centric tier sustaining distribution leverage through carrier partnerships. These three companies represent the competitive spectrum from infrastructure-heavy incumbents to agile cloud specialists reshaping procurement criteria around AI-driven features and sovereign data residency.
| Leading Market Players |
|---|
| 8x8 |
| AT&T |
| RingCentral |
| Zoom |
| 3CX |
| Nextiva |
| Cisco Systems |
| Verizon Communications |
| Mitel Networks Corporation |
| Others |
Value Chain & Pricing Dynamics
ISED cybersecurity certification requirements for critical infrastructure operators gate both vendor eligibility and price differentiation simultaneously, compressing the supplier base toward compliance-heavy incumbents while stratifying service tiers around sovereign data residency and latency guarantees.
Pricing Analysis
CRTC wholesale access rules dictate the pricing tier structure across Canadian hosted PBX deployments, separating premium managed communications platforms with sub-50ms SLA guarantees from standard multi-tenant offerings and economy-grade VoIP resale. Price differentiation hinges on Health Canada-aligned data residency certification and geographic redundancy architecture, with Ontario financial services firms showing lowest price sensitivity while Atlantic Canada municipal verticals drive cost compression in basic connectivity tiers.
Supply Chain Analysis
Canada and the United States anchor data center infrastructure and session border controller manufacturing for North American hosted PBX deployments. Hardware components draw from Taiwanese semiconductor foundries and Chinese optical networking suppliers, creating tariff exposure on edge computing appliances. Distribution runs through carrier partnerships and managed service provider channels rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian hosted PBX penetration remains early-cycle, with CRTC-mandated network unbundling accelerating competitive entry and cloud voice migration tailwinds justifying capacity positioning ahead of western province expansion.
For Market Incumbents: Secure Canadian data center footprint expansion into Calgary and Vancouver corridors before first-mover windows close. Defend against cloud-native specialists by embedding AI voice capabilities into existing unified communications contracts, and reinforce channel density through exclusive MSP partnerships in Kitchener-Waterloo manufacturing clusters.
For New Entrants and Emerging Players: Anchor in Alberta energy sector suppliers and British Columbia e-commerce operations where incumbent presence remains thin. Target healthcare-specific conversational platforms with diagnostic coding integration as the most penetrable vertical white space, and pursue carrier wholesale agreements as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional MSPs consolidating Atlantic Canada and Quebec channel networks. Five-to-ten year viability favors platforms with existing ISED certification and sovereign data residency infrastructure. Watch provincial health privacy statute harmonization efforts as the signal for accelerated healthcare vertical consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Canadian Data Center Expansion | Establishes Health Canada-compliant sovereign infrastructure for Ontario healthcare procurement. |
| AI Voice Platform Integration | Embeds real-time transcription and predictive routing demanded by Toronto financial services RFPs. |
| MSP Channel Partnership | Unlocks mid-market manufacturing penetration through Hamilton and Kitchener-Waterloo distributor networks. |
| Healthcare Vertical Specialization | Captures Ontario clinic digitization budgets with EHR-integrated conversational automation. |
| Western Geographic Expansion | Secures first-mover positioning in underpenetrated Calgary and Vancouver enterprise corridors. |
Study Parameters
Cross-validation between primary interviews with hosted PBX vendor executives, carrier wholesale managers, and healthcare IT procurement officers and secondary sources including CRTC regulatory filings, ISED certification databases, and provincial health privacy commissioner guidance anchors the qualitative findings. Bottom-up deployment estimates triangulate against top-down service provider revenue segmentation.
Sensitivity analysis across deployment architecture, organization size tier, vertical regulatory intensity, and geographic adoption pattern shapes the analytical framework over the projection horizon. CAGRs derive from installed base migration curves and unified communications bundle attach rate trajectories, with inputs including SIP trunking port growth and AI feature penetration by regulated vertical.
Material uncertainties — CRTC wholesale rate revisions, provincial health privacy statute divergence, and ISED certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about incumbent carrier cloud migration pacing and enterprise AI procurement standardization. Recalibration cycles align with material shifts in CRTC access policy and Health Canada data residency enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
GPON Equipment Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Global SS7 Market
Telecommunications
Ghana Telecom Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
5G Radio Access Network Market
Telecommunications
Russia Telecom Market
Telecommunications
Egypt ICT Market
Telecommunications
Angola Telecom Market
Telecommunications
Transport Stream Switching Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market