
 Global Glass Tempering System Market | 2026-2036
Global Glass Tempering System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Tempering System Market Intelligence
Skilled furnace technician availability is unwinding across mature manufacturing bases, forcing equipment makers to embed more automated diagnostics into tempering lines. Glaston Corporation leverages its vertical integration into thermal process control to sustain premium positioning. Luoyang Landglass Technology anchors Chinese domestic supply with large-format continuous tempering capacity. Keraglass Industries differentiates through specialized architectural glass configurations for European facade specialists.
A glass tempering system thermally processes flat or curved glass through controlled heating above six hundred degrees Celsius followed by rapid air quenching, creating compressive surface stresses that improve mechanical strength and thermal shock resistance. These systems serve safety-critical applications where human impact protection or structural load bearing is mandatory. Continuous tempering lines dominate volume throughput for automotive OEMs and large architectural processors, while batch tempering retains margin pools in specialty equipment and custom furniture manufacturing where job flexibility commands pricing power. Electric heating technology is displacing gas-fired furnaces in regulated European markets, though air quenching remains the universal cooling methodology across all product configurations.
Europe's Ecodesign framework and CE marking requirements under the Construction Products Regulation shape tempering system specifications for facade and automotive applications. China's GB standards and MIIT energy efficiency directives drive domestic equipment upgrade cycles. The US lacks federal tempering-specific mandates, but ICC building codes and state-level energy codes influence architectural glass procurement. Stakeholders must monitor how carbon border adjustments and embodied carbon disclosure rules redirect capital toward low-emission furnace technologies and regional equipment sourcing strategies.
Market Dynamics
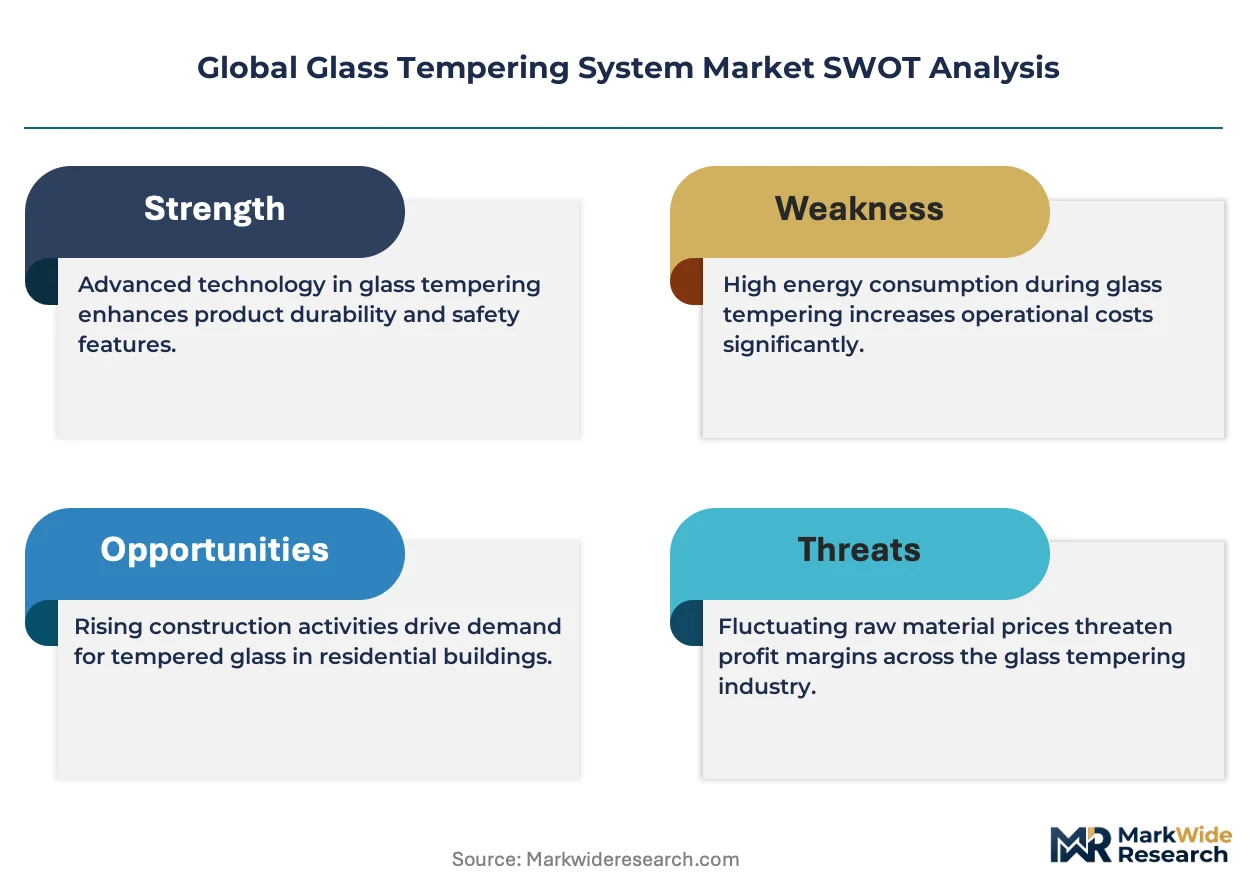
Electric heating technology is displacing gas-fired furnace architectures across regulated European markets, forcing equipment manufacturers to redesign thermal control systems and recalibrate their supply chains around high-amperage electrical infrastructure rather than combustion engineering.
Growth Catalysts
- EU Green Deal implementation:The EU Green Deal and Ecodesign requirements are mandating lower-emission building envelopes, accelerating replacement cycles for tempering equipment serving facade glass processors.
- Automotive OEM safety mandates:Windshield and side-lite specifications under NHTSA and ECE regulations are tightening impact-resistance standards, pulling continuous tempering line demand.
- China's dual carbon goals:MIIT energy efficiency directives are compelling domestic glass processors to upgrade aging furnace fleets, concentrating equipment procurement in Shandong and Guangdong provinces.
Market Restraints
- Specialized refractory material costs:Ceramic roller and silica brick supply concentrates among limited German and Japanese suppliers, exposing furnace makers to input price volatility.
- Technical limitation in ultra-thin glass:Current air quenching uniformity constraints prevent reliable tempering below 2.8mm thickness, excluding smartphone cover glass applications.
- REACH compliance friction:ECHA substance restrictions on certain coating chemistries complicate low-emissivity glass processing configurations for European architectural clients.
Strategic Opportunities
- India's building code enforcement:BIS safety glass mandates in commercial construction are creating first-mover advantage for tempering system vendors establishing local service networks.
- Solar panel cover glass demand:Photovoltaic module manufacturers are specifying thermally strengthened glass for frameless designs, opening a parallel equipment market.
- Digital twin integration:Convergence of furnace control systems with predictive maintenance software enables outcome-based service contracts for fleet operators.
Industry Challenges
- Combustion-to-electric retrofit expertise:Skilled technicians capable of converting gas-fired lines to resistive heating are scarce across mature European manufacturing bases.
- CE marking timeline compression:Construction Products Regulation conformity assessment delays for new furnace architectures extend commissioning schedules by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Tempering System Market |
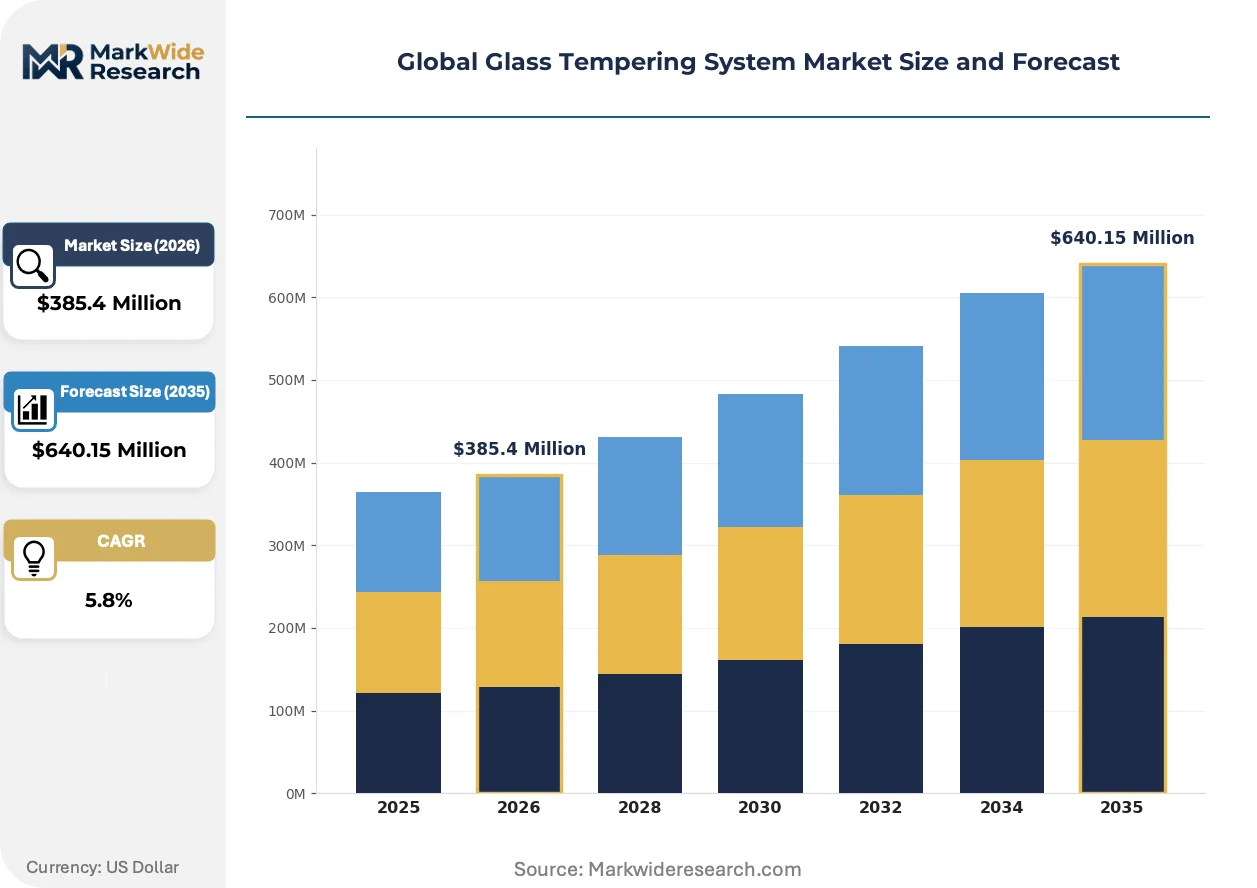
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Tempering, Continuous Tempering, Semi-Automatic Tempering, Automatic Tempering Technology: Quenching, Air Quenching, Electric Heating, Gas Heating, Infrared Heating Application: Architectural, Automotive OEMs, Solar Panel Manufacturing, Furniture Manufacturing, Specialty Equipment End User: Glass Manufacturers, Construction Firms, Vehicle Assemblers, Renewable Energy Companies, Home Furnishing Companies |
| Companies Covered | Glaston Corporation, Luoyang Landglass Technology Co., Ltd., LiSEC Austria GmbH, Luoyang North Glass Technology Co., Ltd., Keraglass Industries Srl, Mappi International Srl, CMS Glass Machinery, Sagertec Machinery, Bystronic Glass AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Tempering System Market Strategic Shifts & Innovations
Thermal process control architectures are converging with industrial IoT platforms, enabling real-time stress profiling that was previously achievable only through offline laboratory testing. This shift is compressing quality assurance cycles and redefining competitive differentiation among furnace manufacturers.
Forced convection heating with precision airflow modulation is displacing conventional radiation-dominant furnace designs. Automotive glass processors in Germany and Japan are adopting these systems to achieve tighter optical distortion specifications for head-up display compatibility. The technology is displacing older tempering lines in premium automotive supply chains, compressing residual value for gas-fired equipment.
The EU F-Gas Regulation and accompanying CE marking requirements under the Construction Products Regulation are prohibiting certain heat transfer fluids in tempering auxiliary systems. Equipment manufacturers are reformulating thermal oil specifications and redesigning heat exchanger architectures to maintain compliance. Architectural glass processors in Italy and the Netherlands are prioritizing certified low-GWP configurations to secure facade project eligibility.
Glass processors are consolidating equipment procurement through multi-site fleet agreements rather than single-line purchases. Large architectural fabricators in China and the United States are negotiating centralized maintenance contracts spanning five to ten tempering lines. This concentration is visible most acutely in the Yangtze River Delta, where three processors account for a substantial share of domestic furnace orders.
Global Glass Tempering System Market Segmentation
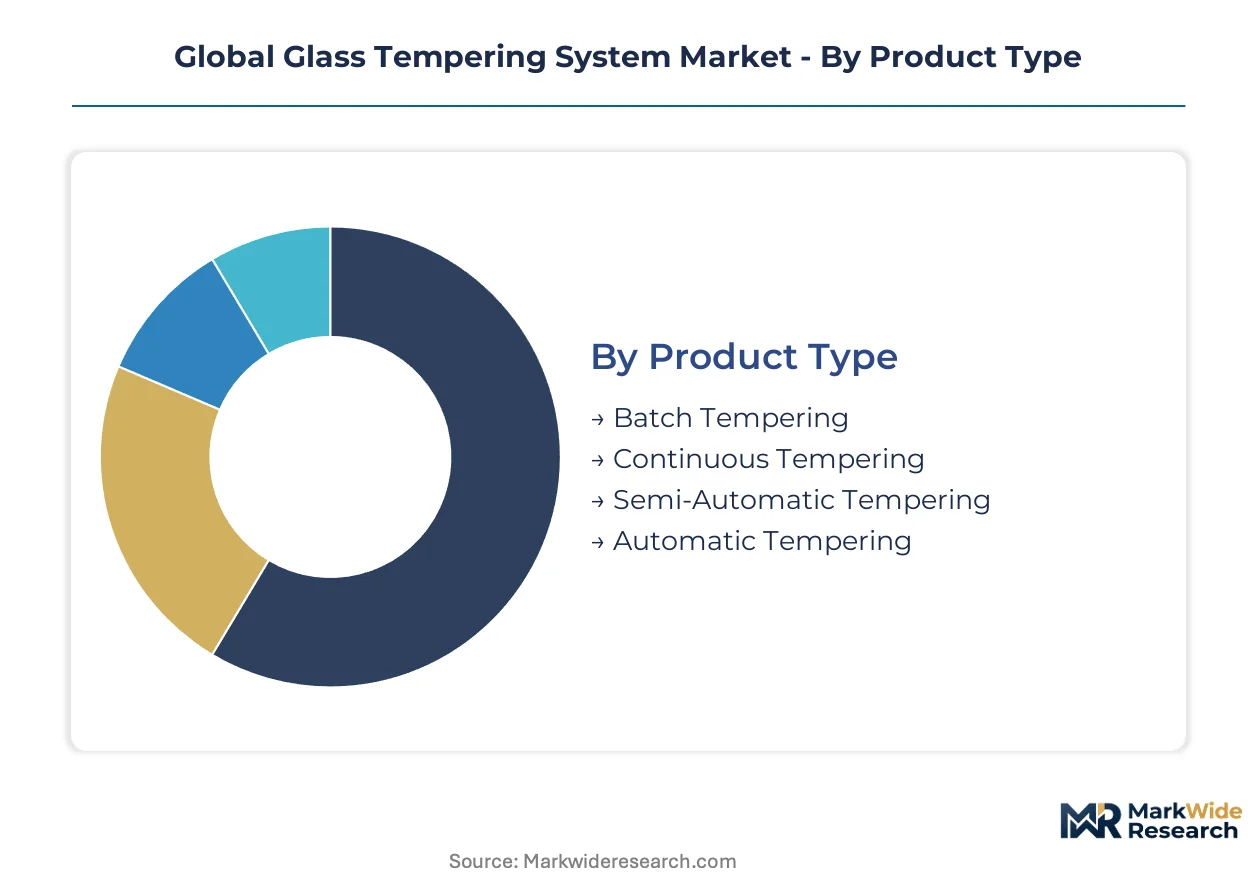
Glass tempering system procurement splits across product architecture, thermal technology, and end-use application. Each dimension carries distinct margin profiles and regulatory exposure that reshape vendor positioning.
Product Type:
Continuous tempering lines face substitution pressure from modular batch systems in low-volume architectural niches where flexibility outweighs throughput economics.
- Batch Tempering:Job-shop configurations process discrete glass loads through heating and quenching cycles. Custom furniture manufacturers in Italy and Germany specify these systems for short-run specialty orders where setup changeover speed determines contract capture.
- Continuous Tempering:Uninterrupted feed systems achieve thermal consistency across high-volume automotive and facade glass production. Vehicle assemblers in Stuttgart and Shanghai anchor demand for these lines under NHTSA and MIIT safety mandates.
- Semi-Automatic Tempering:Operator-assisted loading with automated process control bridges cost gaps for mid-scale processors.
- Automatic Tempering:Fully integrated material handling with predictive diagnostics commands premium positioning.
Continuous tempering retains volume leadership; automatic tempering holds the steepest expansion curve.
Technology:
Electric heating architectures command margin premiums in regulated European markets where gas-fired alternatives face carbon border exposure.
- Quenching:Controlled air impingement creates surface compression through rapid cooling. This foundational method serves all tempering configurations regardless of heating source.
- Air Quenching:High-pressure nozzle arrays deliver uniform cooling rates across glass surfaces. Automotive OEMs in Japan specify these systems for head-up display optical clarity under JIS standards.
- Electric Heating:Resistive element furnaces eliminate combustion emissions. Dutch and Danish architectural processors favor these configurations under EU Green Deal envelope requirements.
- Gas Heating:Convection-radiation hybrid systems retain cost advantage in unregulated developing markets.
- Infrared Heating:Selective wavelength emission reduces thermal cycle times for thin-glass applications.
Air quenching dominates installed base; electric heating is gaining share fastest.
Application:
Architectural glazing faces demand fragmentation as photovoltaic cover glass and automotive safety glass capture capital allocation.
- Architectural:Facade and curtain wall systems require thermally strengthened glass for wind load and thermal stress resistance. High-rise construction in Dubai and Singapore drives specification volume.
- Automotive OEMs:Windshield and side-lite tempering demands tight optical distortion control. German premium vehicle assemblers enforce the most stringent surface flatness specifications.
- Solar Panel Manufacturing:Frameless module designs specify thermally strengthened cover glass for structural integrity.
- Furniture Manufacturing:Tabletop and display case applications prioritize aesthetic edge quality over mechanical performance.
- Specialty Equipment:Appliance and industrial machinery glazing serves niche thermal shock requirements.
Automotive OEMs anchor revenue concentration; solar panel manufacturing climbs the fastest.
End User:
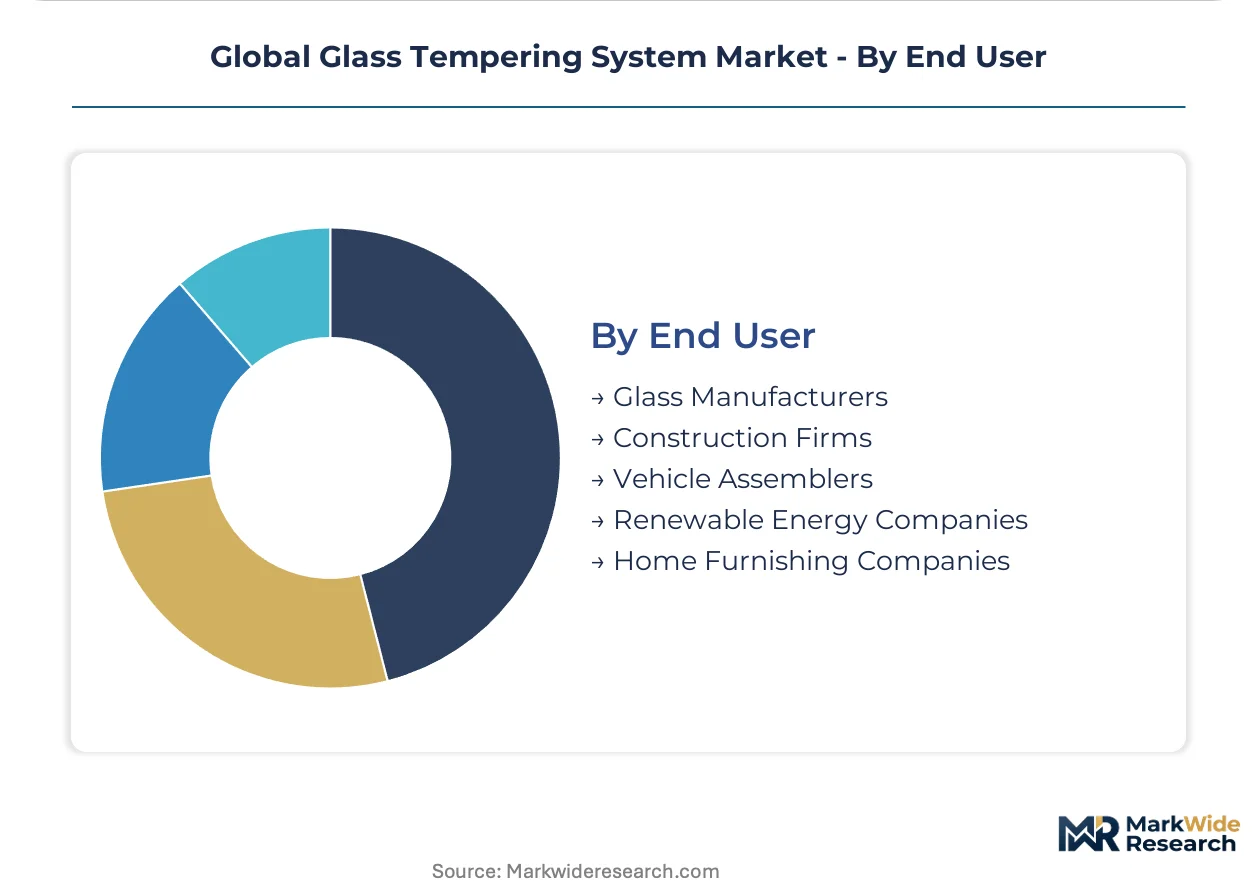
Glass manufacturers consolidate procurement leverage while construction firms fragment demand across project-specific specifications.
- Glass Manufacturers:Integrated processors operate captive tempering capacity for downstream fabrication. Chinese domestic furnace makers in Shandong province scale production to serve these accounts.
- Construction Firms:Project-driven procurement concentrates in commercial high-rise developments. UAE-based contractors specify certified systems for facade eligibility.
- Vehicle Assemblers:Tier-1 glass supply contracts mandate continuous line investment for volume commitments.
- Renewable Energy Companies:Photovoltaic module producers specify tempering equipment for frameless panel architectures.
- Home Furnishing Companies:Furniture brands source tempered glass through processor networks rather than captive equipment.
Glass manufacturers retain procurement scale leadership; renewable energy companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys tempering systems at scale for automotive and solar glass output, while European processors prioritize electric furnace retrofits under carbon pricing pressure. The United States concentrates procurement among large architectural fabricators serving high-rise construction corridors.
China
Shandong and Guangdong provinces house the densest concentration of domestic furnace manufacturing, serving captive demand from integrated glass processors. MIIT energy efficiency directives compel equipment upgrade cycles for processors seeking compliance with dual carbon goals. The Yangtze River Delta cluster anchors volume procurement, where three processors negotiate centralized fleet agreements spanning multiple tempering lines.
Germany
Premium vehicle assemblers in Stuttgart enforce the tightest optical distortion specifications globally, pulling forced convection tempering lines for head-up display compatibility. The EU Green Deal and Ecodesign framework mandate low-emission building envelopes, accelerating electric heating furnace adoption among facade glass specialists. North Rhine-Westphalia and Bavaria concentrate equipment procurement for automotive OEM supply chains.
United States
Commercial high-rise construction in New York, Chicago, and Miami drives architectural glass tempering demand, with ICC building codes influencing safety glass procurement specifications. NHTSA automotive safety standards sustain continuous line investment for windshield and side-lite production. The Southeast manufacturing corridor attracts equipment orders from regional processors serving residential construction recovery.
Italy
Custom furniture manufacturers in Lombardy and Veneto specify batch tempering systems for short-run specialty orders where setup flexibility commands pricing premiums. CE marking requirements under the Construction Products Regulation shape furnace specifications for European architectural export markets. Keraglass Industries anchors domestic supply for facade specialists targeting Mediterranean and Middle Eastern projects.
India
BIS safety glass mandates in commercial construction are creating first-mover advantage for vendors establishing local service networks in Maharashtra and Gujarat. Domestic solar panel manufacturers are specifying thermally strengthened cover glass for frameless module designs, opening parallel equipment demand. The Delhi-Mumbai Industrial Corridor concentrates early procurement as building code enforcement tightens across Tier-1 cities.
Global Glass Tempering System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with differentiation hinging on thermal process control depth and geographic service density. The upper tier commands premium positioning through captive software and predictive diagnostics capabilities, while mid-scale fabricants compete on delivery speed and localized maintenance contracts. Two archetypes dominate: vertically integrated furnace builders controlling ceramic roller supply, and modular system specialists targeting job-shop flexibility. Consolidation pressure is mounting through fleet-based procurement agreements, while technology licensing partnerships accelerate electric heating retrofit penetration.
Among European furnace specialists, Keraglass Industries Srl and LiSEC Austria GmbH exemplify the premium architectural configuration tier, with geographic naming anchoring their respective Italian and Austrian market positions. Luoyang Landglass Technology Co., Ltd. represents the scale-driven Chinese domestic supplier archetype, capturing concentrated procurement from Shandong and Guangdong processors. Glaston Corporation occupies a position as the integrated control systems leader, with corporate naming suggesting Nordic industrial heritage. These three named entities collectively illustrate the competitive spectrum spanning regional specialization, volume manufacturing, and technology integration.
| Leading Market Players |
|---|
| Glaston Corporation |
| Luoyang Landglass Technology Co., Ltd. |
| LiSEC Austria GmbH |
| Luoyang North Glass Technology Co., Ltd. |
| Keraglass Industries Srl |
| Mappi International Srl |
| CMS Glass Machinery |
| Sagertec Machinery |
| Bystronic Glass AG |
| Others |
Cost & Logistics Intelligence
Electric heating element substitution for gas-fired combustion systems simultaneously redistributes supply geography toward high-amperage electrical infrastructure hubs and compresses pricing premiums for legacy furnace architectures. Ceramic roller and silica brick sourcing from German and Japanese suppliers concentrates input cost leverage among a limited supplier base, forcing equipment makers to absorb volatility or pass through to buyers.
Pricing Analysis
Long-term fleet agreements spanning five to ten tempering lines dominate procurement among large architectural fabricators in China and the United States, displacing spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels separates fully automated continuous lines with predictive diagnostics from semi-automatic batch configurations and basic job-shop systems. Cost compression in mid-tier equipment is intensifying because domestic Chinese furnace makers are scaling production for local glass processors. Price sensitivity peaks among custom furniture manufacturers in Italy and Germany where setup flexibility commands premiums, while automotive OEMs in Stuttgart prioritize optical distortion specifications over unit economics.
Supply Chain Analysis
Inventory lead times for specialized refractory materials extend procurement cycles, compelling furnace manufacturers to secure ceramic roller supply through annual offtake commitments rather than just-in-time arrangements. Supply concentrates in China for domestic furnace manufacturing, Germany for premium automotive-grade systems, and Italy for specialized architectural configurations. Production draws from high-purity silica deposits, nickel-chromium heating alloys, and precision-machined quenching nozzle arrays. Single-source vulnerability in ceramic roller supply exposes equipment makers to input price spikes. Distribution runs through direct sales forces for large fleet agreements and regional service partners for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global glass tempering system demand sits at an early-cycle expansion story driven by photovoltaic module manufacturers specifying thermally strengthened cover glass for frameless designs. Building code enforcement in India and solar panel manufacturing globally are creating parallel equipment demand channels beyond traditional architectural and automotive anchors.
For Market Incumbents: Shield premium positioning by embedding predictive maintenance software into furnace control architectures, creating outcome-based service contracts that lock in fleet operators. Deepen backward integration into ceramic roller production to reduce exposure to German and Japanese supplier price volatility. Accelerate electric heating retrofit expertise development before combustion-to-electric conversion capability scarcity widens competitive moats.
For New Entrants and Emerging Players: CE marking fast-track investment opens facade project eligibility among Dutch and Danish architectural processors prioritizing low-emission configurations under EU Green Deal requirements. India's BIS safety glass mandate enforcement in Maharashtra and Gujarat offers first-mover advantage for vendors establishing localized maintenance networks. Solar panel manufacturing equipment represents the most penetrable white-space, with photovoltaic module producers specifying tempering systems outside traditional glass processor channels.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated furnace builders with captive thermal process control software and regional service density. Long-term viability over a multi-year horizon rests on digital twin integration capabilities and electric heating architecture portfolios rather than legacy combustion engineering. Acquisition target archetype: mid-scale specialists with certified low-GWP configurations and established relationships with European facade specialists. The signal to watch is carbon border adjustment implementation timing, which would redirect capital toward low-emission furnace technologies and regional equipment sourcing strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Heating Retrofit Program | Resistive furnace conversions align equipment portfolios with EU Ecodesign and carbon pricing requirements. |
| Ceramic Roller Supply Security | Backward integration into refractory production reduces exposure to German and Japanese supplier concentration. |
| Predictive Maintenance Platform Launch | Digital twin integration enables outcome-based service contracts for multi-line fleet operators. |
| India Local Service Network Buildout | BIS mandate enforcement in Maharashtra and Gujarat creates first-mover equipment procurement advantage. |
| Solar Panel Equipment Certification | Photovoltaic module manufacturer relationships open parallel demand channel beyond architectural and automotive. |
Research Approach
The analysis maps continuous tempering lines, batch tempering systems, electric heating architectures, and gas-fired furnace configurations, each validated through primary interviews with furnace control engineers, procurement leads at glass processors, aftermarket service directors, and regulatory compliance officers. Secondary validation incorporated MIIT energy efficiency directives, EU Ecodesign framework documentation, NHTSA automotive safety standards, BIS building code specifications, and customs trade data for tempering equipment imports. Bottom-up equipment unit economics and top-down construction and automotive glass demand projections were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, thermal technology type, end-use application, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis, construction permit data, and automotive production forecasts. Industry-specific forecast inputs incorporated photovoltaic module manufacturing capacity buildouts and carbon border adjustment policy development timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation, continued MIIT enforcement in China, or stable photovoltaic demand growth would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory compliance timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Asia-Pacific Silica Sand Market
Glass
Global Energy Efficient Glass Market
Glass
Insulated Glass Market
Glass
Laboratory Glassware Market
Glass
Middle East and Africa Glassware Market
Glass
Mirrored Glass Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Silica Market
Glass
Glass Balustrade Lamination Market
Glass
Europe Flat Glass Market
Glass
Global Laminated Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Glass Reactors Market
Glass
Cellular Glass Market
Glass
India Flat Glass Market
Glass
North America Glass Insulators Market