
 Optical Materials Market | 2026-2036
Optical Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Materials Market Outlook
Subscription-based coating performance monitoring is consolidating what optical materials suppliers deliver beyond the physical substrate. SCHOTT AG leverages its fused silica expertise to sustain premium positioning in semiconductor lithography optics. Corning Incorporated anchors North American supply through captive glass melting and precision forming capabilities. HOYA Corporation dominates ophthalmic lens substrates across Asian markets with vertically controlled material science.
Optical materials encompass engineered glasses, crystals, polymers, and ceramics formulated to transmit, reflect, or refract light with controlled dispersion, absorption, and thermal stability, typically specified by refractive index tolerance, Abbe number, and homogeneity grade for integration into lenses, waveguides, and photonic assemblies. These materials serve as the functional backbone of systems ranging from smartphone cameras to laser-based medical equipment and satellite sensors. Lens products command the largest revenue share due to ubiquitous deployment across consumer electronics and automotive vision systems, while coatings represent the fastest-expanding margin pool as anti-reflective, dielectric, and hydrophobic layers become standard specifications rather than add-ons. Filters and prisms occupy specialized niches where military-grade and research-grade certifications create defensible supplier relationships.
The FDA governs optical material biocompatibility for medical device applications, while the FCC regulates optical components in telecommunications infrastructure, and REACH constrains hazardous substance use in European supply chains, collectively elevating compliance costs but also screening out uncertified competitors. ISO 10110 and MIL-PRF-13830B define surface quality and scratch-dig tolerances that differentiate military-grade from commercial-grade supply tiers. Stakeholders must monitor how export control expansions on advanced optical substrates reshape sourcing strategies for precision photonics.
Market Dynamics
Medical device manufacturers are intensifying precision optics procurement as minimally invasive surgical procedures expand, while China's MEE environmental standards and dual carbon goals force rapid adoption of low-carbon glass melting technologies across East Asian manufacturing clusters.
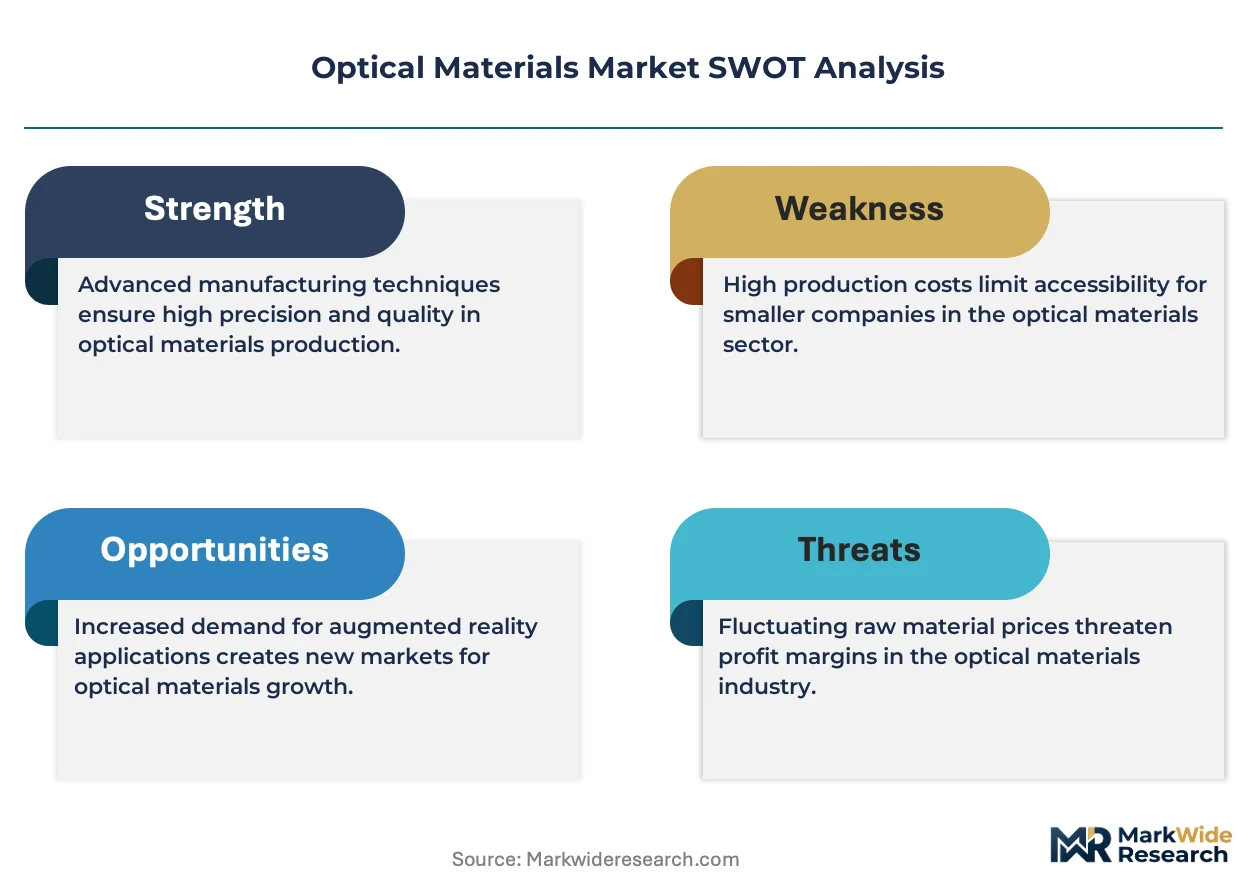
Growth Catalysts
- Minimally invasive surgery expansion:Medical device manufacturers in Germany and the United States are scaling orders for high-homogeneity fused silica substrates to support advanced endoscopic and laser surgical systems.
- REACH compliance screening:European hazardous substance constraints are eliminating uncertified competitors from ophthalmic and photonics supply chains, consolidating qualified supplier pools.
- East Asian fabrication scaling:Manufacturing clusters around Shanghai and Shenzhen are concentrating demand for precision optical components as smartphone camera and automotive lidar production scales.
Market Restraints
- Rare earth oxide volatility:Lanthanum and tantalum price swings destabilize cost structures for high-index glass formulations used in lithography and laser optics.
- Japanese substrate concentration:Premium synthetic quartz and calcium fluoride crystal supply remains captive to a limited set of Japanese producers, creating single-source vulnerability.
- ISO 10110 certification friction:Military-grade surface quality specifications extend qualification timelines for commercial suppliers attempting tier upgrades.
Strategic Opportunities
- India ophthalmic lens underpenetration:Corrective lens adoption rates in tier-2 and tier-3 Indian cities remain below comparable Asian markets, creating white space for mid-index substrate suppliers.
- EU Green Deal melting incentives:Electrified and hydrogen-fired glass furnace investments qualify for accelerated depreciation under revised EU industrial decarbonization frameworks.
- Polymer-glass hybrid convergence:Moldable optical polymers bonded to precision glass cores are enabling cost-reduced smartphone periscope lens assemblies.
Industry Challenges
- Optical fabrication skill scarcity:Master optician and precision polishing technician pipelines in the United States and Germany are failing to replace retiring workforce cohorts.
- Cleanroom capex intensity:Semiconductor-grade fused silica finishing requires ISO Class 5 environments with vibration isolation, demanding eight-figure facility investments.
- FDA biocompatibility timelines:Implantable optical material submissions face 18-24 month review cycles that compress product launch windows against Asian competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Materials Market |
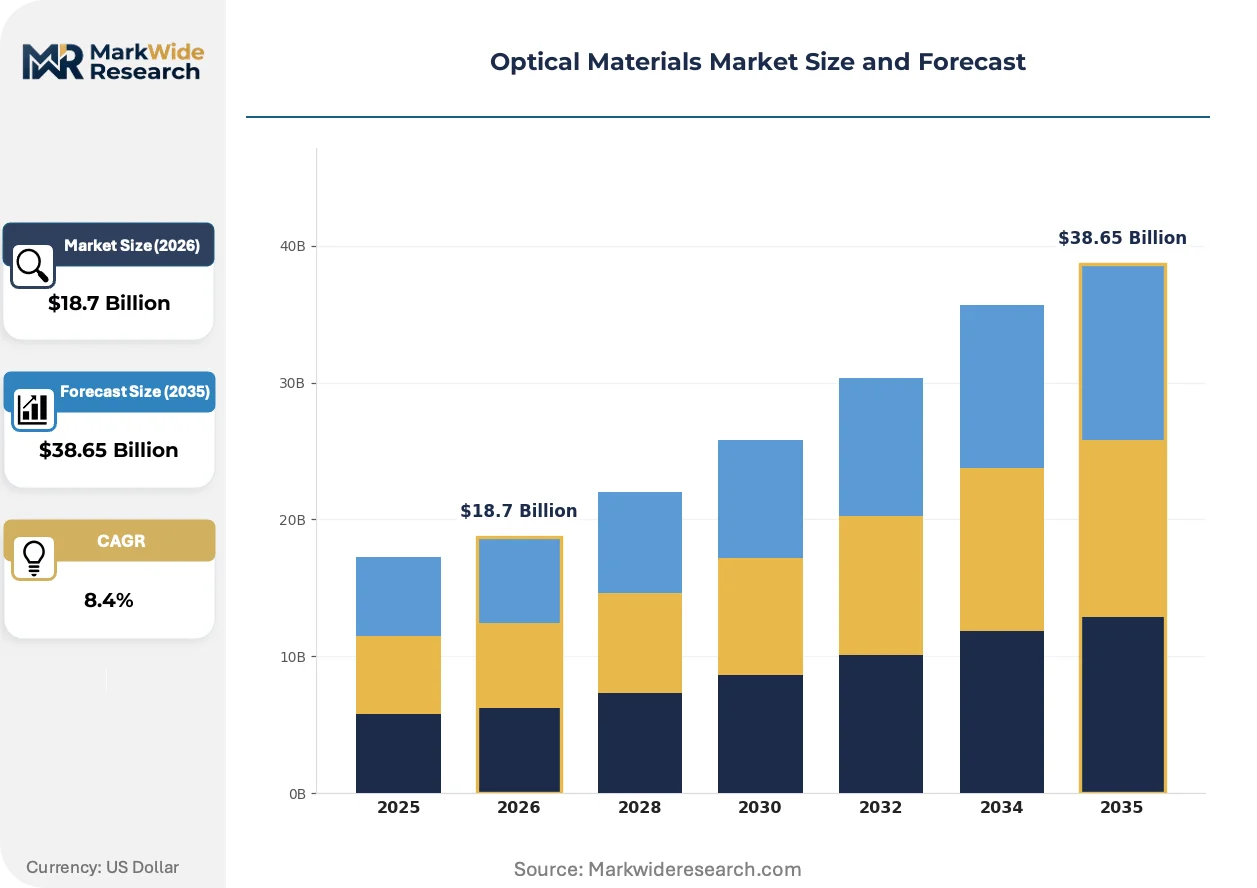
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lens, Filters, Prisms, Coatings Application: Aerospace, Telecommunications, Medical Devices, Consumer Electronics End User: Manufacturers, Researchers, OEMs, Distributors Grade: Optical Grade, Commercial Grade, Research Grade, Military Grade |
| Companies Covered | Corning Incorporated, SCHOTT AG, DuPont de Nemours, Inc., HOYA Corporation, Nippon Sheet Glass Co., Ltd., ZEISS Group, AGC Inc., Coherent, Inc., PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Materials Market Strategic Shifts
Computational design and additive manufacturing are compressing prototyping cycles for complex optical assemblies, while regulatory carbon accounting and subscription service models are restructuring how substrate value is captured and delivered.
Freeform surface metrology is integrating into production lines for automotive head-up displays and augmented reality waveguides. Tier-1 automotive suppliers in Germany and South Korea are adopting in-line interferometric testing at 10x previous throughput rates. This capability is integrating aspheric and conformal optical designs into standard vehicle specification sheets, collapsing the traditional premium tier for complex geometries.
China's MEE emission standards for glass manufacturing are forcing furnace technology upgrades ahead of EU and US regulatory timelines. Stricter particulate and NOx limits are accelerating electric melting and oxy-fuel conversions in Jiangsu and Guangdong provinces. High-volume packaging glass producers serving smartphone cover lens markets are absorbing compliance costs fastest, while specialty optical houses face capital constraints.
Coating performance guarantees are unbundling from substrate sales into subscription monitoring contracts. Medical device and semiconductor OEMs in Japan and the United States now specify real-time degradation tracking for anti-reflective and dielectric stacks. This service-layer attachment is displacing spot-purchase coating business in precision photonics, with contract duration and data access becoming primary negotiation points.
Optical Materials Market Segmentation
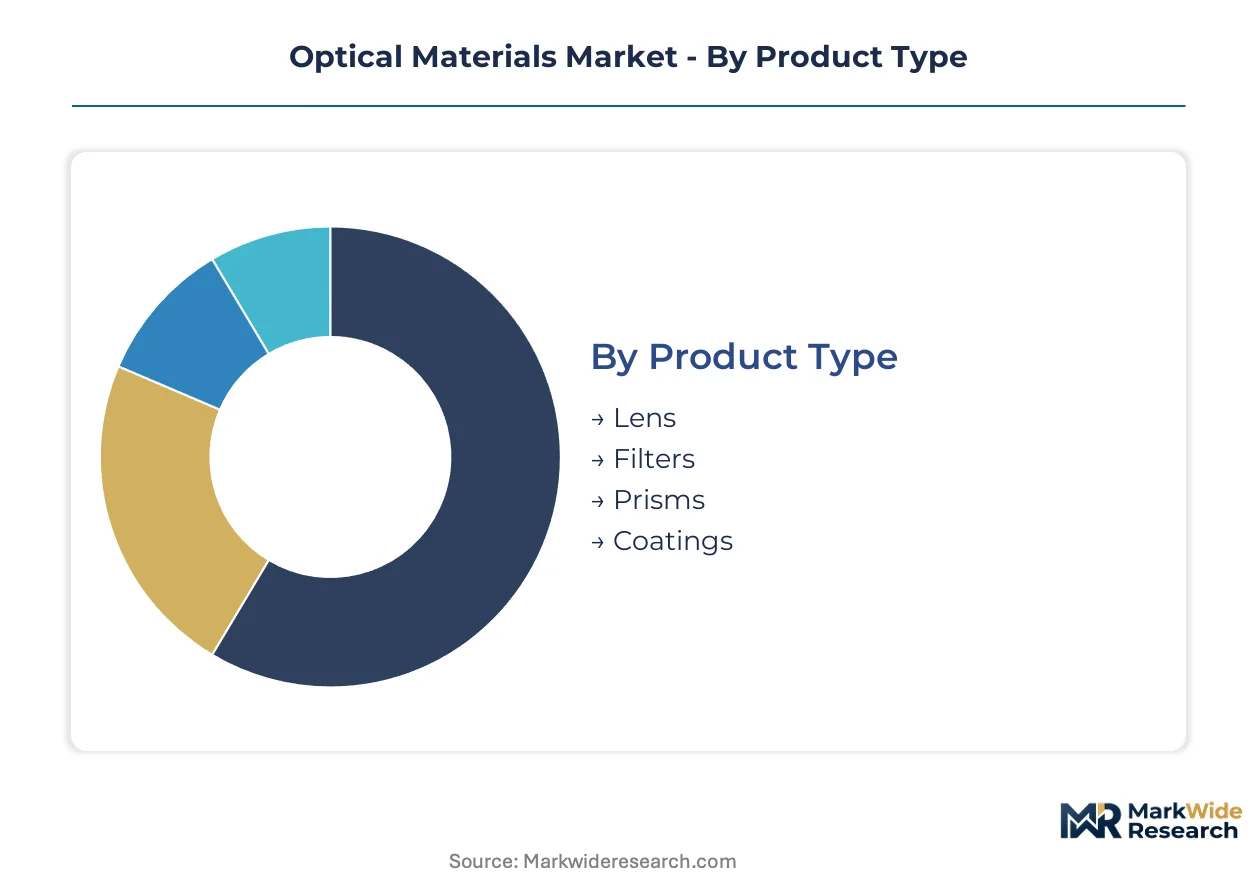
Optical materials suppliers configure production lines around distinct performance tiers and integration depths. Segment boundaries determine qualification timelines, pricing structures, and customer retention mechanics across the value chain.
Product Type:
Standalone optical elements require discrete fabrication and metrology workflows, while surface treatments embed functionality directly onto substrates, altering capital intensity and margin capture.
- Lens:Precision-ground glass or molded polymer elements specified by refractive index tolerance and Abbe number. Demand concentrates in German and South Korean automotive vision systems as head-up displays and lidar modules standardize across vehicle platforms.
- Coatings:Thin-film dielectric, anti-reflective, and hydrophobic layers deposited via ion-beam or sputtering processes. Japanese and United States medical device OEMs now specify real-time degradation monitoring, unbundling coating performance into subscription contracts rather than spot purchases.
- Filters:Wavelength-selective glass or polymer composites for spectral control. Aerospace and defense integrators in France and Israel drive qualification requirements.
- Prisms:Angular beam-deviation elements requiring tight edge-length tolerances and surface flatness. Laboratory and metrology equipment manufacturers represent the core demand pool.
Lens products lead volumes today; coatings are gaining share fastest through service-layer attachment and recurring revenue structures.
Application:
End-use sectors impose divergent certification burdens and volume scales, with consumer-facing applications prioritizing cost compression and mission-critical systems demanding traceability.
- Consumer Electronics:Smartphone camera modules, AR waveguides, and periscope lens assemblies. Shanghai and Shenzhen manufacturing clusters absorb high-volume precision glass substrates as periscope zoom mechanisms proliferate across flagship devices.
- Medical Devices:Endoscopic optics, laser surgical systems, and ophthalmic implants. FDA biocompatibility timelines stretch 18-24 months for implantable materials, compressing launch windows against Asian competitors with faster regulatory pathways.
- Telecommunications:Fiber-optic amplifiers, wavelength-division multiplexers, and data center interconnects. FCC equipment authorization governs optical component deployment in United States infrastructure.
- Aerospace:Satellite sensors, navigation optics, and heads-up displays for military and commercial aviation. MIL-PRF-13830B surface quality specifications create supplier qualification barriers.
Consumer electronics commands the largest volume position; medical devices exhibits the steepest expansion trajectory as minimally invasive procedures multiply.
End User:
Procurement sophistication varies sharply across buyer types, with captive manufacturers integrating backward into material production while distributors intermediate for fragmented research demand.
- OEMs:Original equipment manufacturers with in-house optical design capabilities. German and Japanese automotive and semiconductor equipment builders specify substrate homogeneity grades directly, bypassing distributor markups for critical fused silica and calcium fluoride supply.
- Manufacturers:Component fabricators purchasing raw optical materials for finishing and assembly. East Asian smartphone lens houses concentrate procurement power through volume commitments.
- Researchers:Academic and government laboratory buyers with small-lot, high-specification requirements. Funding cycles and publication timelines drive irregular purchasing patterns.
- Distributors:Inventory-carrying intermediaries serving fragmented demand pools. REACH compliance documentation has become a competitive differentiator in European ophthalmic and photonics channels.
OEMs lead volume absorption today; manufacturers are climbing the fastest as fabrication scales concentrate in East Asian clusters.
Grade:
Quality tier determines allowable defect densities, thermal stability ranges, and pricing multiples, with military and research grades commanding qualification premiums that commercial grades cannot support.
- Optical Grade:Materials meeting ISO 10110 surface quality and homogeneity specifications for precision photonics. Semiconductor lithography and laser optics manufacturers in the Netherlands and Japan specify this tier for wavefront control.
- Military Grade:Substrates certified to MIL-PRF-13830B scratch-dig tolerances and environmental stress standards. United States defense primes and their Tier-1 suppliers maintain approved vendor lists with multi-year qualification cycles.
- Commercial Grade:Cost-optimized materials for imaging and illumination systems with relaxed tolerances. Chinese smartphone cover lens producers absorb compliance costs fastest under MEE emission standards.
- Research Grade:Experimental and prototype quantities with custom specifications. National laboratories and university optics programs drive demand.
Optical grade leads volumes today; military grade is expanding most quickly through export control expansions on advanced substrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where optical materials production concentrates, as China's MEE emission standards force furnace upgrades faster than EU or US timelines, while India's lower compliance costs attract mid-index substrate fabrication.
China
Smartphone periscope lens assemblies and automotive lidar modules drive fused silica demand. The MEE enforces stricter particulate and NOx limits under dual carbon goals. Manufacturing clusters in Shanghai and Shenzhen absorb high-volume precision glass substrates as domestic camera module production scales.
Germany
Automotive head-up displays and semiconductor lithography optics require high-homogeneity substrates. The EU Green Deal offers accelerated depreciation for electrified and hydrogen-fired glass furnace investments. Bavarian precision optics houses qualify military-grade supply chains under MIL-PRF-13830B specifications.
United States
Minimally invasive surgical systems and defense satellite sensors sustain demand for calcium fluoride crystals and synthetic quartz. The FDA governs biocompatibility timelines for implantable optical materials. Greater Boston and Pacific Northwest research corridors host national laboratories driving research-grade procurement.
Japan
Premium synthetic quartz and calcium fluoride crystal supply remains concentrated among limited domestic producers. METI oversees industrial decarbonization frameworks affecting glass melting operations. Kanto and Kansai manufacturing belts serve semiconductor equipment builders with vertically controlled material science.
India
Corrective lens adoption in tier-2 and tier-3 cities trails comparable Asian markets, creating white space for ophthalmic substrate suppliers. BIS standards govern optical material imports and domestic production quality. Maharashtra and Gujarat fabrication clusters scale mid-index lens finishing for export markets.
Optical Materials Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium lithography and medical optics consolidating around qualified suppliers while consumer electronics tolerates fragmented fabrication. The vendor base stratifies into three tiers: multinational glass houses with captive melting, regional precision polishers, and emerging Asian substrate finishers. Two dominant competitive moves are reshaping positioning: strategic partnerships between material scientists and medical device OEMs, and geographic expansion into Indian ophthalmic markets through local finishing joint ventures.
Within the multinational glass house tier, Corning Incorporated and SCHOTT AG exemplify the premium substrate archetype through North American and European melting capabilities. HOYA Corporation occupies a distinct position among Asian specialists with vertically controlled ophthalmic lens material science. These three anchors demonstrate how geographic origin and company structure correlate with served market tiers, with AG-based entities representing European precision and Corporation-suffixed players spanning integrated manufacturing footprints.
| Leading Market Players |
|---|
| Corning Incorporated |
| SCHOTT AG |
| DuPont de Nemours, Inc. |
| HOYA Corporation |
| Nippon Sheet Glass Co., Ltd. |
| ZEISS Group |
| AGC Inc. |
| Coherent, Inc. |
| PPG Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
China's MEE emission standards under dual carbon goals gate qualified supply access and premium-tier pricing power, as furnace upgrade compliance costs stratify producers into certified premium suppliers and cost-pressured commodity players serving divergent buyer archetypes.
Pricing Analysis
Capacity additions in Jiangsu and Guangdong provinces are reshaping price floors for commercial-grade fused silica substrates. Pricing stratifies across premium, standard, and economy tiers based on ISO 10110 certification level and after-sales service bundling. Cost compression in smartphone cover lens supply runs through volume-scale Chinese manufacturers absorbing MEE compliance fastest. OEMs specifying semiconductor-grade homogeneity exhibit lowest price sensitivity; tier-2 Indian ophthalmic distributors face acute margin pressure.
Supply Chain Analysis
Master optician and precision polishing technician shortages in Germany and the United States constrain throughput at specialty optical houses. Supply concentrates in Japan for premium synthetic quartz and calcium fluoride crystals, China for high-volume packaging glass, and Germany for automotive-grade precision substrates. Raw material flows draw from rare earth oxide processors, electric melting furnace operators, and ion-beam deposition equipment makers. Single-source vulnerability around Japanese crystal producers elevates supply risk. Distribution runs through captive OEM supply agreements for critical tiers and distributor networks for research-grade spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical materials margins expand through coating performance guarantees unbundled into subscription contracts, displacing transactional spot purchases with recurring revenue structures that capture value degradation data.
For Market Incumbents: Cement qualification barriers by deepening backward integration into captive fused silica melting and securing MIL-PRF-13830B vendor list positions ahead of export control expansions. Threats from emerging Asian substrate finishers with faster FDA parallel pathways compress launch windows for implantable optics. Prioritize certification investment in ISO 10110 surface quality tiers to defend premium positioning against cost-pressured commodity entrants.
For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities with underpenetrated corrective lens adoption represent the most penetrable buyer archetype for mid-index substrate suppliers. White space concentrates in Maharashtra and Gujarat fabrication clusters scaling export-oriented lens finishing. Go-to-market leverage rests on BIS standards compliance documentation as competitive differentiator against unqualified imports.
For Investors and Strategic Acquirers: Roll-up economics work for regional precision polishers because optical fabrication skill scarcity in the United States and Germany prevents organic workforce expansion. Five-to-ten year viability hinges on platform consolidation of ISO 10110-certified houses with existing OEM vendor list positions. Watch for FDA biocompatibility timeline compression as signal of Asian competitor regulatory pathway acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Melting | Corning and SCHOTT sustain premium positioning through North American and European furnace ownership. |
| Subscription-Based Coating Monitoring | Japanese and United States medical device OEMs now specify real-time degradation tracking contracts. |
| Local Finishing Joint Ventures in India | Maharashtra and Gujarat clusters scale mid-index lens fabrication for underpenetrated tier-2 cities. |
| EU Green Deal Furnace Electrification | German precision optics houses qualify for accelerated depreciation on hydrogen-fired glass melting investments. |
| Freeform Surface Metrology Integration | Tier-1 automotive suppliers in Germany and South Korea adopt in-line interferometric testing at expanded throughput. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from precision optics plant managers, medical device procurement leads at German and United States OEMs, ophthalmic lens distribution channel partners, and semiconductor equipment R&D directors. Secondary validation drew from FDA 510(k) filings, MEE emission standard disclosures, SEC 10-K optical materials segment disclosures, and customs trade data for fused silica and calcium fluoride flows. Bottom-up substrate volume estimates triangulated against top-down end-use demand models.
Segment-weighting approaches distributed value across lens, coating, filter, and prism product types; consumer electronics, medical devices, telecommunications, and aerospace applications; and optical, military, commercial, and research grades. CAGRs derived from regression analysis against smartphone camera module production scales, minimally invasive surgical procedure growth curves, and automotive lidar penetration assumptions. Forecast inputs included MEE compliance cost absorption rates and FDA biocompatibility review cycle durations.
Inputs from primary interviews and regulatory filings were available through the study window; gaps in real-time Japanese synthetic quartz producer capacity utilization introduce uncertainty bands around premium substrate supply assumptions. Forecasts reflect documented assumptions regarding furnace technology conversion timelines and export control expansion scope. Material deviation in MEE enforcement intensity or FDA review cycle compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Europe Glassware Market
Glass
Global Laminated Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Soda Feldspar Market
Glass
Paper Glass Maker Market
Glass
Global Anti-Reflective Glass Market
Glass
Solar PV Glass Market
Glass
Global Glass Tempering System Market
Glass
Spherical Silica Market
Glass
Optical Lens Material Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Glass Block Market
Glass
Float Glass Market
Glass
Laboratory Glassware Market
Glass
Asia-Pacific Silica Sand Market
Glass
Metallic Glass Market