
 Global Vitrification Market | 2026-2036
Global Vitrification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitrification Market Foresight
Modular vitrification kits bundling cryoprotectants with single-use devices is shifting procurement patterns in fertility networks. Vitrolife AB leverages its integrated media-device portfolio to anchor premium positioning in European clinic chains. CooperSurgical, Inc. competes through geographic dominance across North American fertility networks. Shenzhen VitaVitro Biotech extends manufacturing scale to occupy cost-sensitive segments in Asia-Pacific markets.
Vitrification denotes ultra-rapid cooling of biological specimens in high-concentration cryoprotectant solutions to achieve a glass-like amorphous state without ice crystal formation, typically requiring cooling rates exceeding 20,000°C per minute to preserve cellular ultrastructure. The technique serves primarily to maintain viability of oocytes, embryos, stem cells, and tissues across clinical fertility treatment, regenerative medicine, and biobanking applications. Cryoprotectant formulations command the largest value share given recurring consumption and proprietary DMSO-EG blends, while vitrification devices incorporating microfluidic warming channels represent the fastest-expanding segment as clinics prioritize survival-rate consistency. Open pulled straw technology retains volume leadership in developing markets, though cryoloop methods dominate in premium-tier fertility centers where embryologist training depth supports protocol fidelity.
FDA oversight of human cells and tissues under 21 CFR Part 1271 shapes product qualification pathways for US market entry, while EMA-aligned MDR requirements in Europe enforce clinical evidence standards for vitrification device classifications. Japan's PMDA and China's NMPA impose distinct biocompatibility testing protocols that fragment registration strategies for multinational suppliers. Stakeholders must monitor evolving donor-tissue traceability mandates across multiple jurisdictions to align R&D roadmaps with compliance timelines.
Market Dynamics
Modular cryoprotectant-device bundles are compressing procurement cycles across fertility clinic networks, forcing suppliers to integrate media formulation with single-use warming hardware rather than sell components separately.
Growth Catalysts
- EU Tissue and Cells Directive:Harmonized quality benchmarks across member states are standardizing cryopreservation protocols, enabling cross-border sample transfer and expanding addressable clinic networks.
- Oocyte preservation demand:Elective fertility deferral among professional women in urban Spain and Japan is driving capacity expansion at specialized reproductive centers.
- Biobanking infrastructure:National precision medicine initiatives in Germany, South Korea, and the United States are funding automated cryostorage systems with embedded vitrification modules.
Market Restraints
- DMSO supply concentration:Pharmaceutical-grade dimethyl sulfoxide production clusters in Chinese chemical manufacturing zones, exposing cryoprotectant blenders to input volatility and export licensing friction.
- Embryologist training scarcity:Protocol fidelity for cryoloop methods requires 200+ supervised procedures; certification bottlenecks limit premium-tier center expansion in developing markets.
- 21 CFR Part 1271 compliance costs:FDA donor-tissue traceability mandates impose documentation systems that raise operational overhead for smaller US fertility practices.
Strategic Opportunities
- India fertility market:Medical tourism corridors in Mumbai and Delhi remain underpenetrated by automated vitrification systems, presenting first-mover positioning for integrated media-device suppliers.
- Stem cell therapy convergence:CAR-T manufacturing workflows are adopting oocyte-derived vitrification protocols for immune cell preservation, opening regenerative medicine channels beyond reproductive clinics.
- Japan PMDA fast-track:Sakigake designation for novel cryoprotectant formulations accelerates approval timelines for companies submitting biocompatibility data under JIS T 0993 standards.
Industry Challenges
- ISO 20387 biobank certification:Quality management system implementation timelines stretch 18-24 months, delaying revenue recognition for equipment vendors in academic medical center procurement cycles.
- Legacy cryostat integration:Automated warming devices require retrofitting into existing liquid nitrogen infrastructure, complicating installation at established fertility centers with sunk capital in manual straw systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitrification Market |
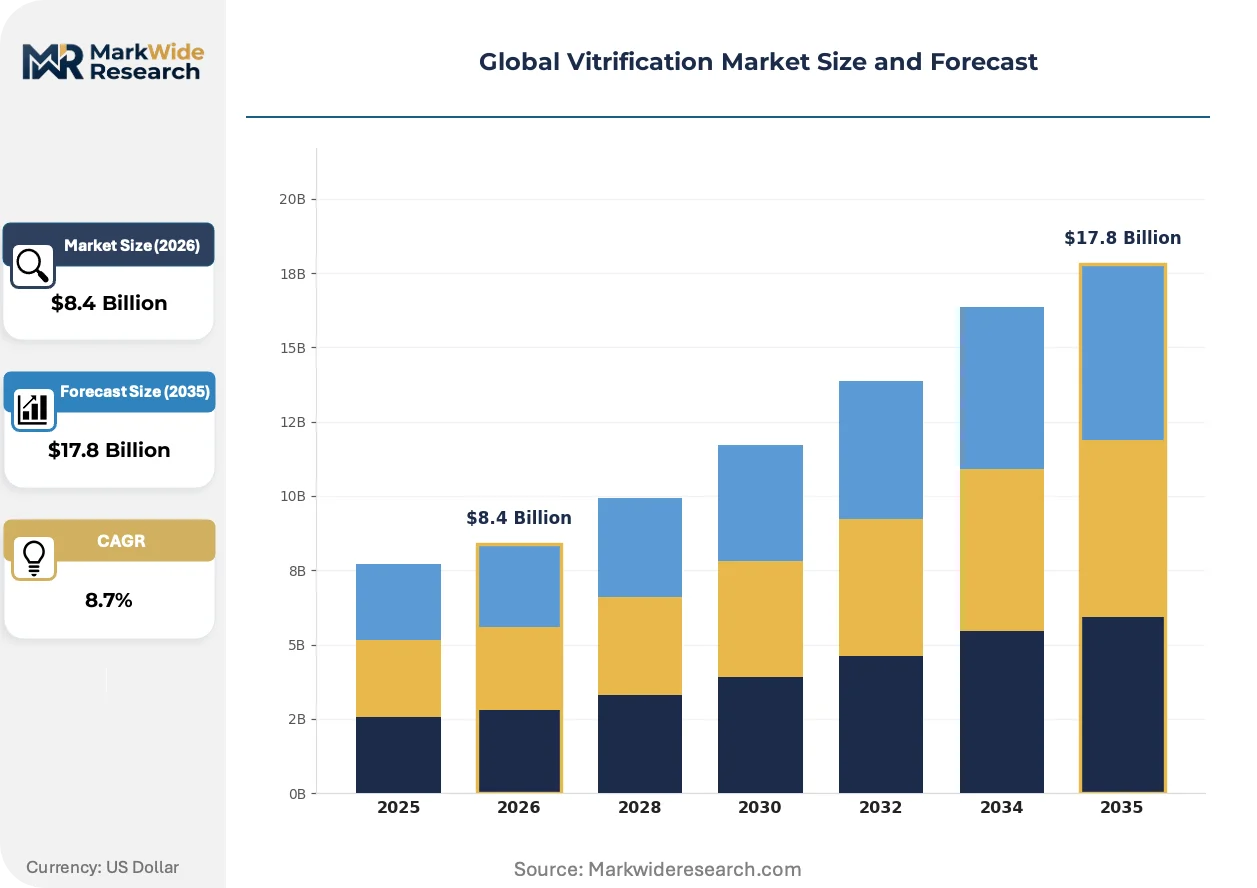
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryoprotectants, Vitrification Devices, Cooling Systems, Storage Containers Application: Embryo Preservation, Oocyte Preservation, Stem Cell Storage, Tissue Preservation End User: Fertility Clinics, Biobanks, Research Laboratories, Stem Cell Banks Technology: Open Pulled Straw, Microdroplet, Cryoloop, Droplet Method |
| Companies Covered | Cryotech Japan Co. Ltd., Genea Biomedx, Vitrolife AB, Merck KGaA, IMV Technologies Group, CooperSurgical, Inc., FUJIFILM Irvine Scientific, Shenzhen VitaVitro Biotech, Kitazato Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitrification Market Shifts & Advancements
Microfluidic warming channels are displacing conventional heat transfer methods as survival-rate consistency becomes the primary procurement criterion for high-volume fertility networks.
Closed vitrification systems with integrated temperature monitoring are consolidating protocol standardization across European clinic chains. These devices embed thermocouple arrays that log cooling-rate compliance automatically, reducing embryologist-dependent variability. Premium-tier centers in Barcelona and Milan are consolidating vendor relationships around suppliers offering media-device-service bundles rather than component procurement.
EMA-aligned MDR requirements are elevating clinical evidence standards for vitrification device classifications in Europe. Manufacturers must now submit biocompatibility studies and post-market surveillance data for Class IIa certifications, extending registration timelines by 12-18 months. German and Swiss suppliers are responding by front-loading clinical validation partnerships with university fertility centers.
Clinic procurement teams are unbundling after-sales service from equipment contracts to negotiate performance-based maintenance agreements. Fertility networks in the United States are replacing fixed annual service fees with per-procedure support pricing, transferring operational risk to vendors. This model is compressing margins for device suppliers while rewarding those with predictive diagnostic capabilities in their hardware platforms.
Global Vitrification Market Segmentation
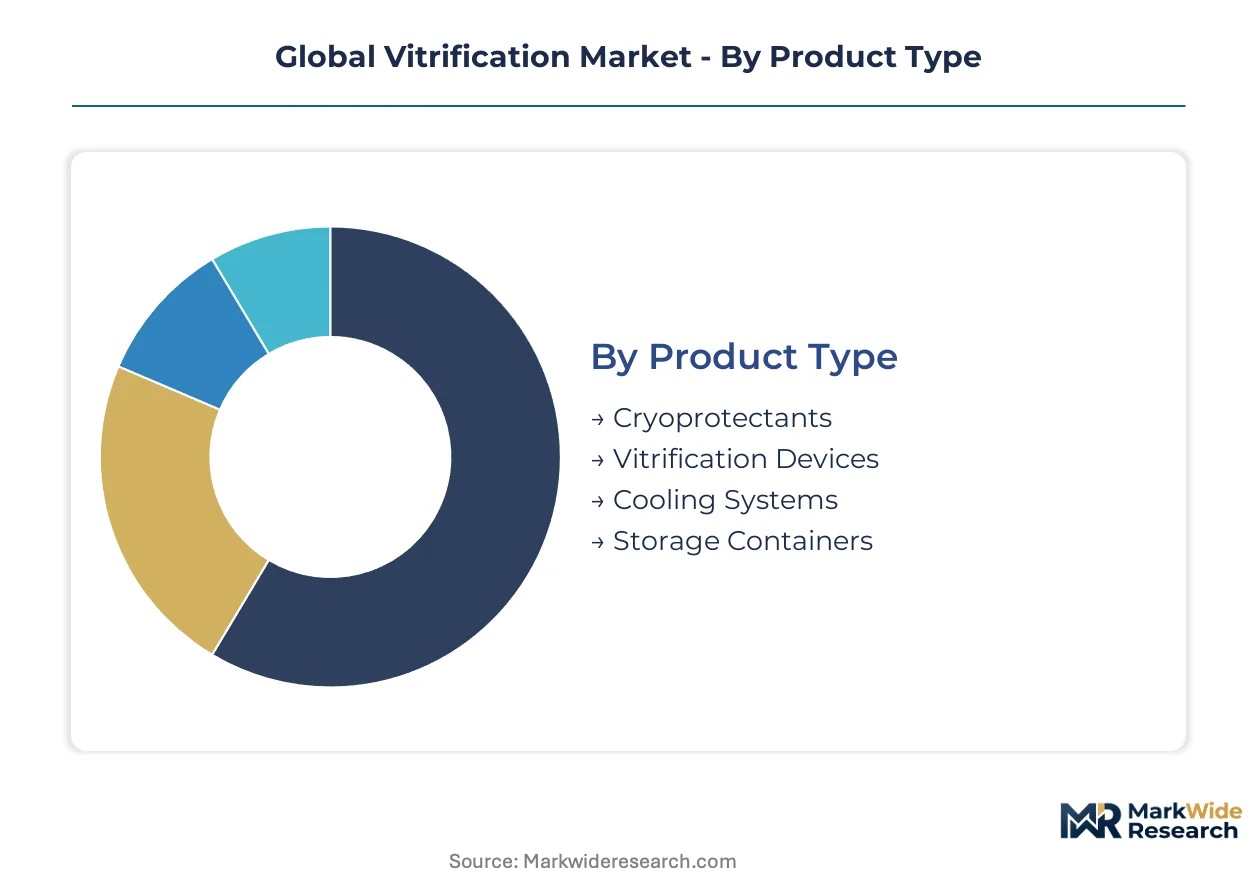
Vitrification market segmentation reveals divergent capital requirements across product categories, with cryoprotectant manufacturing demanding chemical synthesis infrastructure while device segments favor precision engineering investments. Understanding these investment profiles illuminates why supplier consolidation patterns vary dramatically by segment.
Product Type:
Cryoprotectant blending operations require the heaviest upfront capital, with pharmaceutical-grade DMSO purification and EG synthesis facilities dominating facility cost structures.
- Cryoprotectants:Proprietary DMSO-EG formulations with serum protein additives command recurring revenue streams through consumable replenishment cycles. Demand concentrates at fertility networks in Spain and Japan where oocyte preservation protocols mandate high-purity blends with documented lot traceability.
- Vitrification Devices:Microfluidic warming channels etched into polymer substrates deliver cooling-rate precision exceeding 20,000°C per minute. German and Swiss manufacturers are embedding thermocouple arrays for automated compliance logging, attracting premium-tier clinic procurement in Milan and Barcelona.
- Cooling Systems:Programmable rate freezers with liquid nitrogen injection modules.
- Storage Containers:Vacuum-insulated dewars with electronic monitoring for cryogenic stability.
Most installed capacity flows through cryoprotectant supply contracts. Expansion is steepest in microfluidic device segments.
Application:
Application segmentation tracks biological specimen viability requirements, with each category imposing distinct protocol fidelity demands on end-user infrastructure.
- Embryo Preservation:Multi-cellular blastocyst vitrification demands precise cryoprotectant equilibration timing to prevent osmotic shock. Fertility clinics in urban Japan are automating workflow steps previously requiring manual embryologist intervention.
- Oocyte Preservation:Single-cell oocyte vitrification presents the highest survival-rate sensitivity due to spindle apparatus fragility. Elective fertility deferral among professional women in Madrid and Tokyo is expanding dedicated oocyte banking capacity at specialized reproductive centers.
- Stem Cell Storage:Pluripotent and multipotent cell lines for regenerative medicine workflows.
- Tissue Preservation:Organoid and thin-tissue slice protocols for transplant and research applications.
Embryo preservation retains the largest procedure volume base. Oocyte preservation is climbing the fastest as social indications broaden.
End User:
End-user segmentation reflects divergent procurement sophistication, with biobanks demanding integrated automation while research laboratories prioritize protocol flexibility.
- Fertility Clinics:High-volume reproductive medicine centers with embryology laboratory certification requirements. Networks across the United States are consolidating vendor relationships around media-device-service bundles rather than component sourcing.
- Biobanks:ISO 20387-certified repositories with automated cryostorage and sample tracking infrastructure. National precision medicine initiatives in Germany and South Korea are funding expansion of embedded vitrification modules.
- Research Laboratories:Academic and commercial R&D facilities with protocol customization needs.
- Stem Cell Banks:Specialized facilities for CAR-T manufacturing and immune cell preservation workflows.
Fertility clinics deploy the most vitrification devices by unit count. Biobanks are gaining share fastest through national infrastructure investments.
Technology:
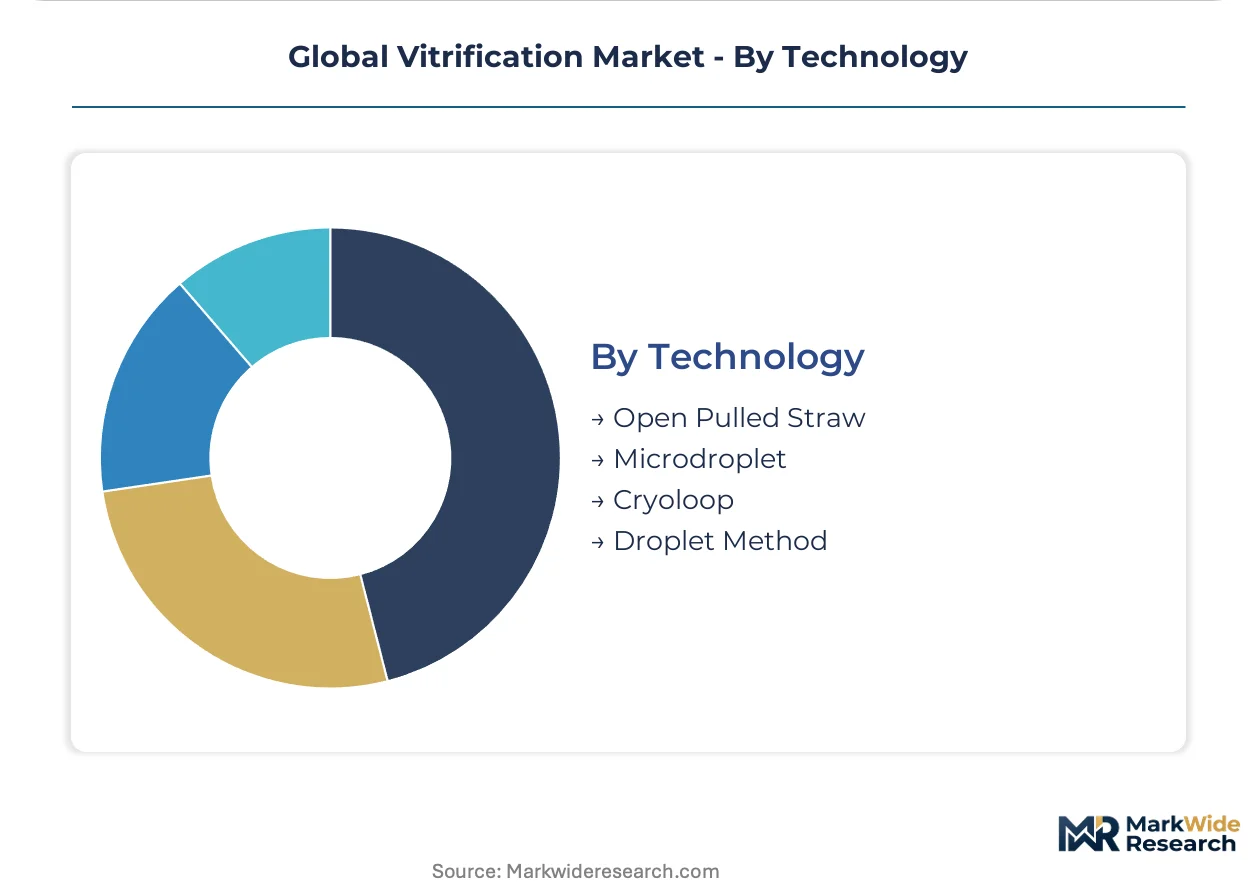
Technology segmentation captures the trade-off between protocol simplicity and survival-rate optimization, with training investment requirements stratifying adoption patterns.
- Cryoloop:Thin nylon or polypropylene loops supporting ultra-rapid heat transfer through minimal sample volume. Premium-tier centers in Barcelona and Milan require 200-plus supervised procedures for embryologist certification, limiting diffusion to developing markets.
- Open Pulled Straw:Hand-drawn glass capillaries with variable internal diameter for cost-sensitive deployment. Volume leadership persists in India and Southeast Asia where manual straw systems dominate clinic infrastructure.
- Microdroplet:Nanoliter-scale sample encapsulation on cryogenic carriers.
- Droplet Method:Direct plunging of suspended droplets into liquid nitrogen.
Open pulled straw technology retains the broadest installed base. Cryoloop methods are expanding most quickly among premium-tier fertility networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vitrification technology first achieved clinical scale in Japanese fertility centers during the 1990s, establishing cooling-rate protocols that later diffused to European and North American reproductive medicine networks. This historical foundation continues to shape regional specialization patterns today.
Japan
Elective oocyte preservation among professional women in Tokyo and Osaka drives capacity expansion at specialized reproductive centers. PMDA fast-track designation under Sakigake accelerates approval timelines for novel cryoprotectant formulations submitting biocompatibility data under JIS T 0993 standards. Yokohama-based manufacturing clusters supply pharmaceutical-grade DMSO-EG blends to domestic clinic networks.
Germany
National precision medicine initiatives fund automated cryostorage systems with embedded vitrification modules across academic medical centers. EMA-aligned MDR requirements enforce clinical evidence standards for Class IIa device certifications, extending registration timelines by 12-18 months. Munich and Berlin fertility networks are consolidating vendor relationships around media-device-service bundles.
United States
FDA oversight under 21 CFR Part 1271 shapes donor-tissue traceability mandates that raise operational overhead for smaller fertility practices. Biobanking infrastructure investments in Boston and San Diego prioritize ISO 20387 certification for automated sample tracking. Fertility networks are replacing fixed annual service fees with per-procedure support pricing.
Spain
EU Tissue and Cells Directive harmonization enables cross-border sample transfer and expands addressable clinic networks for cryopreservation protocols. Barcelona and Madrid centers dominate oocyte banking capacity for medical tourism corridors serving Southern Europe. Catalan fertility chains are adopting closed vitrification systems with integrated temperature monitoring.
South Korea
Government-funded biobanking infrastructure embeds vitrification modules within national precision medicine initiatives. MFDS biocompatibility testing protocols align with international standards while maintaining distinct documentation requirements. Seoul metropolitan area clusters concentrate both fertility clinic expansion and stem cell banking capacity.
Global Vitrification Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cryoprotectant purity grades and device automation levels, with proprietary DMSO-EG formulations commanding recurring revenue against single-use hardware. The supplier base stratifies into three tiers: integrated media-device portfolios, standalone consumable blenders, and regional device fabricators. Two dominant competitive moves are reshaping positioning: backward integration into pharmaceutical-grade chemical synthesis and predictive diagnostic capabilities embedded in warming hardware platforms.
Within the integrated portfolio tier, Vitrolife AB and CooperSurgical, Inc. exemplify divergent geographic anchoring strategies. Vitrolife AB occupies premium positioning through European clinic chain relationships, while CooperSurgical, Inc. leverages North American fertility network density. Shenzhen VitaVitro Biotech represents the scale-driven archetype, extending manufacturing output to serve cost-sensitive Asia-Pacific procurement patterns. These three anchors illustrate how supplier consolidation varies by segment capital requirements.
| Leading Market Players |
|---|
| Cryotech Japan Co. Ltd. |
| Genea Biomedx |
| Vitrolife AB |
| Merck KGaA |
| IMV Technologies Group |
| CooperSurgical, Inc. |
| FUJIFILM Irvine Scientific |
| Shenzhen VitaVitro Biotech |
| Kitazato Corporation |
| Others |
Supply & Pricing Matrix
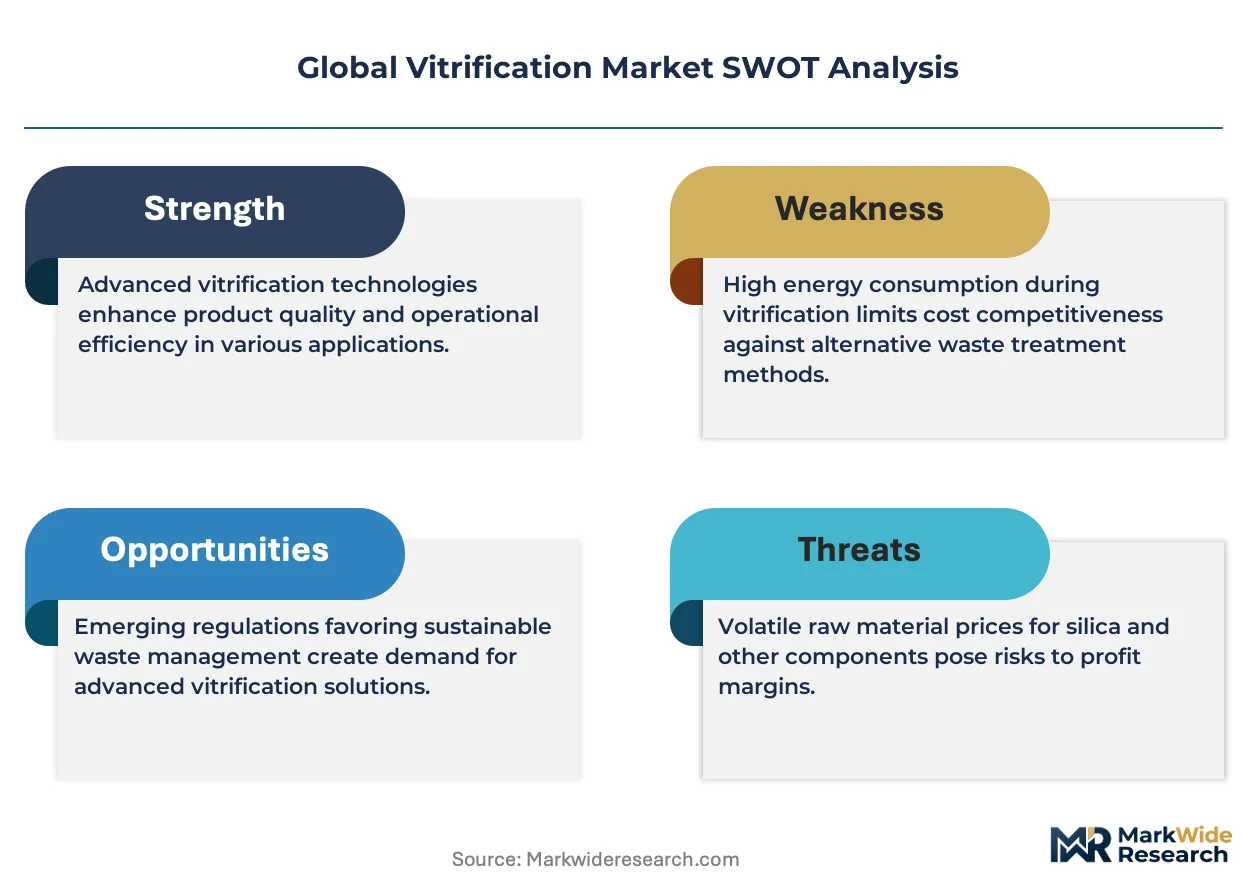
Fertility clinic network procurement teams in Germany, Japan, and the United States command substantial pricing leverage through consolidated media-device-service bundling, compressing margins for component suppliers while rewarding integrated portfolio vendors with recurring cryoprotectant contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with cryoloop systems and proprietary DMSO-EG blends commanding premium positioning against manual straw alternatives. Price differentiation hinges on ISO 20387 certification status and embryologist training depth requirements. Cost compression in economy-tier consumables is intensifying because Shenzhen VitaVitro Biotech extends manufacturing scale into cost-sensitive Asia-Pacific markets. Biobank procurement committees exhibit lowest price sensitivity due to national precision medicine funding, while independent fertility clinics in India remain most cost-conscious.
Supply Chain Analysis
Regional distribution centers in Yokohama, Munich, and San Diego anchor hub-and-spoke patterns serving clinic networks within 48-hour delivery windows. Pharmaceutical-grade DMSO production concentrates in Chinese chemical manufacturing zones, while precision-engineered warming hardware sources from German and Swiss fabrication facilities. Single-source vulnerability in DMSO supply exposes blenders to export licensing friction and input volatility. Distribution runs through authorized distributor networks with temperature-controlled logistics rather than direct-to-clinic fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as survival-rate consistency displaces upfront cost in procurement criteria, with premium-tier fertility networks in Barcelona and Milan consolidating around closed vitrification systems with integrated temperature monitoring.
For Market Incumbents: Acquire embryologist training certification programs to lock in protocol fidelity dependencies at premium-tier centers. Consolidate vendor relationships around predictive diagnostic capabilities embedded in warming hardware platforms. Threats from automated workflow substitution and embryologist training scarcity limit premium-tier center expansion. Capacity addition in Indian medical tourism corridors defends against cost-driven competitors. For New Entrants and Emerging Players: Begin with Mumbai and Delhi fertility corridors where automated vitrification systems remain underpenetrated by established suppliers. Target stem cell therapy convergence channels beyond reproductive clinics, where CAR-T manufacturing workflows adopt oocyte-derived preservation protocols. A go-to-market angle emphasizing per-procedure support pricing rather than fixed service fees transfers operational risk and accelerates clinic adoption. For Investors and Strategic Acquirers: Integrated media-device portfolio vendors are the most active acquirer in this space, seeking cryoprotectant formulation capabilities to anchor recurring revenue streams. Long-term viability centers on backward integration into pharmaceutical-grade chemical synthesis and captive DMSO supply. Acquisition target archetypes include regional device fabricators with thermocouple array technology and JIS T 0993 biocompatibility data packages. The signal to watch is Sakigake designation submissions to Japan's PMDA, indicating accelerated approval timelines for novel cryoprotectant formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pharmaceutical-Grade DMSO Synthesis | Cryoprotectant blenders secure captive supply against Chinese export licensing volatility. |
| CE Marking Pathway for Class IIa Vitrification Devices | EMA-aligned MDR requirements extend registration timelines by 12-18 months for European market entry. |
| Embryologist Training Certification Partnerships | University fertility centers in Milan and Barcelona lock in protocol fidelity dependencies. |
| Per-Procedure Support Pricing Model | US fertility networks transfer operational risk to vendors while compressing fixed-fee margins. |
| Sakigake Fast-Track Submission to PMDA | Novel cryoprotectant formulations with JIS T 0993 data accelerate Japan approval timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with embryology laboratory directors, biobank quality managers, cryoprotectant procurement leads, and regulatory affairs specialists at fertility networks with secondary validation against FDA 21 CFR Part 1271 filings, EMA MDR device classifications, PMDA Sakigake designations, and ISO 20387 certification databases. Bottom-up procedure volume estimates and top-down market sizing triangulated across cryoprotectant consumption data and device installation records.
Historical reference periods anchored the forecast window to pre-pandemic baseline demand and post-recovery capacity expansion phases across the projection horizon. Segmentation dimensions modeled include product type, application specimen category, end-user procurement sophistication, and technology protocol complexity. CAGRs derived from procedure volume growth curves weighted by cryoprotectant replenishment cycles and device replacement timelines. Industry-specific inputs incorporated biobank infrastructure investment announcements and national precision medicine initiative funding allocations.
Several conditions sit outside the modeled scope, including regulatory approval delays beyond standard timelines, DMSO supply disruptions from export restrictions, and embryologist certification bottlenecks limiting premium-tier center expansion. Forecasts reflect documented assumptions regarding survival-rate improvement trajectories and automation adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Recycled Glass Aggregates Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Glass Block Market
Glass
Low Temperature Laminated Glass Market
Glass
Double Glazing Glass Market
Glass
Glass Alternative Materials Market
Glass
Coated Solar Control Glass Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Porous Glass Market
Glass
Asia Pacific Flexible Glass Market
Glass
China Flat Glass Market
Glass
Glass Balustrade Lamination Market
Glass
India Flat Glass Market
Glass
Glass Grade Dolomite Market
Glass
Shatterproof Glass Market
Glass
Mexico Flat Glass Market