
 North America and Australia Silica Market | 2026-2036
North America and Australia Silica Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Australia Silica Market Intelligence
The American Petroleum Institute's RP 19C qualification for proppants is unwinding the traditional supply base for certain industrial sand grades. This standard creates a quality floor that favors large-scale, consistent producers. U.S. Silica Holdings Inc. leverages its extensive logistics network across North America to serve multiple end markets. Meanwhile, Australian producer VRX Silica Limited positions its assets to meet regional demand, and Covia Holdings LLC specializes in high-purity grades for specialty applications.
Silica, or silicon dioxide (SiO2), is a hard, crystalline mineral compound found extensively in nature as quartz. Its primary industrial value stems from its high melting point, hardness, and chemical inertness. The construction sector's use of sand represents a foundational application, while the electronics industry drives growth for high-purity fused silica. Granular silica forms a major volume segment, but higher-margin opportunities exist in colloidal silica for precision applications like coatings and catalysts.
Regulations from the US Environmental Protection Agency (EPA) concerning respirable crystalline silica dust dictate stringent workplace safety and handling protocols. Similarly, Safe Work Australia sets exposure standards that shape operational practices and investment in dust mitigation technology. These frameworks add compliance costs but also create barriers to entry for smaller operators. Success for market participants depends on navigating these health and safety regulations while investing in purification technologies for high-value segments.
Market Dynamics
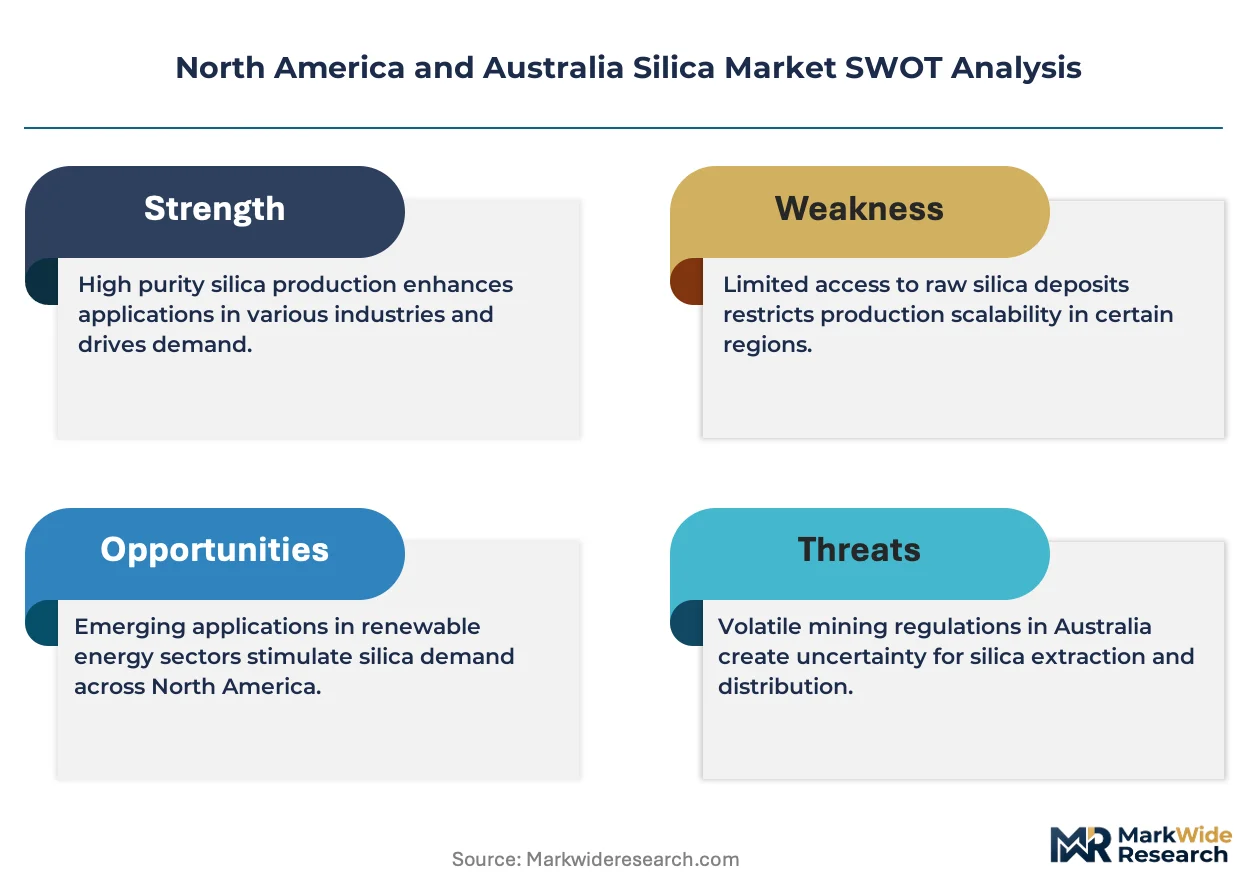
The central structural force shaping the market is the heightened regulatory scrutiny over respirable crystalline silica. This pressure, enforced by agencies like the US EPA and Safe Work Australia, is creating a distinct divide between commodity and specialty silica grades.
Growth Catalysts
- Semiconductor Fabrication:Demand for high-purity fused silica and powders is expanding within US technology corridors for manufacturing advanced integrated circuits and microelectronics.
- Hydraulic Fracturing:The North American energy sector requires vast quantities of industrial sand meeting American Petroleum Institute proppant specifications for shale oil and gas extraction.
- Infrastructure Investment:Government-funded construction and public works projects in both Australia and the United States provide a foundational demand base for construction-grade sand.
Market Restraints
- Energy Intensity:The production of fused and high-purity silica is an energy-intensive process, making producers vulnerable to electricity and natural gas price volatility in North America and Australia.
- Logistical Costs:Major quartz deposits are often located far from industrial centers, creating substantial transportation and supply chain costs to move bulk material to end markets.
- Proppant Substitution:In the oil and gas sector, silica proppants face competition from higher-cost alternatives like resin-coated sand and ceramics that offer different downhole performance characteristics.
Strategic Opportunities
- Renewable Energy Components:The manufacturing of solar panel glass and components for battery energy storage systems creates new applications for specific silica grades in both Australia and the US.
- Colloidal Silica Development:Formulating nano-scale colloidal silica opens high-margin opportunities in precision polishing, advanced coatings, and as binders in catalysts for the chemical industry.
- Mexican Manufacturing Corridor:Supplying specialty silica to Mexico's expanding automotive and electronics manufacturing base represents an underpenetrated geographic adjacency for North American producers.
Industry Challenges
- Compliance Capital Expenditures:Operators face significant investment requirements for dust suppression and wet processing equipment to meet OSHA and Safe Work Australia exposure limits for respirable silica.
- Permitting Delays:Securing environmental and operational permits for new quarrying sites or expanding existing ones is a lengthy and complex administrative hurdle in both regions.
- Specialized Talent Scarcity:A shortage of materials scientists and process engineers with expertise in silica purification and modification limits the pace of new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Australia Silica Market |
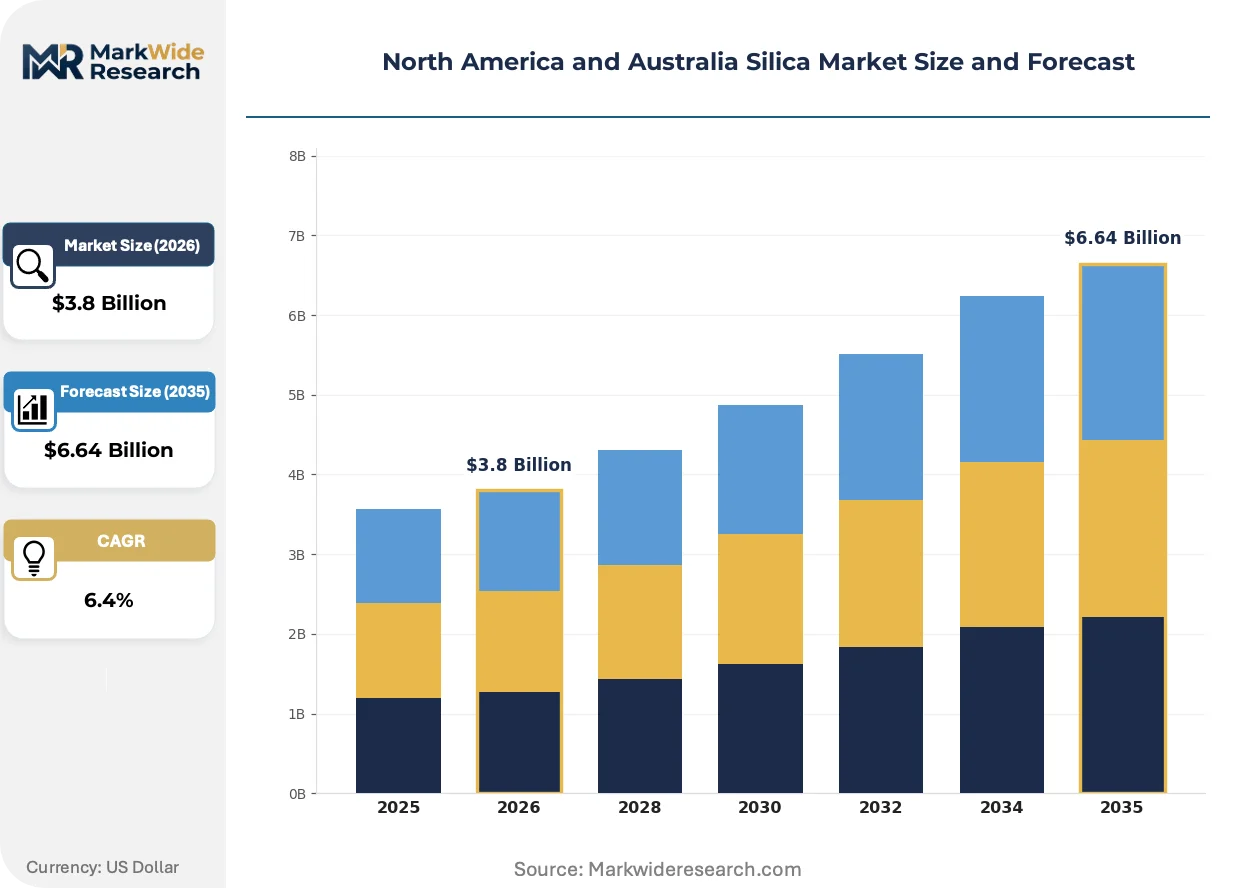
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Silica, Colloidal Silica, Fused Silica, Silica Gel Application: Construction, Glass Manufacturing, Electronics, Agriculture End User: Manufacturers, Builders, Research Institutions, Agricultural Firms Form: Powder, Granules, Beads, Paste |
| Companies Covered | Evonik Industries, PPG Industries, U.S. Silica Holdings Inc., Badger Mining Corporation, Hi-Crush Inc., Covia Holdings LLC, Nouryon, VRX Silica Limited, Sibelco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Australia Silica Market Strategic Shifts & Innovations
Technological advancement in the silica market is defined by a dual pursuit. Producers are developing novel purification methods to meet electronics-grade specifications while simultaneously engineering products and processes that mitigate occupational health risks.
Colloidal silica offers a stable liquid dispersion of amorphous silica nanoparticles for superior surface finishing. The semiconductor industry is rapidly adopting these formulations for chemical-mechanical planarization slurries to achieve defect-free wafer surfaces. This advanced material is displacing traditional abrasive powders and binders due to its capacity for achieving nanometer-scale precision without causing subsurface damage.
The US Environmental Protection Agency's stringent Permissible Exposure Limit for respirable crystalline silica is mandating operational overhauls. This rule requires engineering controls like wet-cutting and vacuum systems, along with rigorous air quality monitoring programs. The construction and oilfield services sectors are most affected, driving investment in dust-suppression technologies and a preference for coated or low-dust silica products.
A clear behavioral change is the increasing reliance on product certifications to guide sourcing decisions, exemplified by the American Petroleum Institute's RP 19C standard. This practice disrupts legacy supply chains by establishing a verifiable quality floor, favoring producers with documented process controls. This procurement pattern is most pronounced in the North American energy sector, where operators demand certified proppants to ensure predictable well performance.
North America and Australia Silica Market Segmentation
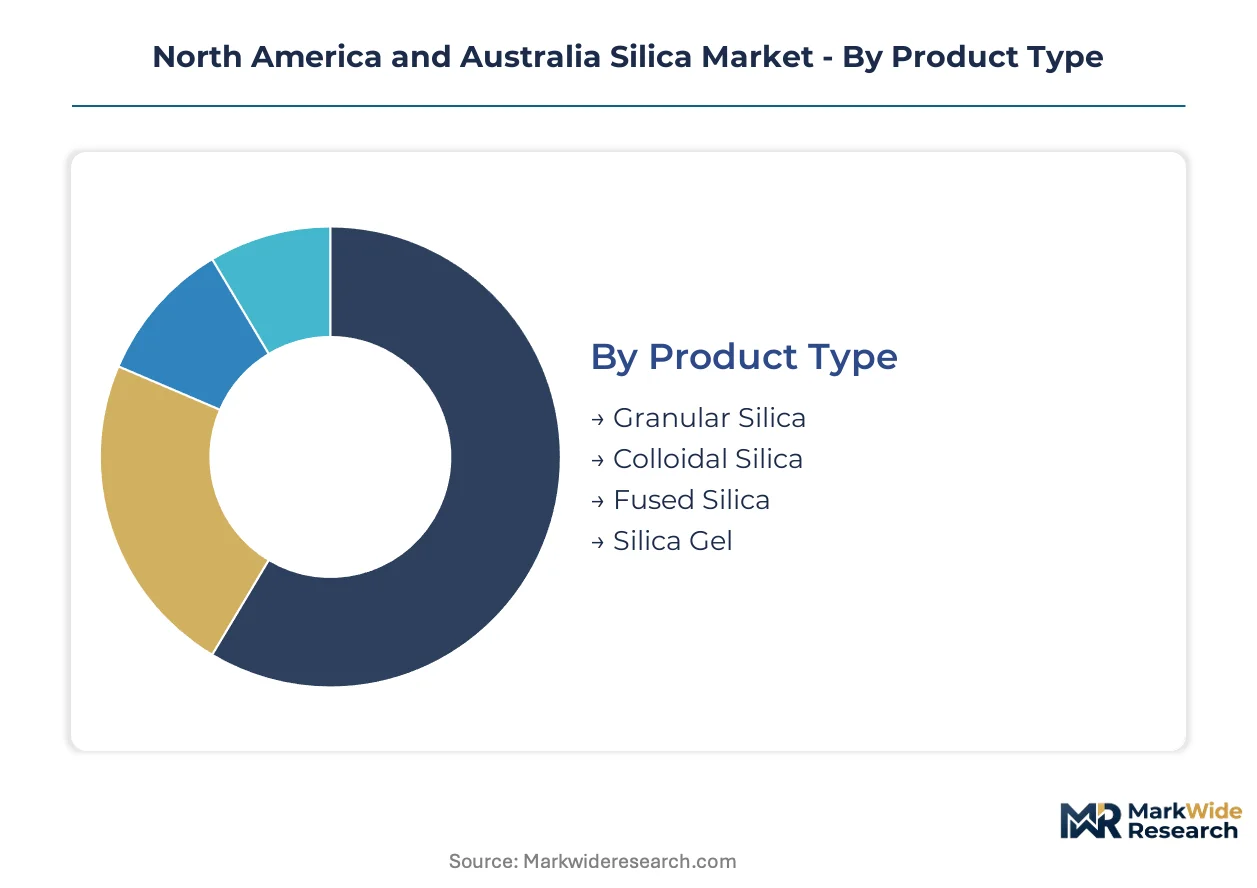
Segmentation provides a critical framework for understanding the diverse dynamics within the North America and Australia silica market. Distinct product types, applications, end-users, and forms exhibit varied growth trajectories and are subject to unique regulatory and technological influences. Analyzing these segments reveals where value creation and demand concentration truly lie.
Product Type:
Regulatory frameworks, particularly those addressing respirable crystalline silica, significantly differentiate product types based on processing requirements and end-use safety protocols.
- Granular Silica:This foundational material, often sourced as industrial sand, serves as a bulk ingredient in numerous industries. Its widespread use in construction and as proppants for hydraulic fracturing establishes its high volume demand.
- Colloidal Silica:This stable liquid dispersion of amorphous silica nanoparticles offers superior surface finishing capabilities. The semiconductor industry in US technology corridors drives demand for these formulations in chemical-mechanical planarization slurries to achieve defect-free wafer surfaces.
- Fused Silica:Produced from high-purity quartz, this non-crystalline form exhibits excellent thermal shock resistance and optical transparency. Electronics manufacturing in North America requires fused silica for critical components like semiconductor wafers and optical fibers, demanding stringent purity levels.
- Silica Gel:A porous form of silica, silica gel functions primarily as a desiccant, adsorbing moisture in packaging and industrial drying applications.
Granular Silica handles the majority of throughput; Colloidal Silica is the fastest mover on share.
Application:
The volume and value contribution of silica varies significantly across its diverse applications, reflecting both commodity scale and specialized performance needs.
- Construction:Sand and gravel, primarily granular silica, serve as fundamental aggregates in concrete, asphalt, and masonry. Infrastructure investment in Australia and the United States ensures a consistent foundational demand for construction-grade silica, driven by public works projects.
- Glass Manufacturing:High-purity silica sand is the primary raw material for producing flat glass, container glass, and specialty glass products.
- Electronics:This sector demands ultra-high-purity silica for semiconductor fabrication, integrated circuits, and optical components. US technology corridors represent a major hub for electronics manufacturing, requiring defect-free silica for advanced microelectronics.
- Agriculture:Silica finds use in agricultural settings as a soil amendment, improving plant strength and resistance to pests and diseases.
Construction applications command the largest market size; Electronics applications drive the most innovation.
End User:
Customer types in the silica market exhibit distinct procurement patterns, driven by scale, technical specifications, and regulatory compliance requirements.
- Manufacturers:This segment encompasses diverse industries like electronics, glass, chemicals, and rubber, all requiring specific silica grades for their production processes. Large-scale manufacturers often seek long-term supply contracts with producers capable of meeting stringent quality and volume specifications.
- Builders:Construction companies and contractors utilize vast quantities of silica in the form of sand and aggregates for infrastructure projects and residential/commercial developments. Their procurement prioritizes local availability, consistent supply, and adherence to construction material standards.
- Research Institutions:Academic and corporate research entities require highly specialized and ultra-pure silica for material science, chemical synthesis, and advanced technological development.
- Agricultural Firms:Farms and agricultural businesses use silica-based products for soil conditioning, crop protection, and livestock feed supplements.
Manufacturers exert the broadest market influence; Research Institutions represent highly specialized niche demand.
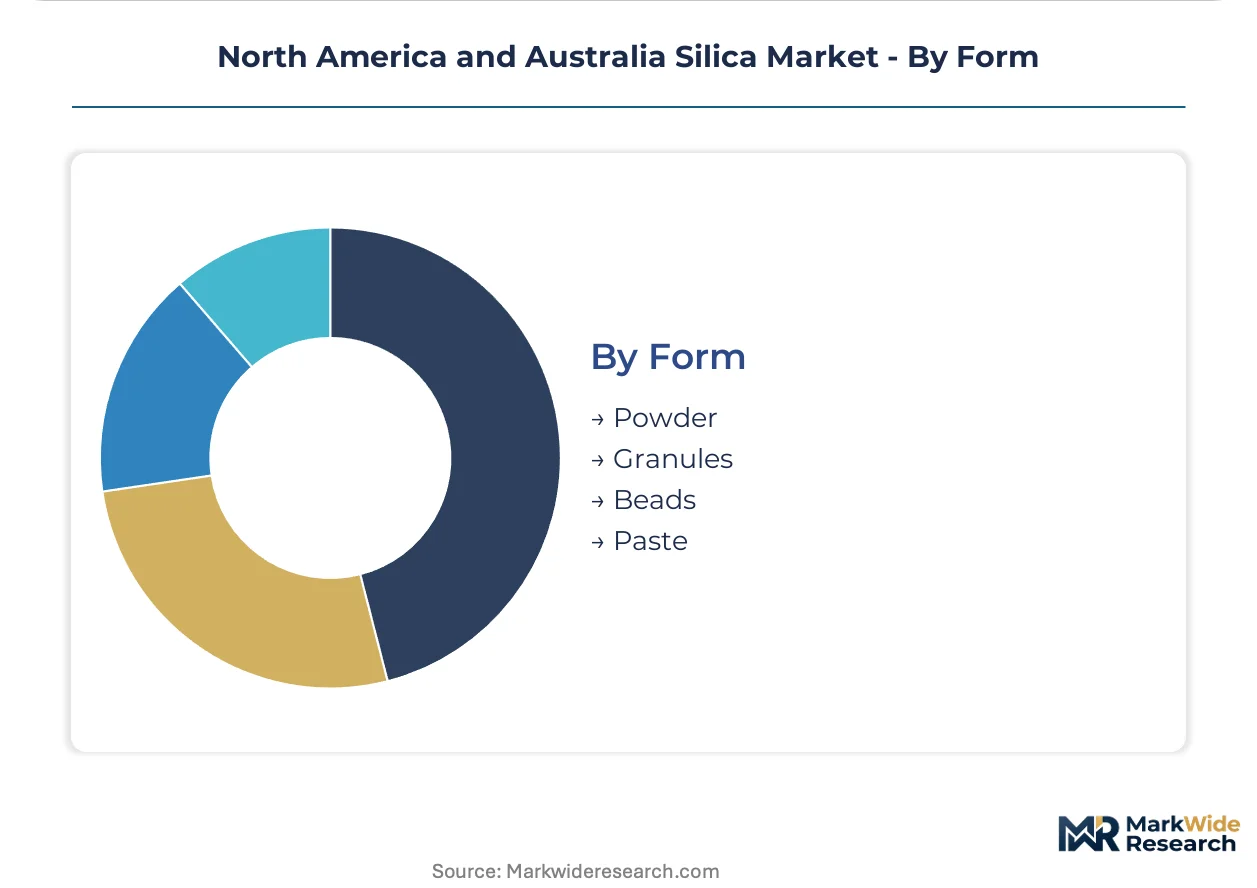
Form:
The physical form of silica directly impacts its processing requirements, handling logistics, and the value proposition it offers across different industrial applications.
- Powder:Fine silica powders are critical for high-purity applications in electronics, coatings, and chemical manufacturing. The semiconductor industry uses specialized silica powders for chemical-mechanical planarization and as fillers in encapsulants, requiring precise particle size distribution.
- Granules:This form represents the largest volume segment, used extensively as industrial sand, proppants for hydraulic fracturing, and aggregates in construction. The North American energy sector relies on granular silica meeting American Petroleum Institute proppant specifications for shale oil and gas extraction.
- Beads:Silica beads, often in gel form, are employed as desiccants, chromatography media, and catalyst supports due to their high surface area and porosity.
- Paste:Silica in paste form is typically used in specialty applications like polishing compounds, sealants, and advanced ceramic formulations.
Granules dominate the bulk volume; Powder forms enable high-precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stricter environmental and occupational health regulations, alongside significant infrastructure investment, shape the silica market across North America and Australia. These frameworks influence processing methods and procurement decisions, creating distinct regional dynamics. Demand concentrates in specific industrial corridors and resource-rich regions, reflecting varied economic priorities.
United States
United States demand for high-purity silica expands in semiconductor fabrication and hydraulic fracturing. The US EPA and OSHA regulations mandate stringent workplace safety protocols for respirable crystalline silica. US technology corridors in California and the Permian Basin in Texas drive specific material requirements for advanced electronics and energy extraction.
Canada
Canadian energy sector projects, including oil sands extraction and shale gas development, require specialized silica proppants and construction aggregates. Health Canada sets exposure standards for crystalline silica, influencing operational practices across the country's industrial sites. Alberta's oil and gas industry and Ontario's manufacturing base represent major demand centers for various silica grades.
Mexico
Mexican automotive and electronics manufacturing sectors increasingly require specialty silica grades for various components and production processes. Federal labor laws in Mexico govern workplace safety and dust exposure limits, impacting material handling and processing. The Bajío region, with its automotive clusters, and northern border states, for electronics assembly, are focal points for industrial silica consumption.
Australia
Australian mining operations and extensive infrastructure development projects create consistent demand for industrial sand and proppants. Safe Work Australia's exposure standards for respirable silica shape investment in dust mitigation technologies and processing methods. Western Australian mining regions and Queensland's construction sector are key consumption areas, alongside emerging solar panel manufacturing.
North America and Australia Silica Market Key Industry Players
Listed leaders compete with private specialists across the silica market, which exhibits a tiered structure. Large-scale commodity producers focus on volume and logistics, while high-purity specialty material providers target niche applications. Regional suppliers often serve localized construction and industrial needs, adapting to specific local demand. Companies pursue capacity expansion and technology investments to meet regulatory compliance and evolving product specifications across these segments.
Specialists in logistics and high-volume supply, such as U.S. Silica Holdings Inc., exemplify the market's scale-driven segment across North America. Australian producer VRX Silica Limited occupies a position focused on regional resource development and local market supply within Australia. Covia Holdings LLC represents the archetype of a producer specializing in high-purity grades, targeting advanced applications like electronics manufacturing in critical technology corridors. These companies navigate distinct market pressures, from commodity pricing to stringent purity requirements.
| Leading Market Players |
|---|
| Evonik Industries |
| PPG Industries |
| U.S. Silica Holdings Inc. |
| Badger Mining Corporation |
| Hi-Crush Inc. |
| Covia Holdings LLC |
| Nouryon |
| VRX Silica Limited |
| Sibelco |
| Others |
Cost & Logistics Intelligence
American Petroleum Institute's RP 19C standard for proppants establishes a critical quality floor, directly impacting supply qualification and creating distinct price differentiation across industrial sand grades. This certification gates market access and influences pricing power for compliant producers.
Pricing Analysis
Certification level, such as API RP 19C for proppants or ultra-high purity for electronics, creates the primary price spread in the silica market. The dominant pricing model combines long-term contract-based offtake for specialty grades with commodity spot pricing for bulk industrial sands; geographic delivery cost also drives significant price differentiation. Pricing softness stems from energy intensity and substantial logistical costs. Construction sector buyers are most price-sensitive, while electronics manufacturers prioritize performance.
Supply Chain Analysis
Strategic stockpiling of raw quartz and processed silica is common for high-volume commodity grades, while specialty silica often operates on a more just-in-time basis for specific applications. Supply concentration centers on Western Australian mining regions and the Permian Basin in the United States, drawing heavily from high-purity quartz deposits and consistent energy supply. Logistics chokepoints, given the bulk nature and distance from deposits, pose a structural risk. Distribution runs through direct sales for large industrial clients and regional networks for smaller, specialized buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America and Australia silica market demands a strong substitution defense from incumbents. Proppant substitution in the oil and gas sector by higher-cost alternatives like resin-coated sand and ceramics represents a key threat.
For Market Incumbents:Shield core proppant and construction sand volumes by leveraging extensive logistics networks and API RP 19C certification. Invest in advanced purification technologies and colloidal silica R&D to capture high-margin electronics applications. Regulatory compliance costs from the US EPA and Safe Work Australia create barriers to entry for smaller competitors. Strategic capacity additions in key technology corridors will secure future growth.
For New Entrants and Emerging Players:Technical support and customized formulation services represent a service-layer gap where incumbents under-serve. Target the Mexican manufacturing corridor for specialty silica in automotive and electronics components. Focus on developing nano-scale colloidal silica for precision polishing and advanced coatings, offering superior performance. A go-to-market strategy emphasizing technical expertise and application-specific solutions will foster early adoption.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core silica assets. Long-term demand for high-purity and specialty silica remains strong across the forecast horizon. Focus on acquiring vertically integrated mid-cap specialists possessing proprietary purification technologies and strong logistics. The signal to watch is sustained capital expenditure in advanced dust mitigation and colloidal silica production capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Silica | Secures supply for semiconductor fabrication and optical fiber production. |
| Investment in Dust Mitigation Technology | Ensures compliance with EPA and Safe Work Australia regulations. |
| Development of Colloidal Silica Formulations | Captures high-margin opportunities in precision polishing and catalysts. |
| Long-term Offtake Agreements with Electronics Manufacturers | Provides revenue stability and volume commitment for specialty grades. |
| Logistics Network Optimization in North America | Reduces transportation costs for bulk materials to industrial centers. |
Research Approach
Initial hypotheses were tested against primary input from plant managers, R&D directors, procurement leads at electronics firms, and environmental compliance officers, then refined through iterative analysis. This involved extensive interviews with industry participants, validated by secondary data. Secondary sources included US EPA reports, Safe Work Australia guidelines, API specifications, and company 10-K filings. A bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Variance decomposition isolates the impact of demand drivers, regulatory shifts, and technological advancements on market growth across the analysis window. The model segmented demand by product type, application, end-user, form, and regional regulatory impact. Compound Annual Growth Rates were derived from historical trends, projected demand drivers, and anticipated technological adoption rates. Key inputs included semiconductor manufacturing output and hydraulic fracturing activity.
Underlying assumptions cover a stable regulatory environment and consistent energy prices, with deviation risk concentrated in unforeseen geopolitical events or rapid technological disruption. Forecasts reflect these assumptions throughout the projection horizon. Revision becomes warranted when significant shifts in environmental regulations or energy commodity prices cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Shatterproof Glass Market
Glass
Decorative Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Crystalware and Glassware Market
Glass
Screen-Printing Glass Market
Glass
Pharma Glass Tubing Market
Glass
Ultra Violet Glass Bottles Market
Glass
Global Self-Cleaning Glass Market
Glass
France Silica Sand Market
Glass
Global Scratch Resistant Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Borosilicate Glass Market
Glass
Asia-Pacific Flat Glass Market
Glass
Europe Glass Insulators Market
Glass
Recycled Glass Aggregates Market
Glass
Fiberglass Window Market