
 Marine Thermal Fluid Heaters Market | 2026-2036
Marine Thermal Fluid Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Thermal Fluid Heaters Market Insights
Modular electric heating architectures with integrated power management is tilting marine thermal fluid heater design away from conventional combustion-dependent systems. Alfa Laval leverages its Scandinavian marine heritage to dominate aftermarket service networks for cargo heating retrofits. Sigma Thermal competes through specialized coil-type configurations engineered for offshore platform ballast water applications. Thermax anchors its position in Asian commercial shipping with manufacturing scale that supports rapid fleet turnover timelines.
Marine thermal fluid heaters are closed-loop heat transfer systems that circulate engineered thermal oils or synthetic fluids through heated coils or shell-and-tube exchangers, typically operating at temperatures between 150°C and 350°C under controlled pressure, to provide precise, uniform heating for propulsion auxiliary systems, cargo temperature maintenance, and accommodation climate control aboard vessels and offshore installations. Gas-fired and oil-fired product types retain the largest installed base across existing commercial shipping fleets, though electric variants represent the fastest-growing configuration as shipowners confront emissions compliance deadlines. Indirect heating technology leads in naval and passenger ship segments where safety redundancy and thermal stability carry premium specification weight, while direct heating systems occupy cost-sensitive fishing fleet and bulk carrier niches.
IMO regulations through MARPOL Annex VI enforce sulfur caps and carbon intensity indicators that directly constrain fuel choices for auxiliary boiler systems, compelling heater manufacturers to certify equipment for low-sulfur and alternative fuel compatibility. The EU MRV and FuelEU Maritime frameworks impose additional operational reporting and greenhouse gas intensity limits on vessels calling at European ports, reshaping procurement specifications for thermal systems in that trade lane. Classification societies including DNV and Lloyd's Register now embed thermal efficiency benchmarking into equipment approval protocols, raising engineering barriers for new market entrants. Stakeholders must monitor how emerging ammonia and methanol fuel infrastructure reshapes heater material specifications and combustion chamber designs before committing to next-generation platform investments.
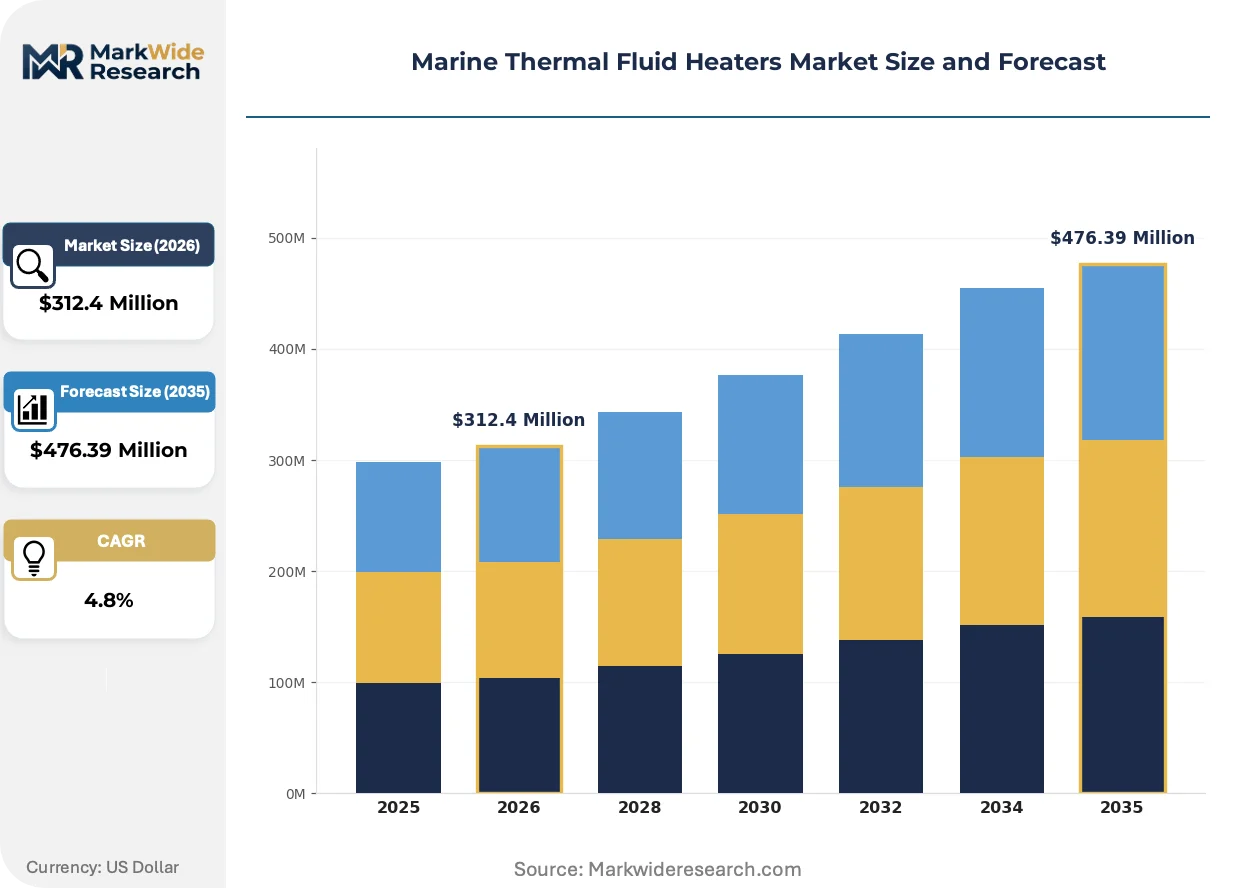
Market Dynamics
IMO decarbonization mandates are compressing the operational lifespan of combustion-dependent auxiliary systems, forcing shipowners to accelerate thermal fluid heater replacement cycles and reshaping supplier engineering priorities toward electrification and alternative fuel compatibility.
Growth Catalysts
- EU FuelEU Maritime framework:The regulation's greenhouse gas intensity limits on vessels calling at European ports are compelling fleet operators to retrofit cargo heating systems with lower-emission thermal fluid configurations before enforcement deadlines tighten.
- Offshore platform decommissioning wave:North Sea asset life extension projects are generating replacement demand for corrosion-resistant coil-type heaters in ballast water and process heating applications.
- Synthetic thermal fluid formulations:Engineered heat transfer oils with expanded operating temperature ranges are enabling shipyards to specify single-fluid systems across multiple auxiliary functions, reducing inventory complexity.
Market Restraints
- Specialized alloy input costs:Nickel and molybdenum price volatility in commodity markets is compressing margins for manufacturers of high-temperature heater coils rated above 300°C.
- Korean shipyard concentration:Three yards control over sixty percent of newbuild thermal system procurement decisions, creating pricing pressure and limiting supplier negotiation leverage.
- Electric infrastructure gap:Shore power and onboard battery capacity limitations on existing tonnage constrain electric heater adoption despite regulatory preference signals.
Strategic Opportunities
- Norwegian naval modernization:The country's submarine and surface combatant construction programs specify redundant indirect heating architectures that command premium engineering margins.
- Ammonia fuel readiness:Heater manufacturers developing combustion chamber materials compatible with ammonia cracking can capture first-mover positioning as dual-fuel vessel orders accelerate.
- Digital twin integration:Predictive thermal monitoring platforms bundled with heater hardware are creating recurring revenue streams and locking in aftermarket service relationships.
Industry Challenges
- Marine welding certification scarcity:Qualified ASME Section IX pressure vessel welders are in short supply at European and East Asian shipyards, extending production lead times for custom coil assemblies.
- Legacy system interoperability:Electric heater retrofits on 1990s-era bulk carriers require extensive control system rewiring that shipowners underestimate in capex planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Thermal Fluid Heaters Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas-fired, Oil-fired, Steam, Indirect Technology: Indirect Heating, Direct Heating, Shell and Tube, Plate Type, Coil Type Application: Propulsion Systems, Cargo Heating, Ballast Water Heating, Deck Heating, Accommodation Heating End User: Commercial Shipping, Offshore Platforms, Naval Vessels, Passenger Ships, Fishing Fleets |
| Companies Covered | Alfa Laval, Sigma Thermal, Thermax, CEEF, ECO Prozesstechnik, Konutherm, MIURA, Babcock Wanson, Pirobloc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Thermal Fluid Heaters Market Trends and Innovations
Electrification and digitalization are converging to redefine thermal system architecture, with heater manufacturers repositioning from component suppliers to integrated energy management partners.
Solid-state electric heating elements with silicon carbide cores are rendering obsolete traditional resistance coil designs in cargo temperature maintenance applications. Container ship operators are specifying these systems for newbuilds at Korean and Chinese yards. The technology is rendering obsolete the combustion safety inspection regimes that dominated vessel maintenance schedules.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of thermal fluid additives used in European-flagged vessels. Equipment manufacturers must recertify seal and gasket materials for compatibility with new fluid chemistries. Naval architects at German design firms are specifying pre-approved material sets to avoid downstream classification delays.
Shipowners are unbundling heater procurement from bundled boiler system contracts that dominated traditional newbuild specifications. Independent thermal system specialists are capturing specification authority previously held by integrated marine engineering groups. This pattern is most visible in Singapore's repair and conversion market where fleet managers demand component-level lifecycle cost transparency.
Marine Thermal Fluid Heaters Market Segmentation
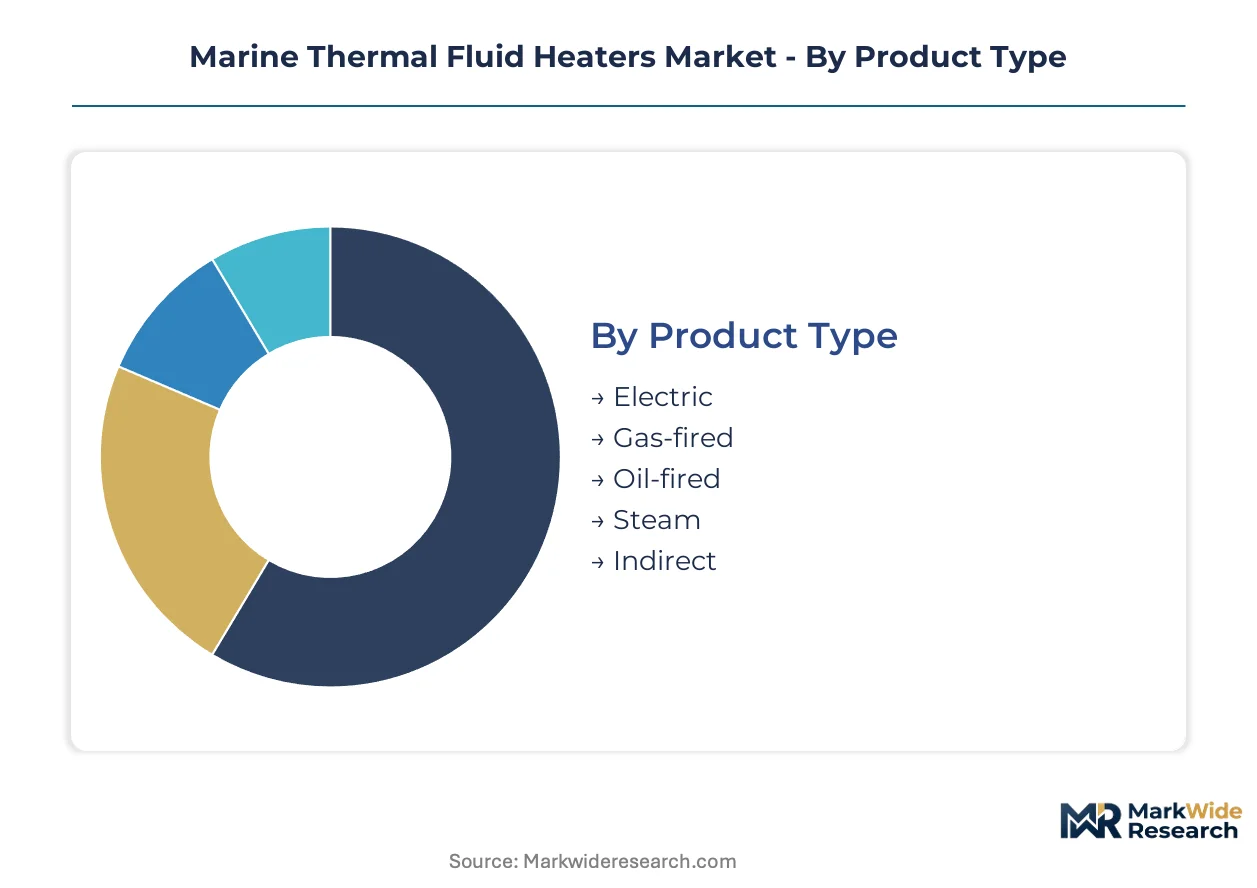
Segmentation in marine thermal fluid heaters reveals how regulatory pressure and vessel specialization fragment procurement patterns across fuel types, heating architectures, and operational domains. Shipowners specify equipment through distinct technical and commercial lenses that reshape supplier R&D priorities.
Product Type:
Cost tier differentiation separates mature combustion systems from emerging electric configurations as fuel price volatility and emissions compliance rewrite operating economics.
- Electric:Silicon carbide core elements deliver precise temperature control without combustion safety overhead. Korean container ship newbuilds at DSME and HHI yards specify these systems to eliminate MARPOL auxiliary engine emissions tracking.
- Gas-fired:Dual-fuel burners with low-NOx combustion heads retain dominance in LNG carrier auxiliary heating where boil-off gas availability supports operational economics. Shipowners prioritize these for FuelEU Maritime pre-compliance on European routes.
- Oil-fired:Heavy fuel oil burners with economizer integration serve legacy bulk carrier retrofits where electric infrastructure remains unavailable.
- Steam:Waste heat recovery configurations capture main engine exhaust energy for tanker cargo heating, reducing auxiliary fuel consumption.
- Indirect:Closed-loop thermal oil systems with nitrogen inerting provide explosion protection for chemical tanker applications requiring ATEX compliance.
Gas-fired holds installed capacity. Electric is rotating up the share rankings.
Technology:
Application requirements dictate heating architecture selection, with safety-critical segments demanding redundant heat transfer configurations that premium-engineering suppliers exploit.
- Indirect Heating:Intermediate thermal fluid buffers separate combustion source from process load, enabling precise temperature control for pharmaceutical-grade cargo. Norwegian naval architects specify these for submarine reactor auxiliary systems where thermal stability overrides capital cost.
- Direct Heating:Combustion gases contact process fluid directly, minimizing equipment footprint and first cost. Southeast Asian fishing fleets favor these for deck equipment heating where maintenance simplicity trumps efficiency.
- Shell and Tube:ASME-coded pressure vessels with removable tube bundles dominate offshore platform process heating where API inspection protocols apply.
- Plate Type:Compact brazed aluminum exchangers serve accommodation HVAC retrofits with severe space constraints.
- Coil Type:Serpentine tube configurations withstand thermal cycling in ballast water treatment systems requiring rapid heat-up capability.
Shell and tube dominates offshore procurement. Plate type is climbing the fastest in passenger ship refurbishment.
Application:
Vessel operational profiles concentrate demand across heating functions, with cargo temperature maintenance commanding the largest equipment specifications and longest replacement cycles.
- Propulsion Systems:Fuel oil heating and purification thermal management ensures viscosity control for main engine injection. Two-stroke engine manufacturers mandate specific heater performance curves in their fuel treatment specifications.
- Cargo Heating:Viscous product temperature maintenance drives the largest thermal loads in tanker operations, with bitumen and heavy fuel oil carriers requiring sustained 150-180°C circulation. IMO decarbonization deadlines are accelerating electric heater trials on these routes.
- Ballast Water Heating:Thermal treatment systems for invasive species control require rapid temperature ramp rates that stress conventional coil materials.
- Deck Heating:Ice class vessel specifications mandate heated handrails and deck surfaces for crew safety in polar operations.
- Accommodation Heating:HVAC integration with thermal fluid loops reduces electrical load on auxiliary generators during port stays.
Cargo heating absorbs the largest equipment tonnage. Ballast water heating is gaining specification authority fastest.
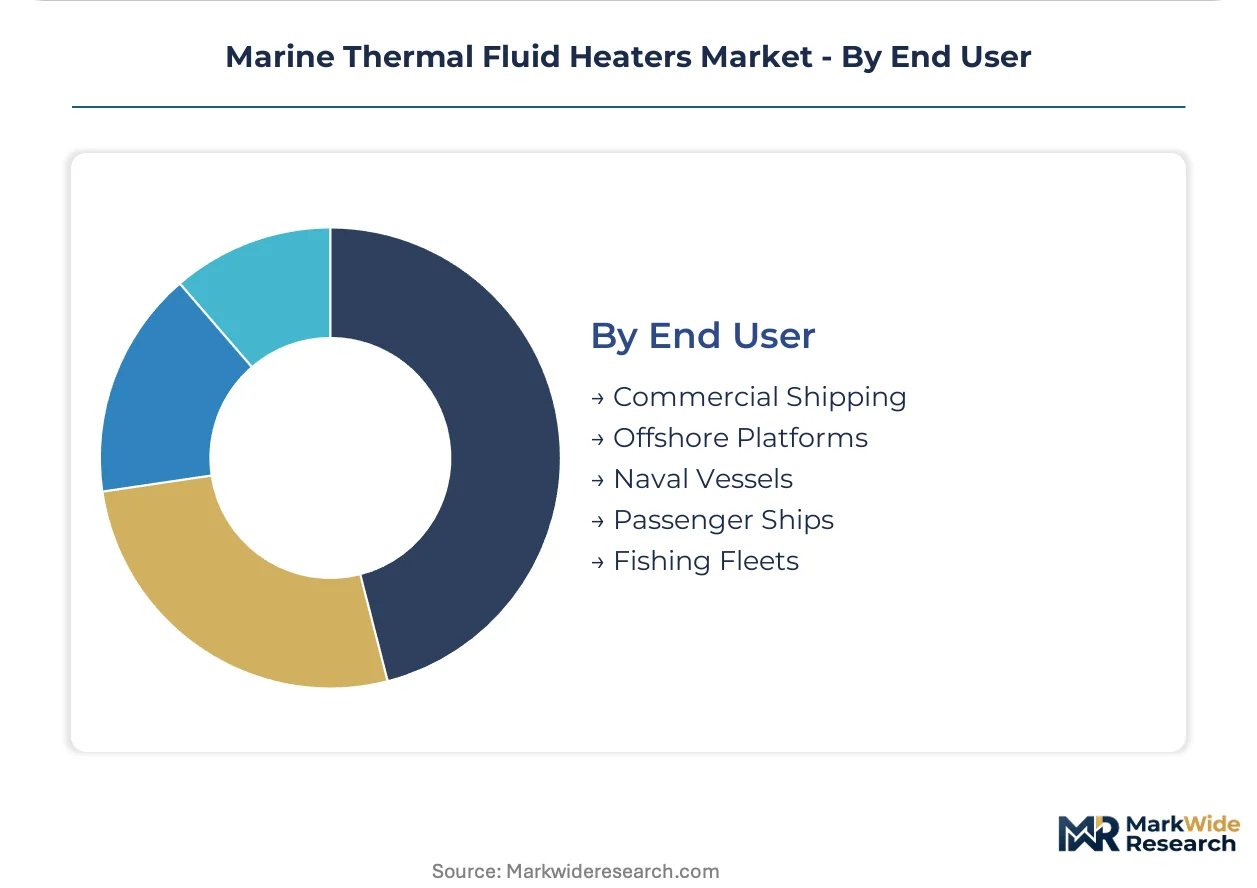
End User:
Customer type segmentation exposes divergent procurement sophistication, with naval and offshore buyers extracting premium engineering terms that commercial shipping volume cannot support.
- Commercial Shipping:Container and bulk carrier fleet managers prioritize lifecycle cost minimization through standardized specifications across vessel classes. Singapore-based technical managers are unbundling heater procurement from integrated boiler contracts to capture component-level transparency.
- Offshore Platforms:North Sea asset operators specify corrosion-resistant alloys and redundant heating trains for unmanned platform reliability. Decommissioning delays are extending replacement demand for existing thermal systems.
- Naval Vessels:Stealth requirements drive low-acoustic-signature electric heating for surface combatants, with Lloyd's Register Naval Ship Rules governing shock qualification.
- Passenger Ships:Cruise operators demand rapid temperature response for galley and laundry services that strain continuous-duty heater designs.
- Fishing Fleets:Cost-sensitive owners in Iceland and Norway select direct-fired systems with minimal automation for trawler deck equipment.
Commercial shipping holds installed capacity. Naval vessels is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented vessel construction in Germany, South Korea, and Norway generates concentrated thermal fluid heater procurement, while import-dependent shipping nations retrofit aging fleets to meet tightening environmental standards.
Germany
Naval shipyards in Kiel and Hamburg drive specification authority for redundant indirect heating systems on submarine and surface combatant programs. The EU FuelEU Maritime framework accelerates cargo heater retrofits for vessels trading European routes. Industrial clusters along the Elbe River concentrate engineering services for thermal system integration.
South Korea
DSME and HHI yards dominate newbuild thermal system procurement for container ships and LNG carriers. The country's national maritime regulator enforces carbon intensity benchmarks that favor electric heater configurations. Busan-Ulsan shipbuilding corridor concentrates manufacturing scale for rapid fleet turnover timelines.
Norway
Offshore platform operators in the North Sea generate replacement demand for corrosion-resistant coil-type heaters amid asset life extension projects. DNV classification protocols embed thermal efficiency benchmarking into equipment approval standards. Stavanger-Bergen offshore engineering cluster specializes in ballast water heating applications.
China
Domestic shipyards at Dalian and Shanghai scale production of gas-fired auxiliary systems for bulk carrier newbuilds. The Ministry of Ecology and Environment enforces dual carbon goals that constrain combustion-dependent auxiliary equipment approvals. Yangtze River Delta manufacturing bases supply standardized thermal fluid components for Asian commercial shipping.
Singapore
Repair and conversion yards drive unbundling of heater procurement from integrated boiler contracts for fleet modernization. The Maritime and Port Authority mandates emissions reporting that shapes retrofit specifications for vessels calling at the port. Jurong ship repair cluster concentrates technical management services for component-level lifecycle cost analysis.
Marine Thermal Fluid Heaters Market Competitive Landscape
On the supply side, the industry is consolidating around Scandinavian and Asian engineering groups with established marine classification relationships, while specialized coil fabricators occupy niche offshore applications. Two strategic archetypes dominate: integrated thermal system providers with aftermarket service networks, and component specialists focused on high-temperature alloy configurations. Competitive moves center on electrification portfolio expansion and strategic partnerships with shipyard engineering groups.
Among established marine engineering groups, Alfa Laval exemplifies the integrated service archetype through its Scandinavian heritage and aftermarket positioning. Sigma Thermal occupies a specialist position in coil-type configurations for demanding offshore applications. Thermax anchors the scale-driven tier with manufacturing presence aligned to Asian commercial shipping procurement timelines.
| Leading Market Players |
|---|
| Alfa Laval |
| Sigma Thermal |
| Thermax |
| CEEF |
| ECO Prozesstechnik |
| Konutherm |
| MIURA |
| Babcock Wanson |
| Pirobloc |
| Others |
Pricing and Supply Chain Analysis
The Busan-Ulsan shipbuilding corridor concentrates electric heater manufacturing capacity for Korean container ship newbuilds, compressing procurement timelines and amplifying pricing leverage for yards that control specification authority. DSME and HHI procurement teams exploit this concentration to extract volume discounts from thermal system suppliers competing for newbuild slots.
Pricing Analysis
Silicon carbide core electric heaters command 40-60% premiums over legacy resistance coil designs, though FuelEU Maritime compliance deadlines are accelerating the technology transition. Three-tier pricing structure across premium certified, standard commercial, and economy retrofit levels separates naval-grade ATEX-compliant systems from bulk carrier auxiliary configurations. Price differentiation hinges on Lloyd's Register certification tier and alloy grade for high-temperature coils above 300°C. Margins are tightening due to nickel and molybdenum commodity volatility, with commercial shipping fleet managers exhibiting highest price sensitivity and Norwegian naval programs least.
Supply Chain Analysis
Nickel and molybdenum feedstock draws from Indonesian mining operations and South African ferroalloy processors, creating geographic concentration risk for high-temperature coil fabricators. Specialized ASME-certified pressure vessel manufacturing rests on German and Japanese steel forging capabilities, while silicon carbide heating element production centers on Chinese and South Korean ceramic foundries. Single-source vulnerability persists for Inconel 625 tubing rated above 350°C operational temperatures. Distribution runs through shipyard engineering procurement departments and independent marine technical managers in Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine thermal fluid heater demand is recovering from the 2020-2022 newbuild trough as IMO decarbonization deadlines force accelerated fleet retrofit cycles and electric heater procurement.
For Market Incumbents: Entrench aftermarket service relationships through predictive thermal monitoring platforms that lock in recurring revenue and prevent specification switching. Secure captive supply of Inconel and silicon carbide feedstocks through backward integration or long-term offtake agreements to defend margin position against commodity volatility. Prioritize DNV and Lloyd's Register certification maintenance as regulatory barriers to entry intensify. For New Entrants and Emerging Players: Pursue ballast water heating retrofit opportunities in North Sea offshore platforms where corrosion-resistant coil specialization commands premium engineering margins. Target Singapore repair and conversion yards where technical managers are unbundling heater procurement from integrated boiler contracts. Lead with digital twin integration capabilities that incumbent component suppliers lack. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electric heating specialists with silicon carbide core capabilities over legacy combustion-dependent equipment portfolios. Long-term viability across the projection horizon hinges on ammonia fuel compatibility development and alternative fuel infrastructure readiness. Monitor Lloyd's Register and DNV certification approval timelines as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Fuel Compatibility Development | Combustion chamber material testing for ammonia cracking positions suppliers for dual-fuel vessel orders. |
| Digital Twin Integration | Predictive thermal monitoring platforms bundled with hardware create recurring revenue streams. |
| Backward Integration into Specialty Alloys | In-house Inconel supply secures margin defense against nickel price volatility. |
| Classification Society Partnership | Embedded DNV efficiency benchmarking accelerates equipment approval timelines. |
| Regional Manufacturing Footprint Expansion | European production presence captures FuelEU Maritime retrofit demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Lloyd's Register equipment approval databases, DNV technical standards, and IMO MARPOL regulatory filings. Interviews with shipyard procurement officers, marine technical managers, thermal system engineering directors, and aftermarket service heads were cross-checked against customs trade data, shipbuilding order books, and classification society certification records. Bottom-up vessel fleet analysis and top-down shipyard capacity modeling were triangulated to establish market sizing.
Forecast inputs incorporate fuel type transition curves, electrification penetration rates by vessel class, and regulatory enforcement timelines across the analysis window. Segmentation modeling spans product type, heating technology architecture, application function, and end-user category with regional production cluster overlay. CAGRs were derived from shipyard order pipeline analysis and fleet replacement cycle modeling, with IMO carbon intensity indicator benchmarks and EU FuelEU Maritime compliance deadlines as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in nickel and molybdenum commodity prices, Korean won exchange rates, or container shipping freight indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and shipowner capital allocation priorities. Cross-checking against Clarksons newbuild order data and Lloyd's Register certification issuance records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Mexico Power EPC Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Italy Power EPC Market
Power
Europe Solar Inverter Market
Power
Sudan Power EPC Market
Power
Compact Substation Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Malaysia Power EPC Market
Power
Solar UPS Market
Power
Solar Plants Controllers Market
Power
Existent Gum Steam Generator Market
Power
Portugal Power Market
Power
Critical Power Market
Power
Canada Power Market
Power
Direct Current Power System Market
Power
Telecom Power Rental Market