
 India E-Bike Market | 2026-2036
India E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
India E-Bike Market Outlook
The India E-Bike Market is decoupling into premium lithium-ion models with connected features and commoditized lead-acid variants serving price-sensitive buyers. Hero Electric leverages its nationwide service network to sustain volume leadership in tier-two cities. Ola Electric anchors its position through in-house cell manufacturing and direct-to-consumer digital sales. EMotorad specializes in rugged, long-range designs that occupy the adventure and rural mobility niche.
An e-bike is a two-wheeled electric vehicle integrating a rechargeable battery pack, hub or mid-drive motor, and pedal-assist or throttle-based propulsion, typically governed by a controller limiting speed to 25 km/h under Indian regulations. Its primary purpose is to replace internal-combustion two-wheelers and pedal cycles for short-to-medium urban trips while reducing operating costs and particulate emissions. Pedal-Assist products dominate unit volumes due to regulatory permissiveness and consumer familiarity with cycling mechanics, while the Above 90 km range category captures disproportionate margin pools from fleet operators and intercity commuters. Delivery Services represent the fastest-growing end-user segment as logistics firms electrify last-mile operations to comply with municipal clean-air mandates.
The Ministry of Heavy Industries administers FAME II subsidies that directly reduce e-bike purchase prices, while BIS certification mandates govern battery safety and vehicle construction standards. State transport departments in Delhi and Maharashtra enforce registration exemptions and road-tax waivers that accelerate consumer adoption. Stakeholders must monitor how BIS updates its EV battery standards and whether states extend commercial fleet incentives beyond current program horizons.
Market Dynamics
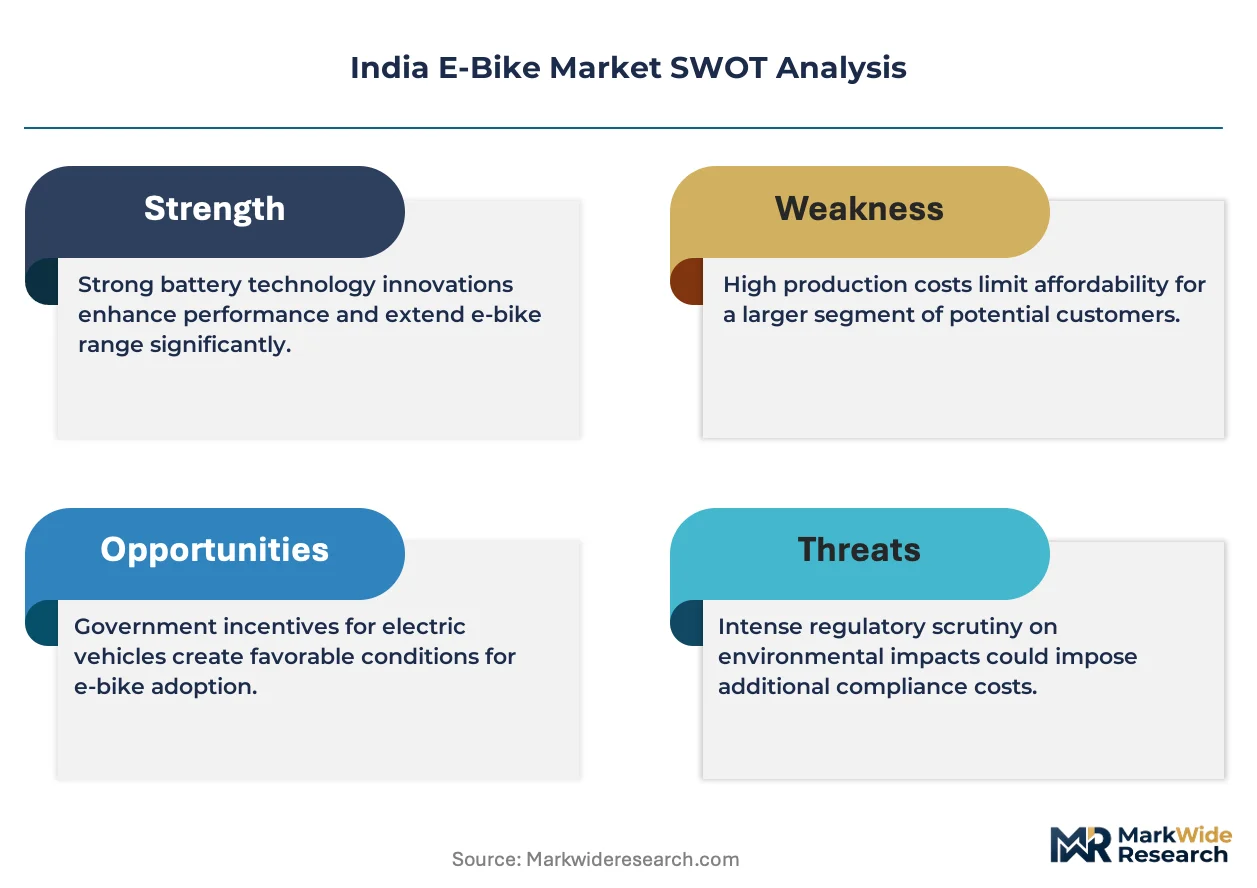
FAME II subsidy compression and state-level EV policy fragmentation are forcing manufacturers to arbitrage between lithium-ion premiumization and lead-acid volume defense, reshaping how capital flows across the value chain.
Growth Catalysts
- FAME II subsidy regime:Direct purchase price reductions administered by the Ministry of Heavy Industries accelerate consumer uptake in Maharashtra and Karnataka.
- Last-mile delivery electrification:Logistics firms in Bengaluru and Mumbai expand fleet procurement to comply with municipal clean-air mandates.
- Lithium-ion cell cost curves:Domestic battery pack assembly integration compresses total cost of ownership versus internal-combustion alternatives.
Market Restraints
- Charging infrastructure gaps:Uneven distribution of public charging points across tier-three cities limits range confidence for intercity commuters.
- Lead-acid dependency:Price-sensitive rural segments remain locked to heavier, shorter-lifecycle battery chemistries that constrain product margins.
- BIS certification timelines:Extended battery safety testing protocols delay new model launches by six to nine months.
Strategic Opportunities
- Tamil Nadu industrial corridor:Chennai-Ambattur manufacturing clusters offer proximity to electronics component suppliers and port logistics.
- Adventure and rural mobility niche:Rugged, long-range designs for unpaved terrain remain underserved by mainstream urban-focused portfolios.
- Direct-to-consumer digital channels:App-based configuration and home delivery bypass traditional dealer margin stacking.
Industry Challenges
- Power electronics talent scarcity:Motor controller firmware and battery management system engineering skills concentrate in Bengaluru and Hyderabad, creating recruitment bottlenecks for tier-two manufacturers.
- Dealer network retraining costs:Legacy two-wheeler service technicians require certification in high-voltage safety protocols and diagnostic equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India E-Bike Market |
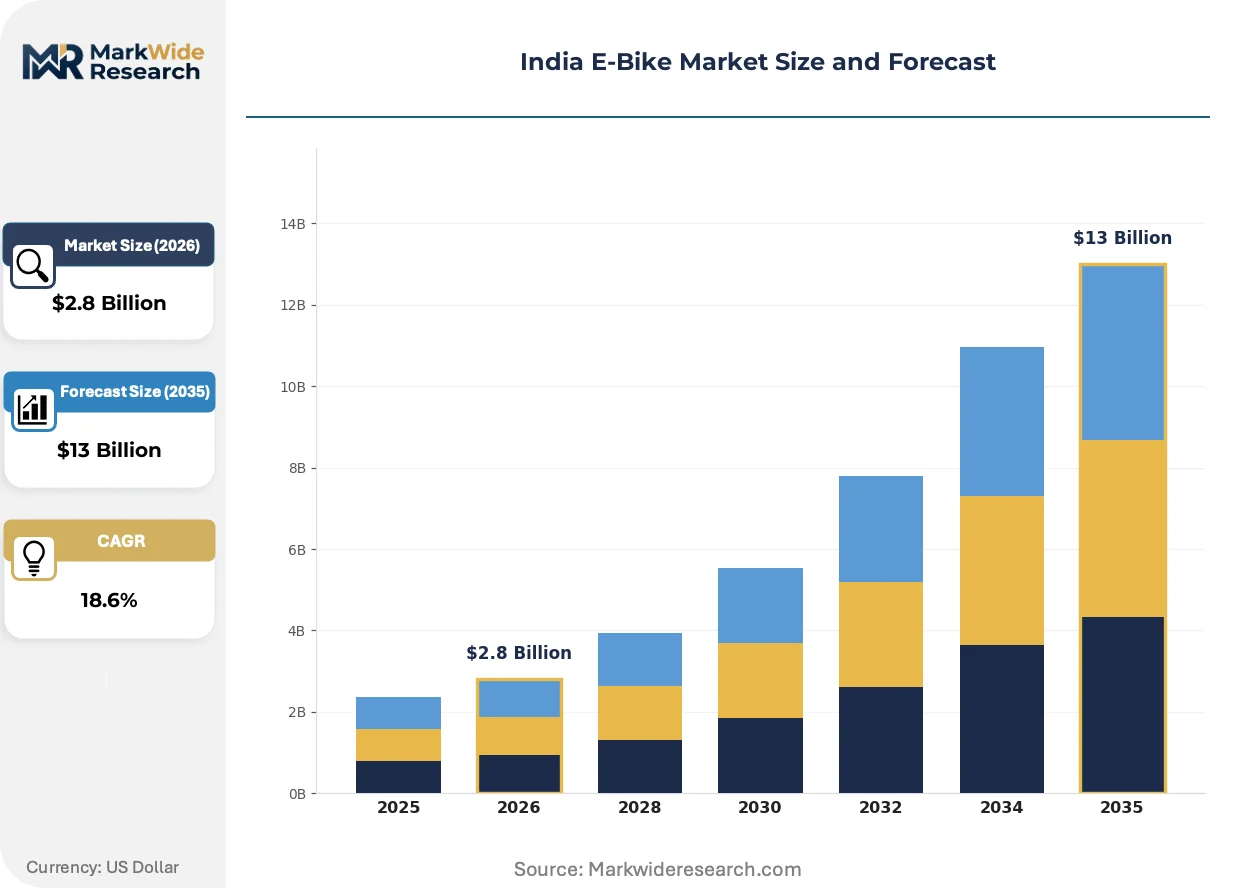
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedal-Assist, Throttle-Controlled, Folding, Mountain Battery Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Lithium Polymer Range: Up to 30 km, 31-60 km, 61-90 km, Above 90 km End User: Urban Commuters, Delivery Services, Recreational Users, Seniors |
| Companies Covered | Hero Electric, Ola Electric, EMotorad, Hero Cycles Limited, TVS Motor, Bajaj Auto, Alphavector, Voltebyk, Motovolt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India E-Bike Market Strategic Shifts
Connected vehicle architectures and telematics integration are redefining how fleet operators manage asset utilization, while regulatory pressure on battery chemistry safety accelerates technical substitution cycles.
Lithium-iron-phosphate cell chemistry is overtaking nickel-manganese-cobalt alternatives in commercial fleet applications due to superior thermal stability and cycle life. Delivery operators in Mumbai and Delhi specify this chemistry for twelve-hour shift duty cycles. The technology is overtaking premium cobalt-dependent packs in total cost of ownership calculations despite higher upfront cell costs.
BIS updates to EV battery standards are mandating nail-penetration testing and thermal runaway propagation containment for all certified packs. This regulatory tightening disqualifies uncertified imported battery modules from subsidy eligibility. Tamil Nadu and Maharashtra transport departments are responding by requiring dealer-level verification of BIS compliance documentation before registration.
Fleet procurement teams now specify outcome-based total cost per kilometer contracts rather than upfront vehicle purchase. Leasing providers absorb battery degradation risk and guarantee uptime thresholds. This shift is most visible in Bengaluru's last-mile logistics sector where operators prioritize operational expenditure predictability over capital ownership.
India E-Bike Market Segmentation
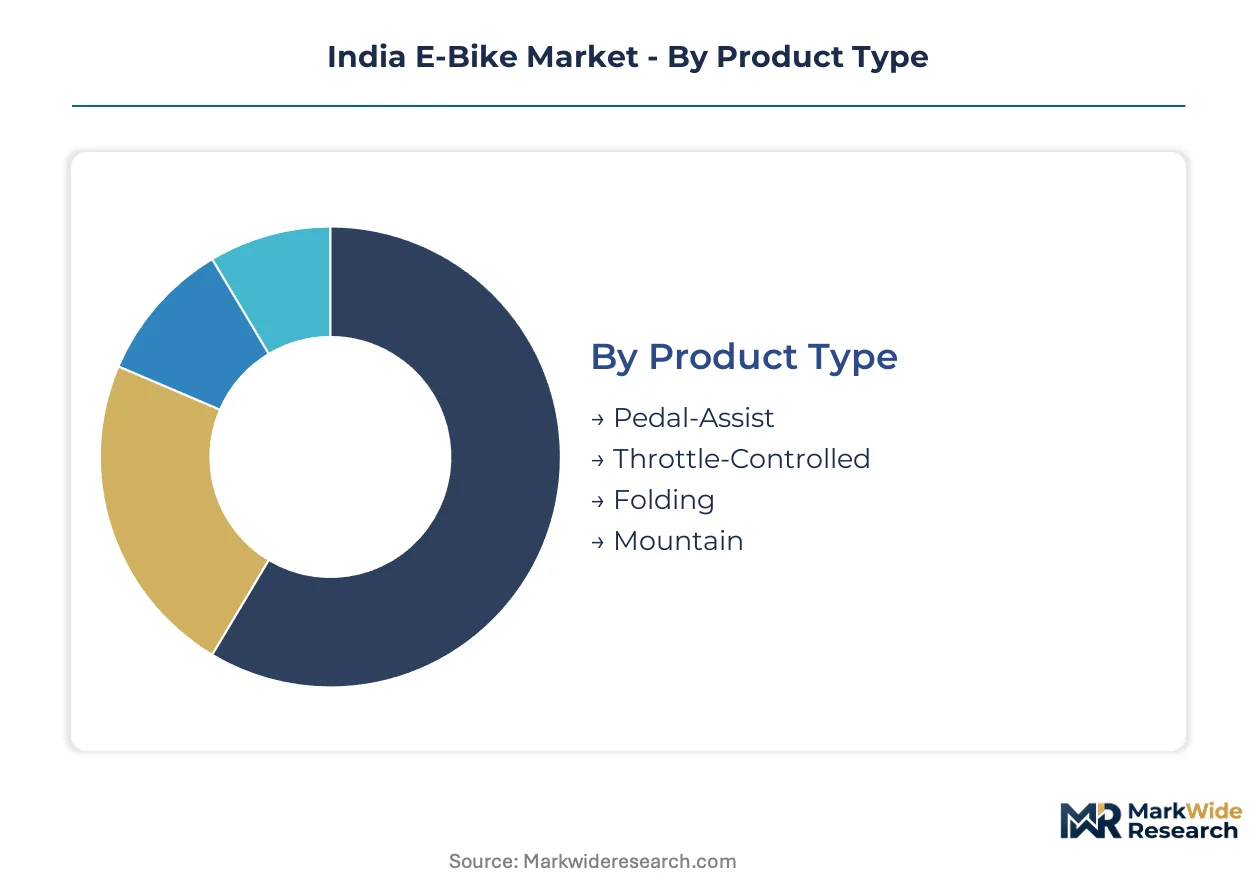
India's e-bike market fragments along battery chemistry, propulsion architecture, and duty-cycle requirements. Each segmentation axis carries distinct margin profiles and regulatory implications that determine manufacturer positioning.
Product Type:
Propulsion architecture defines the regulatory pathway and consumer interaction model across Indian states.
- Pedal-Assist:Motor engagement triggers only during pedaling, capping assisted speed at 25 km/h per Central Motor Vehicle Rules. Maharashtra and Karnataka transport departments exempt these from registration, accelerating consumer uptake in Bengaluru and Mumbai metro corridors.
- Throttle-Controlled:Twist-grip or thumb-activated motor engagement without pedaling. Demand concentrates in tier-three towns where consumers treat e-bikes as scooter replacements; heavier regulatory scrutiny in Delhi limits deployment.
- Folding:Collapsible frame designs with 16-inch wheels for multimodal transit integration. Mumbai suburban rail commuters and Hyderabad metro riders drive procurement for first-last connectivity.
- Mountain:Reinforced suspension and knobby tire configurations for unpaved terrain. EMotorad and similar specialists target the Western Ghats adventure tourism circuit and rural Himachal Pradesh.
Mature deployment sits with Pedal-Assist. Newer deployment is concentrated in Mountain variants.
Battery Type:
Chemistry selection governs total cost of ownership, subsidy eligibility, and thermal safety compliance under evolving BIS standards.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants dominate fleet procurement. FAME II subsidies apply exclusively to BIS-certified lithium packs; Tamil Nadu and Maharashtra commercial operators specify lithium-iron-phosphate for twelve-hour shift cycles due to superior thermal stability.
- Lead-Acid:Flooded and sealed lead-acid batteries retain 40-45% unit share in rural Rajasthan, Uttar Pradesh, and Bihar. Price points below 35,000 rupees sustain volume, though BIS certification timelines and weight penalties constrain margin expansion.
- Nickel-Cadmium:Obsolete chemistry with cadmium toxicity concerns. Limited to legacy fleet retrofits and replacement cycles in legacy municipal e-bike programs; no new model launches incorporate this technology.
- Lithium Polymer:Pouch-cell configurations enabling non-rectangular battery geometries. Premium urban designs in Delhi and Pune exploit form-factor flexibility for frame integration, though cost premiums limit penetration beyond 75,000 rupee price points.
Established chemistry deployment sits with Lead-Acid. Newer deployment is concentrated in Lithium-Ion variants.
Range:
Range specification determines addressable use case and charging infrastructure dependency across India's urban density gradient.
- Up to 30 km:Single-charge radius sufficient for intra-neighborhood errands and short commutes. Tier-two city housewives and elderly riders in Coimbatore and Madurai prioritize low upfront cost over range redundancy.
- 31-60 km:Standard commuter specification covering 90% of Indian urban trip distances. Hero Electric and similar volume manufacturers anchor portfolios here; replacement cycle economics favor this band for price-sensitive salaried workers.
- 61-90 km:Intercity-capable specification requiring overnight charging. Pune-Nashik and Chennai-Tirupati corridor commuters drive demand; battery weight penalties begin affecting ride quality.
- Above 90 km:Dual-battery or high-capacity single-pack configurations for commercial fleet duty. Swiggy, Zomato, and Amazon last-mile contractors in Bengaluru specify this range band to complete twelve-hour shifts without midday charging; margin pools concentrate here.
Mature deployment sits with 31-60 km. Newer deployment is concentrated in Above 90 km variants.
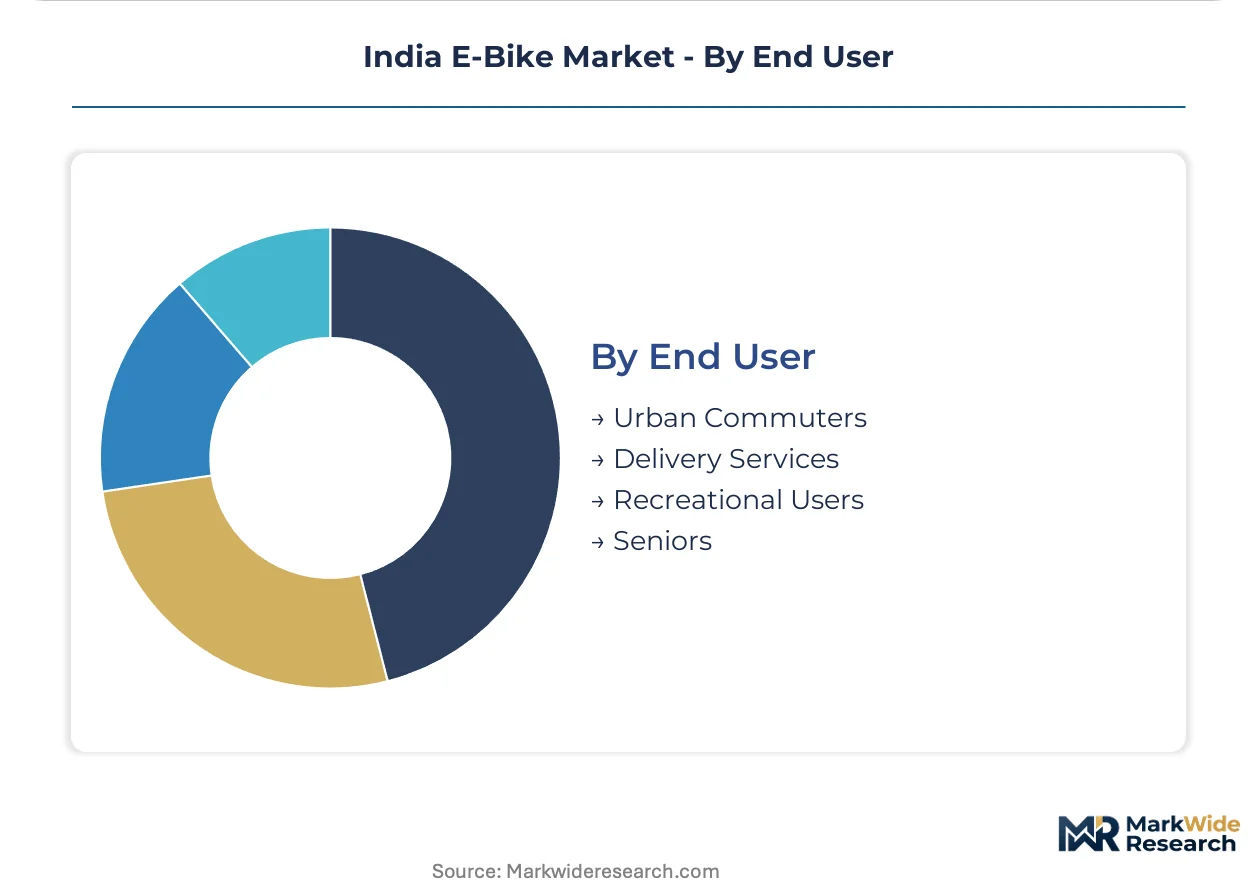
End User:
Customer archetype segmentation aligns product specification with trip purpose and purchasing authority structure.
- Urban Commuters:Salaried professionals replacing public transit or petrol two-wheelers for 10-25 km daily trips. Mumbai and Delhi metro catchment areas show highest conversion rates; financing penetration exceeds 60% in this cohort.
- Delivery Services:Fleet-operated or gig-economy rider-owned assets for commercial package and food delivery. Municipal clean-air mandates in Bengaluru and Mumbai accelerate electrification timelines; total-cost-per-kilometer contracting is displacing upfront purchase.
- Recreational Users:Weekend leisure riders and fitness enthusiasts in hill stations and coastal circuits. Kerala backwaters and Lonavala weekend markets sustain niche premium pricing.
- Seniors:Riders over 55 seeking mobility independence with physical effort reduction. Chennai and Hyderabad retirement communities drive demand for step-through frames and low seat heights.
Mature deployment sits with Urban Commuters. Newer deployment is concentrated in Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's Electronic City corridor anchors India's e-bike production ecosystem, with component suppliers and battery pack assemblers clustering within 50 kilometers of the Karnataka capital. This concentration shapes procurement patterns for western and southern markets.
Maharashtra
Mumbai's last-mile delivery fleets drive commercial procurement volumes as Swiggy and Zomato contractors electrify twelve-hour shift operations. The state transport department enforces road-tax waivers and registration exemptions for pedal-assist vehicles under 25 km/h. Pune-Nashik manufacturing corridors host Hero Electric assembly plants serving the Mumbai-Pune industrial belt.
Karnataka
Bengaluru's software engineering talent pool enables connected-vehicle firmware development for telematics integration. BIS certification timelines compress for manufacturers locating testing facilities near the Electronics City cluster. Hubli-Dharwad tier-two markets sustain lead-acid volume distribution through rural dealer networks.
Tamil Nadu
Chennai-Ambattur industrial zones offer port access for lithium cell imports and electronics component sourcing. The state's commercial fleet operators specify lithium-iron-phosphate chemistry for thermal stability in twelve-hour delivery cycles. Coimbatore and Madurai housewives drive pedal-assist demand for intra-neighborhood errands.
Delhi-NCR
Municipal clean-air mandates accelerate fleet electrification timelines for last-mile logistics operators. The transport department enforces stricter registration requirements for throttle-controlled variants, limiting scooter-replacement demand. Gurugram and Faridabad warehousing clusters generate bulk procurement for intercity delivery contractors.
Gujarat
Surat and Ahmedabad textile industry workers convert to 31-60 km range commuter specifications for factory commutes. State-level EV policies extend subsidy eligibility to commercial fleet registrations beyond FAME II horizons. Vadodara engineering institutes supply power electronics talent for motor controller development.
India E-Bike Market Competitive Environment
Premium-margin players sit above commodity-margin players across battery chemistry and connected-feature dimensions. Hero Electric and Ola Electric occupy the lithium-ion tier with FAME II subsidy eligibility, while lead-acid specialists defend volume in rural Rajasthan and Uttar Pradesh. Three archetypes define competitive positioning: legacy two-wheeler OEMs with dealer networks, direct-to-consumer digital natives with in-house cell manufacturing, and rugged-design specialists targeting adventure niches. Capacity expansion and backward integration into battery pack assembly represent the dominant competitive moves.
Within the legacy OEM tier, Hero Electric leverages its nationwide service infrastructure to sustain volume leadership in tier-two cities. Ola Electric anchors the direct-to-consumer vector through captive cell manufacturing and app-based sales channels. EMotorad occupies the adventure-specialist position with long-range designs for Western Ghats terrain. These three exemplify how capital allocation diverges between network density, manufacturing integration, and niche product development.
| Leading Market Players |
|---|
| Hero Electric |
| Ola Electric |
| EMotorad |
| Hero Cycles Limited |
| TVS Motor |
| Bajaj Auto |
| Alphavector |
| Voltebyk |
| Motovolt |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion premiumization against lead-acid commoditization defines India's e-bike pricing architecture, with FAME II subsidy eligibility and BIS certification status determining which tier manufacturers occupy and where they source battery packs. This bifurcation concentrates margin capture in Tamil Nadu and Maharashtra assembly plants for certified lithium variants while locking rural distributors into heavier, shorter-lifecycle lead-acid inventory from Uttar Pradesh and Rajasthan.
Pricing Analysis
Outcome-based total cost per kilometer contracting now anchors fleet procurement decisions in Bengaluru and Mumbai, with Swiggy and Zomato operators prioritizing operational expenditure predictability over upfront vehicle ownership. Price differentiation rests on battery chemistry certification tier and connected telematics bundling, with BIS-certified lithium-iron-phosphate packs commanding premiums for twelve-hour shift duty cycles. Cost compression in lead-acid tiers is intensifying because subsidy ineligibility and weight penalties erode competitiveness against internal-combustion alternatives. Delivery fleet operators show least price sensitivity due to uptime guarantees, while tier-three rural households exhibit highest sensitivity to upfront purchase thresholds.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for advanced chemistry cell manufacturing are reshaping sourcing patterns, pressuring assemblers to substitute imported nickel-manganese-cobalt cells with locally produced lithium-iron-phosphate alternatives. Manufacturing gravity centers on China, South Korea, and Japan for cell production, with India concentrating in pack assembly and controller firmware development. Raw material dependencies span lithium carbonate, graphite anodes, and rare-earth permanent magnets for hub motors. Single-source vulnerability concentrates in electrolyte supply from Chinese specialty chemical producers. Distribution runs through state-level dealer networks for consumer sales and direct fleet contracting for commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's e-bike market sits in a technology-transition phase where lithium-iron-phosphate chemistry is systematically displacing lead-acid and nickel-manganese-cobalt alternatives across commercial applications. This substitution wave rewards manufacturers with backward integration into cell assembly and certified pack testing capabilities.
For Market Incumbents: Extend service network density in tier-two cities to defend against direct-to-consumer digital entrants, while accelerating in-house lithium cell production to reduce exposure to imported battery cost volatility. Hero Electric's nationwide technician infrastructure represents a defensible moat against Ola Electric's app-based sales model. Priority investment in BIS pre-certification testing facilities compresses new model launch timelines against regulatory tightening.
For New Entrants and Emerging Players: Capture the adventure and rural mobility niche where EMotorad has demonstrated pricing power for rugged, long-range designs targeting Western Ghats terrain and Himachal Pradesh unpaved circuits. This segment remains underserved by urban-focused mainstream portfolios. Go-to-market execution through regional outdoor recreation retailers and trekking operator partnerships bypasses entrenched two-wheeler dealer networks.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated cell manufacturers given FAME II extension debates and state-level commercial fleet incentive programs. Long-term viability in the five-to-ten year window hinges on domestic battery chemistry scale and controller firmware talent retention in Bengaluru and Hyderabad. The signal to watch is Tamil Nadu transport department adoption of lithium-iron-phosphate mandates for twelve-hour delivery shift licensing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Ola Electric's captive battery plant secures FAME II subsidy eligibility and insulates margin from imported cell price swings. |
| Direct-to-Consumer Digital Channel Launch | App-based configuration and home delivery bypass traditional dealer margin stacking in Maharashtra and Karnataka urban corridors. |
| BIS Certification Pre-Investment | Early testing facility deployment near Electronics City compresses new model approval timelines against regulatory tightening. |
| Fleet Outcome-Based Contracting | Leasing providers absorbing battery degradation risk align pricing with Swiggy and Zomato uptime requirements. |
| Adventure Niche Product Development | Long-range rugged designs for Western Ghats terrain capture underserved premium pricing outside urban commuter saturation. |
Study Parameters
Ministry of Heavy Industries FAME II disbursement records, state transport department registration databases, and BIS certification filings formed the secondary backbone for this analysis. Primary interviews with e-bike fleet procurement managers at Bengaluru logistics operators, lithium cell assembly plant engineers in Tamil Nadu, dealer network operators in tier-two Karnataka markets, and power electronics firmware developers in Hyderabad validated demand assumptions. Top-down market sizing from macro vehicle electrification targets and bottom-up triangulation from manufacturer production disclosures were reconciled across the analysis window.
Historical trendline analysis of lithium cell cost curves and lead-acid price elasticity informed the projection framework. Segmentation dimensions modeled span battery chemistry tier, propulsion architecture, range specification, and end-user archetype, with regional state-level policy variation treated as a cross-cutting modifier. CAGRs were derived from fitted adoption curves against municipal clean-air mandate timelines and subsidy program horizons. Forecast inputs incorporated charging infrastructure rollout pace in tier-three cities and BIS standard revision schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FAME II extension decisions and lithium raw material import tariff trajectories. Forecasts reflect documented assumptions on subsidy continuity and cell cost reduction slopes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Oman EV Market