
 Recreational Vehicle (RV) Batteries Market | 2026-2036
Recreational Vehicle (RV) Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Vehicle (RV) Batteries Market Analytics
Deep-cycle lithium-ion specifications with 200 Ah capacity and integrated battery management systems is redrawing competitive benchmarks across the RV power storage sector. Battle Born Batteries leverages domestic cell assembly and vertical assembly control to sustain premium positioning in the North American aftermarket. Trojan Battery anchors its franchise through decades of brand equity in flooded lead-acid designs for price-sensitive fleet operators. Dragonfly Energy differentiates through proprietary lithium iron phosphate cell architecture purpose-built for mobile off-grid applications.
Recreational vehicle batteries constitute electrochemical storage systems engineered for cyclic discharge-recharge regimes, typically delivering 12V DC output through configurations ranging from 100 Ah to 300 Ah capacity ratings, with lithium-ion variants achieving 3,000–5,000 cycle lifetimes versus 400–600 cycles for conventional flooded lead-acid alternatives. Their primary commercial purpose centers on sustaining auxiliary loads—lighting, climate control, refrigeration, and inverter-driven appliances—in motorized and towable recreational vehicles disconnected from shore power infrastructure. The battery type dimension shows lithium-ion chemistry capturing the fastest expansion trajectory while lead-acid retains volume dominance in entry-level towable units where upfront cost sensitivity governs procurement decisions. Application segmentation reveals boondocking and off-grid deployment as the margin-rich growth frontier, with camping and marine tours representing mature, replacement-driven revenue pools.
EPA tailpipe emissions standards and NHTSA Federal Motor Vehicle Safety Standards govern OEM battery integration requirements in the United States, while UN 38.3 lithium transport regulations and UL 1973 stationary battery safety certifications constrain cross-border product movement and market access protocols. The regulatory architecture increasingly mandates thermal runaway propagation resistance and crashworthiness validation, elevating compliance costs for smaller suppliers lacking in-house testing infrastructure. Stakeholders must monitor evolving DOT hazardous materials classification debates and state-level zero-emission camping mandates that could reclassify auxiliary power systems as regulated vehicle components rather than aftermarket accessories.
Market Dynamics
Lithium-ion chemistry is displacing legacy lead-acid systems across off-grid RV applications, rewriting competitive benchmarks around cycle life, weight reduction, and thermal management requirements. This electrochemical transition concentrates margin capture among cell manufacturers with vertical assembly control while compressing pricing power for flooded lead-acid incumbents.
Growth Catalysts
- Boondocking Infrastructure Expansion:Dispersed camping access across the United States, particularly Bureau of Land Management territories and national forest service roads, sustains demand for deep-cycle power storage independent of shore hookups.
- NHTSA Safety Integration Mandates:Federal Motor Vehicle Safety Standards now require crash-tested battery containment systems, accelerating OEM adoption of certified lithium-ion banks over aftermarket lead-acid retrofits in motorized chassis.
- Cell Chemistry Advancement:Lithium iron phosphate formulations achieve 3,000–5,000 cycle lifetimes, eliminating the replacement frequency that burdened RV owners under legacy flooded lead-acid regimes.
Market Restraints
- Cobalt and Lithium Carbonate Volatility:Raw material input costs for cathode active materials fluctuate with electric vehicle battery demand, compressing gross margins for RV-specific pack assemblers lacking long-term offtake agreements.
- UN 38.3 Transport Classification:Lithium battery hazardous materials designation imposes documentation, packaging, and carrier restrictions that inflate logistics costs and limit cross-border distribution flexibility.
- Lead-Acid Price Anchoring:Entry-level towable RV manufacturers continue specifying flooded lead-acid for cost-sensitive fleet procurement, delaying premium chemistry penetration in the highest-volume sales channel.
Strategic Opportunities
- State-Level Zero-Emission Camping Mandates:California and Oregon regulatory frameworks are beginning to classify auxiliary power systems as regulated vehicle components, creating compliance-driven replacement cycles for legacy installations.
- Integrated Solar-Battery Convergence:MPPT charge controllers paired with lithium storage architectures enable all-in-one power management systems that capture margin from panel, controller, and battery categories simultaneously.
- RV Rental Fleet Electrification:Peer-to-peer rental platforms and commercial fleet operators represent an underpenetrated channel where standardized lithium specifications reduce maintenance liability and improve asset utilization rates.
Industry Challenges
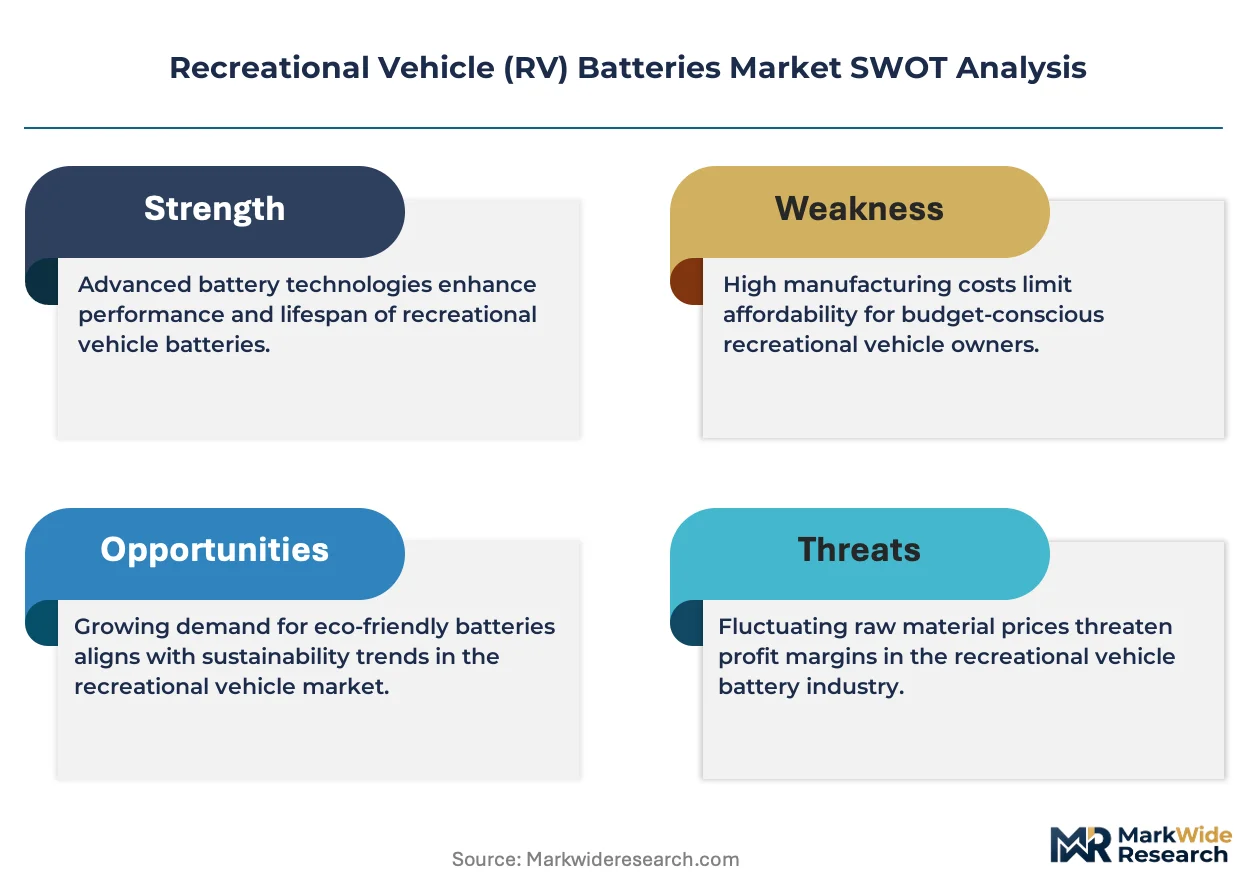
- Thermal Runaway Testing Infrastructure:UL 1973 certification requires propagation resistance validation that demands capital-intensive abuse testing chambers beyond the reach of mid-tier pack assemblers.
- Legacy 12V System Integration:Existing RV electrical architectures designed for lead-acid charging profiles require converter upgrades or battery management system reprogramming, complicating retrofit sales cycles and installation reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Vehicle (RV) Batteries Market |
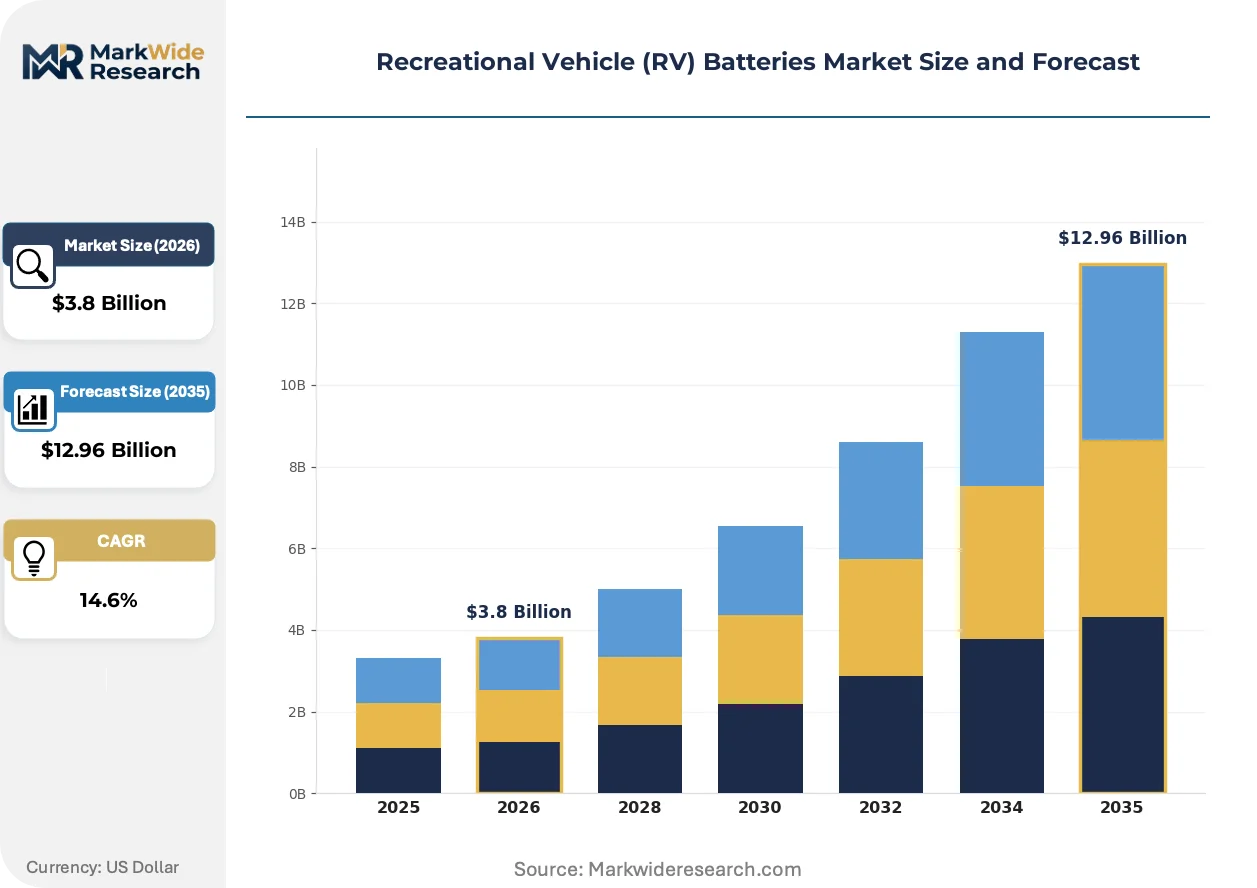
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium Ion, AGM, Gel Cell Application: Camping, Boondocking, Off-Grid, Marine Tours Capacity: 200 Ah, 100 Ah, 300 Ah, 150 Ah Installation Type: OEM, Aftermarket, Portable, Fixed |
| Companies Covered | East Penn Manufacturing, Exide Technologies, EnerSys, Johnson Controls, Interstate Batteries, Trojan Battery, Battle Born Batteries, Renogy, Dragonfly Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Vehicle (RV) Batteries Market Evolving Landscape
Electrochemical storage architectures, regulatory safety mandates, and buyer procurement patterns are converging to reshape how power systems are specified, distributed, and serviced across the recreational vehicle sector.
Prismatic lithium iron phosphate cells with integrated battery management systems are displacing absorbed glass mat and flooded lead-acid configurations in premium motorized and towable segments. Off-grid boondocking enthusiasts are adopting these systems fastest, driven by weight reduction imperatives and extended dry-camping autonomy requirements. The structural consequence is a bifurcation in supplier economics: cell-integrated manufacturers capture value previously distributed across separate battery, charger, and monitoring suppliers.
EPA tailpipe emissions standards and NHTSA crashworthiness protocols are tightening auxiliary power system integration requirements for OEM chassis manufacturers. These rules now mandate thermal runaway containment and structural battery protection validation before factory installation approval. Motorized Class A and Class C manufacturers face the steepest compliance burden, driving consolidation toward Tier 1 suppliers with in-house testing and homologation capabilities.
Direct-to-consumer channel expansion is compressing traditional RV dealer parts counter dominance in battery replacement cycles. E-commerce platforms and manufacturer-owned websites now capture an expanding share of lithium upgrade sales, particularly among technically proficient owner-operators performing self-installation. This pattern concentrates most visibly in the United States, where dispersed geography and established parcel freight infrastructure support remote technical support and warranty fulfillment models.
Recreational Vehicle (RV) Batteries Market Segmentation
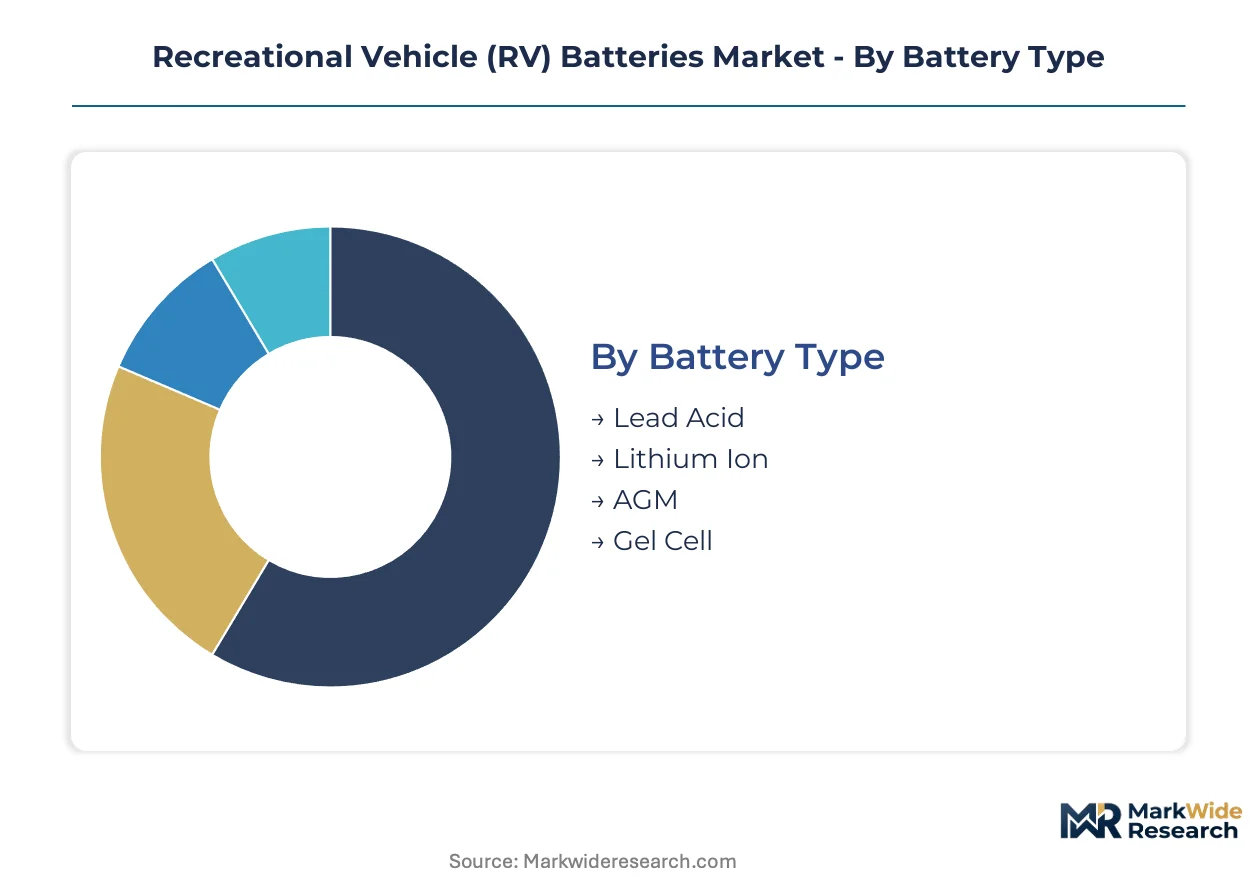
RV battery procurement splits sharply between domestic fleet specifications and export-driven premium aftermarket demand. Electrochemical chemistry, installation channel, and capacity tier determine margin capture and regulatory exposure for suppliers.
Battery Type:
Lead-acid variants dominate North American fleet procurement through established dealer networks. Lithium-ion chemistries flow disproportionately to export markets and direct-to-consumer channels where weight and cycle life command premium positioning.
- Lithium Ion:Lithium iron phosphate cells with integrated battery management systems deliver 3,000–5,000 cycle lifetimes. Demand concentrates in off-grid boondocking applications across Bureau of Land Management territories, driven by weight reduction imperatives for extended dry-camping autonomy.
- Lead Acid:Flooded and absorbed glass mat configurations retain volume dominance in entry-level towable units. Fleet operators in price-sensitive procurement channels specify these for replacement cycles in established camping infrastructure.
- AGM:Valve-regulated lead-acid with fiberglass mat separators offers maintenance-free operation for marine tour operators.
- Gel Cell:Silica-thickened electrolyte designs serve vibration-intensive motorized chassis applications.
Lead-acid commands the established base. The steepest expansion runs through lithium-ion.
Application:
Cost tier differentiation separates replacement-driven camping from premium off-grid deployment. Marine tours and boondocking represent opposite ends of the price-performance spectrum.
- Boondocking:Dispersed camping without shore power infrastructure demands deep-cycle storage with 200+ Ah capacity and rapid solar recharge compatibility. Western United States public lands access sustains pull for lithium specifications with 5,000-cycle durability.
- Camping:Established campground hookup availability supports conventional lead-acid replacement cycles. Seasonal RV owners in developed park infrastructure prioritize upfront cost over cycle life metrics.
- Off-Grid:Permanent residential and remote cabin installations require thermal stability across temperature extremes.
- Marine Tours:Saltwater corrosion resistance and vibration tolerance govern specification requirements.
Camping anchors volume throughput. Boondocking captures margin expansion fastest.
Capacity:
Volume concentration sits at 100 Ah for entry towables. Premium motorized segments scale toward 300 Ah for all-electric appliance loads.
- 200 Ah:The emerging standard for lithium retrofit kits enables 24–48 hour autonomy without generator support. Class A and Class C motorized chassis in the United States specify this tier for inverter-driven air conditioning and residential refrigerator loads.
- 100 Ah:Entry-level towable OEM specifications favor this capacity for lighting and basic 12V loads. Travel trailer and fifth-wheel fleet procurement in cost-sensitive channels sustains lead-acid dominance at this tier.
- 300 Ah:Residential-grade power systems for luxury motorized coaches.
- 150 Ah:Mid-range towable and truck camper applications.
100 Ah retains the highest unit volumes. 200 Ah scales fastest through lithium conversion cycles.
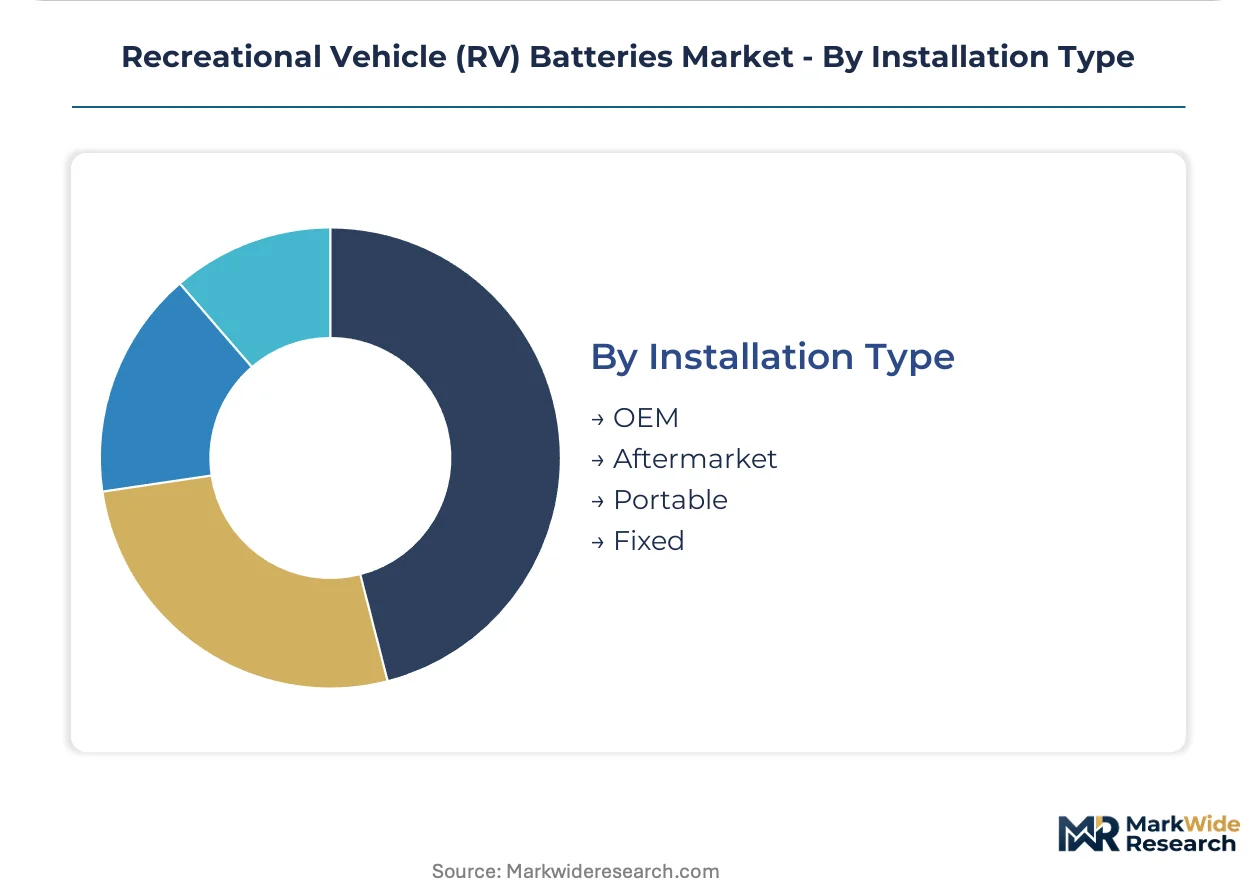
Installation Type:
Customer type bifurcation separates OEM fleet standardization from aftermarket owner-operator customization. Channel economics favor integrated suppliers differently across each tier.
- OEM:Factory installation mandates NHTSA crashworthiness certification and UL 1973 thermal runaway validation. Motorized chassis manufacturers in the United States consolidate procurement toward Tier 1 suppliers with in-house homologation capabilities.
- Aftermarket:Direct-to-consumer lithium upgrade sales bypass traditional dealer parts counters. E-commerce platforms capture technical owner-operators performing self-installation with remote warranty support.
- Portable:External power stations for tent camping and auxiliary use cases.
- Fixed:Permanent battery bay integration in custom van builds and skoolie conversions.
OEM locks in fleet standardization. Aftermarket captures the steepest lithium conversion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell assembly and pack integration concentrate heavily in the United States, where dispersed camping infrastructure and federal land access sustain the deepest aftermarket demand. Manufacturers with domestic testing capabilities capture OEM certification requirements that foreign competitors struggle to meet.
United States
Bureau of Land Management territory expansion and national forest road access fuel boondocking demand across the Western states. NHTSA Federal Motor Vehicle Safety Standards mandate crash-tested battery containment for factory installations. Elkhart, Indiana anchors RV manufacturing concentration, drawing Tier 1 battery suppliers with homologation laboratories to northern Indiana.
Germany
Caravan and motorhome touring culture sustains replacement cycles for deep-cycle storage across Central European campground networks. KBA vehicle type approval requirements govern auxiliary power system integration for OEM chassis. Baden-Württemberg industrial clusters host precision electronics manufacturers supplying battery management systems to European RV converters.
China
Domestic RV rental fleet growth and camper van conversion trends drive lithium cell demand through Guangdong and Jiangsu manufacturing bases. MIIT new energy vehicle regulations increasingly influence auxiliary power system safety standards for motorized chassis. Shenzhen and Dongguan concentrate prismatic cell production for export-oriented pack assemblers serving North American aftermarket channels.
Australia
Remote outback touring and caravanning culture generates premium demand for high-capacity off-grid power systems. The country's national electrical safety regulator enforces stringent installation standards for lithium battery retrofits in recreational vehicles. Melbourne and Brisbane host specialized distributors serving the grey nomad demographic with solar-battery integration packages.
Canada
Seasonal camping patterns and provincial park infrastructure sustain steady replacement demand across the Prairie and Ontario corridor. Transport Canada motor vehicle safety standards align with US NHTSA protocols, simplifying cross-border product certification. Ontario's manufacturing belt supplies lead-acid batteries for entry-level towable units while Vancouver-area importers handle premium lithium distribution.
Recreational Vehicle (RV) Batteries Market Competitive Landscape
Concentration sits with vertically integrated cell manufacturers and established lead-acid incumbents defending replacement cycles. The supplier base splits between chemistry specialists controlling upstream cell production and legacy brands anchored in dealer service networks. Three archetypes dominate: domestic lithium cell assemblers with captive BMS development, flooded lead-acid manufacturers serving fleet procurement, and energy storage generalists diversifying into mobile applications. Competitive moves center on thermal runaway certification investments and direct-to-consumer channel bypass of traditional dealer counters.
Among North American specialists, Battle Born Batteries and Dragonfly Energy exemplify the integrated lithium archetype with domestic cell assembly capabilities. Trojan Battery anchors the legacy lead-acid position through decades of brand equity in deep-cycle applications. East Penn Manufacturing and Exide Technologies represent diversified industrial battery producers with RV as a vertical segment. EnerSys and Johnson Controls occupy positions spanning motive power and reserve capacity markets with technology portfolios extending into lithium chemistries.
| Leading Market Players |
|---|
| East Penn Manufacturing |
| Exide Technologies |
| EnerSys |
| Johnson Controls |
| Interstate Batteries |
| Trojan Battery |
| Battle Born Batteries |
| Renogy |
| Dragonfly Energy |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day cathode active material lead times from Chinese cell manufacturers concentrate pricing power among vertically integrated pack assemblers with captive lithium iron phosphate supply, while compressing margins for aftermarket distributors dependent on spot market procurement. This inventory compression dynamic intensifies during electric vehicle battery demand surges that divert cell capacity away from RV-specific form factors.
Pricing Analysis
UL 1973 thermal runaway certification dictates the pricing tier structure across the RV battery sector, separating premium lithium iron phosphate banks with integrated battery management systems from uncertified import alternatives and legacy flooded lead-acid replacements. Pricing stratifies across certified premium, compliant standard, and uncertified economy tiers based on cycle life guarantees and NHTSA crashworthiness validation. Cost compression in the lead-acid replacement tier is intensifying because fleet operators prioritize upfront acquisition cost over total cost of ownership metrics. Entry-level towable RV manufacturers exhibit the highest price sensitivity, while off-grid boondocking enthusiasts demonstrate minimal elasticity for weight-reduced lithium specifications.
Supply Chain Analysis
China and South Korea anchor prismatic lithium iron phosphate cell production for the RV battery sector, with domestic US pack integration concentrating in northern Indiana and Nevada manufacturing corridors. The supply chain draws from Australian spodumene concentrate and Chilean lithium carbonate for cathode precursors, while separator membranes and electrolyte salts source primarily from Japanese chemical specialists. Single-source vulnerability in cathode active material procurement exposes RV pack assemblers to electric vehicle sector demand spikes that redirect cell allocation. Distribution runs through direct-to-consumer e-commerce platforms and OEM Tier 1 procurement channels, bypassing traditional dealer parts counters for lithium upgrade cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RV battery sector is entering a cyclical upswing driven by replacement demand from aging lead-acid installed base and federal land access expansion sustaining boondocking participation rates.
For Market Incumbents: Consolidate testing infrastructure investments around UL 1973 propagation resistance certification and NHTSA crashworthiness validation to defend OEM chassis procurement against emerging Chinese cell manufacturers lacking domestic homologation capabilities. Acquire captive lithium carbonate offtake agreements to secure cathode supply against electric vehicle sector demand surges. Channel control through exclusive dealer service network agreements protects replacement cycle capture against direct-to-consumer lithium specialists. For New Entrants and Emerging Players: Remote technical support and warranty fulfillment capabilities represent the most pronounced service-layer gap where established incumbents under-serve self-installing owner-operators in dispersed western US geographies. Target peer-to-peer RV rental fleet operators in California and Texas with standardized lithium specifications that reduce maintenance liability and improve asset utilization. Deploy subscription-based battery health monitoring as the primary go-to-market angle to establish recurring revenue relationships before hardware commoditization accelerates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across UL-certified pack assembly as thermal runaway testing infrastructure requirements exclude mid-tier competitors from OEM qualification pools. The five-to-ten-year viability window favors acquisition targets with domestic cell assembly capabilities and captive battery management system firmware development rather than pure import distributors. Monitor California Air Resources Board zero-emission camping mandate progression as the critical regulatory signal indicating compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| UL 1973 Certification Investment | Unlocks OEM factory installation approval from NHTSA-regulated chassis manufacturers. |
| Direct-to-Consumer Channel Buildout | Captures margin from self-installing boondocking enthusiasts bypassing dealer counters. |
| Cathode Active Material Offtake Agreement | Secures lithium carbonate supply against EV sector demand volatility. |
| Integrated Solar-Battery System Development | Captures simultaneous margin from MPPT controllers, panels, and storage architectures. |
| Rental Fleet Standardization Partnership | Reduces maintenance liability for peer-to-peer platforms through lithium specification uniformity. |
Research Methodology
Operator-level perspectives from RV dealership service managers, OEM chassis procurement directors, lithium cell manufacturing executives, and Bureau of Land Management recreation planners anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary validation from NHTSA Federal Motor Vehicle Safety Standard filings, EPA emissions compliance databases, UN 38.3 lithium transport classification records, and US Forest Service dispersed camping access statistics. Bottom-up unit shipment estimates across battery chemistry, capacity tier, and installation channel converged with top-down value projections derived from cathode active material cost curves.
Sensitivity analysis across raw material price volatility scenarios and regulatory mandate timing variations informed the projection framework. The analytical model segmented volume and value outputs by electrochemical chemistry, application intensity, capacity rating, and installation channel across the analysis window. CAGRs were derived from regression-weighted historical replacement cycles and forward-projected boondocking participation elasticity. Forecast inputs incorporated lithium carbonate spot price trajectories and NHTSA safety standard adoption curves for motorized chassis integration.
Forecasts assume regulatory continuity in EPA tailpipe emissions standards and NHTSA Federal Motor Vehicle Safety Standards; material policy shifts would require re-modeling. Specific risk factors include UN 38.3 transport classification revisions, state-level zero-emission camping mandate acceleration, and cobalt-lithium carbonate demand correlation with electric vehicle sector expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Electric Axle Drive Systems Market