
 China Electric Vehicle Market | 2026-2036
China Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Market Intelligence
Software-defined vehicle features, including autonomous driving subscriptions and over-the-air updates, are shifting the core value proposition beyond hardware performance. BYD Co. Ltd. leverages its extensive vertical integration into battery production to control costs and achieve immense manufacturing scale. NIO Ltd. differentiates its brand with a unique battery-as-a-service model and premium user services. XPeng Inc. competes aggressively on the capabilities of its advanced driver-assistance systems and in-car intelligence.
An electric vehicle in China is a road vehicle powered by electric motors using energy from rechargeable battery packs, often featuring high-density lithium iron phosphate (LFP) chemistry for mass-market models. Its primary purpose is to advance national energy security by reducing oil import dependency and to help meet the MEE's stringent air quality targets. Battery Electric Vehicles represent the fastest-growing product type, significantly outpacing Plug-in Hybrid Electric Vehicles. In terms of application, strong demand from individual buyers for private commuting and from ride-hailing companies forms the market's foundation.
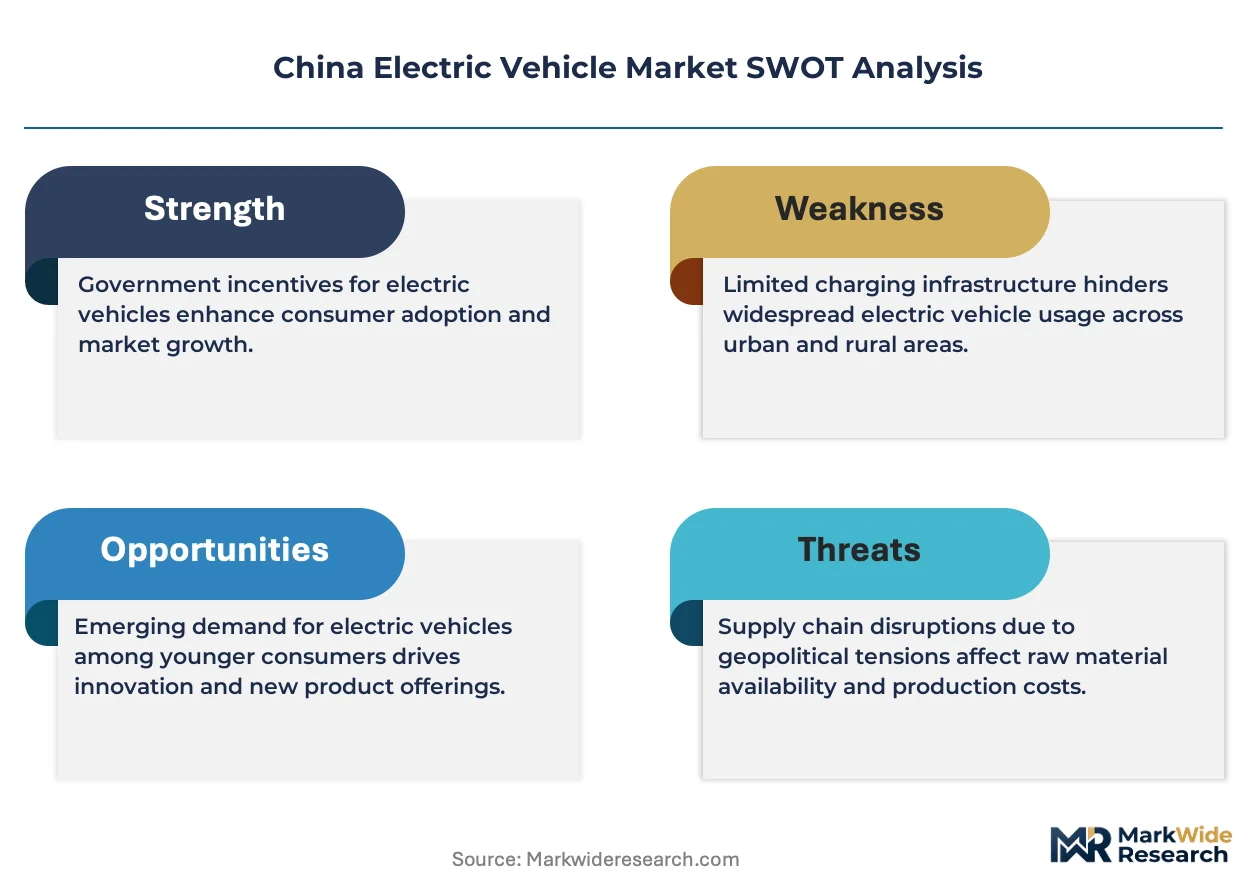
The Ministry of Industry and Information Technology (MIIT) steers the market through its New Energy Vehicle credit program and strict manufacturing licensing. Concurrently, national GB standards mandate specifications for charging interfaces and battery safety, ensuring technical uniformity and consumer protection across China. Navigating the evolving battery supply chain and anticipating shifts in consumer preference for digital cabin experiences will be critical for sustained success.
Market Dynamics
The market's trajectory is defined by the central government's 'dual carbon goals' policy, which translates national strategic imperatives into direct industrial support, compelling rapid electrification across both private and commercial vehicle segments.
Growth Catalysts
- Supportive Regulatory Framework:China's New Energy Vehicle (NEV) credit program, administered by the MIIT, creates strong financial incentives for manufacturers to prioritize electric vehicle production and innovation to meet stringent national targets.
- Battery Technology Maturation:The widespread adoption of lower-cost and safer lithium iron phosphate (LFP) battery chemistry for mass-market models has significantly reduced vehicle prices, making EVs accessible to a broader consumer base.
- Charging Infrastructure Expansion:Aggressive public and private investment in charging station networks, particularly within tier-1 and tier-2 cities like Shanghai and Hangzhou, alleviates range anxiety and supports higher EV adoption rates.
Market Restraints
- Raw Material Volatility:The market remains highly exposed to price fluctuations and supply chain bottlenecks for critical battery materials such as lithium and cobalt, which can directly impact vehicle production costs and consumer pricing.
- Geographic Infrastructure Imbalance:While charging infrastructure is dense in major urban centers, its scarcity in lower-tier cities and rural regions presents a significant structural barrier to widespread EV adoption outside of metropolitan areas.
- Grid Capacity Constraints:The increasing concentration of electric vehicles places considerable strain on local and national power grids, particularly during peak evening charging hours, posing a long-term challenge for energy management.
Strategic Opportunities
- Expansion into Lower-Tier Cities:As market saturation increases in top-tier cities, significant white-space opportunity exists in targeting consumers in tier-3 and tier-4 cities with affordable, practical EV models tailored to local commuting needs.
- Commercial Vehicle Electrification:Beyond logistics and delivery vans, the electrification of specialized vocational vehicles, such as municipal sanitation trucks and construction equipment, offers a new avenue for market growth and emissions reduction.
- Energy Service Business Models:The development of battery-as-a-service (BaaS) platforms, vehicle-to-grid (V2G) services, and sophisticated battery swapping networks creates new, recurring revenue streams beyond the initial vehicle sale.
Industry Challenges
- Intense Domestic Competition:A crowded marketplace with numerous domestic brands leads to severe price wars and margin compression, challenging the long-term financial sustainability of less-capitalized players.
- Software and Semiconductor Talent Gap:The pivot to software-defined vehicles creates immense demand for specialized engineers in autonomous driving, cybersecurity, and digital systems, leading to a critical talent shortage.
- Battery End-of-Life Management:Establishing a scalable and environmentally sound system for recycling and repurposing a massive volume of retired EV battery packs presents a complex logistical and regulatory hurdle for the entire industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Market |
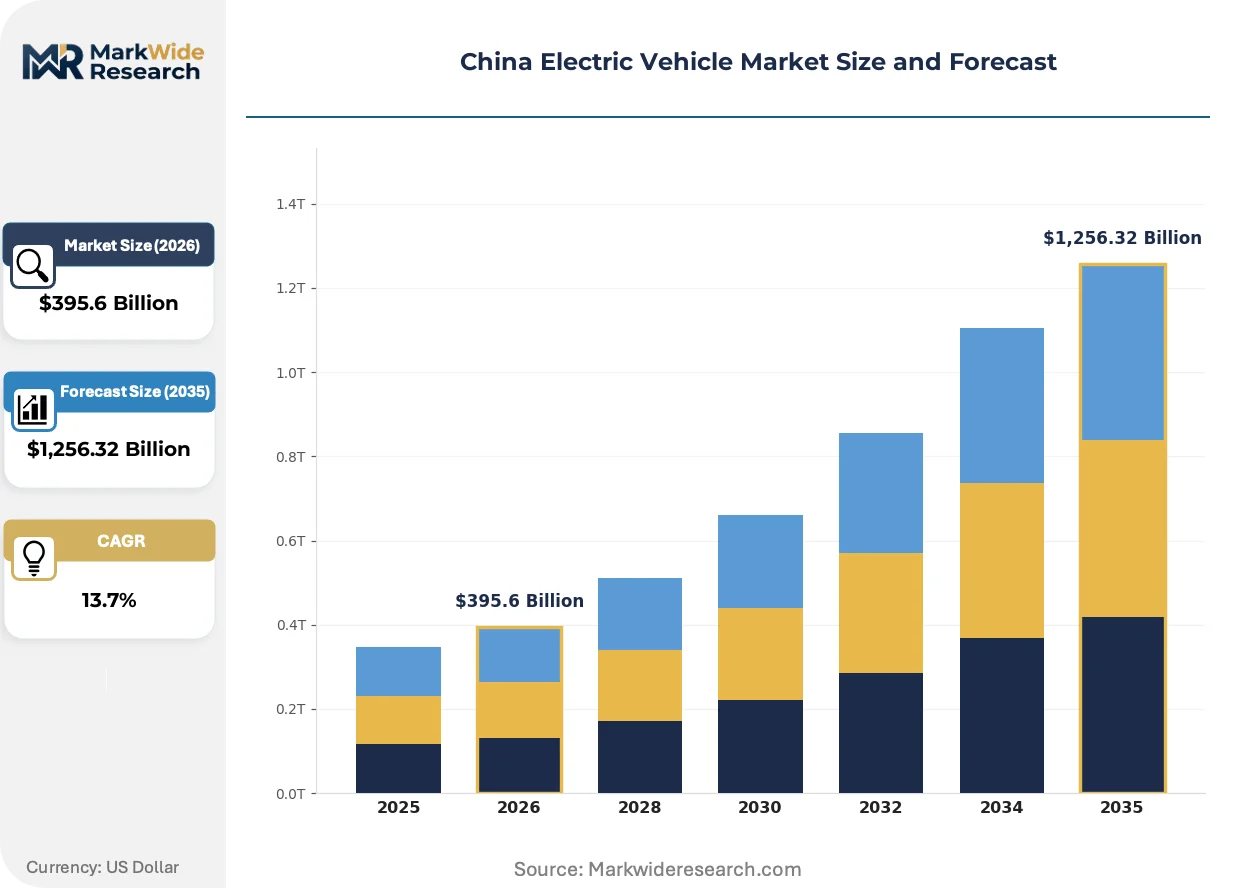
| Market Size in 2026 | $395.6 Billion |
| Market Size in 2035 | $1,256.32 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Extended Range Electric Vehicles Charging Technology: Fast Charging, Wireless Charging, Level 1 Charging, Level 2 Charging, Ultra-Fast Charging Application: Private Commuting, Shared Mobility, Government Fleet, Corporate Transportation, Logistics & Delivery Customer Type: Individual Buyers, Ride-Hailing Companies, Public Transport Operators, Freight Companies, Taxi Services |
| Companies Covered | BYD Co. Ltd., SAIC Motor, Wuling, Li Auto Inc., Geely Auto, NIO Ltd., XPeng Inc., Zeekr, Chery Automobile Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Market Strategic Shifts & Innovations
The basis of competitive advantage is shifting from hardware specifications to the sophistication of software and the richness of the in-cabin digital experience. This transition redefines long-term value and customer loyalty in China's mature EV landscape.
High-voltage 800V electrical architecture provides the foundation for ultra-fast charging capabilities, drastically reducing the time required to replenish battery capacity. Premium and increasingly mid-market models are rapidly adopting this platform to deliver a superior ownership experience. As a result, this advanced architecture is overtaking traditional 400V systems as the new performance benchmark for next-generation EVs in China.
The Ministry of Industry and Information Technology (MIIT) continues to enforce its dual-credit policy for New Energy Vehicles. This framework compels automakers to meet EV production quotas or purchase credits, creating a direct financial incentive for electrification. The policy disproportionately impacts legacy international joint ventures, forcing them to accelerate EV model introductions to maintain compliance and avoid penalties.
A notable behavioral shift involves the unbundling of software features from the initial vehicle purchase. Consumers increasingly opt for subscription-based access or one-time over-the-air updates for advanced driver-assistance systems and entertainment functions, disrupting the traditional sales model. This trend is most advanced among affluent buyers in tier-1 cities like Beijing and Guangzhou who prioritize digital connectivity.
China Electric Vehicle Market Segmentation
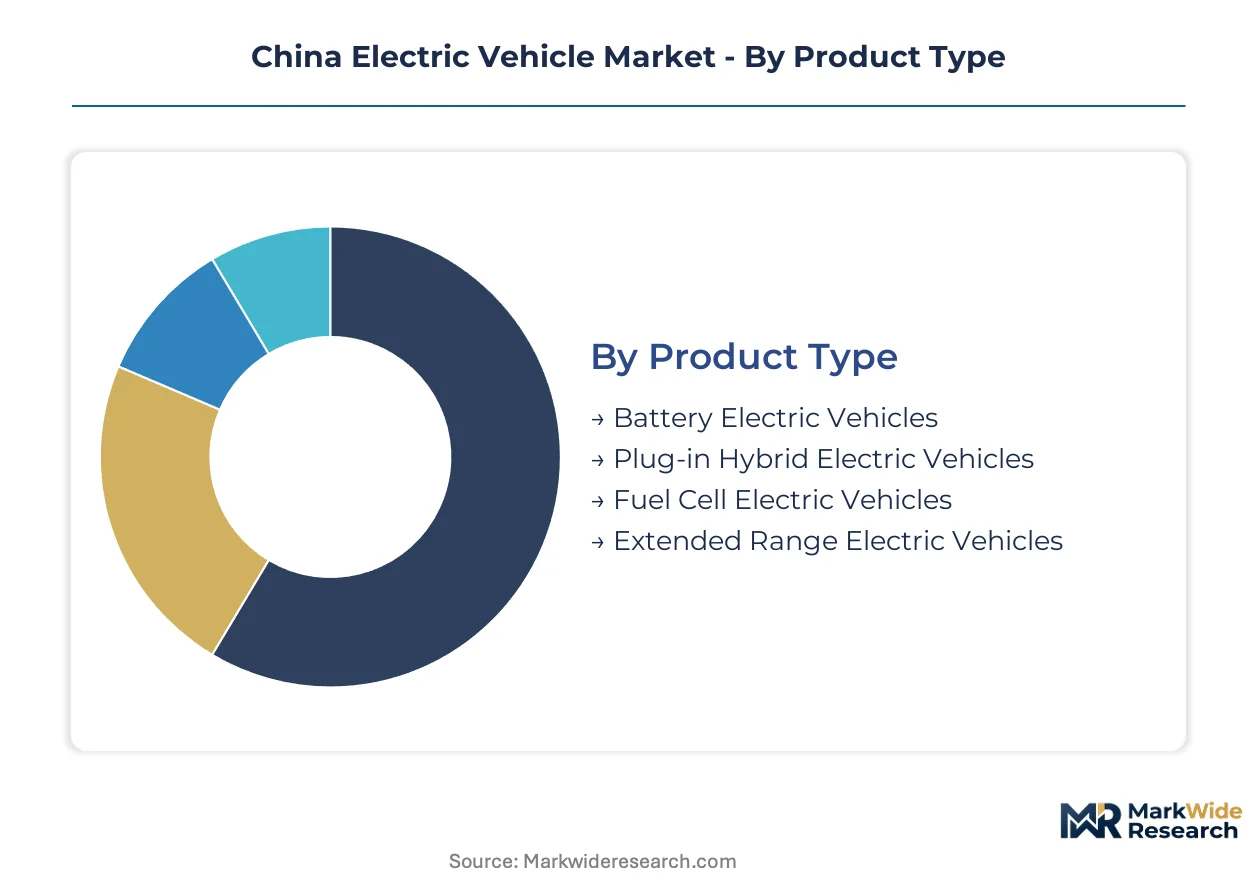
The China electric vehicle market, characterized by its rapid expansion and diverse consumer base, demands granular segmentation to understand underlying demand drivers and competitive dynamics. Analyzing these distinct segments reveals where technological innovation and policy support intersect with specific user requirements, guiding strategic investments.
Product Type:
Buyer decisions on electric vehicle product type in China often hinge on balancing range anxiety with upfront cost considerations and charging infrastructure availability.
- Battery Electric Vehicles:These vehicles rely solely on an electric motor and rechargeable battery for propulsion, offering zero tailpipe emissions. Demand is concentrating in China's tier-1 cities like Shanghai, driven by strong municipal incentives and a dense charging network.
- Plug-in Hybrid Electric Vehicles:Combining an internal combustion engine with an electric motor and battery, these vehicles offer extended range flexibility. This segment sees significant demand from consumers in tier-2 cities, where charging infrastructure is still developing but longer travel distances are common.
- Fuel Cell Electric Vehicles:These vehicles generate electricity from hydrogen via a fuel cell, emitting only water vapor.
- Extended Range Electric Vehicles:These vehicles feature a small gasoline generator to charge the battery, extending the electric driving range.
Volume sits with Battery Electric Vehicles; growth tilts toward Fuel Cell Electric Vehicles.
Charging Technology:
Convenience and charging speed are paramount factors influencing consumer and fleet operator choices for electric vehicle charging technology.
- Fast Charging:This technology typically uses DC power to rapidly replenish battery capacity, significantly reducing charging times. It is crucial for public charging stations in urban centers and along major highways across China.
- Ultra-Fast Charging:Utilizing high-voltage 800V electrical architectures, this technology delivers extremely rapid charging, often adding hundreds of kilometers of range in minutes. Premium EV models in China's affluent areas, such as Beijing and Guangzhou, are increasingly adopting this capability.
- Wireless Charging:This emerging technology allows EVs to charge without physical connection, using inductive power transfer.
- Level 1 Charging:Operating on standard household outlets, this is the slowest charging method, primarily used for overnight charging at home.
- Level 2 Charging:This offers faster charging than Level 1, suitable for home installations and workplace charging.
The market prioritizes rapid energy replenishment, with demand shifting towards higher power solutions.
Application:
Operational needs and fleet size primarily drive the selection of electric vehicle applications across various commercial and private sectors.
- Logistics & Delivery:This segment involves electric vans and trucks used for goods transportation, particularly within urban areas to meet strict emissions regulations. Commercial fleet operators are electrifying vehicles to achieve corporate sustainability goals in China.
- Private Commuting:Individual buyers acquire electric vehicles for daily personal travel, forming a foundational demand segment. Strong demand from individual buyers for private commuting underpins the market's expansion.
- Shared Mobility:This includes electric vehicles used in ride-sharing and car-sharing services.
- Government Fleet:Public sector organizations utilize electric vehicles for various governmental functions and services.
- Corporate Transportation:Businesses integrate electric vehicles into their company fleets for employee transport and operational needs.
Individual mobility and commercial logistics underpin core market demand.
Customer Type:
The purchasing power and fleet scale of different customer types dictate their engagement with China's electric vehicle market.
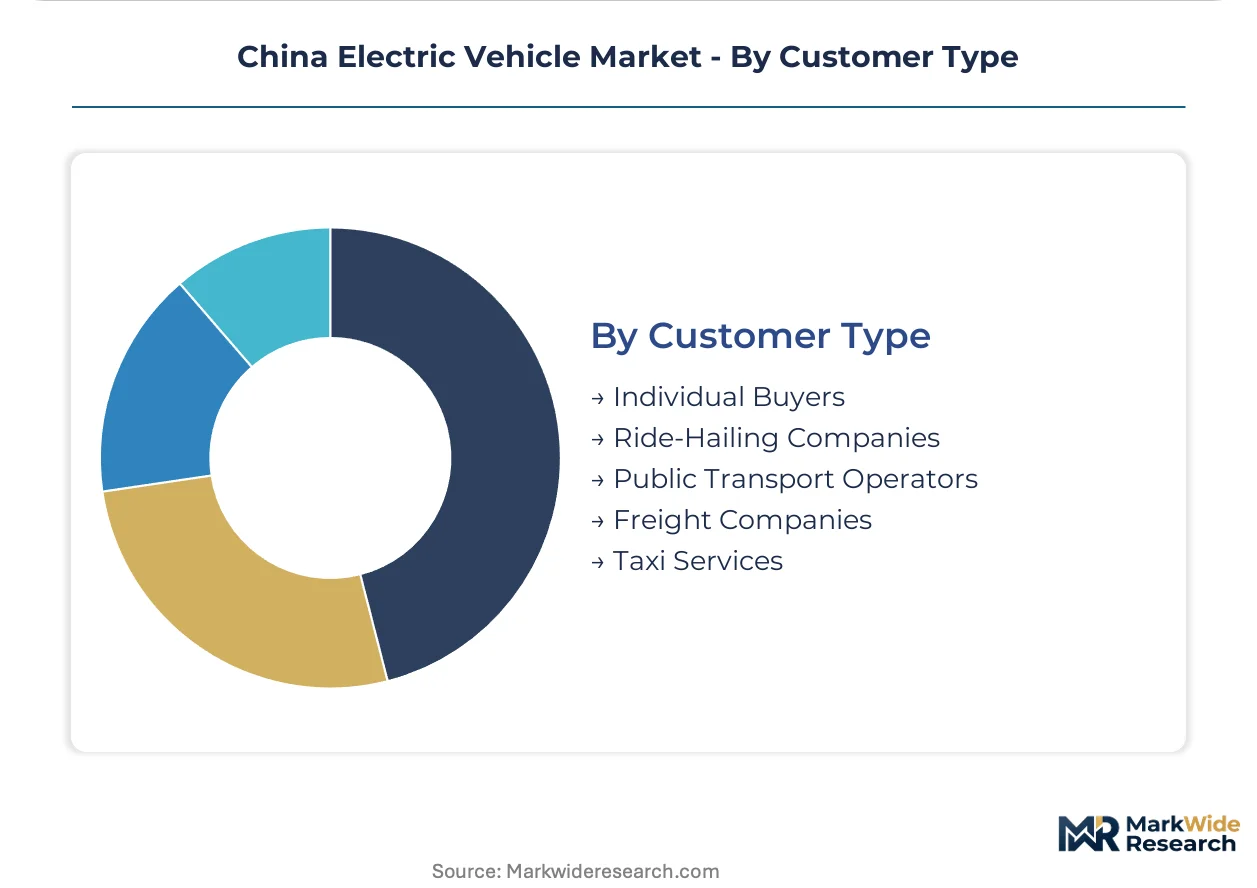
- Individual Buyers:Private citizens purchasing EVs for personal use constitute the largest customer base. These buyers are often influenced by municipal incentives and the availability of home charging solutions.
- Ride-Hailing Companies:These businesses operate large fleets of electric vehicles for on-demand passenger transport services. Ride-hailing companies form a significant part of the market's foundation, especially in densely populated urban centers.
- Public Transport Operators:Government-owned or managed entities operating electric buses and other public transit vehicles.
- Freight Companies:Businesses specializing in cargo transport, increasingly adopting electric trucks and vans for logistics.
- Taxi Services:Traditional taxi operators transitioning their fleets to electric vehicles to reduce operational costs and emissions.
Private consumers form the largest buyer base, while corporate fleets drive specialized vehicle demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's electric vehicle market presents a unique dynamic, serving as both a primary production hub and the largest consumption market globally. This dual role necessitates a nuanced understanding of regional demand drivers, policy implementation, and localized industrial ecosystems across its vast geography.
Yangtze River Delta
Demand for electric vehicles in the Yangtze River Delta is primarily driven by affluent individual buyers and corporate fleets pursuing sustainability goals. Municipal incentives, such as license plate quotas and purchase subsidies in cities like Shanghai, significantly influence consumer choices. This region hosts a dense concentration of EV manufacturing facilities and advanced battery R&D centers, fostering innovation.
Pearl River Delta
The Pearl River Delta exhibits robust demand from ride-hailing companies and logistics operators electrifying their urban fleets. Favorable municipal policies in Shenzhen and Guangzhou support the rapid expansion of charging infrastructure and vehicle adoption. This area is a hotbed for technology innovation, particularly in advanced driver-assistance systems and smart cabin experiences.
Beijing-Tianjin-Hebei
Government fleets and individual commuters in the Beijing-Tianjin-Hebei cluster contribute significantly to EV sales, spurred by stringent air quality targets. The MIIT's New Energy Vehicle credit program strongly encourages manufacturers to introduce diverse EV models here. Beijing leads in public charging network density and serves as a critical policy implementation zone for national EV strategies.
Sichuan-Chongqing
Emerging middle-class consumers and regional logistics needs are fueling EV demand in the Sichuan-Chongqing economic zone. Local industrial policies support the development of EV manufacturing and battery production capabilities within Chengdu and Chongqing. This inland region is becoming an important market for affordable, practical EV models tailored to local travel patterns.
China Electric Vehicle Market Key Industry Players
Top-tier vendors anchor the premium and technology-driven segments, while numerous smaller players compete intensely in the mass-market and specialized application niches. The market structure is highly tiered, with established automotive groups vying with agile new energy vehicle startups. Strategic archetypes include vertically integrated giants, software-defined vehicle innovators, and cost-efficient mass-market producers. Competitive moves frequently involve aggressive capacity expansion and continuous product differentiation.
Within the segment of differentiated offerings, BYD Co. Ltd. exemplifies a vertically integrated approach, leveraging in-house battery production for cost advantages and scale. NIO Ltd. represents a premium brand, focusing on unique battery-as-a-service models and sophisticated user experiences. XPeng Inc. occupies a position emphasizing advanced driver-assistance systems and in-car intelligence capabilities to attract tech-savvy buyers.
| Leading Market Players |
|---|
| BYD Co. Ltd. |
| SAIC Motor |
| Wuling |
| Li Auto Inc. |
| Geely Auto |
| NIO Ltd. |
| XPeng Inc. |
| Zeekr |
| Chery Automobile Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Vertical integration, exemplified by BYD Co. Ltd.'s in-house battery production, anchors a strong supply position and enables significant pricing power within China's electric vehicle market. This strategic choice allows manufacturers to control critical input costs and scale production efficiently. Such integration also influences the downstream pricing of mass-market EV models.
Pricing Analysis
Margin tightening across China's mass-market electric vehicle segment reflects intense domestic competition and aggressive price wars. The dominant pricing model combines per-unit transactional sales for vehicles with subscription-based access for advanced software features like autonomous driving. Price differentiation stems from advanced driver-assistance system capabilities, in-car intelligence, and brand premium, particularly in tier-1 cities. Buyers in lower-tier cities exhibit higher price sensitivity, prioritizing affordability and practical utility.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke logistics network efficiently move electric vehicles and components across China's vast geography. Geographic supply concentration for critical EV inputs, especially lithium-ion batteries and their raw materials, is centered predominantly within China. The market draws from key components like lithium, cobalt, and semiconductors. Raw material volatility for battery minerals represents a significant structural risk. Downstream distribution runs through a mix of direct-to-consumer sales, traditional dealership networks, and online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as intense domestic competition and margin compression are forcing less-capitalized players out. Strategic moves are critical for sustained success.
For Market Incumbents: Deepen vertical integration into core technologies like battery production and software development to mitigate supply chain risks and enhance cost control. Invest heavily in advanced driver-assistance systems and in-car intelligence to differentiate offerings against emerging entrants. Continuous innovation in high-voltage 800V electrical architectures ensures a competitive edge against the threat of rapid technological obsolescence.
For New Entrants and Emerging Players: Underserved buyer archetypes in tier-3 and tier-4 cities represent a significant white-space opportunity for affordable, practical EV models. Focus on commercial vehicle electrification beyond logistics, targeting specialized vocational vehicles like sanitation trucks. A compelling go-to-market angle involves offering robust, cost-efficient vehicles tailored to local commuting needs, supported by accessible charging solutions.
For Investors and Strategic Acquirers: Exit pathways concentrate in software-defined vehicle innovators and battery technology specialists, offering high growth potential. The long-term viability of the market remains strong, driven by China's dual carbon goals and continuous policy support. A critical signal to watch is the evolution of consumer preference for digital cabin experiences and the regulatory landscape around battery end-of-life management.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Chain Control | Securing raw material access and reducing production costs enhances competitive advantage for EV manufacturers. |
| Software-Defined Vehicle Investment | Developing advanced autonomous driving and digital cabin features differentiates brands and captures new revenue streams. |
| Charging Infrastructure Partnership | Expanding access to fast and ultra-fast charging networks alleviates range anxiety and boosts EV adoption rates. |
| Lower-Tier City Market Entry | Targeting consumers in underserved regions with affordable EV models unlocks substantial untapped demand. |
| Commercial Fleet Electrification | Electrifying specialized vocational vehicles expands market application and supports national emissions reduction targets. |
Research Approach
Document review covered MIIT reports, GB standards, and industry association publications, complemented by interviews with OEM platform engineers, battery material suppliers, charging infrastructure developers, and MIIT policy advisors. This approach combined primary insights with secondary validation. Bottom-up and top-down triangulation ensured data accuracy for the China electric vehicle market.
Volume and value outputs were generated through a proprietary analytical framework across the analysis window, modeling segmentation dimensions including product type, charging technology, application, customer type, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected future demand, incorporating inputs such as the NEV credit program impacts and LFP battery cost curves.
Revisions become necessary when significant regulatory shifts or unexpected technological breakthroughs materialize within the market. Forecasts reflect assumptions documented during the research process, acknowledging risks like raw material volatility and grid capacity constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
EV Platform Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Global Smart Electric Drive Market