
 France Hybrid Electric Vehicle Battery Market | 2026-2036
France Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
France Hybrid Electric Vehicle Battery Market Insights
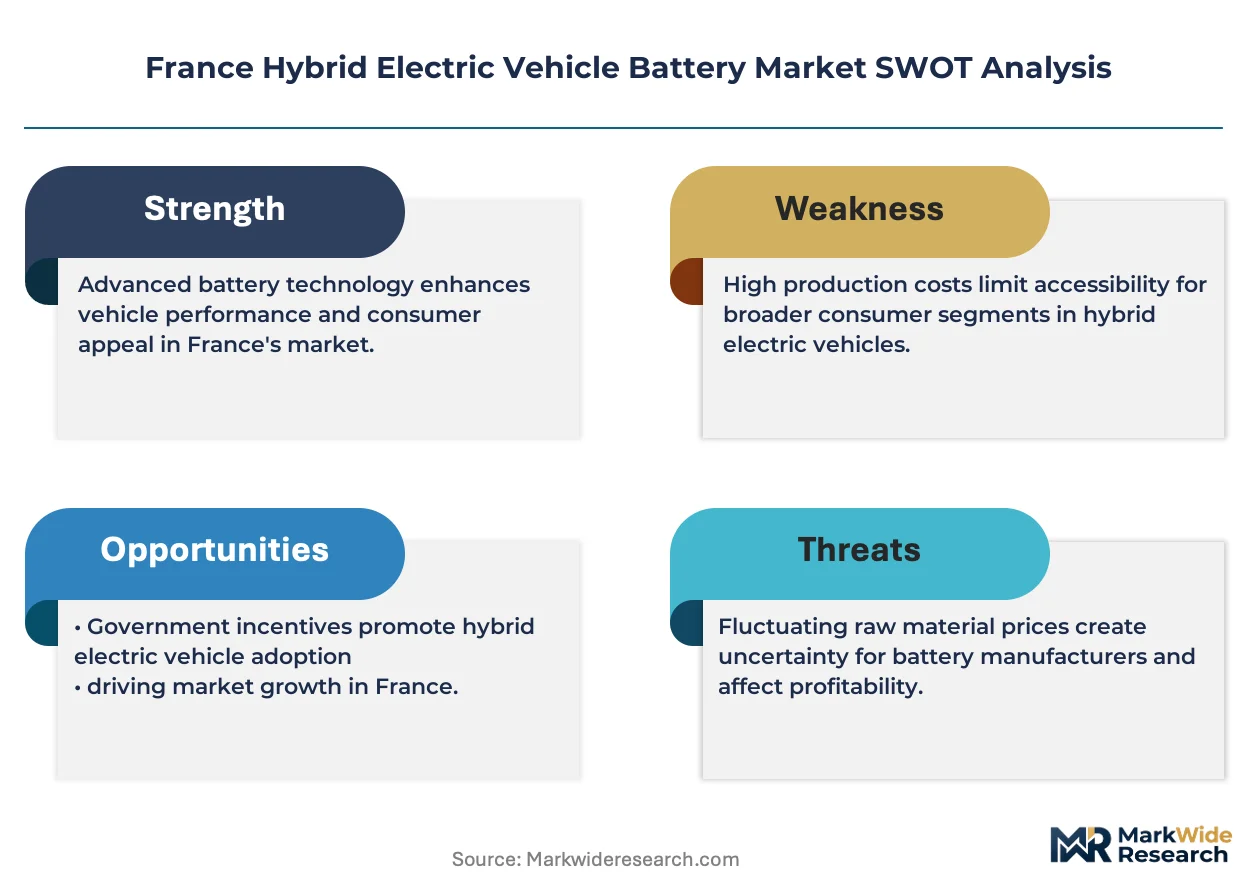
Project finance tied to gigafactory construction is fragmenting the competitive landscape for French hybrid battery supply. Saft Groupe SA leverages its domestic manufacturing footprint to anchor defense and industrial contracts. Verkor competes through vertical integration into cell production for European OEM programs. Contemporary Amperex Technology Co Ltd extends its position via licensing arrangements with French automakers seeking LFP chemistry access.
France Hybrid Electric Vehicle Battery refers to electrochemical energy storage systems combining internal combustion with electric propulsion, typically employing lithium-ion cells with nickel-manganese-cobalt cathodes operating at 300-400V system architectures for passenger and light commercial applications. The primary purpose involves enabling torque-fill, regenerative energy recovery, and emission-reduced urban driving modes. Lithium-ion chemistry dominates installed capacity due to superior gravimetric energy density versus nickel-metal hydride alternatives, though solid-state prototypes attract R&D funding for next-generation thermal stability. Fast Charging technology leads infrastructure deployment timelines, while Battery Management System development concentrates margin pools through software-defined performance optimization and warranty risk reduction.
France's regulatory environment operates under the EU Green Deal framework, with ANSM monitoring industrial chemical safety and REACH compliance governing cathode material imports. The EU AI Act introduces conformity requirements for autonomous battery diagnostics, while F-Gas Regulation phases constrain thermal management refrigerant selections. Stakeholders must monitor how the CSRD's supply chain disclosure mandates reshape procurement qualification criteria for cell suppliers serving French OEM platforms.
Market Dynamics
France's hybrid battery sector faces structural pressure from the EU Green Deal's tightening CO2 performance standards, which compress automaker compliance timelines and accelerate powertrain electrification roadmaps. Fleet procurement patterns now favor hybrid architectures as transitional compliance pathways before full battery-electric mandates take effect.
Growth Catalysts
- EU Green Deal CO2 Standards:Automakers face binding emission reduction trajectories that position 48V mild-hybrid systems as cost-effective compliance bridges for passenger car portfolios.
- Paris-Saclay Battery Cluster Concentration:Research infrastructure density around this innovation hub accelerates cell chemistry iteration cycles and talent pipeline development for domestic suppliers.
- Urban Delivery Fleet Electrification:Light commercial operators in French metropolitan zones prioritize hybrid powertrains to maintain route flexibility while satisfying municipal low-emission zone requirements.
Market Restraints
- Cathode Material Cost Volatility:Nickel-manganese-cobalt formulations face price instability from concentrated DRC cobalt extraction and Indonesian nickel processing bottlenecks.
- Domestic Cell Manufacturing Gap:France lacks operational gigafactory capacity at scale, forcing dependence on Asian cell imports and exposing supply security to maritime logistics disruption.
- F-Gas Regulation Thermal Constraints:Phase-down mandates for hydrofluorocarbon refrigerants complicate battery thermal management system design and extend validation timelines.
Strategic Opportunities
- Solid-State Prototype Commercialization:Next-generation cell architectures promise enhanced thermal stability and energy density for premium hybrid applications currently under development.
- Renault ElectriCity Hub Expansion:Northern France manufacturing concentration creates localized demand anchor for module and pack assembly suppliers seeking OEM proximity.
- CSRD Supply Chain Disclosure Alignment:Corporate sustainability reporting mandates create qualification advantages for cell suppliers with traceable raw material sourcing and carbon footprint documentation.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Domestic universities produce insufficient cell scientists and battery management system software architects to match facility expansion timelines.
- REACH Compliance Documentation Burden:Cathode material importers face extended substance registration timelines that delay new supplier qualification for French OEM platforms.
- Legacy Powertrain Integration Complexity:Hybrid system architecture demands simultaneous optimization of internal combustion thermal cycles and electric torque delivery, straining cross-functional engineering coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Hybrid Electric Vehicle Battery Market |
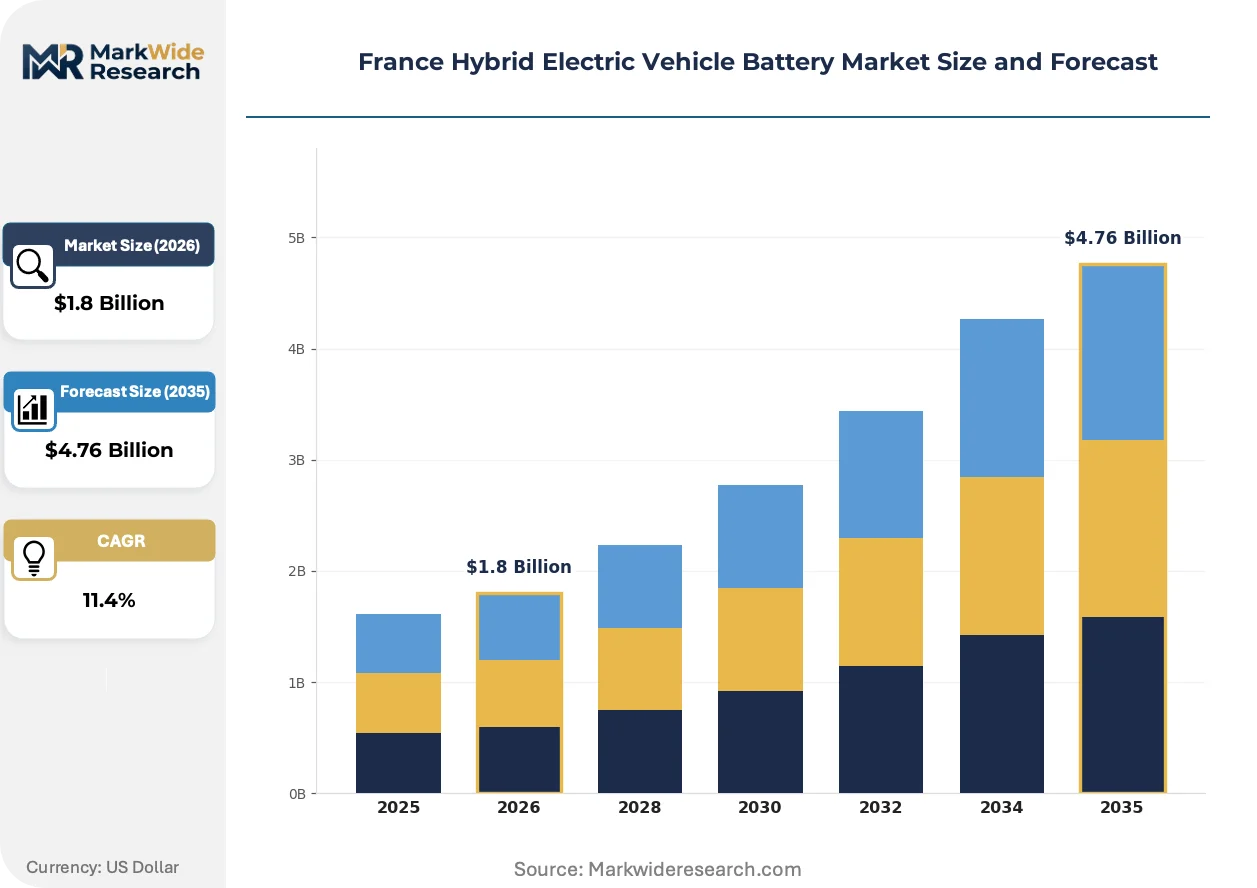
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state End User: OEMs, Aftermarket, Fleets, Individual Consumers Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Technology: Fast Charging, Regenerative Braking, Battery Management System, Thermal Management |
| Companies Covered | LG Energy Solution, Contemporary Amperex Technology Co Ltd, BYD Company, Saft Groupe SA, Elecsys France, Verkor, Panasonic Holdings Corporation, SK Innovation, FIAMM SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Hybrid Electric Vehicle Battery Market Trends and Innovations
Cell chemistry evolution and software-defined battery management are compressing development cycles while regulatory disclosure mandates reshape supplier qualification protocols across French automotive supply chains.
Solid-state electrolyte prototypes are collapsing the traditional trade-off between energy density and thermal stability that has constrained nickel-manganese-cobalt cell architectures. French OEM engineering teams evaluate these formulations for next-generation 400V hybrid systems targeting premium vehicle segments. The technology is collapsing warranty risk premiums that currently inflate battery pack pricing for high-performance applications.
REACH substance registration requirements now extend to full supply chain transparency for cathode active materials entering French manufacturing facilities. ECHA enforcement priorities have shifted toward downstream battery sector compliance verification, elevating documentation costs for non-EU material suppliers. Module assemblers serving Renault and Stellantis platforms invest in in-house analytical laboratories to accelerate substance characterization and regulatory filing preparation.
Fleet operators now specify total-cost-of-ownership performance guarantees rather than unit price in hybrid battery procurement negotiations. Leasing subsidiaries and energy service companies displace traditional component distributors as the primary contracting channel for urban delivery vehicle powertrain suppliers. This pattern concentrates most visibly in the Île-de-France logistics corridor, where municipal clean air mandates accelerate fleet renewal decisions.
France Hybrid Electric Vehicle Battery Market Segmentation
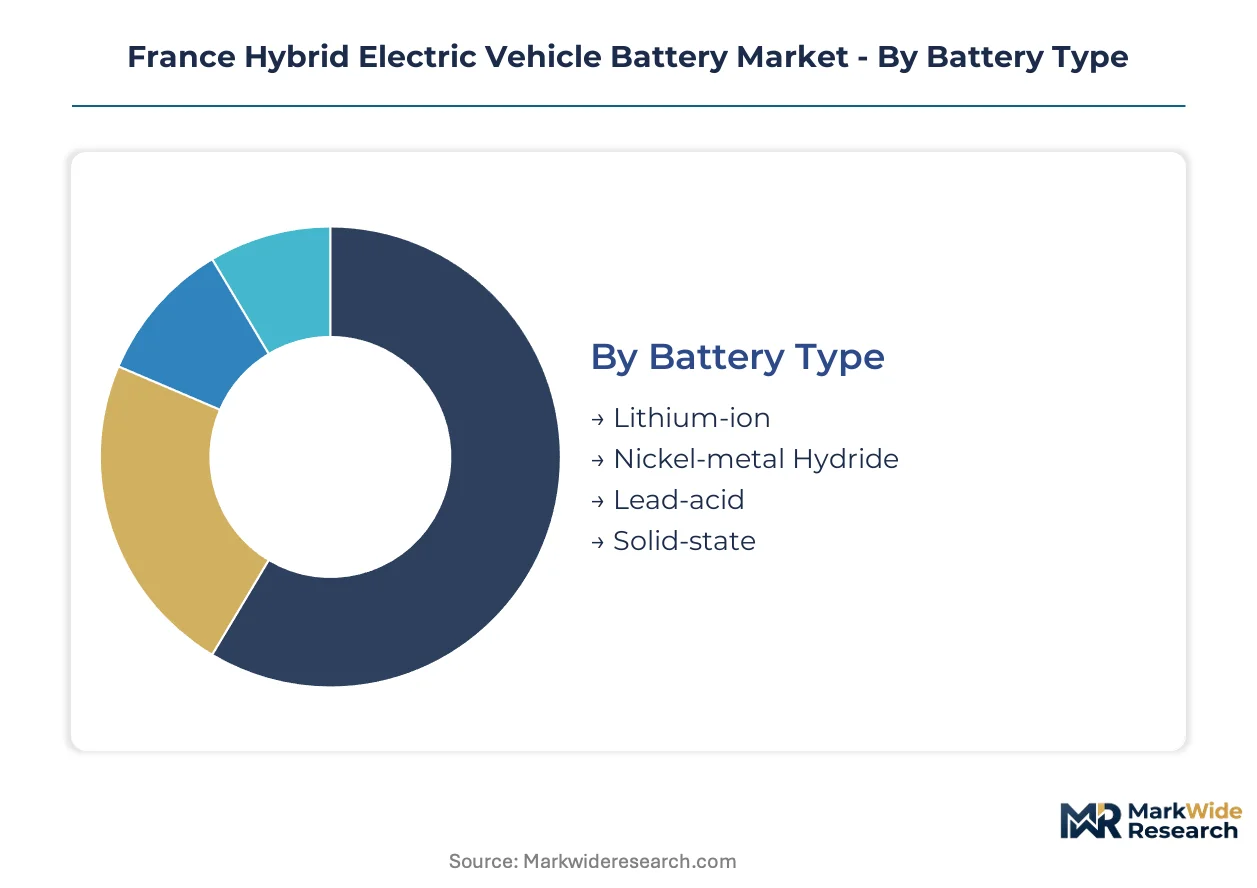
Segmentation in the France hybrid battery market reveals distinct procurement rhythms and margin profiles across chemistry types and customer channels. Understanding these divides exposes where contract values concentrate and which segments compress supplier margins through volume concentration.
Battery Type:
Cycle times vary dramatically across chemistries, with established formats turning inventory rapidly while next-generation platforms extend validation phases.
- Lithium-ion:Nickel-manganese-cobalt cathode architectures dominate current French OEM platforms, delivering 300-400V system compatibility for passenger hybrid powertrains. Renault and Stellantis assembly lines in northern France anchor procurement volume for this chemistry, though cathode material cost volatility from DRC cobalt and Indonesian nickel processing squeezes margin predictability for cell suppliers.
- Solid-state:Prototype solid-electrolyte cells promise enhanced thermal stability and energy density for premium 400V hybrid applications currently under evaluation by French engineering teams. Paris-Saclay cluster research infrastructure accelerates iteration timelines, but commercial scale-up remains constrained by manufacturing equipment availability and dry-room facility construction lead times.
- Nickel-metal Hydride:Legacy chemistry retains position in select cost-sensitive hybrid applications where proven cycle life outweighs gravimetric density disadvantages.
- Lead-acid:Auxiliary power applications and starter-generator subsystems in mild-hybrid architectures sustain residual demand from established supply relationships.
Lithium-ion anchors the volume base while solid-state gains share at the steepest rate.
End User:
Customer type determines contract structure, with direct OEM relationships offering scale but demanding warranty risk transfer, while fleet channels concentrate buying power through leasing intermediaries.
- OEMs:Renault's ElectriCity manufacturing hub in northern France and Stellantis platform engineering teams in Île-de-France drive specification-setting for cell chemistry, module architecture, and battery management system integration. These relationships demand multi-year supply commitments with stringent REACH compliance documentation and CSRD-aligned carbon footprint traceability.
- Fleets:Urban delivery operators in Paris and Lyon metropolitan zones specify total-cost-of-ownership performance guarantees rather than unit pricing, with leasing subsidiaries displacing traditional distributors as primary contracting channels. Municipal low-emission zone mandates accelerate renewal decisions for light commercial hybrid powertrains.
- Aftermarket:Replacement module demand concentrates around warranty expiration timelines for first-generation French hybrid vehicle populations.
- Individual Consumers:Retail channel fragmentation limits direct procurement, with most replacement volume flowing through authorized dealer networks.
OEMs command the volume base while fleet channels climb the fastest as procurement professionalization accelerates.
Capacity:
Pack sizing correlates with vehicle class and electrification depth, from 48V mild-hybrid assist to 400V full-hybrid architectures.
- Medium Capacity:5-15 kWh packs serve mainstream passenger hybrid applications where electric-only urban range satisfies municipal emission restrictions without full battery-electric cost premiums. French OEM passenger car portfolios concentrate procurement here as CO2 compliance bridges under tightening EU Green Deal standards.
- High Capacity:15-30 kWh configurations enable extended electric-only operation for premium hybrid SUVs and light commercial vehicles operating in Paris-Saclay and Lyon logistics corridors. These packs demand sophisticated thermal management to maintain cycle life under rapid charging protocols.
- Low Capacity:Sub-5 kWh 48V systems provide torque-fill and regenerative recovery for entry mild-hybrid powertrains.
- Ultra High Capacity:Above-30 kWh formats approach battery-electric territory and see limited hybrid-specific application in French market configurations.
Medium capacity holds the volume base while high capacity expands most quickly as fleet electrification deepens.
Technology:
Technology segmentation separates hardware components from software-defined performance optimization layers where margin pools concentrate.
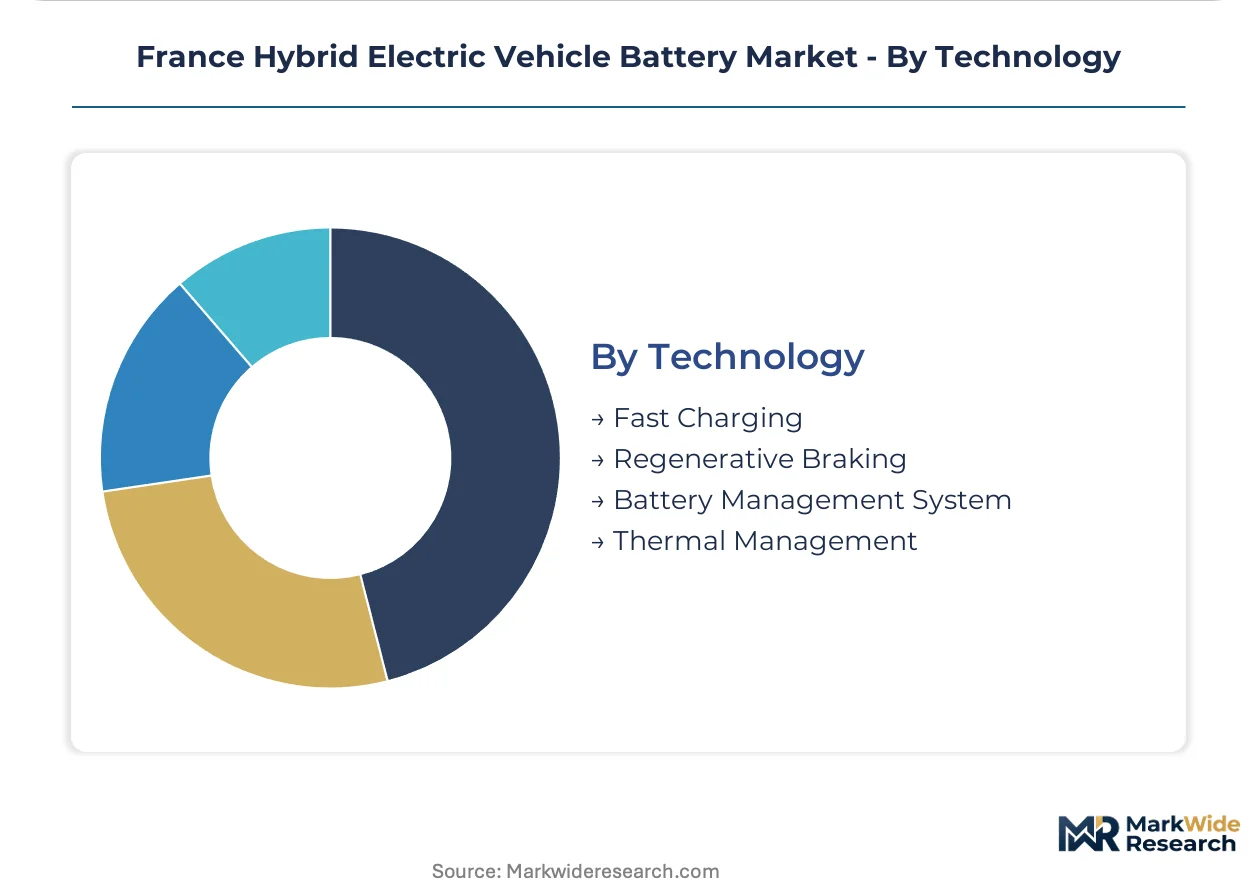
- Fast Charging:High-power DC infrastructure deployment timelines in France prioritize 150-350 kW capability for highway corridor networks, with hybrid battery architectures requiring cell chemistry compatibility for rapid charge acceptance without lithium plating degradation. ANSM safety monitoring extends to thermal runaway prevention under aggressive charging protocols.
- Battery Management System:Software-defined performance optimization and warranty risk reduction concentrate margin pools through state-of-charge estimation algorithms, cell balancing, and predictive thermal control. EU AI Act conformity requirements for autonomous battery diagnostics reshape development roadmaps for French OEM platform suppliers.
- Regenerative Braking:Kinetic energy recovery system integration with friction brake blending demands precise torque coordination.
- Thermal Management:F-Gas Regulation phase-down constraints complicate refrigerant selection and extend validation timelines for active cooling systems.
Battery Management System anchors the margin base while fast charging infrastructure sees the steepest deployment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's hybrid battery trade flows reflect a structural import dependency on Asian cell manufacturing, with domestic module assembly concentrating around northern industrial corridors. The Paris-Saclay innovation cluster anchors R&D capacity while procurement patterns diverge across metropolitan demand zones.
Île-de-France
Greater Paris anchors fleet electrification demand through urban delivery operators navigating municipal low-emission zone mandates. ANSM chemical safety monitoring extends to battery thermal runaway prevention protocols for high-density logistics corridors. The Paris-Saclay battery cluster concentrates cell chemistry research infrastructure and electrochemical engineering talent pipelines for domestic suppliers.
Hauts-de-France
Renault's ElectriCity manufacturing hub in northern France drives specification-setting for hybrid module architectures and pack assembly integration. EU Green Deal CO2 performance standards compress automaker compliance timelines, accelerating powertrain electrification procurement from this concentration. Douai and Maubeuge assembly facilities anchor localized demand for tier-one battery management system suppliers.
Auvergne-Rhône-Alpes
Lyon metropolitan logistics operators specify total-cost-of-ownership performance guarantees for light commercial hybrid powertrains serving regional distribution networks. REACH compliance documentation requirements for cathode active materials reshape supplier qualification protocols for OEM platforms. The Grenoble engineering ecosystem contributes thermal management system development for 400V hybrid architectures.
Provence-Alpes-Côte d'Azur
Marseille-Fos port infrastructure handles maritime import flows of lithium-ion cells from Asian manufacturing centers, exposing supply security to shipping lane disruption risks. F-Gas Regulation phase-down constraints complicate refrigerant selection for battery thermal management systems in this Mediterranean climate zone. Aix-Marseille University research partnerships accelerate solid-state electrolyte prototype evaluation timelines.
France Hybrid Electric Vehicle Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell chemistry and thermal management subsystems. The French hybrid battery sector exhibits tiered consolidation, with established Asian cell manufacturers anchoring supply volume while domestic specialists capture module assembly and battery management software margins. Three archetypes dominate: vertically integrated cell producers, regional module assemblers, and software-defined performance optimization vendors. Capacity expansion and strategic technology licensing represent the dominant competitive moves as firms position for EU Green Deal compliance-driven procurement waves.
Within the domestic specialist tier, Saft Groupe SA and Verkor occupy positions anchored by French manufacturing footprints and defense-industrial contract relationships. Contemporary Amperex Technology Co Ltd exemplifies the licensing-oriented market entry archetype, extending chemistry access through partnership structures rather than direct facility investment. These three firms represent distinct strategic postures: captive domestic production, emerging vertical integration, and technology access through contractual arrangement.
| Leading Market Players |
|---|
| LG Energy Solution |
| Contemporary Amperex Technology Co Ltd |
| BYD Company |
| Saft Groupe SA |
| Elecsys France |
| Verkor |
| Panasonic Holdings Corporation |
| SK Innovation |
| FIAMM SpA |
| Others |
Pricing and Supply Chain Analysis
Paris-Saclay battery cluster research infrastructure concentrates domestic R&D capacity but leaves French OEMs exposed to Asian cell pricing power for volume procurement. Module assemblers serving Renault and Stellantis platforms absorb margin compression from cathode material cost volatility while competing on REACH compliance documentation speed.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered discounts and multi-year supply commitments. Price differentiation separates premium NMC cathode grades with full CSRD traceability from standard-tier cells with limited carbon footprint documentation. Pricing pressure stems from Indonesian nickel processing bottlenecks and DRC cobalt extraction concentration squeezing margin predictability for cell suppliers. Fleet operators show highest price sensitivity through total-cost-of-ownership negotiations, while defense-industrial buyers absorb premium pricing for domestic manufacturing security.
Supply Chain Analysis
Contemporary Amperex Technology Co Ltd, LG Energy Solution, and SK Innovation hold dominant contract-manufacturing capacity for lithium-ion cells entering French module assembly facilities. French supply chains draw from Chinese cathode active material processing, South Korean separator films, and Japanese electrolyte formulations. Single-source vulnerability concentrates in maritime import lanes through Marseille-Fos port infrastructure exposed to shipping disruption. Distribution runs through tier-one module assemblers co-located with Renault ElectriCity hub operations in northern France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's hybrid battery sector sits in early-cycle expansion as EU Green Deal CO2 standards compress automaker compliance timelines and accelerate powertrain electrification procurement ahead of full battery-electric mandates.
For Market Incumbents: Pre-empt emerging solid-state prototype competition by securing Paris-Saclay cluster research partnerships and accelerating dry-room facility construction timelines. Lock in long-term cathode material offtake agreements before REACH substance registration backlogs extend supplier qualification delays. Prioritize backward integration into battery management system software to capture margin pools from state-of-charge estimation algorithms.
For New Entrants and Emerging Players: Build out module assembly capacity adjacent to Hauts-de-France OEM manufacturing corridors where localization requirements concentrate demand. Target fleet leasing subsidiaries in Île-de-France urban logistics corridors as the most penetrable channel displacing traditional component distributors. Lead with total-cost-of-ownership performance guarantees rather than unit pricing to match procurement professionalization trends.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cell chemistry specialists with captive supply of NMC cathode formulations and established REACH compliance documentation infrastructure. Five-to-ten year viability hinges on solid-state electrolyte commercialization timelines and thermal management system integration capabilities. Watch for inflection signals in dry-room manufacturing equipment order backlogs and Paris-Saclay cluster talent migration patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell Chemistry Licensing Agreement | Contemporary Amperex Technology Co Ltd extends LFP chemistry access to French OEMs seeking cost-competitive compliance pathways. |
| Gigafactory Capacity Buildout | Verkor's vertical integration into cell production reduces French dependence on Asian imports for European OEM programs. |
| Battery Management System Acquisition | Software-defined performance optimization concentrates margin pools through predictive thermal control and warranty risk reduction. |
| Solid-State Prototype Joint Venture | Paris-Saclay cluster partnerships accelerate dry-room facility construction and next-generation thermal stability validation. |
| CSRD-Aligned Supply Chain Certification | Traceable raw material sourcing creates qualification advantages for cathode suppliers serving Renault and Stellantis platforms. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, fleet leasing operations managers, and thermal management system R&D directors and refined through secondary validation. Primary fieldwork combined structured interviews with aftermarket distributors and dealership service operations. Secondary sources included EU Green Deal regulatory filings, ANSM chemical safety monitoring reports, ECHA REACH substance registration databases, and vehicle production registration data from French automotive industry associations. Bottom-up cell chemistry demand modeling triangulated against top-down OEM powertrain electrification roadmaps.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled included battery chemistry type, vehicle propulsion architecture, pack capacity tier, and regional manufacturing cluster concentration. CAGRs were derived from installed base growth trajectories and replacement cycle timing. Industry-specific inputs incorporated F-Gas Regulation thermal constraint compliance timelines and CSRD supply chain disclosure mandate implementation schedules.
Practitioners should monitor nickel-cobalt price volatility indices and dry-room manufacturing equipment lead times for early signals of forecast revision. Assumptions reflect current EU Green Deal CO2 performance standard trajectories and REACH enforcement priority shifts. Quarterly review of cathode material import customs data and Paris-Saclay cluster patent filing velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Scooter Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market