
 Asia-Pacific Train Battery Market | 2026-2036
Asia-Pacific Train Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Train Battery Market Analytics
High-cycle-life lithium-ion specifications is collapsing the historical dominance of nickel-cadmium in Asia-Pacific rolling stock. CATL leverages its cell-to-pack architecture to anchor supply contracts with Chinese state rail operators. GS Yuasa Corporation sustains its position through JIS-certified manufacturing for Japanese Shinkansen auxiliary systems. BYD Company differentiates via in-house production of lithium iron phosphate cells for metro energy storage.
Asia-Pacific train batteries store and discharge electrical energy for traction, auxiliary power, and regenerative braking in electrified rail systems, with cell configurations typically rated for 800 to 1,500 charge cycles at temperatures spanning minus 20 to 55 degrees Celsius. Lithium-ion chemistry dominates new procurements due to superior energy density and reduced weight penalties versus lead-acid alternatives. Application segmentation shows high-speed trains capturing premium margin pools through stringent thermal management requirements, while light rail systems represent the fastest-growing installation base as Southeast Asian cities expand urban transit networks. Technology segmentation reveals rechargeable systems maintaining volume leadership, though hybrid configurations pairing batteries with ultra-capacitors are gaining traction for stop-start urban routes.
China's MIIT enforces GB standards for rail battery safety and recycling, while India's BIS mandates performance certification for traction batteries deployed on Indian Railways infrastructure. Japan's METI directs R&D subsidies toward solid-state battery prototypes for next-generation Shinkansen auxiliary power. Stakeholders must monitor how Australia's TGA-equivalent rail safety frameworks and South Korea's MFDS-aligned industrial standards reshape import compliance and local assembly requirements.
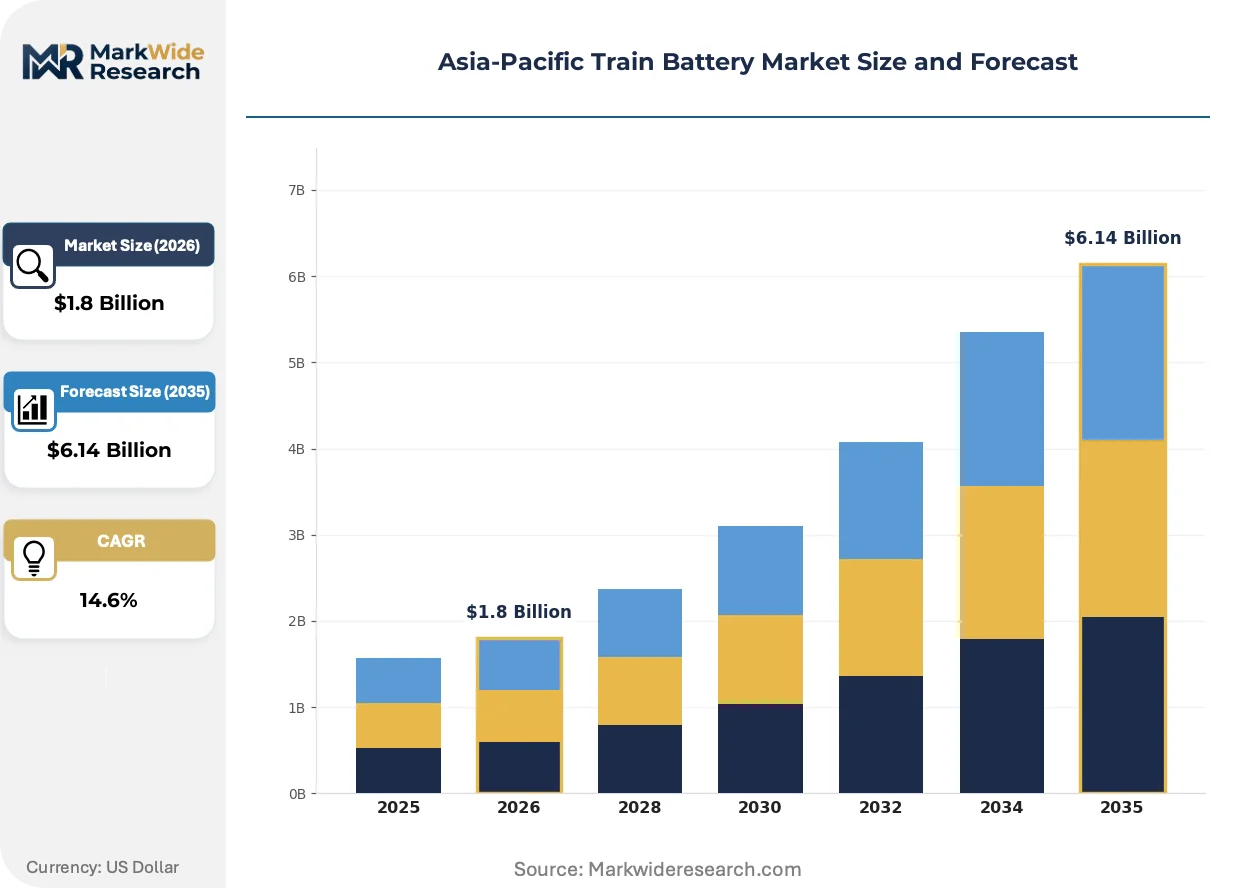
Market Dynamics
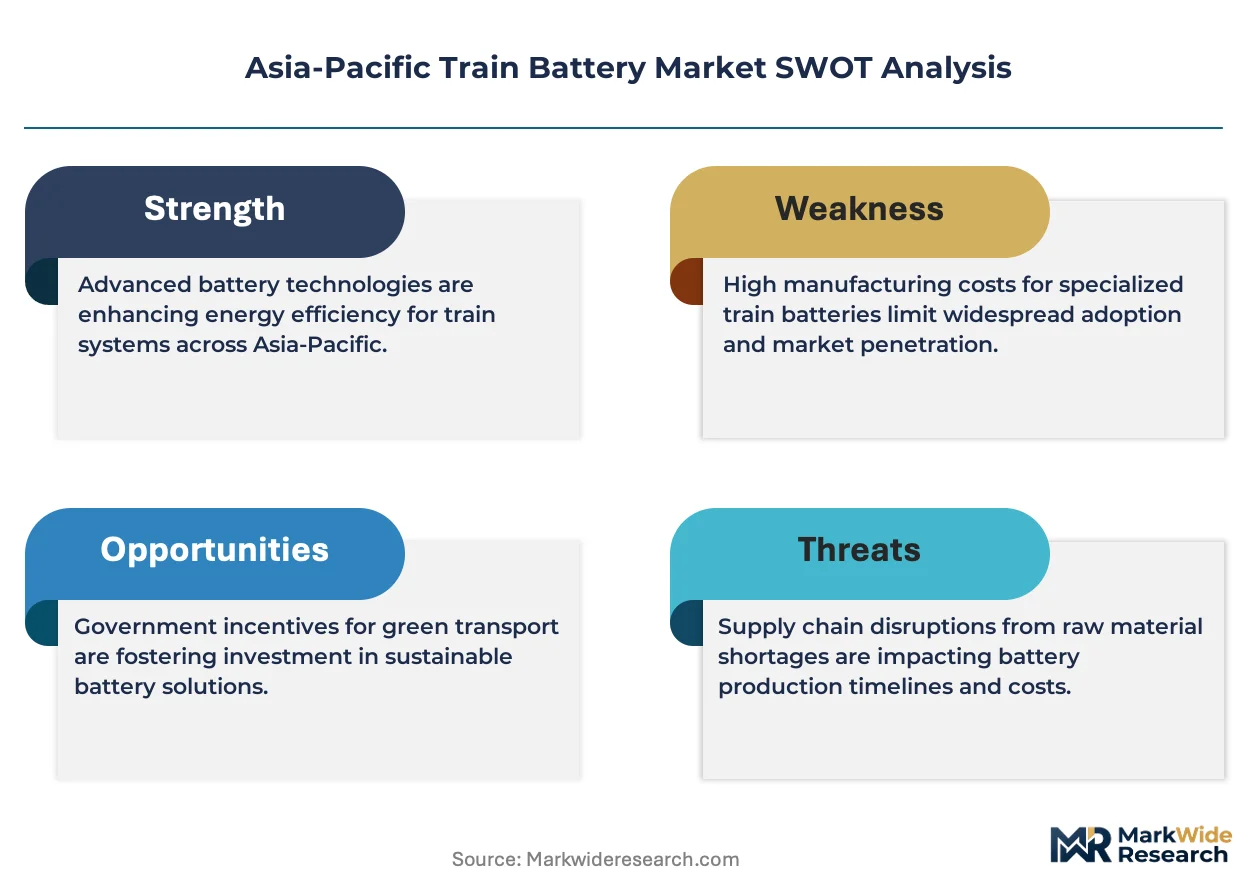
China's MIIT enforcement of GB rail battery safety standards is compressing supplier qualification timelines while India's PLI scheme for advanced chemistry cells redirects procurement toward domestic lithium-ion manufacturing capacity.
Growth Catalysts
- Urban metro fleet electrification:Operators in China and India are replacing diesel locomotives with battery-electric multiple units, creating sustained procurement pipelines for high-cycle lithium-ion systems.
- India's PLI scheme for ACC manufacturing:Production-linked incentives for advanced chemistry cells are localizing cell supply chains and reducing import dependency for traction battery packs.
- Regenerative braking integration:High-speed rail corridors are mandating energy recovery systems that require high-power-density battery configurations for kinetic energy capture.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for cathode active materials fluctuate with spot market conditions, compressing cell manufacturer margins.
- Cell supply concentration in East Asia:Overreliance on Chinese and South Korean cell producers creates geographic supply risk for rolling stock OEMs outside these markets.
- Nickel-cadmium installed base inertia:Legacy traction battery systems in Southeast Asian rail networks delay replacement cycles due to capital allocation constraints.
Strategic Opportunities
- Vietnam and Indonesia urban rail expansion:Greenfield metro projects in Ho Chi Minh City and Jakarta represent untapped demand for light rail battery systems.
- Solid-state battery R&D:METI-directed subsidies in Japan are accelerating prototype development for next-generation Shinkansen auxiliary power applications.
- Battery-ultracapacitor hybrid architectures:Convergent energy storage technologies are opening specification windows for stop-start urban routes with frequent acceleration profiles.
Industry Challenges
- Thermal management engineering talent scarcity:Rail-specific battery system integration requires specialized expertise in high-voltage safety and cell balancing that outpaces training pipeline output.
- Multi-jurisdiction certification complexity:India's BIS performance mandates, China's GB standards, and Japan's JIS certifications create overlapping compliance burdens for pan-Asia-Pacific suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Train Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Cadmium, Lead-Acid, Sodium-Sulfur Application: Passenger Trains, Freight Trains, High-Speed Trains, Light Rail Technology: Rechargeable, Fast Charging, Ultra-Capacitor, Hybrid End User: Rail Operators, Government Agencies, Freight Companies, Private Rail |
| Companies Covered | EnerSys, CATL, GS Yuasa Corporation, Furukawa Electric Co., Ltd., BYD Company, Exide Industries, Amara Raja Batteries, Shuangdeng Group Co., Ltd, Saft, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Train Battery Market Evolving Landscape
Cell-to-pack architectures are compressing system-level costs while regulatory pressure on thermal runaway containment is reshaping safety engineering priorities across the Asia-Pacific rail supply base.
Lithium iron phosphate chemistry is decomposing the historical cost-performance tradeoff in metro energy storage applications. Chinese state rail operators are specifying LFP-dominant configurations for new rolling stock procurements. This chemistry shift is decomposing nickel-cobalt supply chain dependencies while extending cycle life specifications beyond 1,500 cycles.
China's MIIT GB standards for rail battery safety and recycling are mandating cell-level thermal runaway propagation containment. Manufacturers must redesign pack architectures with ceramic separators and pressure-relief venting. High-speed train segments face the steepest compliance costs, with some suppliers withdrawing from premium thermal management specification tiers.
Rolling stock OEMs are consolidating supplier relationships around vertically integrated cell producers capable of delivering certified traction battery systems. Japanese Shinkansen operators now require JIS-certified manufacturing footprints for auxiliary power contracts. This buyer concentration is most visible in Australia's urban rail procurement, where state transport authorities are pre-qualifying only two to three battery system vendors per tender.
Asia-Pacific Train Battery Market Segmentation
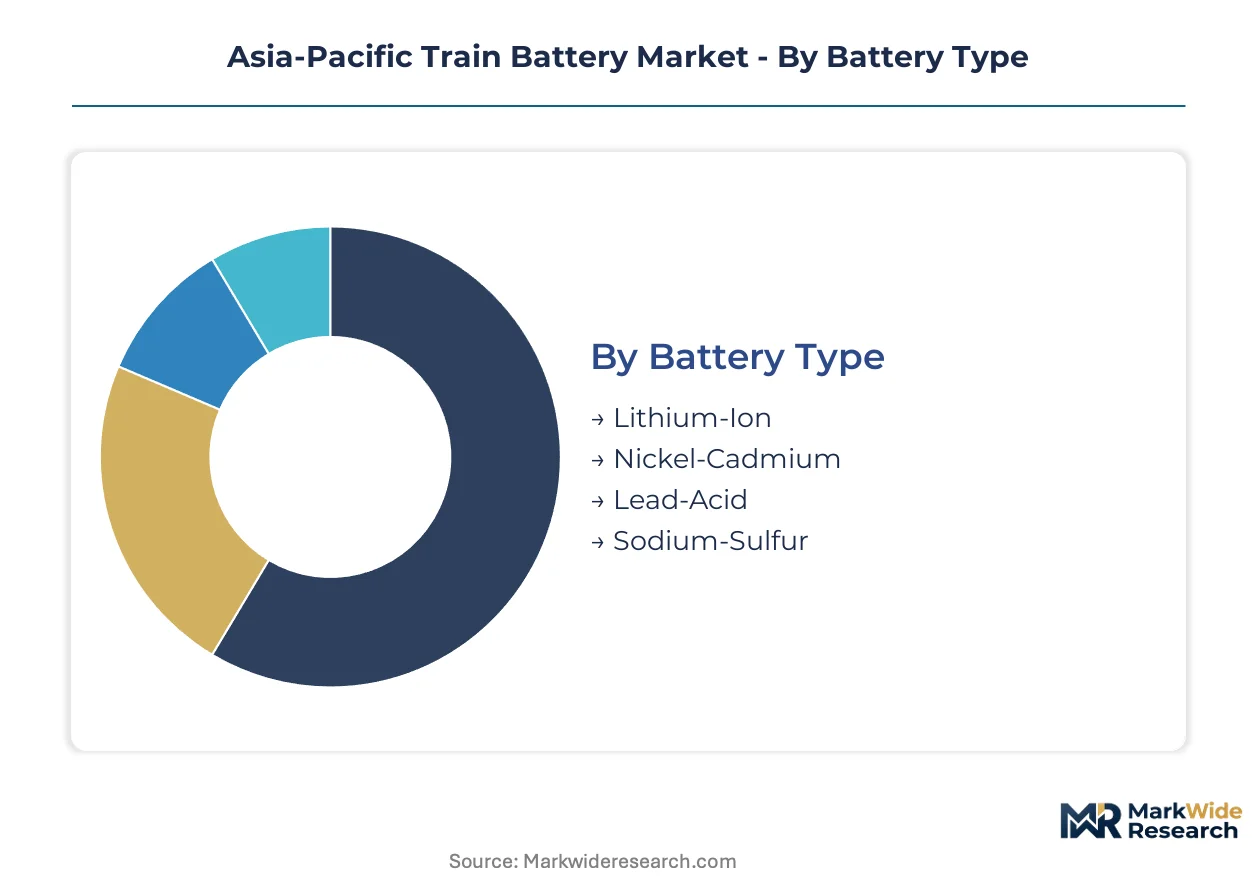
Rolling stock electrification across Asia-Pacific creates divergent procurement specifications based on duty cycle intensity and thermal management requirements. Battery chemistry selection, application context, and charging infrastructure availability determine system architecture decisions for rail operators.
Battery Type:
Lithium-ion specifications are displacing legacy chemistries fastest where cycle life requirements exceed 1,000 charge cycles and weight penalties constrain rolling stock design.
- Lithium-Ion:Cell configurations rated for 800 to 1,500 cycles at minus 20 to 55 degrees Celsius dominate new procurements from Chinese state rail operators and Indian metro authorities. Energy density advantages reduce axle load penalties while supporting regenerative braking integration on high-speed corridors.
- Nickel-Cadmium:Legacy installed base in Southeast Asian rail networks persists due to capital allocation constraints and established maintenance protocols. JIS-certified manufacturing for Japanese Shinkansen auxiliary systems sustains residual demand despite lithium-ion substitution pressure.
- Lead-Acid:Lowest first-cost option for non-traction auxiliary loads in heritage rolling stock and maintenance vehicles where energy density requirements are minimal.
- Sodium-Sulfur:High-temperature operation chemistry attracts pilot deployments for stationary rail yard energy storage applications requiring extended discharge duration.
Lithium-ion retains volume leadership; sodium-sulfur holds the steepest expansion curve among emerging chemistries.
Application:
Stop-start duty profiles in urban environments impose distinct power density requirements versus constant-load long-haul operations.
- High-Speed Trains:Stringent thermal management specifications for traction batteries operating at sustained high discharge rates. China's MIIT GB standards mandate cell-level thermal runaway containment, compressing supplier qualification timelines for premium system tiers.
- Light Rail:Fastest-expanding installation base as Ho Chi Minh City, Jakarta, and Southeast Asian capitals commission greenfield metro networks. Frequent acceleration profiles favor hybrid configurations pairing batteries with ultra-capacitors.
- Passenger Trains:Suburban rail modernization programs in India drive demand for auxiliary power systems with extended cycle life specifications.
- Freight Trains:Diesel-electric hybrid conversions for last-mile yard operations create niche demand for high-power-density configurations.
Light rail is expanding most quickly; high-speed trains command premium margin pools through compliance-intensive specifications.
Technology:
Charging infrastructure availability and route electrification status determine technology selection across Asia-Pacific rail networks.
- Rechargeable:Volume leadership maintained through established supply chains for lithium-ion cell-to-pack architectures serving continuously electrified corridors.
- Hybrid:Battery-ultracapacitor convergent architectures gain specification traction for urban routes with frequent stops. Japanese METI-directed R&D subsidies accelerate prototype development for next-generation configurations.
- Fast Charging:Opportunity charging systems for light rail applications with partial route electrification and mid-route power pickup infrastructure.
- Ultra-Capacitor:Standalone configurations for kinetic energy recovery in stop-start duty cycles where battery cycle life degradation is uneconomical.
Rechargeable systems anchor current procurement volumes; hybrid configurations are climbing the fastest as urban route specifications evolve.
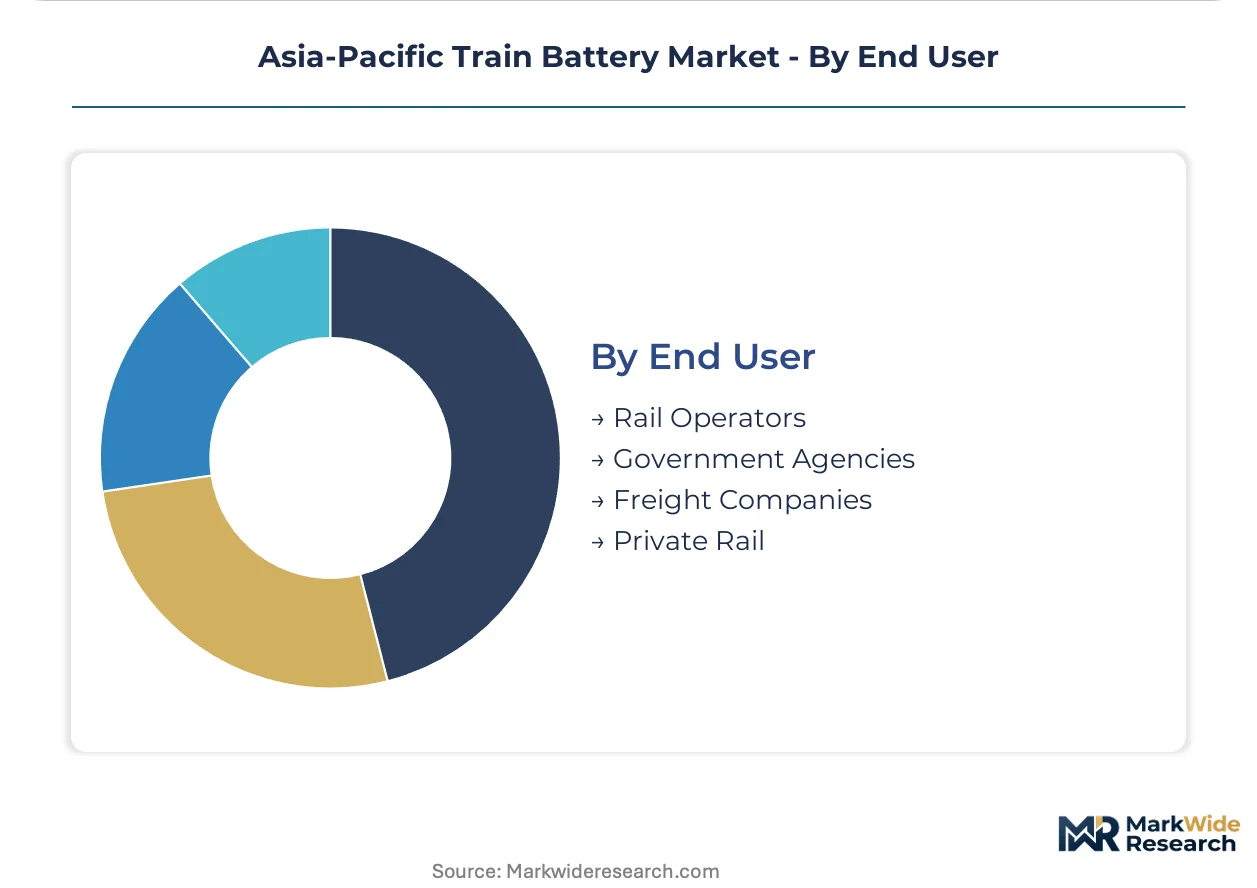
End User:
Public procurement frameworks concentrate purchasing power while private operators prioritize total cost of ownership optimization.
- Rail Operators:State-owned enterprises in China and India consolidate supplier relationships around vertically integrated cell producers capable of delivering certified traction battery systems. Pre-qualification requirements limit vendor pools to two or three certified suppliers per tender.
- Government Agencies:India's PLI scheme for advanced chemistry cells redirects procurement toward domestic lithium-ion manufacturing capacity, reducing import dependency for publicly funded rail infrastructure.
- Freight Companies:Private logistics operators evaluate battery-electric multiple units for terminal switching operations based on fuel cost arbitrage versus diesel alternatives.
- Private Rail:Japanese Shinkansen operators require JIS-certified manufacturing footprints, sustaining premium supplier margins through compliance barriers.
Rail operators retain volume leadership; government agencies are gaining share fastest through localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific's train battery trade flows reflect a regional surplus in cell manufacturing capacity against concentrated demand from state rail electrification programs. Import dependency for finished battery packs persists in Southeast Asian markets lacking domestic cell fabrication, while China and South Korea anchor export supply.
China
State rail operators are electrifying high-speed corridors at scale, driving procurement volumes for lithium-ion traction systems. MIIT enforces GB standards for rail battery safety and recycling, compressing supplier qualification timelines. The Yangtze River Delta cluster hosts vertically integrated cell producers serving rolling stock OEMs with certified pack architectures.
India
Suburban rail modernization and metro fleet expansion in Mumbai, Delhi, and Bangalore create sustained demand pipelines. The PLI scheme for advanced chemistry cell manufacturing redirects procurement toward domestic lithium-ion capacity and reduces import dependency. Tamil Nadu and Gujarat are emerging as cell manufacturing hubs with rail-specific certification infrastructure.
Japan
Shinkansen auxiliary power system replacements and next-generation solid-state R&D sustain premium battery demand. METI directs subsidies toward prototype development for future rail applications. The Kansai industrial corridor maintains JIS-certified manufacturing footprints for domestic rail operator contracts.
South Korea
MFDS-aligned industrial standards shape import compliance for traction battery systems deployed on Korail infrastructure. Seoul's metropolitan rail expansion drives demand for light rail energy storage configurations. The Busan-Ulsan manufacturing belt supplies cell technologies to regional rolling stock integrators.
Australia
State transport authorities in New South Wales and Victoria are pre-qualifying limited vendor pools for urban rail battery tenders. TGA-equivalent rail safety frameworks reshape compliance requirements for imported traction systems. Sydney and Melbourne metro electrification programs represent the primary demand concentration.
Asia-Pacific Train Battery Market Competitive Landscape
Concentration sits with vertically integrated cell producers capable of delivering certified traction battery systems to state rail operators. The supplier base stratifies between large-scale chemistry specialists and regionally focused pack integrators. Three archetypes dominate: captive cell producers with rail-dedicated lines, independent battery system houses, and diversified industrial conglomerates with energy storage divisions. Competitive moves center on backward integration into cathode active material supply and geographic expansion through JIS or BIS certification acquisition.
Among Asia-Pacific-based producers, CATL, GS Yuasa Corporation, and BYD Company exemplify the vertically integrated archetype. CATL represents the scale-driven cell-to-pack model anchoring Chinese state rail contracts. GS Yuasa Corporation occupies a position within Japan's premium certification tier for Shinkansen auxiliary systems. BYD Company sits within the in-house chemistry control segment, leveraging captive lithium iron phosphate production for metro energy storage applications.
| Leading Market Players |
|---|
| EnerSys |
| CATL |
| GS Yuasa Corporation |
| Furukawa Electric Co., Ltd. |
| BYD Company |
| Exide Industries |
| Amara Raja Batteries |
| Shuangdeng Group Co., Ltd |
| Saft |
| Others |
Value Network & Pricing Analysis
China's MIIT GB standards for rail battery safety and recycling gate both supplier qualification timelines and price differentiation across certification tiers simultaneously. Buyers face compressed vendor pools alongside steep compliance premiums for thermal runaway containment specifications.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on JIS certification grade and volume scale, with Shinkansen auxiliary contracts commanding premiums against Indian metro bulk tenders. Cost compression in standard-tier lithium-ion packs is intensifying because Chinese state rail operators consolidate procurement around cell-to-pack architectures. Freight companies and private logistics operators exhibit highest price sensitivity, while Japanese Shinkansen authorities prioritize certification compliance over unit cost.
Supply Chain Analysis
Rolling stock OEMs maintain strategic stockpiles of cathode active materials rather than just-in-time cathode powder deliveries given lithium carbonate spot volatility. Cell manufacturing concentrates in China, South Korea, and Japan, with pack assembly drawing from Vietnam and Thailand for Southeast Asian rail projects. Raw material dependencies center on lithium carbonate, nickel sulfate, and cobalt hydroxide refined through Chinese chemical processing hubs. Single-source vulnerability in East Asian cell supply creates geographic concentration risk for Indian and Australian operators. Distribution runs through state rail procurement authorities with pre-qualified vendor pools limiting channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific train battery incumbents face substitution defense against solid-state chemistry prototypes and hybrid ultracapacitor architectures reshaping next-generation specifications.
For Market Incumbents: Fortify JIS-certified manufacturing footprints to lock in Shinkansen auxiliary replacement cycles. Deepen backward integration into lithium iron phosphate cathode production to offset raw material volatility. Secure long-term offtake agreements with Chinese state rail operators before solid-state prototypes reach commercial scale.
For New Entrants and Emerging Players: Differentiate on battery-ultracapacitor hybrid system integration for stop-start urban routes in Ho Chi Minh City and Jakarta. Target Vietnam and Indonesia greenfield metro projects where incumbent certification barriers remain lowest. Lead with fast-charging infrastructure partnerships rather than standalone cell supply.
For Investors and Strategic Acquirers: India's PLI scheme for advanced chemistry cells reshapes the acquisition landscape toward domestic lithium-ion manufacturing capacity. Five-to-ten-year viability favors vertically integrated cell producers with rail-specific certification infrastructure. Target acquisition archetypes include mid-scale pack integrators holding BIS pre-qualification status. Revision becomes warranted when solid-state prototype timelines accelerate or lithium carbonate price floors breach operational thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive lithium iron phosphate production insulates BYD Company from carbonate spot volatility. |
| JIS Certification Acquisition | GS Yuasa Corporation sustains Shinkansen margins through manufacturing footprint compliance barriers. |
| Battery-Ultracapacitor Hybrid Development | Japanese METI subsidies accelerate prototype deployment for next-generation urban rail configurations. |
| Domestic Cell Manufacturing Scale-Up | India's PLI scheme redirects Tamil Nadu and Gujarat capacity toward Indian Railways traction demand. |
| Thermal Management Engineering Talent Recruitment | Specialized high-voltage safety expertise scarcity constrains pack integrator expansion timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with rail procurement officers, battery system engineering directors, and rolling stock OEM sourcing leads; and secondary validation through MIIT GB standard filings, Indian Railways tender documentation, and Japanese METI subsidy disclosures. Bottom-up cell shipment estimates triangulated against top-down rolling stock electrification capex projections.
Across the analysis window, forecasts model battery type, application duty cycle, technology configuration, and end-user procurement framework dimensions. CAGRs derive from segment-level volume build-ups calibrated to stated electrification targets and replacement cycle assumptions. Industry-specific inputs include regenerative braking adoption curves and thermal management specification tier penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate supply expansion or accelerated solid-state commercialization timelines would require recalibration. Forecasts reflect assumptions around PLI scheme disbursement continuity and GB standard enforcement intensity. Revision becomes warranted when hybrid ultracapacitor specification adoption crosses threshold penetration in Southeast Asian urban rail tenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Solar Car Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Used EV Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
E-Bike Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
EV Condenser Market