
 China Courier, Express, and Parcel (CEP) Market | 2026-2036
China Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
China Courier, Express, and Parcel (CEP) Market Insights
Autonomous sorting robotics is rewriting fulfillment economics for Chinese logistics networks. SF Express leverages its captive air fleet to sustain next-day coverage across all provincial capitals. JD Logistics anchors same-day delivery through in-house warehousing density in Beijing, Shanghai, and Guangzhou. ZTO Express dominates automated parcel hubs to control unit costs at scale.
Courier, Express, and Parcel services constitute a multi-modal logistics system encompassing document envelopes, standard parcels, and palletized freight transported via ground fleets, air cargo, and emerging drone networks. The system operates through hub-and-spoke distribution architecture with automated sortation, real-time tracking protocols, and last-mile handoff to residential or commercial endpoints. Standard delivery occupies the largest volume pool across service types, while same-day delivery captures premium pricing from urban consumers. E-commerce end users generate the dominant flow of parcels, though healthcare cold-chain shipments represent the fastest-growing margin segment.
MIIT enforces data security standards on logistics platforms under national cyberspace governance frameworks, while SAMR monitors anti-competitive pricing and merchant exclusivity arrangements in express delivery. GB standards mandate packaging material recyclability and electric vehicle adoption ratios for urban delivery fleets. Stakeholders must weigh regulatory compliance costs against automation returns when allocating capital across hub upgrades and last-mile drone deployment.
Market Dynamics
Autonomous sorting robotics and real-time route optimization algorithms are compressing per-package fulfillment costs while expanding serviceable geographies across China's interior provinces. This technological inflection is redrawing competitive boundaries between asset-heavy integrators and platform-dependent carriers.
Growth Catalysts
- E-commerce penetration in tier-three cities:Live-streaming commerce platforms activate first-time parcel demand in lower-tier urban clusters previously underserved by express networks.
- GB standards for electric vehicle fleets:Municipal mandates for zero-emission last-mile delivery accelerate fleet turnover and unlock carbon credit monetization for compliant operators.
- Cold-chain pharmaceutical logistics:Biologics distribution requirements under NMPA temperature-control guidelines create premium service tiers with structurally higher margins than standard parcels.
Market Restraints
- Labor cost escalation in coastal hubs:Warehouse operator wages in the Yangtze River Delta have risen faster than automation depreciation schedules can offset.
- Aviation slot scarcity:Peak-season air cargo capacity constraints at Shenzhen Bao'an and Shanghai Pudong limit express carriers' next-day coverage guarantees.
- Packaging material cost volatility:Recycled corrugated board prices fluctuate with pulp import dependencies, compressing unit economics for high-volume shippers.
Strategic Opportunities
- Cross-border e-commerce corridors:China-Europe rail freight integration enables parcel consolidation at Xi'an and Zhengzhou hubs for 12-day delivery to EU consumers.
- Rural drone delivery networks:MIIT experimental airspace approvals in Sichuan and Yunnan provinces permit beyond-visual-line-of-sight operations for mountain village distribution.
- Carbon accounting services:SAMR disclosure requirements for scope-three emissions create demand for logistics-specific carbon footprint verification tools.
Industry Challenges
- Sorting technician skill gaps:Automated hub operations require mechatronics competencies that vocational training pipelines have not scaled to match deployment timelines.
- Multi-platform data interoperability:Proprietary tracking protocols between competing e-commerce marketplaces fragment visibility for merchants using multiple channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Courier, Express, and Parcel (CEP) Market |
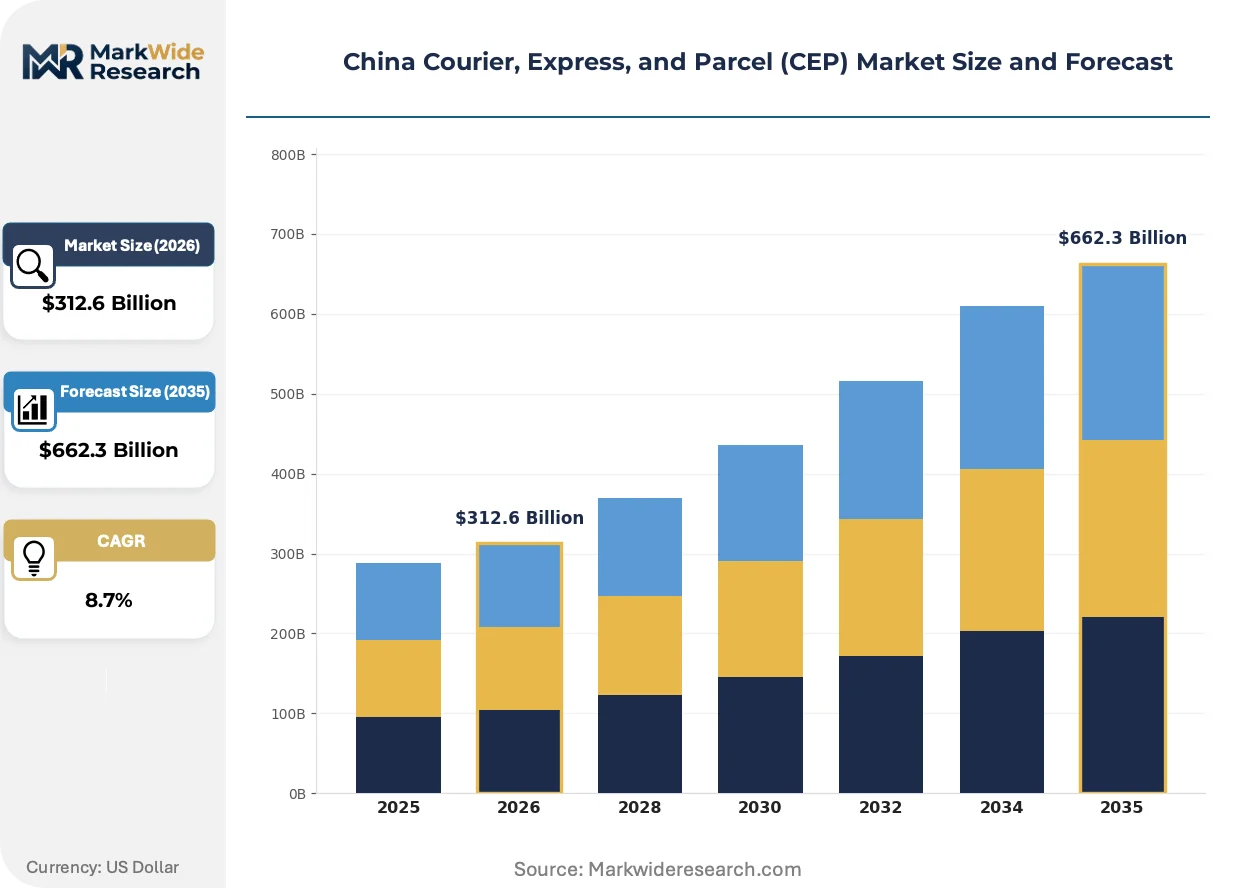
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Delivery, Same-Day Delivery, Next-Day Delivery End User: E-Commerce, Retail, Healthcare, Manufacturing Delivery Mode: Ground, Air, Sea, Drone Package Type: Parcel, Document, Pallet, Envelope |
| Companies Covered | ZTO Express, SF Express, YTO Express, STO Express, Yunda Express, China Post, JD Logistics, Best Inc., Deppon Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital twin simulations of hub operations are enabling predictive capacity planning that reduces peak-season congestion. These modeling capabilities represent a shift from reactive volume absorption to anticipatory network design across China's express infrastructure.
Computer vision-based parcel dimensioning is digitizing manual measurement workflows at sortation facilities. Third-party logistics providers deploy these systems to eliminate dimensional weight disputes with e-commerce merchants. The technology is digitizing rate negotiation dynamics by introducing objective volumetric data into contract terms.
SAMR enforcement actions against merchant exclusivity arrangements are restructuring platform-carrier contracting norms. The regulator's scrutiny of "choose one" clauses forces e-commerce marketplaces to open supplier access to multiple express providers. Cross-border merchants in Guangdong free-trade zones now route parcels through competing networks to mitigate concentration risk.
Subscription-based delivery memberships are displacing per-shipment pricing for high-frequency urban consumers. Young professionals in Chengdu and Hangzhou purchase annual unlimited-delivery passes from integrated retail-logistics platforms. This behavioral shift locks in volume commitments while shifting revenue recognition from transactional to recurring models.
China Courier, Express, and Parcel (CEP) Market Segmentation
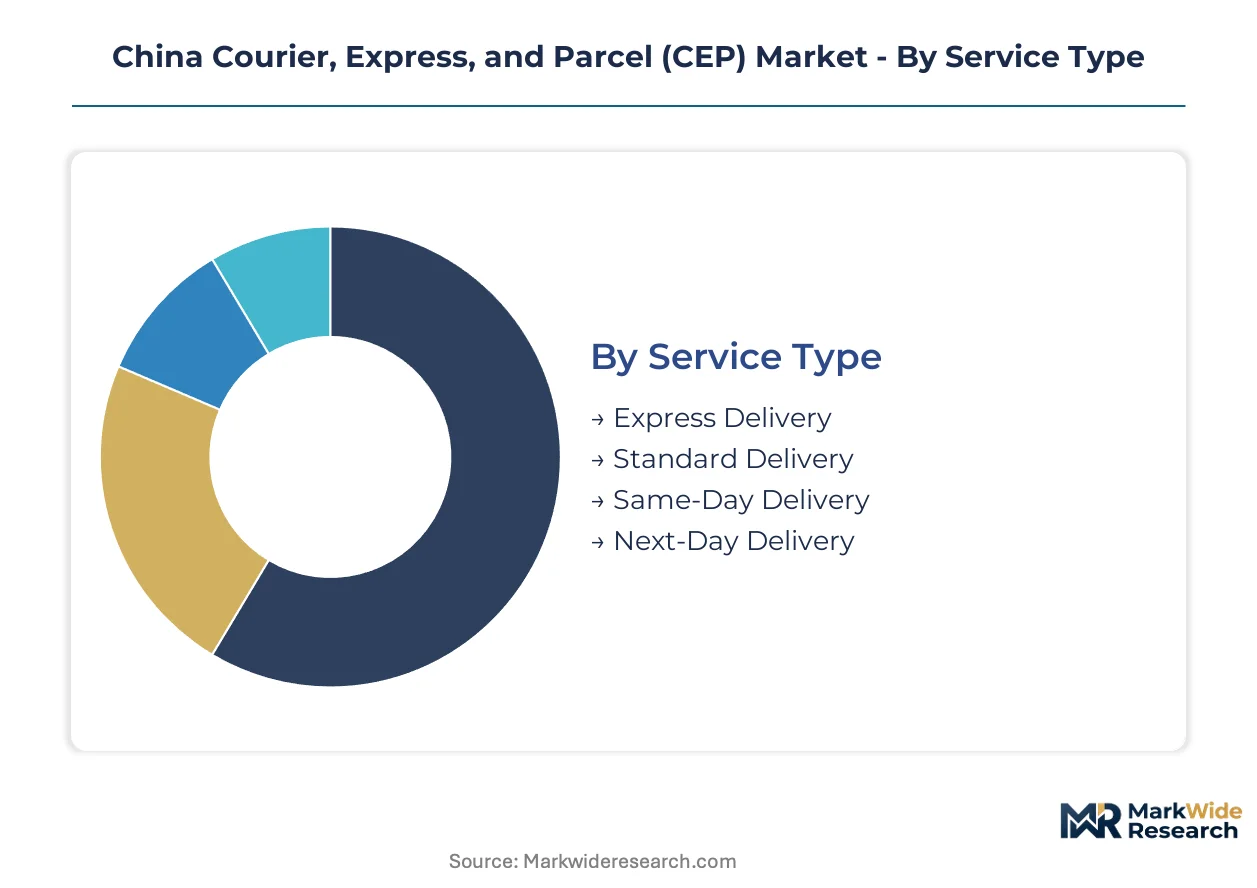
CEP market segmentation reveals distinct operational economics across service tiers, with automation feasibility and labor intensity varying sharply between express and standard delivery. Understanding these structural differences guides capital allocation toward high-margin segments.
Service Type:
After-sales service intensity escalates from standard delivery through same-day and next-day tiers, with premium segments requiring dedicated customer support infrastructure and real-time exception handling.
- Express Delivery:Time-definite service with guaranteed delivery windows and proactive shipment monitoring. Demand concentrates in Yangtze River Delta manufacturing corridors where just-in-time supply chains penalize delays. NMPA pharmaceutical distribution mandates drive temperature-validated express adoption.
- Standard Delivery:Non-time-critical ground transport with consolidated sorting and flexible routing. Volume pools in tier-three cities activated by live-streaming commerce platforms. GB packaging recyclability standards add compliance costs per unit.
- Same-Day Delivery:Urban-centric fulfillment requiring hyperlocal warehousing density. JD Logistics deploys this tier through captive Beijing, Shanghai, and Guangzhou distribution centers.
- Next-Day Delivery:Air-enabled coverage leveraging overnight hub operations. SF Express sustains provincial capital coverage through captive freighter fleet deployment.
By volume, Standard Delivery leads. By growth pace, Same-Day Delivery is ahead.
End User:
Customer concentration patterns diverge across B2C e-commerce and B2B manufacturing accounts, with procurement scale and contract duration shaping carrier negotiation leverage.
- E-Commerce:Platform-aggregated parcel flows with high frequency and low per-shipment value. Cross-border merchants in Guangdong free-trade zones route through competing networks to mitigate concentration risk under SAMR exclusivity scrutiny.
- Healthcare:Cold-chain biologics distribution under NMPA temperature-control guidelines. Structurally higher margins than standard parcels with validated packaging and chain-of-custody documentation.
- Retail:Omnichannel replenishment bridging physical storefronts and digital order fulfillment. Seasonal volume spikes align with promotional calendars.
- Manufacturing:Spare parts and production input logistics with penalty clauses for delivery failures. Electronics clusters in Pearl River Delta generate consistent B2B express demand.
E-Commerce commands absolute parcel volume. Healthcare posts the steepest expansion trajectory.
Delivery Mode:
Modal selection reflects the trade-off between unit cost and transit velocity, with infrastructure availability constraining options in interior provinces.
- Ground:Dominant mode for intra-provincial and short-haul intercity flows. ZTO Express controls automated hub economics at scale.
- Air:Essential for next-day coverage guarantees across provincial capitals. Aviation slot scarcity at Shenzhen Bao'an and Shanghai Pudong limits peak-season capacity.
- Sea:Bulk parcel consolidation for cross-border corridors, notably China-Europe rail freight integration at Xi'an and Zhengzhou hubs.
- Drone:Experimental beyond-visual-line-of-sight operations in Sichuan and Yunnan mountain villages under MIIT airspace approvals.
Ground transport handles the greatest shipment mass. Drone networks are climbing the fastest.
Package Type:
Physical characteristics determine sortation automation compatibility and dimensional pricing structures.
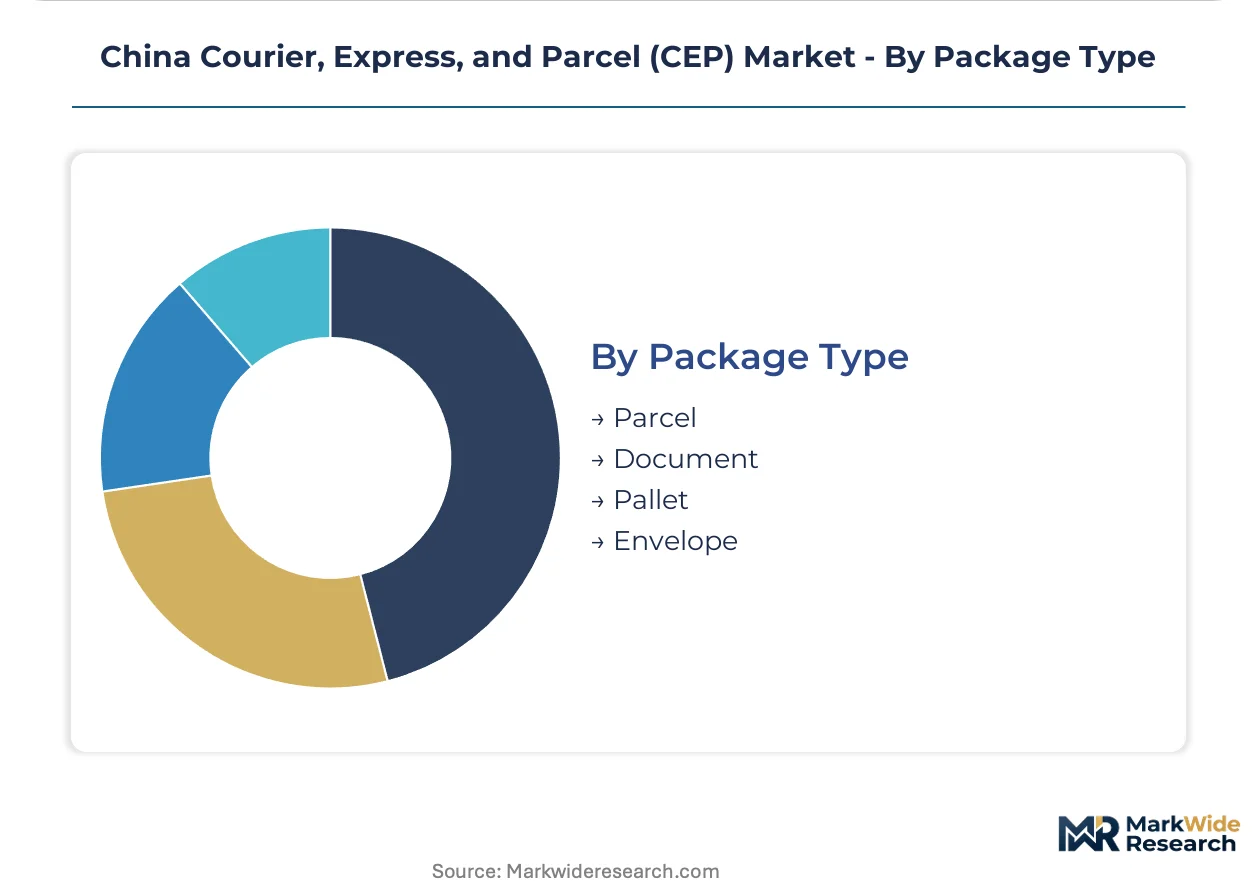
- Parcel:Standardized corrugated containers forming the volume base. Computer vision dimensioning systems digitize volumetric rate negotiations.
- Document:Lightweight envelope formats with premium security protocols. Financial and legal sectors sustain demand despite digital displacement.
- Pallet:Unitized freight at the CEP boundary, requiring specialized handling equipment. Manufacturing B2B flows dominate this tier.
- Envelope:Flat-format documents and small items with minimal sortation complexity. Cross-border e-commerce samples utilize this format.
Parcels generate the highest absolute throughput. Palletized freight is gaining share fastest in manufacturing logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic e-commerce merchants and cross-border traders dominate parcel procurement decisions across China's regional logistics corridors. Manufacturing clusters and live-streaming commerce hubs generate divergent volume patterns. Regulatory frameworks from MIIT and SAMR reshape network investments province by province.
Yangtze River Delta
Pharmaceutical cold-chain shipments and semiconductor just-in-time logistics drive premium express demand across Shanghai, Jiangsu, and Zhejiang. NMPA temperature-control guidelines mandate validated packaging for biologics distribution. Suzhou and Hangzhou host dense automated sortation hubs where ZTO Express and SF Express compete for manufacturing accounts.
Pearl River Delta
Cross-border e-commerce merchants in Guangdong free-trade zones route parcels through competing networks under SAMR exclusivity scrutiny. GB standards for packaging recyclability add compliance costs per unit shipped. Shenzhen Bao'an aviation slot scarcity limits peak-season air cargo capacity for next-day guarantees.
Beijing-Tianjin-Hebei
JD Logistics anchors same-day delivery through captive warehousing density in Beijing municipal boundaries. Municipal zero-emission fleet mandates accelerate electric vehicle turnover for last-mile operators. Tianjin port consolidation enables sea-air intermodal options for Northeast Asian export corridors.
Sichuan-Chongqing
MIIT experimental airspace approvals permit beyond-visual-line-of-sight drone operations for mountain village distribution. Live-streaming commerce platforms activate first-time parcel demand in tier-three cities previously underserved by express networks. Chengdu subscription-based delivery memberships displace per-shipment pricing for urban professionals.
Shandong Peninsula
Automotive spare parts logistics and agricultural cold-chain shipments generate consistent B2B express volume. SAMR monitors anti-competitive pricing arrangements among regional carriers. Qingdao and Yantai ports serve as consolidation nodes for Korea-Japan maritime parcel corridors.
China Courier, Express, and Parcel (CEP) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Asset-heavy integrators with captive air fleets and warehousing density face platform-dependent carriers leveraging e-commerce volume aggregation. Strategic archetypes include captive-network operators, automation-scale specialists, and platform-integrated fulfillers. Capacity expansion at automated hubs and cross-border corridor partnerships constitute the dominant competitive moves reshaping market boundaries.
Within the captive-network tier, SF Express and JD Logistics exemplify asset-heavy positioning through controlled infrastructure. ZTO Express occupies a position among automation-scale specialists leveraging hub economics. These three entities represent divergent capital allocation strategies across air cargo, warehousing, and sortation robotics.
| Leading Market Players |
|---|
| ZTO Express |
| SF Express |
| YTO Express |
| STO Express |
| Yunda Express |
| China Post |
| JD Logistics |
| Best Inc. |
| Deppon Logistics |
| Others |
Pricing and Supply Chain Analysis
China-Europe rail freight corridors at Xi'an and Zhengzhou hubs concentrate cost dynamics that ripple through both upstream supply concentration and downstream price differentiation across express delivery tiers. GB standards compliance for electric vehicle fleets and packaging recyclability add regulatory-indexed cost layers that carriers pass through via contract structures tied to fuel and material indices.
Pricing Analysis
Cost-plus contracts with fuel surcharge indexation dominate B2B manufacturing accounts in the Yangtze River Delta, where just-in-time penalty clauses amplify price sensitivity. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery velocity and temperature-validation requirements, with cold-chain pharmaceutical shipments commanding the widest spreads. Cost compression in standard delivery intensifies because live-streaming commerce platforms aggregate high-volume, low-margin parcel flows from tier-three cities. E-commerce merchants show highest price sensitivity, while healthcare distributors under NMPA guidelines accept premium positioning for validated chain-of-custody documentation.
Supply Chain Analysis
MIIT data security frameworks and SAMR exclusivity enforcement function as de facto export-control regimes limiting cross-border data flows and platform-carrier integration depth. Automated sorting equipment concentrates supply in Germany, Japan, and South Korea, while electric vehicle drivetrains and battery systems draw from domestic Chinese manufacturing clusters. Single-source vulnerability in aviation slot allocation at Shanghai Pudong and Shenzhen Bao'an constrains peak-season air cargo expansion. Distribution runs through hub-and-spoke architecture with automated sortation feeding last-mile ground fleets and emerging drone networks in Sichuan and Yunnan provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based delivery memberships and carbon accounting services represent service-attach layers expanding faster than core parcel throughput, creating recurring revenue architectures that decouple carrier economics from per-shipment volatility.
For Market Incumbents: Build captive air fleet density as the primary moat against platform-dependent carriers lacking overnight coverage guarantees. SF Express and JD Logistics should deepen automation-scale investments at Yangtze River Delta hubs to offset coastal wage escalation faster than depreciation schedules allow. SAMR exclusivity scrutiny threatens merchant lock-in strategies, making multi-platform data interoperability infrastructure a defensive priority.
For New Entrants and Emerging Players: Rural drone delivery networks in Sichuan and Yunnan provinces under MIIT experimental airspace approvals represent the most penetrable entry point with limited incumbent automation deployment. Cold-chain pharmaceutical logistics for biologics distribution offers structurally higher margins than standard parcels with lower volume concentration risk. Partner with cross-border e-commerce merchants in Guangdong free-trade zones to build corridor-specific consolidation expertise before scaling.
For Investors and Strategic Acquirers: Automation-scale specialists with hub economics dominance but limited captive air coverage offer the most compelling acquisition target archetype for portfolio assembly. Long-term viability across the analysis window hinges on regulatory compliance cost absorption versus automation return thresholds. Watch for MIIT drone airspace approval expansion beyond Sichuan and Yunnan as the signal indicating rural network economics have crossed viability thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Hub Capacity Expansion | ZTO Express-style robotics deployment compresses per-package sortation costs below labor-intensive competitors. |
| Cold-Chain Certification Investment | NMPA temperature-control compliance unlocks biologics distribution premiums above standard parcel economics. |
| Drone Network Pilot Scaling | MIIT beyond-visual-line-of-sight approvals in mountain provinces extend serviceable geography without ground infrastructure. |
| Subscription Membership Platform Launch | JD Logistics-style annual passes shift revenue recognition from transactional volatility to recurring predictability. |
| Cross-Border Rail Corridor Partnership | Xi'an and Zhengzhou hub integration enables parcel consolidation for EU delivery within competitive time windows. |
Research Methodology
Cross-validation between primary interviews with express carrier operations directors, e-commerce platform logistics managers, and pharmaceutical supply chain executives anchors the qualitative findings against secondary validation from MIIT policy circulars, SAMR enforcement notices, and GB standards documentation. Bottom-up volume modeling triangulates with top-down macroeconomic consumption indicators to constrain forecast variance across the projection horizon.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the analytical framework across service type, end user, delivery mode, and package type segmentation dimensions. CAGRs derive from logistic curve fitting to technology adoption patterns and infrastructure deployment schedules. Cold-chain pharmaceutical logistics penetration and autonomous sorting robotics deployment density serve as industry-specific forecast inputs.
Practitioners should monitor MIIT drone airspace approval expansion, SAMR exclusivity enforcement intensity, and GB standards electric vehicle mandate acceleration for early signals of structural shift. Material shifts in aviation slot allocation policy or cross-border rail corridor tariff structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market