
 Netherlands Freight and Logistics Market | 2026-2036
Netherlands Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Freight and Logistics Market Foresight
Belgium's Antwerp-Bruges port expansion is reshaping North Sea freight competition and redirecting transshipment volumes toward Dutch inland networks. DB Schenker leverages its integrated rail-road terminals near Venlo to sustain cross-border pharmaceutical distribution. Kuehne + Nagel International AG anchors temperature-controlled warehousing along the Rotterdam corridor, while DSV competes through specialized project-cargo operations serving North Sea offshore energy.
Netherlands freight and logistics encompasses the coordinated movement, storage, and customs facilitation of goods through multimodal networks centered on Europe's largest seaport at Rotterdam, with operations governed by EU customs union protocols and standardized container handling specifications. The sector's primary commercial purpose is to function as Western Europe's maritime gateway, connecting Rhine-Meuse-Scheldt delta waterways to continental distribution networks. Transportation services dominate revenue flows given Rotterdam's throughput volumes, while freight forwarding commands premium margins due to customs complexity and EU regulatory navigation. Warehousing is expanding fastest around E-commerce end users, though automation technology deployment remains concentrated among large integrated operators serving manufacturing supply chains.
The Dutch Human Environment and Transport Inspectorate enforces EU Mobility Package driving-hour limits and cabotage restrictions that constrain road haulage capacity and elevate intermodal demand. REACH and EU Green Deal emissions standards mandate fleet decarbonization and alternative fuel infrastructure investment across port zones. Stakeholders must monitor how EU Carbon Border Adjustment Mechanism implementation reshapes customs brokerage complexity and whether inland waterway congestion triggers permanent modal reallocation toward rail corridors through Germany.
Market Dynamics
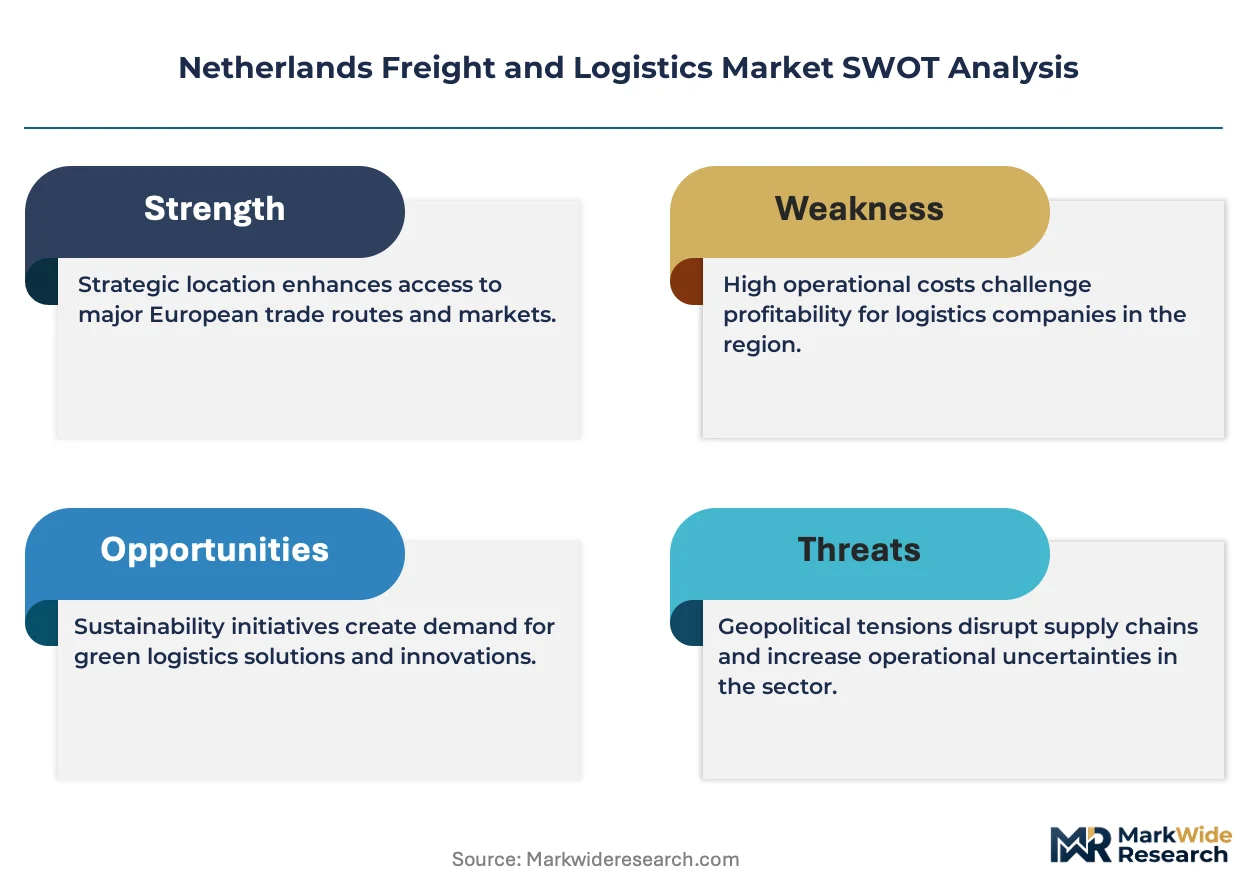
The EU Green Deal's emissions mandates are compressing road haulage margins and forcing modal reallocation toward rail and inland waterway corridors through the Rhine-Meuse-Scheldt delta. Rotterdam port operators face simultaneous pressure to electrify yard equipment and expand hydrogen bunkering infrastructure.
Growth Catalysts
- EU Green Deal decarbonization mandates:The regulation is accelerating fleet electrification and alternative fuel infrastructure investment across Dutch port zones. Barge operators gain competitive advantage on Amsterdam-Rotterdam-Antwerp corridors.
- Pharmaceutical cold-chain expansion:Temperature-controlled warehousing demand is surging around Schiphol and Rotterdam corridors. Biologics manufacturers require validated GDP-compliant distribution networks.
- E-commerce fulfillment concentration:Automated distribution centers are clustering in North Brabant and Gelderland provinces. Same-day delivery expectations are compressing last-mile radius requirements.
Market Restraints
- EU Mobility Package driving-hour limits:The regulation constrains road haulage capacity and elevates driver recruitment costs. Cabotage restrictions limit cross-border fleet utilization.
- Inland waterway congestion bottlenecks:Rhine water level volatility disrupts container barge schedules. Terminal operators face demurrage cost volatility during low-water periods.
- Alternative fuel infrastructure gaps:Hydrogen and electric charging networks remain sparse along A15 and A12 motorway corridors. Fleet operators defer vehicle replacement decisions.
Strategic Opportunities
- Maasvlakte automated terminal expansion:Deep-water berth capacity is creating transshipment volume capture from Antwerp-Bruges competition. Mega-vessel handling capability attracts Asia-Europe loop rotations.
- Carbon Border Adjustment Mechanism compliance services:The EU regulation is generating customs brokerage complexity premiums. Forwarders can embed carbon accounting into documentation workflows.
- Battery-electric short-sea integration:Converging shore power and vessel electrification technologies enable zero-emission feeder operations. North Sea port rotation networks favor early adopters.
Industry Challenges
- Intermodal synchronization complexity:Rail terminal dwell times and barge schedule reliability create inventory buffer requirements. Shippers demand real-time visibility across modal handoffs.
- WMS-TMS integration legacy debt:Mid-sized forwarders operate fragmented IT stacks that obstruct automation deployment. Cloud migration timelines extend due to customs data localization requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Freight and Logistics Market |
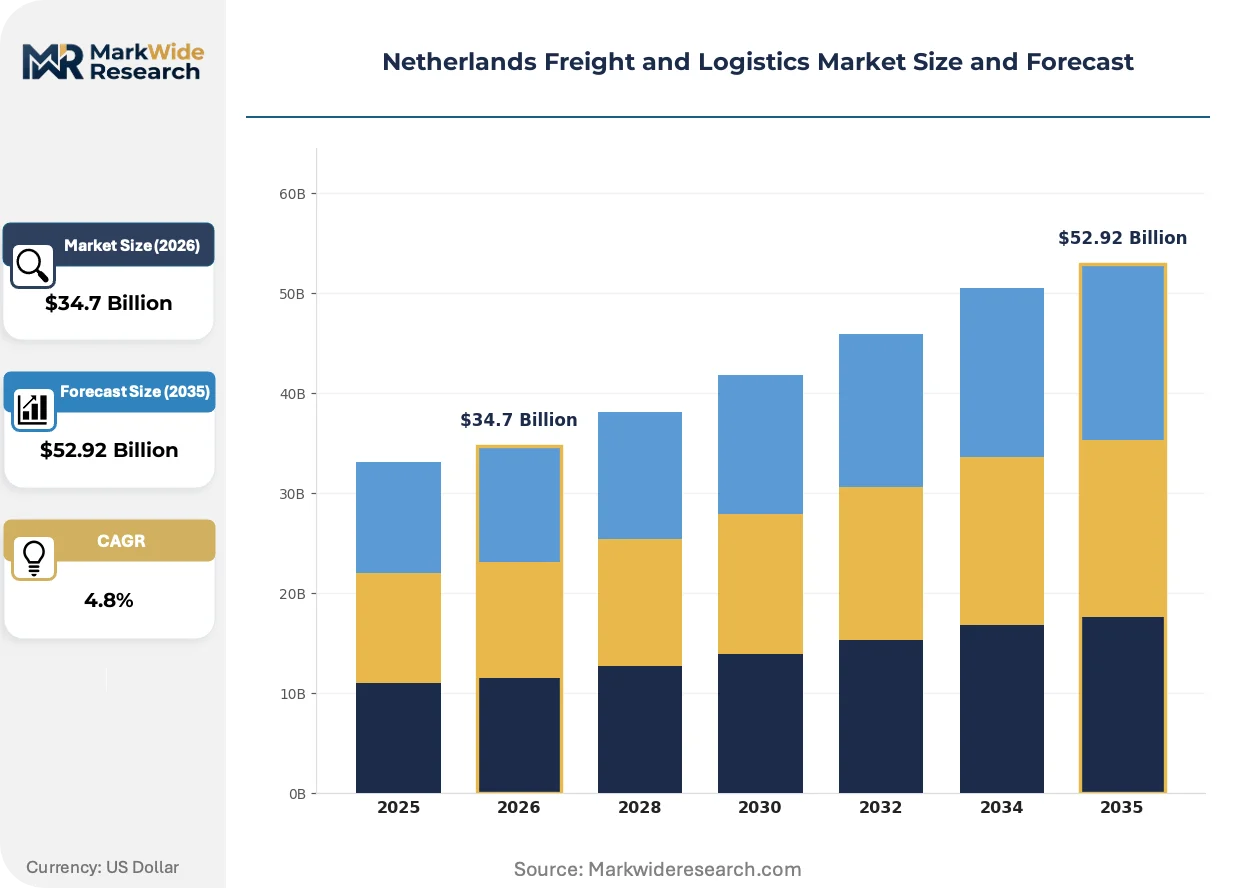
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.92 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: E-commerce, Manufacturing, Wholesale, Retail Mode: Road, Rail, Air, Sea Technology: Tracking Systems, Automation, Blockchain, IoT |
| Companies Covered | DB Schenker, Neele-Vat Logistics, AP Moller - Maersk A/S, E. van Wijk Logistics B.V., Mainfreight Ltd, Kuehne + Nagel International AG, DHL Supply Chain & Global Forwarding, Lubbers Logistics Group, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Freight and Logistics Market Shifts & Advancements
Digitization is compressing information asymmetries between shippers and carriers while automation is reshaping labor economics at container terminals and distribution warehouses.
Automated guided vehicles and robotic process automation are migrating from pilot deployments to production-scale terminal operations. Rotterdam World Gateway and APM Terminals Maasvlakte II are deploying autonomous yard tractors and AI-powered gate systems. Labor cost arbitrage is diminishing as equipment productivity gains offset wage inflation.
REACH chemical handling regulations and EU Emissions Trading System expansion are mandating cargo classification transparency and carbon cost pass-through mechanisms. Freight forwarders must embed substance data and emissions calculations into standard documentation. Pharmaceutical and chemical shippers face the steepest compliance cost escalations.
Shippers are consolidating vendor relationships around integrated control-tower providers that bundle execution, visibility, and carbon reporting. Transactional spot buying is compressing toward contracted volume commitments with penalty structures. Food retail and automotive verticals are driving this consolidation most aggressively in the Randstad logistics corridor.
Netherlands Freight and Logistics Market Segmentation
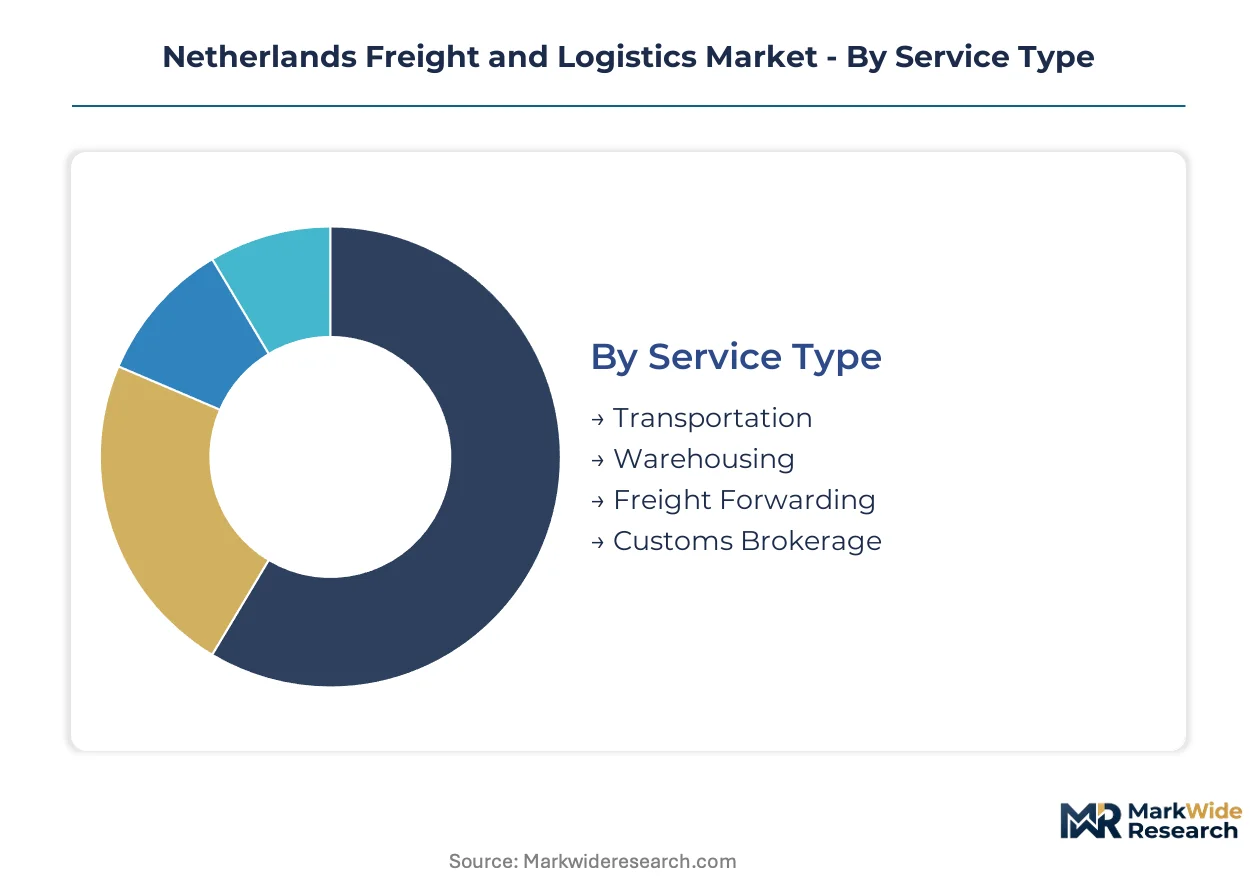
Segmentation in Dutch freight and logistics reveals how Rotterdam's port dominance, modal constraints under EU Green Deal mandates, and pharmaceutical cold-chain requirements create distinct service tiers. Each dimension exposes where margin compression concentrates and where automation investments yield competitive separation.
Service Type:
Shippers across the Randstad corridor select service tiers based on customs complexity, cargo value density, and modal flexibility requirements rather than price alone.
- Transportation:Road haulage commands the largest revenue flow given Rotterdam's container throughput volumes and Rhine-Meuse-Scheldt delta connectivity. Dutch road operators face EU Mobility Package driving-hour constraints that elevate intermodal demand on Amsterdam-Rotterdam-Antwerp corridors.
- Freight Forwarding:Customs brokerage and documentation management generate premium margins due to REACH chemical handling rules and EU Carbon Border Adjustment Mechanism complexity. Forwarders embedding carbon accounting into workflows capture compliance-service premiums from pharmaceutical and chemical shippers.
- Warehousing:Temperature-controlled facilities around Schiphol and Rotterdam corridors serve biologics manufacturers requiring GDP-validated distribution networks. Automated distribution centers cluster in North Brabant and Gelderland provinces to meet same-day delivery radius compression.
- Customs Brokerage:Documentation and regulatory navigation services concentrate around Rotterdam port hinterlands where EU customs union protocols intersect with CBAM carbon reporting requirements.
The dominant share belongs to Transportation, while Freight Forwarding is closing the gap fastest through compliance-service premiums.
End User:
Customer concentration patterns track industrial geography across the Netherlands, with demand intensity varying by inventory velocity and regulatory exposure.
- E-commerce:Automated fulfillment networks in North Brabant and Gelderland provinces compress last-mile delivery radii under same-day expectations. Warehouse management system investments concentrate here due to SKU proliferation and returns processing volumes.
- Manufacturing:Automotive and chemical producers in the Rotterdam-The Hague corridor drive just-in-time rail and barge integration. REACH substance data requirements and EU Emissions Trading System compliance elevate documentation complexity for this segment.
- Wholesale:Bulk commodity distributors leverage inland waterway corridors through the Rhine-Meuse-Scheldt delta to minimize per-unit transport costs. Rhine water level volatility creates inventory buffer requirements during low-water periods.
- Retail:Food retail chains in the Randstad logistics corridor consolidate vendor relationships around integrated control-tower providers bundling execution, visibility, and carbon reporting.
E-commerce holds the revenue concentration lead, though Manufacturing is expanding most quickly through pharmaceutical cold-chain requirements.
Mode:
Modal selection reflects EU Green Deal emissions mandates that compress road haulage margins while elevating rail and inland waterway competitiveness.
- Road:Trucking dominates final-mile and time-sensitive cargo despite EU Mobility Package cabotage restrictions and driver recruitment cost inflation. Fleet operators defer vehicle replacement decisions due to sparse hydrogen and electric charging infrastructure along A15 and A12 motorway corridors.
- Sea:Deep-water berth capacity at Maasvlakte terminals attracts Asia-Europe loop rotations and transshipment volumes from Antwerp-Bruges competition. Shore power and vessel electrification technologies enable zero-emission feeder operations across North Sea port networks.
- Rail:Integrated rail-road terminals near Venlo sustain cross-border pharmaceutical distribution into Germany. Terminal dwell times and schedule reliability gaps create inventory buffer requirements that shippers address through real-time visibility demands.
- Air:Schiphol corridor operations concentrate on temperature-controlled pharmaceutical and biologics cargo requiring validated GDP-compliant handling. Carbon cost pass-through mechanisms under EU Emissions Trading System expansion elevate pricing for air freight relative to surface modes.
Sea transport anchors volume throughput, yet Rail is gaining share fastest through EU decarbonization mandates and inland waterway congestion.
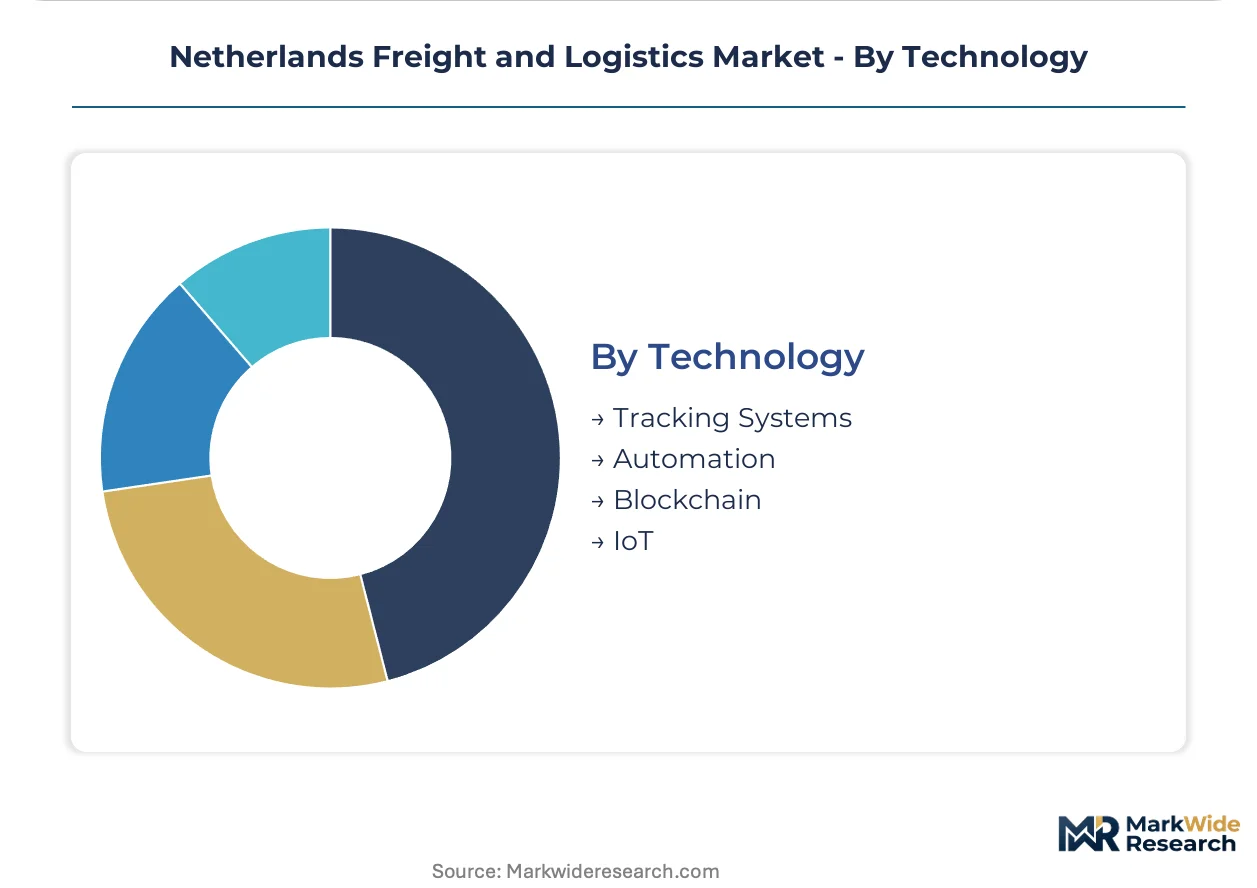
Technology:
Technology deployment stratifies between large integrated operators with automation capital and mid-sized forwarders carrying legacy IT debt.
- Automation:Autonomous yard tractors and AI-powered gate systems at Rotterdam World Gateway and APM Terminals Maasvlakte II reshape labor economics. Equipment productivity gains offset wage inflation as labor cost arbitrage diminishes.
- Tracking Systems:Real-time visibility platforms address shipper demands for intermodal synchronization across rail terminal dwell times and barge schedule handoffs. Cloud migration timelines extend due to customs data localization requirements.
- IoT:Sensor networks monitor pharmaceutical cold-chain integrity and chemical cargo conditions throughout Rhine-Meuse-Scheldt delta corridors. REACH regulations mandate substance data transparency that IoT systems feed into documentation workflows.
- Blockchain:Distributed ledger applications remain pilot-scale for customs documentation and carbon accounting verification. Mid-sized forwarders with fragmented IT stacks face adoption barriers due to integration complexity.
Automation captures the investment majority, while Tracking Systems are scaling most rapidly through shipper visibility mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dutch Human Environment and Transport Inspectorate enforces EU Mobility Package regulations across the Netherlands, shaping freight flows through the Rhine-Meuse-Scheldt delta. Rotterdam port throughput and inland waterway connectivity anchor Western European distribution networks.
Randstad
Pharmaceutical cold-chain demand concentrates around Schiphol and Rotterdam corridors, driven by biologics manufacturers requiring GDP-validated distribution. EU Green Deal emissions mandates accelerate fleet electrification across port zones. Automated distribution centers in North Brabant and Gelderland provinces compress last-mile delivery radii under same-day expectations.
Brabant
E-commerce fulfillment networks cluster here due to central positioning within the Benelux consumer market. The EU Mobility Package driving-hour limits constrain road haulage capacity and elevate intermodal demand. Integrated rail-road terminals near Venlo sustain cross-border pharmaceutical distribution into Germany.
Eindhoven Region
High-tech manufacturing supply chains demand just-in-time logistics services with minimal inventory buffers. REACH chemical handling regulations mandate substance data transparency throughout distribution networks. Specialized temperature-controlled warehousing serves semiconductor and medical device producers.
Northern Netherlands
Groningen and Friesland provinces leverage inland waterway corridors through the Rhine-Meuse-Scheldt delta for bulk commodity distribution. Rhine water level volatility disrupts container barge schedules during low-water periods. Terminal operators face demurrage cost volatility that elevates rail competitiveness.
Netherlands Freight and Logistics Market Competitive Landscape
Capability concentration sits with integrated multimodal operators; scale advantage sits with global forwarding networks. The Dutch market structures around three tiers: port-centric terminal operators, specialized cold-chain providers, and e-commerce fulfillment specialists. Strategic archetypes include EU regulatory compliance specialists, automated warehousing deployers, and cross-border rail integrators. Dominant competitive moves encompass Maasvlakte terminal capacity expansion and carbon accounting service embedding.
Among integrated forwarding networks, DB Schenker and Kuehne + Nagel International AG occupy positions exemplifying multimodal pharmaceutical distribution capabilities. DSV represents the project-cargo specialization archetype serving North Sea offshore energy logistics. These three entities anchor competitive positioning across temperature-controlled warehousing, integrated rail-road terminals, and specialized heavy-lift operations respectively.
| Leading Market Players |
|---|
| DB Schenker |
| Neele-Vat Logistics |
| AP Moller - Maersk A/S |
| E. van Wijk Logistics B.V. |
| Mainfreight Ltd |
| Kuehne + Nagel International AG |
| DHL Supply Chain & Global Forwarding |
| Lubbers Logistics Group |
| DSV |
| Others |
Supply & Pricing Matrix
Rhine-Meuse-Scheldt delta port concentration in Rotterdam and Antwerp-Bruges funnels margin pools toward customs brokerage and cold-chain compliance services rather than commodity transport. EU Carbon Border Adjustment Mechanism documentation complexity and REACH substance-handling requirements elevate pricing power for forwarders embedding regulatory navigation into standard workflows.
Pricing Analysis
Amsterdam-Rotterdam-Antwerp corridor spreads widen during Rhine low-water periods as barge schedule disruptions force modal shifts onto higher-cost rail alternatives. Three-tier pricing structure across premium GDP-validated pharmaceutical handling, standard containerized freight, and economy bulk commodity barge transport dominates service segmentation. Cost compression in road haulage intensifies because EU Mobility Package driving-hour limits constrain fleet utilization and elevate driver recruitment expenses. Wholesale commodity distributors exhibit highest price sensitivity due to thin margins on bulk cargo, while biologics manufacturers accept premium tiers for validated temperature-controlled distribution.
Supply Chain Analysis
Tariff exposure between EU member states and post-Brexit UK customs territories dominates cross-border documentation complexity for Dutch forwarders. Manufacturing inputs draw from Germany, Belgium, and China for automotive components and chemical feedstocks. Diesel fuel, electricity for yard electrification, and hydrogen bunkering infrastructure represent critical cost dependencies. Single-source vulnerability concentrates in specialized pharmaceutical cold-chain equipment suppliers. Distribution runs through Rotterdam port-centric hub-and-spoke networks radiating via inland waterway and rail corridors into German industrial regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight forwarding margins increasingly attach to recurring compliance-service layers rather than transactional cargo movement, with carbon accounting and customs brokerage subscriptions expanding faster than pure transport revenue.
For Market Incumbents: Harden market position through backward integration into automated terminal operations at Maasvlakte expansion zones and captive development of hydrogen bunkering infrastructure. DB Schenker and Kuehne + Nagel International AG demonstrate how integrated rail-road terminal control defends against modal shift disruption. EU Emissions Trading System expansion threatens margin compression for operators lacking carbon cost pass-through mechanisms. For New Entrants and Emerging Players: Pursue white-space opportunity in battery-electric short-sea feeder services connecting North Sea port rotations, where shore power infrastructure gaps delay incumbent fleet renewal. North Brabant e-commerce fulfillment automation presents penetrable terrain for specialized warehouse management system deployers. Go-to-market execution should anchor on same-day delivery radius guarantees to Randstad retail chains. For Investors and Strategic Acquirers: Capital is best deployed toward EU regulatory compliance specialists with embedded carbon accounting workflows and GDP-validated cold-chain certifications. Long-term viability over the next decade hinges on modal flexibility and alternative fuel infrastructure positioning. Monitor Rhine water level volatility frequency as inflection indicator for permanent rail corridor investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Maasvlakte Terminal Automation | Autonomous yard tractors at Rotterdam World Gateway reduce labor cost exposure under EU Mobility Package constraints. |
| Hydrogen Bunkering Infrastructure | Early shore power and vessel electrification deployment captures zero-emission feeder advantages across North Sea networks. |
| Rail-Road Terminal Integration | Venlo corridor cross-border connectivity sustains pharmaceutical distribution into German chemical manufacturing clusters. |
| Carbon Accounting Service Embedding | CBAM-compliant documentation workflows generate recurring revenue premiums from REACH-regulated chemical shippers. |
| Temperature-Controlled Warehousing Expansion | GDP-validated facilities around Schiphol capture biologics manufacturer demand for validated distribution networks. |
Research Methodology
Cross-validation between Dutch Human Environment and Transport Inspectorate enforcement data and EU customs union trade statistics anchors the qualitative findings. Primary interviews with terminal operations directors, freight forwarding compliance officers, pharmaceutical supply chain managers, and inland waterway barge operators combined with secondary validation from EU Mobility Package regulatory filings, Rotterdam port authority throughput disclosures, and Rhine water level monitoring datasets. Bottom-up service provider revenue estimates and top-down modal volume aggregates underwent iterative reconciliation.
Calibration against historical modal shift patterns during prior Rhine low-water episodes informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled encompass service type, end-user vertical, transport mode, and technology deployment tier, with pharmaceutical cold-chain compliance and e-commerce automation intensity as industry-specific stratifiers. CAGRs derived from logistic curve fitting to adoption S-cycles for electrification infrastructure and automation capital deployment. Forecast inputs incorporated EU Emissions Trading System carbon price pass-through rates and EU Green Deal mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in German industrial production indices and Rhine basin precipitation patterns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and alternative fuel infrastructure buildout schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Spain 3PL Market