
 Global Retail 3PL Market | 2026-2036
Global Retail 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retail 3PL Market Foresight
Grade-A cold-chain certification is redrawing competitive thresholds in pharmaceutical and fresh-food logistics. DHL Supply Chain & Global Forwarding leverages its temperature-controlled network density to anchor European pharma corridors. Kuehne + Nagel sustains margin leadership through specialized perishable-airfreight protocols. GXO Logistics differentiates via robotics-heavy warehouse automation that reduces labor dependency in high-cost markets.
Retail third-party logistics encompasses outsourced supply-chain execution—encompassing inventory storage, order fulfillment, and last-mile delivery—performed under service-level agreements specifying on-time-in-full rates and temperature integrity windows. Its commercial purpose is to replace fixed warehouse and fleet assets with variable-cost structures that flex with seasonal demand spikes. Warehousing Solutions commands the largest value pool as retailers outsource fulfillment center construction and operation to avoid capital intensity. Real-Time Tracking is expanding fastest as artificial intelligence and cloud-based platforms converge to generate predictive visibility that reduces safety-stock requirements. Transportation Management remains mature, with margin compression from fuel-price volatility and driver shortages offset by route-optimization software.
The EPA regulates heavy-duty truck emissions in the United States, compelling fleet operators to electrify or adopt alternative fuels that reshape total-cost-of-ownership calculations. The EU Green Deal and REACH framework impose carbon-accounting and material-safety obligations on cross-border logistics networks, favoring providers with certified sustainability reporting. India's BIS standards and PLI scheme for logistics infrastructure are accelerating automated warehouse adoption. Stakeholders must monitor which regulatory jurisdiction's compliance costs will determine provider selection in multi-country retail networks.
Market Dynamics
Omnichannel grocery fulfillment is compressing delivery windows to same-day and two-hour thresholds, forcing 3PL providers to reconfigure warehouse networks for micro-fulfillment density rather than regional consolidation.
Growth Catalysts
- EU Green Deal fleet mandates:Carbon-accounting requirements for cross-border logistics are accelerating electric-vehicle adoption among contracted fleet operators serving European retail corridors.
- Cold-chain infrastructure gaps in India:Pharmaceutical and fresh-food e-commerce expansion is multiplying demand for temperature-certified warehousing as BIS standards tighten certification requirements.
- Robotics integration:Automated picking systems are reducing labor dependency in high-cost fulfillment markets where warehouse wage inflation outpaces productivity gains.
Market Restraints
- Driver shortage concentration:Long-haul capacity constraints in the United States are tightening truckload availability and inflating spot-market rates for seasonal retail surges.
- Electrification capex burden:Battery-electric truck procurement and charging infrastructure deployment are compressing 3PL margins before total-cost-of-ownership parity with diesel fleets materializes.
- REACH material-safety compliance:Chemical-handling protocols for warehouse equipment and packaging materials are adding documentation overhead to European operations.
Strategic Opportunities
- India's PLI logistics infrastructure scheme:Automated warehouse construction subsidies are lowering capital barriers for providers establishing pharmaceutical-grade cold-chain nodes in Mumbai and Hyderabad.
- AI-IoT convergence in real-time tracking:Predictive visibility platforms are enabling inventory positioning that reduces safety-stock requirements for omnichannel retailers.
- Dark-store micro-fulfillment:Conversion of urban retail footprints into automated fulfillment nodes is creating last-mile density without greenfield construction timelines.
Industry Challenges
- Grade-A cold-chain certification timelines:Pharmaceutical logistics providers face extended validation periods for temperature-mapping protocols that delay contract onboarding.
- Warehouse management system fragmentation:Integration complexity between legacy retailer ERP platforms and 3PL WMS architectures is inflating implementation costs and error rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retail 3PL Market |
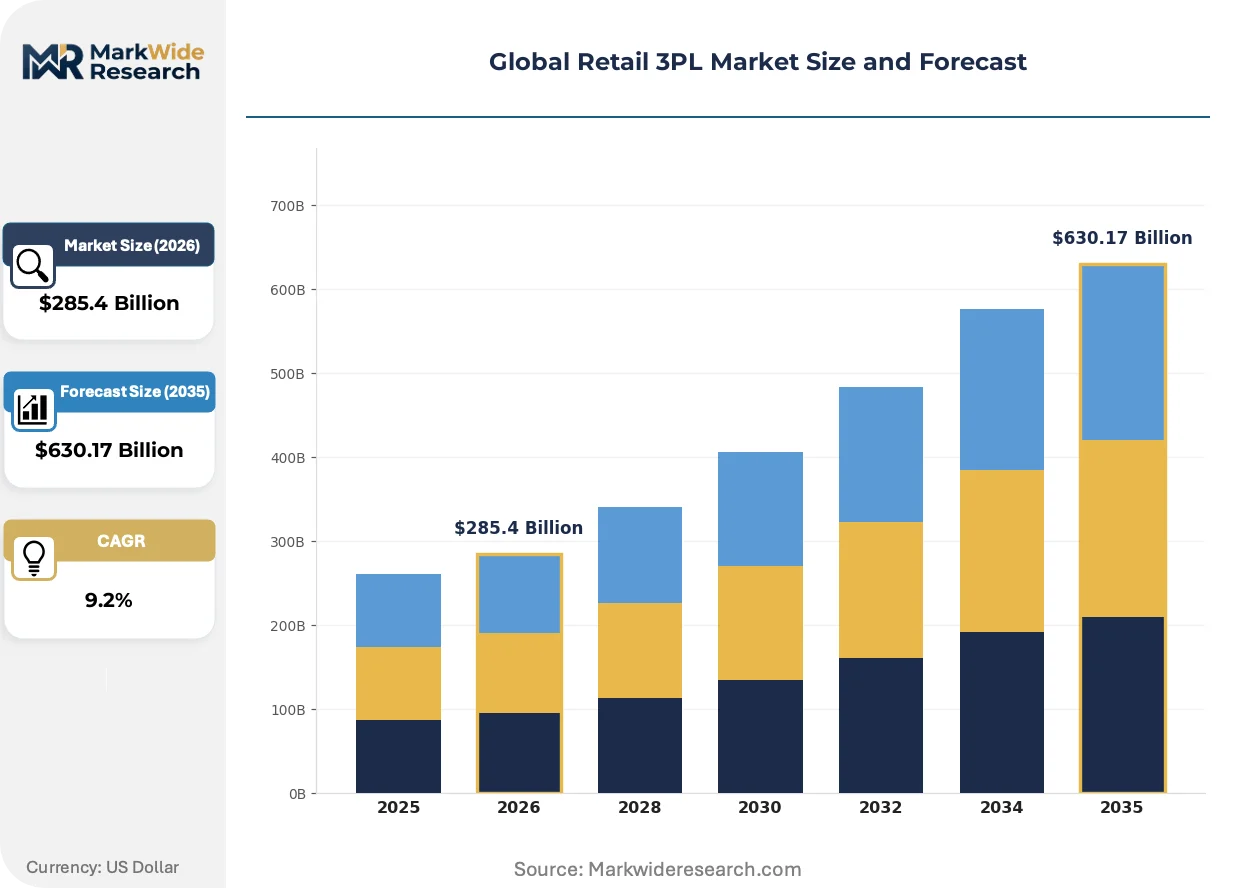
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $630.17 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Warehousing Solutions, Freight Forwarding, Inventory Management, Distribution Services, Reverse Logistics Customer Type: Online Retailers, Brick-and-Mortar Chains, Specialty Stores, Department Stores, Wholesale Buyers, Direct-to-Consumer Brands Distribution Channel: Third-Party Logistics Providers, In-House Fulfillment, Drop Shipping, Contract Carriers, Parcel Delivery, Dedicated Fleet Technology Adoption: Warehouse Automation, Real-Time Tracking, Artificial Intelligence, Cloud-Based Platforms, Blockchain Integration, Robotics |
| Companies Covered | Amazon, DSV, DHL Supply Chain & Global Forwarding, Kuehne + Nagel, CEVA Logistics, NIPPON EXPRESS, C.H. Robinson, UPS Supply Chain Solutions, GXO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retail 3PL Market Shifts & Advancements
Retail 3PL operations are converging on predictive automation and carbon-accounted service tiers as labor costs and emissions compliance reshape provider selection criteria.
Autonomous mobile robots are displacing manual picking and packing in high-volume fulfillment centers. Grocery and fashion retailers with same-day delivery commitments are deploying AMR fleets at scale. This technology is displacing traditional zone-picking labor models and compressing order-cycle times from hours to minutes.
CSRD sustainability reporting mandates are requiring granular carbon disclosure from logistics providers serving EU retail networks. Fleet operators must now document scope-three emissions across subcontracted last-mile delivery. Pharmaceutical and fresh-food corridors face the steepest compliance ramps as temperature-controlled transport adds energy-intensity tracking requirements.
Buyer procurement patterns are consolidating vendor relationships around integrated service bundles that combine warehousing, transportation, and value-added fulfillment. Mid-market omnichannel retailers are abandoning point-solution contracts for single-provider accountability. This concentration is most visible in Germany and the Netherlands where retail cooperative networks favor consolidated 3PL partnerships over fragmented supplier bases.
Global Retail 3PL Market Segmentation
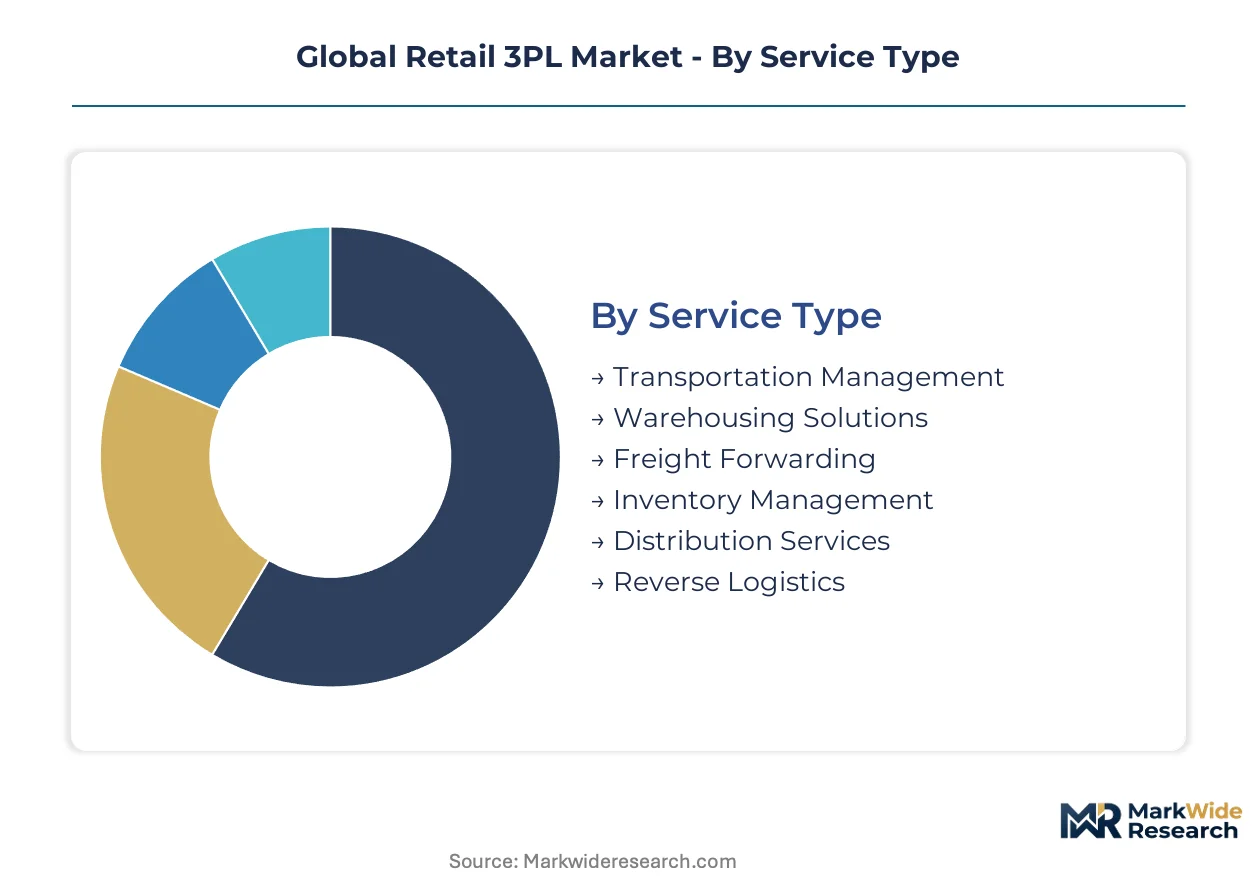
Service differentiation in retail 3PL separates providers capable of handling EU Green Deal carbon-accounting mandates from commodity competitors. Customer complexity and technology intensity further stratify the market into premium-certified and standard-service tiers.
Service Type:
EPA emissions rules for heavy-duty trucking and EU REACH chemical-handling protocols create divergent compliance burdens across service lines.
- Warehousing Solutions:Temperature-controlled facilities with Grade-A cold-chain certification command premium pricing from pharmaceutical and fresh-food retailers. India's BIS standards are tightening certification requirements for automated warehouse construction under the PLI scheme, concentrating new capital deployment in Mumbai and Hyderabad corridors.
- Transportation Management:Fleet electrification timelines under the EU Green Deal are compressing margins before total-cost-of-ownership parity with diesel vehicles materializes. Route-optimization software adoption is accelerating among providers serving German and Dutch retail cooperative networks where consolidated vendor relationships dominate procurement.
- Freight Forwarding:Cross-border carbon-accounting documentation is expanding overhead for European pharma corridors.
- Inventory Management:AI-driven demand forecasting reduces safety-stock requirements for omnichannel retailers with same-day delivery commitments.
- Distribution Services:Micro-fulfillment density is replacing regional consolidation as grocery networks compress delivery windows.
- Reverse Logistics:Returns processing automation lags outbound fulfillment technology adoption.
Warehousing Solutions handles the majority of throughput; Real-Time Tracking convergence within Transportation Management is expanding most quickly on share.
Customer Type:
Procurement concentration varies by retail format and regulatory exposure to cold-chain mandates.
- Online Retailers:Same-day and two-hour delivery thresholds are forcing reconfiguration of fulfillment networks toward urban micro-fulfillment density. India's e-commerce infrastructure maturation is multiplying demand for temperature-certified warehousing as pharmaceutical and fresh-food categories expand.
- Direct-to-Consumer Brands:Subscription-model replenishment cycles require flexible warehouse capacity that scales with seasonal spikes. These brands are abandoning point-solution contracts for single-provider accountability bundles that combine storage, transport, and value-added fulfillment.
- Brick-and-Mortar Chains:Dark-store conversion of retail footprints is creating last-mile density without greenfield construction timelines.
- Specialty Stores:Limited SKU breadth permits consolidated distribution through regional 3PL hubs.
- Department Stores:Complex omnichannel inventory positioning demands real-time visibility integration.
- Wholesale Buyers:Pallet-scale fulfillment tolerates longer cycle times than unit-pick operations.
Online Retailers anchor volume concentration; Direct-to-Consumer Brands are gaining share fastest as vendor consolidation accelerates.
Distribution Channel:
Channel selection reflects capital intensity preferences and emissions compliance capabilities.
- Third-Party Logistics Providers:Integrated service bundles combining warehousing, transportation, and value-added fulfillment are displacing fragmented supplier relationships. CSRD sustainability reporting mandates require granular carbon disclosure from providers serving EU retail networks.
- Dedicated Fleet:Battery-electric truck procurement and charging infrastructure deployment favor large-scale operators with balance-sheet capacity to absorb electrification capex before diesel parity. The EPA's heavy-duty truck emissions regulations are compelling fleet operators to electrify or adopt alternative fuels.
- In-House Fulfillment:Capital intensity of automated warehouse construction is driving outsourcing decisions among mid-market retailers.
- Drop Shipping:Supplier-direct fulfillment reduces inventory carrying costs but fragments delivery experience control.
- Contract Carriers:Spot-market rate volatility during seasonal surges is tightening availability for non-contracted volume.
- Parcel Delivery:Last-mile density requirements favor network operators with established urban footprint.
Third-Party Logistics Providers dominate transaction volume; Dedicated Fleet investment is climbing the fastest as electrification mandates harden.
Technology Adoption:
Regulatory pressure on labor costs and emissions tracking is accelerating capital deployment into automation and visibility platforms.
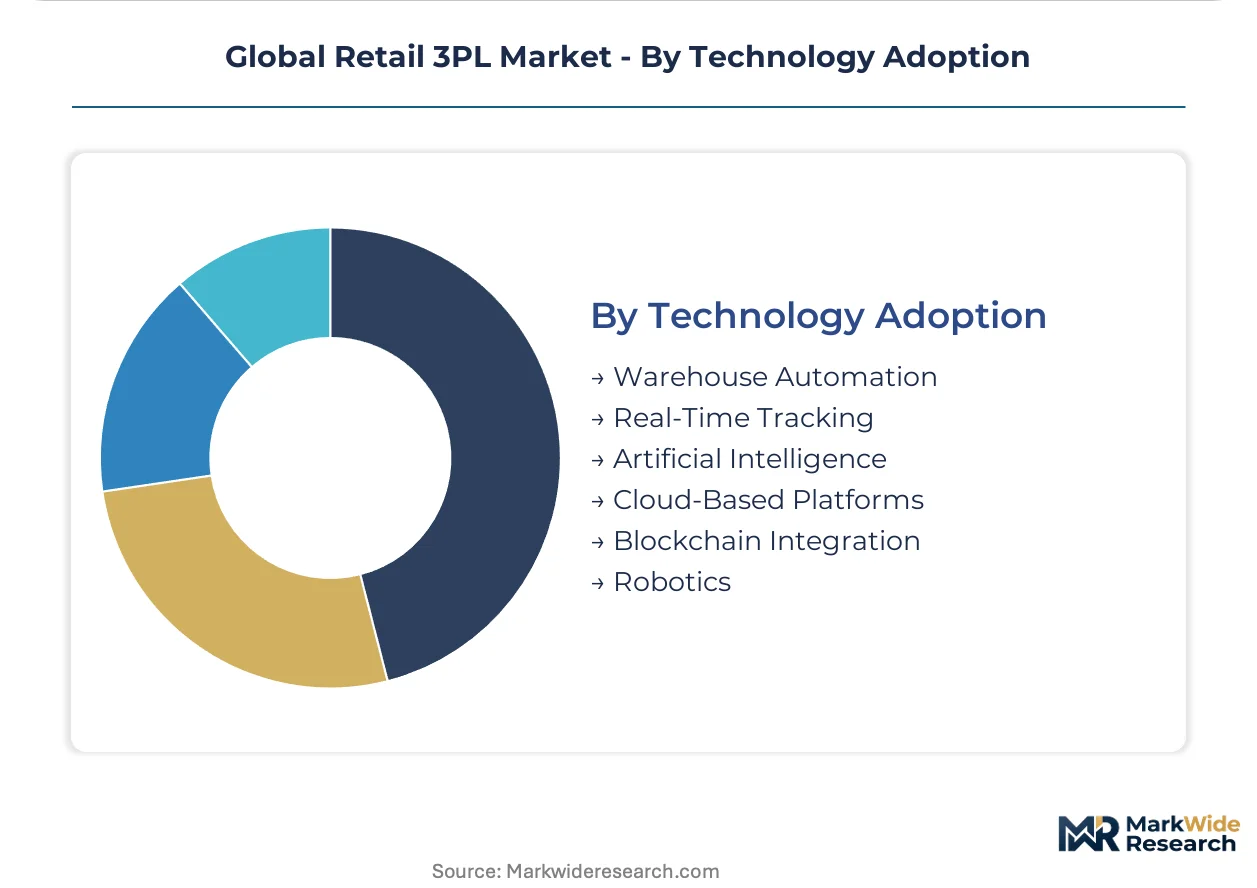
- Warehouse Automation:Autonomous mobile robots are displacing manual picking in high-volume fulfillment centers where warehouse wage inflation outpaces productivity gains. Grocery and fashion retailers with same-day delivery commitments are deploying AMR fleets at scale.
- Real-Time Tracking:AI-IoT convergence generates predictive visibility that reduces safety-stock requirements. Cloud-based platforms enable inventory positioning across distributed fulfillment nodes for omnichannel retailers.
- Artificial Intelligence:Demand forecasting algorithms improve order-cycle compression.
- Cloud-Based Platforms:ERP-WMS integration complexity remains a implementation barrier.
- Robotics:Automated picking systems reduce labor dependency in high-cost markets.
- Blockchain Integration:Pharmaceutical provenance tracking adoption lags other visibility technologies.
Warehouse Automation captures the largest capital allocation; Real-Time Tracking is expanding fastest as AI-IoT convergence matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in consumer goods are reshaping warehouse location strategies across major economies. Nations with trade surpluses in manufactured retail products require outbound logistics density, while deficit markets need import deconsolidation infrastructure.
United States
E-commerce fulfillment demand from Amazon and Walmart is saturating last-mile networks in major metros. The EPA's heavy-duty truck emissions regulations are accelerating electric fleet trials among contracted operators. The Inland Empire east of Los Angeles anchors the nation's largest concentration of automated fulfillment centers serving Pacific Rim imports.
Germany
Retail cooperative procurement networks are consolidating vendor relationships around integrated 3PL bundles. The EU Green Deal's fleet electrification mandates are compressing margins for road freight operators serving cross-border corridors. The Rhine-Ruhr conurbation hosts Europe's densest cluster of temperature-controlled pharma logistics facilities.
China
Domestic e-commerce infrastructure maturation is multiplying demand for same-day fulfillment density in tier-one cities. The MIIT's dual carbon goals are imposing emissions accounting on logistics networks serving cross-border retail exports. The Yangtze River Delta around Shanghai concentrates automated warehouse construction for outbound consumer goods consolidation.
India
Pharmaceutical and fresh-food e-commerce expansion is driving cold-chain infrastructure investment. The BIS standards and PLI scheme for logistics infrastructure are accelerating automated warehouse adoption. Mumbai and Hyderabad corridors are emerging as the primary nodes for pharmaceutical-grade temperature-certified storage capacity.
Netherlands
Rotterdam's port-centric logistics ecosystem is repositioning for carbon-accounted service tiers under CSRD mandates. The REACH framework's chemical-handling protocols are adding documentation overhead to warehouse operations serving EU retail networks. The Randstad conurbation maintains Europe's highest density of integrated warehousing and distribution facilities for omnichannel fulfillment.
Global Retail 3PL Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth. The market structures around three tiers: global integrators with balance-sheet capacity for fleet electrification, regional specialists with cold-chain certification density, and technology-heavy entrants automating labor-dependent processes. Consolidation pressures favor providers capable of bundling warehousing, transportation, and value-added fulfillment under single-accountability contracts. Dominant competitive moves include M&A to capture certified cold-chain assets and strategic partnerships to deploy micro-fulfillment density in urban cores.
Among integrated service providers, DHL Supply Chain & Global Forwarding, Kuehne + Nagel, and GXO Logistics exemplify divergent specialization vectors. DHL Supply Chain & Global Forwarding occupies a position anchored in temperature-controlled network density for pharmaceutical corridors. Kuehne + Nagel represents margin leadership through perishable-airfreight protocol specialization. GXO Logistics sits within the automation-driven tier, reducing labor dependency through robotics-heavy warehouse deployment in high-cost fulfillment markets.
| Leading Market Players |
|---|
| Amazon |
| DSV |
| DHL Supply Chain & Global Forwarding |
| Kuehne + Nagel |
| CEVA Logistics |
| NIPPON EXPRESS |
| C.H. Robinson |
| UPS Supply Chain Solutions |
| GXO Logistics |
| Others |
Supply & Pricing Matrix
Fulfillment center utilization rates above 85% anchor margin structures across high-cost markets, compressing price floors for sub-scale operators while concentrating contract awards among providers with automated warehouse density in Germany and the Netherlands. This scale dynamic reinforces procurement consolidation around integrated service bundles that bundle warehousing, transportation, and carbon-accounted delivery tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across Grade-A cold-chain certified, standard temperature-controlled, and ambient warehousing tiers. Price differentiation rests on certification level and automation intensity, with EU Green Deal carbon-accounting premiums widening spreads. Cost compression in ambient fulfillment is intensifying because robotics deployment amortization outpaces labor inflation in high-wage corridors. Mid-market omnichannel retailers exhibit highest price sensitivity; pharmaceutical networks demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
China, Germany, and the United States anchor automated warehouse equipment manufacturing and fulfillment center construction capacity. Critical inputs draw from lithium-ion battery systems for electrified fleets, precision temperature-control units for pharmaceutical corridors, and autonomous mobile robot assemblies. Single-source vulnerability concentrates in AMR component sourcing from East Asian suppliers. Distribution runs through integrated 3PL networks that consolidate vendor relationships under single-accountability contracts serving EU retail cooperative procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern provider selection as AI-IoT visibility layers interoperate across retailer ERP systems and 3PL warehouse management architectures, collapsing information asymmetries that previously fragmented vendor relationships.
For Market Incumbents: Compound automation density in Rhine-Ruhr and Randstad corridors to defend against technology-heavy entrants automating labor-dependent processes. Prioritize backward integration into temperature-control equipment manufacturing to secure Grade-A cold-chain certification timelines. Capture certified cold-chain assets through targeted M&A in Mumbai and Hyderabad pharmaceutical corridors.
For New Entrants and Emerging Players: Grade-A cold-chain certification fast-tracks in India's PLI logistics infrastructure scheme unlock pharmaceutical-grade warehousing contracts as BIS standards tighten. Target dark-store micro-fulfillment conversions in tier-one Chinese cities where urban retail footprint repurposing outpaces greenfield construction. Lead with AI-driven demand forecasting modules that reduce safety-stock requirements for omnichannel grocery networks.
For Investors and Strategic Acquirers: Regional specialists with dense cold-chain certification assets in European pharma corridors represent priority acquisition targets. Long-term viability hinges on fleet electrification balance-sheet capacity and CSRD sustainability reporting infrastructure. Monitor EPA heavy-duty truck emissions enforcement intensity as inflection indicator for electrification capex burden distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Construction | PLI scheme subsidies in India lower capital barriers for pharmaceutical-grade cold-chain nodes. |
| Fleet Electrification Partnership | Battery-electric truck procurement with charging infrastructure addresses EU Green Deal mandates. |
| AI-IoT Visibility Platform Integration | Predictive tracking reduces safety-stock requirements for omnichannel retailers with same-day commitments. |
| Dark-Store Micro-Fulfillment Conversion | Urban retail footprint repurposing creates last-mile density without greenfield construction timelines. |
| CSRD Sustainability Reporting Certification | Granular carbon disclosure meets procurement requirements from EU retail cooperative networks. |
Research Methodology
Cross-validation between primary interviews with logistics procurement directors, warehouse operations managers, fleet electrification specialists, and pharmaceutical supply chain leads anchors the qualitative findings. Secondary validation draws from EPA emissions filings, EU Green Deal regulatory texts, BIS certification databases, and SEC 10-K disclosures from listed 3PL providers. Bottom-up capacity modeling and top-down demand aggregation triangulate market sizing.
Sensitivity analysis across service type, customer complexity tier, and technology adoption intensity shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include warehousing solutions, transportation management, freight forwarding, inventory management, and distribution services crossed with online retailer, direct-to-consumer brand, and brick-and-mortar chain archetypes. CAGRs derive from logistics infrastructure investment trajectories and e-commerce fulfillment density expansion rates.
Underlying assumptions cover electrification cost-parity timelines and cold-chain certification validation periods, with deviation risk concentrated in EPA enforcement intensity and EU carbon-accounting mandate implementation pace. Recalibration cycles align with material shifts in fleet electrification subsidy programs and pharmaceutical e-commerce penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market