
 Slovakia Freight and Logistics Market | 2026-2036
Slovakia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia Freight and Logistics Market Analytics
E-commerce retailers is reorganizing procurement patterns across Slovakia's logistics landscape, pulling capacity away from traditional automotive contract structures. DACHSER Slovakia a.s. leverages its European network density to anchor cross-border road freight operations from Bratislava. Rail Cargo Group competes on bulk and containerized rail corridors linking the Port of Hamburg to inland terminals. Rhenus Group specializes in value-added warehousing and customs brokerage near the Austrian and Czech borders.
Freight and logistics encompasses the physical movement, storage, and coordination of goods through multimodal networks operating across road corridors, rail lines, air cargo terminals, and inland waterway connections, with fleet specifications governed by EURO VI emission standards and axle-load regulations for cross-border interoperability. The sector's primary commercial purpose is synchronizing inventory flows with manufacturing schedules and consumption cycles. Transport Services captures the dominant value pool given Slovakia's position as a Central European transit corridor, while Freight Forwarding is gaining structural importance as shippers outsource customs complexity and multimodal orchestration. Last-Mile delivery is expanding fastest in response to e-commerce penetration around Bratislava and Košice, though margin compression remains acute in this segment.
The European Union's Mobility Package enforcement through the European Commission shapes driver rest rules and cabotage restrictions that directly constrain fleet utilization rates for Slovak carriers. BIS-aligned technical standards for vehicle dimensions and the country's national transport regulator's enforcement of EURO VI compliance create equipment upgrade cycles that filter through to logistics pricing. Stakeholders must monitor how EU emissions trading scheme expansion to road transport alters the total cost of ownership for diesel-dependent fleet operators and whether rail electrification investments keep pace with modal shift targets.
Market Dynamics
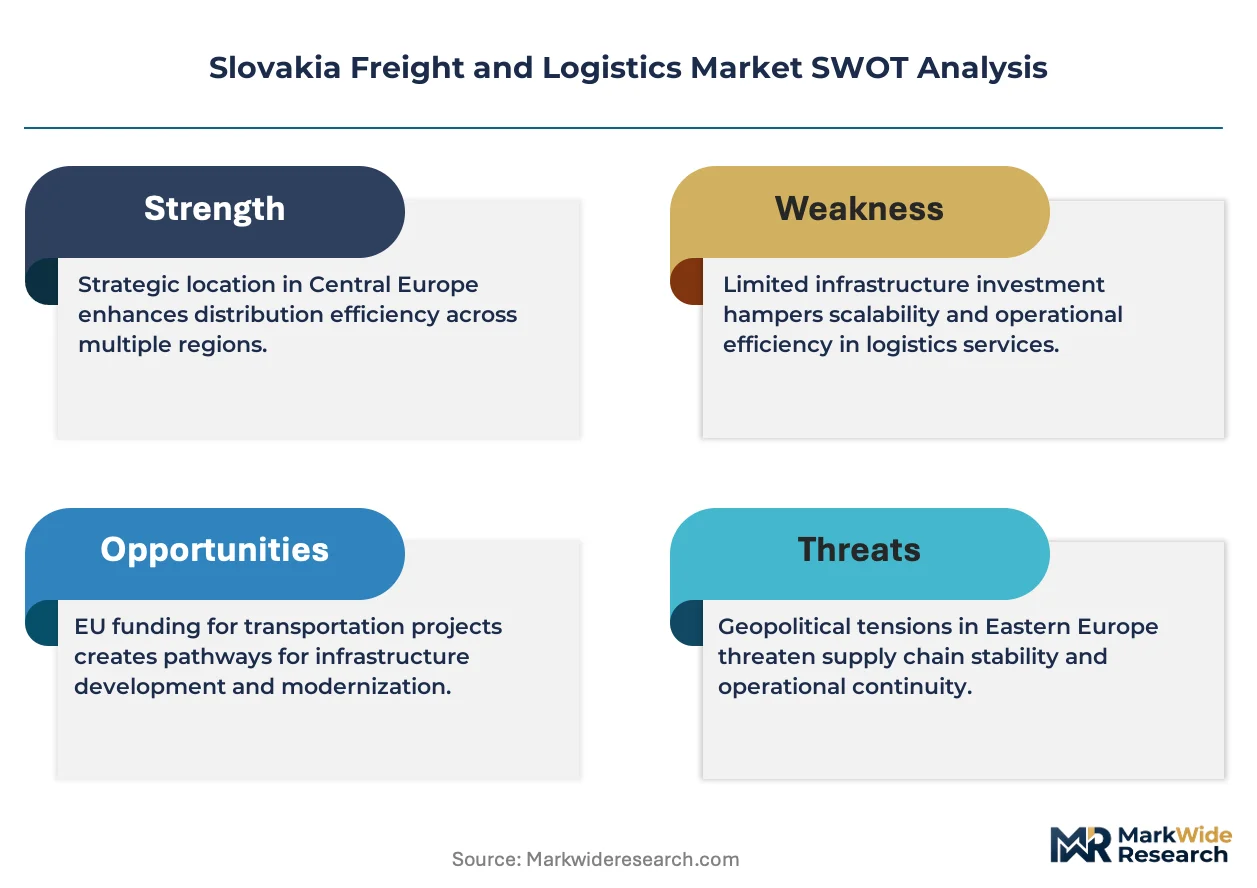
The EU Green Deal emissions standards are forcing fleet modernization across Slovakia's automotive-dominated logistics corridors, compressing diesel-dependent operators while electrified intermodal investments absorb capital flows. This regulatory pressure synchronizes with just-in-time supply chain tightening from Bratislava-Zilina manufacturers, restructuring carrier economics and infrastructure deployment priorities.
Growth Catalysts
- EU Green Deal:The European Commission's emissions trading scheme expansion to road transport accelerates electric fleet procurement and charging infrastructure rollout along Slovakia's western industrial belt.
- Automotive just-in-time requirements:Volkswagen, Kia, and Stellantis assembly plants demand synchronized inbound logistics, pulling specialized contract logistics capacity toward the Bratislava-Zilina corridor.
- Intermodal rail electrification:Rail Cargo Group's containerized corridors linking the Port of Hamburg to Žilina and Bratislava terminals enable modal shift away from cross-border trucking.
Market Restraints
- Driver shortage and EU Mobility Package constraints:The European Commission's cabotage restrictions and mandatory rest rules reduce fleet utilization rates for Slovak carriers operating international routes.
- Diesel price volatility and carbon cost pass-through:EU emissions trading scheme allowance prices inflate total cost of ownership for conventional fleets before electrification economies mature.
- Warehousing land scarcity near Bratislava:Industrial zone saturation around the capital limits greenfield logistics park development for e-commerce fulfillment expansion.
Strategic Opportunities
- Eastern Slovakia underpenetration:Košice and Prešov regions lack equivalent logistics density to western corridors, creating first-mover advantage for regional distribution center placement.
- Battery supply chain logistics:InoBat and emerging cell manufacturing investments near Bratislava require specialized hazardous materials handling and temperature-controlled transport infrastructure.
- Digital freight platforms:Real-time capacity matching and dynamic pricing algorithms are compressing spot market transaction costs for SME shippers outside traditional contract structures.
Industry Challenges
- Telematics and autonomous fleet management skill gaps:Slovak carriers struggle to recruit software engineers and data analysts capable of optimizing electric vehicle range and charging schedules.
- Legacy warehouse management system integration:Mid-sized 3PLs face friction connecting robotic picking and automated storage systems with existing ERP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia Freight and Logistics Market |
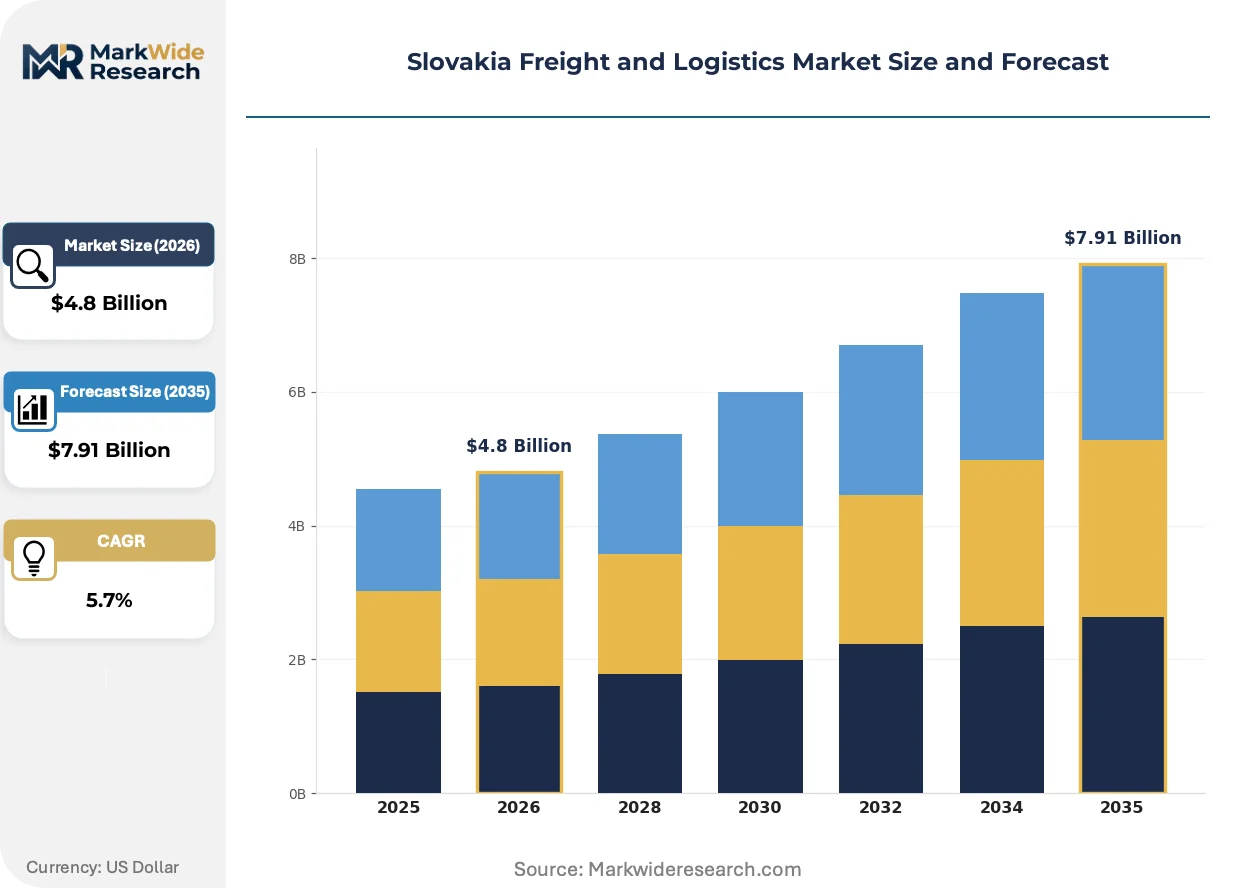
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport Services, Warehousing, Distribution, Freight Forwarding Delivery Model: Door-to-Door, Port-to-Port, Cross-Docking, Last-Mile Transit Mode: Rail, Road, Air, Sea Customer Type: Retail, Manufacturing, E-commerce, Automotive |
| Companies Covered | Rhenus Group, DACHSER Slovakia a.s., Rail Cargo Group, ROHLIG SUUS Logistics S.A., Augustin Quehenberger Group GmbH, GEFCO Deutschland GmbH, Express Group, a.s., TransLog Slovakia, a.s., A.P. Moller - Maersk A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia Freight and Logistics Market Evolving Landscape
Electrification and digital orchestration are compressing traditional diesel-road dominance while regulatory compliance costs restructure competitive economics across Slovakia's freight corridors.
Battery-electric trucks with 300-400 kilometer range specifications are displacing diesel tractors on fixed Bratislava-Vienna and Bratislava-Brno routes. Automotive component suppliers with predictable shuttle schedules pilot these vehicles for overnight charging at manufacturing plants. The displacement of conventional fleet assets is accelerating residual value depreciation for EURO VI diesel tractors before regulatory bans take effect.
The EU Green Deal's Fit for 55 package tightens CO2 emission standards for heavy-duty vehicles through 2030, mandating progressive fleet decarbonization. Slovak carriers face compliance cost pass-through to automotive contract rates or capital-intensive electrification programs. The Bratislava-Zilina corridor absorbs disproportionate impact given automotive shipment density and just-in-time penalty clauses for delivery failures.
E-commerce fulfillment networks are compressing delivery windows to same-day and next-day service around Bratislava and Košice urban zones. Retailers bypass traditional distribution centers for direct-to-consumer micro-fulfillment placement in last-mile nodes. This pattern concentrates demand volatility in parcel networks while eroding margin structures for conventional palletized freight operators serving brick-and-mortary retail.
Slovakia Freight and Logistics Market Segmentation
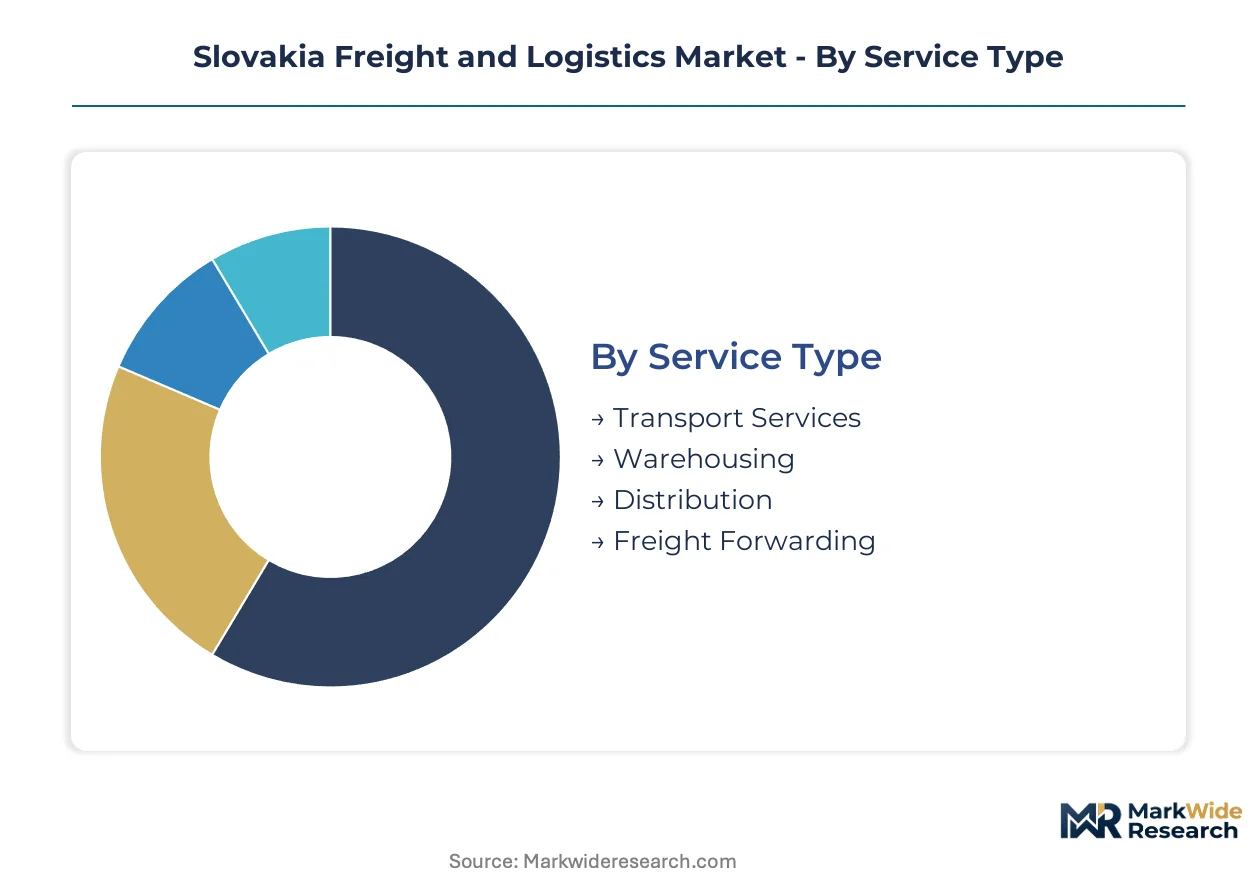
Slovakia's freight and logistics market segments reflect the country's dual identity as an automotive manufacturing hub and Central European transit corridor. Channel configurations vary sharply between just-in-time automotive contracts and fragmented e-commerce fulfillment networks.
Service Type:
Road haulage flows through Transport Services and Freight Forwarding channels, while contract manufacturers pull dedicated Warehousing and Distribution capacity toward the Bratislava-Zilina corridor.
- Transport Services:Full-truckload and less-than-truckload road operations dominate value capture, with fleet specifications governed by EURO VI emission standards. Demand concentrates along the D1 and D2 motorway corridors serving Volkswagen, Kia, and Stellantis assembly plants, where just-in-time penalty clauses enforce sub-hour delivery windows.
- Freight Forwarding:Customs brokerage and multimodal orchestration absorb structural importance as shippers outsource EU Mobility Package complexity. Slovak carriers operating international routes rely on forwarders to navigate cabotage restrictions and cross-border documentation, particularly for Hamburg-Žilina rail intermodal handoffs.
- Warehousing:Temperature-controlled and hazardous materials facilities cluster near Bratislava's airport and border crossings, supporting InoBat battery cell manufacturing and pharmaceutical distribution. Land scarcity limits greenfield expansion.
- Distribution:Consolidation and deconsolidation services feed both automotive sequencing centers and e-commerce sortation hubs, with operational models diverging between high-frequency shuttle schedules and volatile parcel batch processing.
Transport Services dominates installed base. Freight Forwarding is where expansion concentrates.
Delivery Model:
Cost structures stratify sharply between asset-heavy Door-to-Door operations and fixed-cost Port-to-Port trunking, with margin profiles determining carrier participation across customer tiers.
- Door-to-Door:End-to-end liability and fleet ownership requirements restrict this model to integrated logistics providers with balance sheet capacity. Automotive contract logistics operators absorb inventory risk through vendor-managed inventory arrangements.
- Last-Mile:Same-day and next-day delivery windows around Bratislava and Košice urban zones compress route density economics. E-commerce penetration drives volume but erodes per-stop margins through residential address fragmentation.
- Cross-Docking:High-velocity freight transfer without intermediate storage suits automotive component sequencing and perishable food distribution, requiring precise inbound-outbound synchronization.
- Port-to-Port:Rail and maritime container movements through Hamburg, Koper, and Trieste terminals minimize handling costs for bulk commodities and non-urgent manufactured goods.
Door-to-Door captures premium pricing tiers. Last-Mile is climbing the fastest despite margin pressure.
Transit Mode:
Modal choice tracks shipment urgency, cargo density, and EU emissions trading scheme cost pass-through, with electrification investments reshaping intermodal competitiveness.
- Road:Diesel tractors retain dominance for sub-400-kilometer movements and just-in-time automotive shuttles. Battery-electric pilots with 300-400 kilometer range specifications displace conventional fleets on fixed Bratislava-Vienna and Bratislava-Brno routes.
- Rail:Rail Cargo Group's electrified corridors linking Hamburg to Žilina and Bratislava terminals enable modal shift for containerized manufacturing inputs. Bulk commodities and automotive components concentrate on these corridors.
- Air:Bratislava Airport's cargo terminal handles high-value electronics and pharmaceutical time-critical shipments, though volume remains constrained by proximity to Vienna's larger hub.
- Sea:Maritime access depends on Koper and Trieste Adriatic ports for containerized imports, with rail feeder services completing the inland leg to Slovak terminals.
Road maintains volume leadership. Rail is gaining share fastest on decarbonization mandates.
Customer Type:
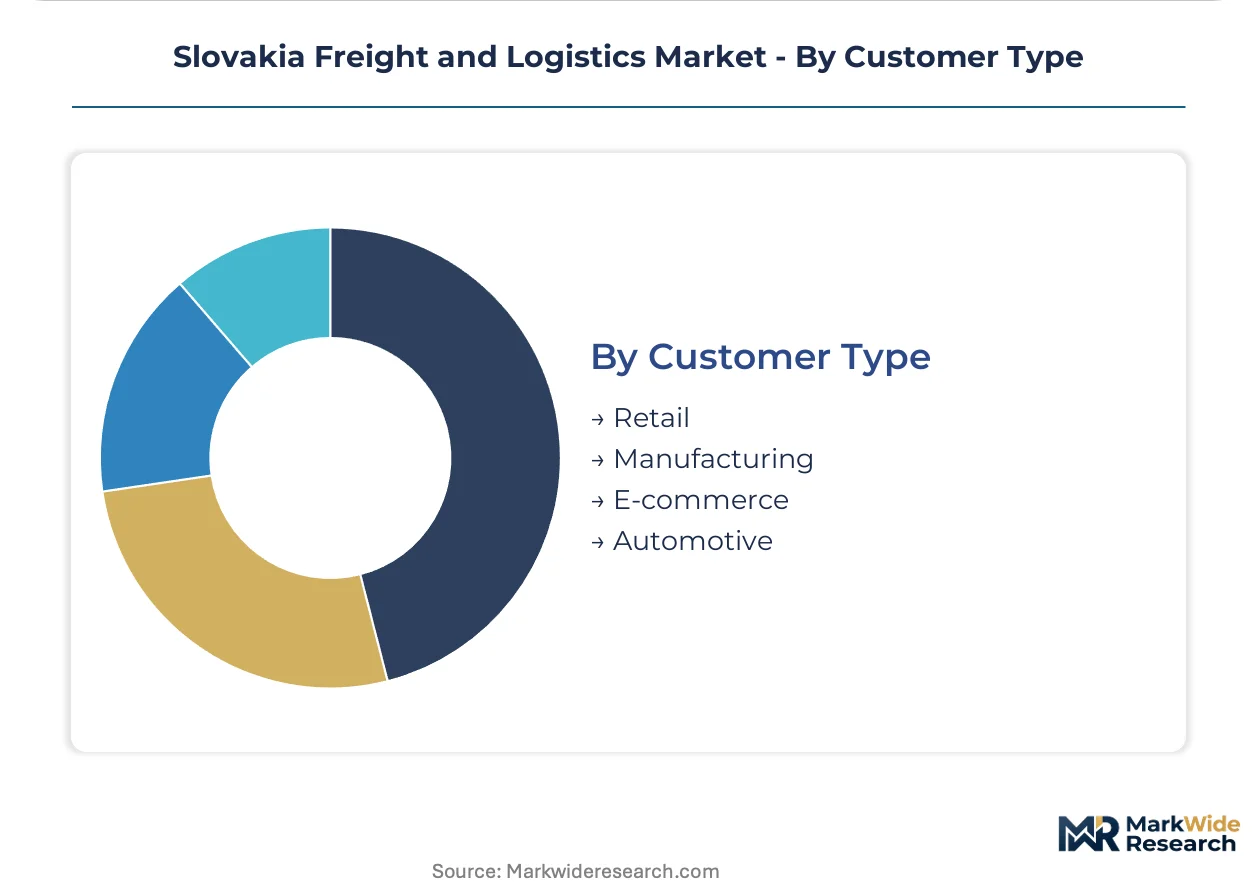
Procurement patterns diverge between long-term contract structures in Automotive and Manufacturing versus spot-market volatility in E-commerce and Retail.
- Automotive:Volkswagen, Kia, and Stellantis plants impose synchronized inbound logistics with penalty clauses for delivery failures. Dedicated contract logistics capacity anchors carrier revenue stability.
- E-commerce:Direct-to-consumer fulfillment networks bypass traditional distribution centers for micro-fulfillment placement in last-mile nodes, concentrating demand volatility in parcel networks.
- Manufacturing:Electronics and machinery producers in western Slovakia require temperature-controlled and hazardous materials handling, pulling specialized warehousing investment.
- Retail:Brick-and-mortary chains face margin erosion from e-commerce competition, compressing conventional palletized freight rates while demanding shorter replenishment cycles.
Automotive anchors contract structures. E-commerce is where demand volatility concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The D1 motorway corridor anchors Slovakia's freight distribution architecture, threading automotive assembly plants and inland terminals across the western industrial belt toward Vienna and Brno.
Bratislava Region
Volkswagen and Stellantis assembly plants generate synchronized inbound logistics demand with sub-hour delivery windows. The EU Mobility Package cabotage restrictions constrain Slovak carriers operating cross-border routes from this hub. Devínska Nová Ves and Senec logistics parks concentrate contract warehousing capacity for just-in-time component sequencing.
Žilina Region
Kia Motors manufacturing pulls dedicated fleet capacity toward specialized automotive contract structures. Rail Cargo Group's electrified corridor from Hamburg terminates here, enabling modal shift for containerized manufacturing inputs. The Kysuce industrial zone absorbs hazardous materials warehousing for battery supply chain logistics.
Košice Region
E-commerce fulfillment networks are expanding same-day delivery coverage into this underpenetrated eastern corridor. The national transport regulator enforces EURO VI compliance standards uniformly across the region. The Kechnec industrial park attracts first-mover distribution center placement as logistics density lags western Slovakia.
Prešov Region
Pharmaceutical and electronics manufacturing requires temperature-controlled transport infrastructure that remains undersupplied. EU Green Deal emissions trading scheme cost pass-through affects fleet economics for carriers serving this peripheral market. Poprad-Tatry Airport cargo terminal handles limited high-value air freight volumes.
Trnava Region
Peugeot-Citroën assembly operations sustain dedicated contract logistics corridors alongside D1 motorway access. The EU emissions trading scheme expansion to road transport accelerates electric fleet pilot programs on fixed Bratislava-Vienna routes. Galanta and Dunajská Streda host consolidation facilities for cross-border retail distribution.
Slovakia Freight and Logistics Market Competitive Landscape
Concentration sits with integrated European network operators possessing balance sheet capacity for fleet electrification and customs brokerage infrastructure. The market structure tiers between multinational logistics platforms with EU-wide density and mid-sized Slovak carriers constrained by driver shortage and Mobility Package utilization limits. Strategic archetypes include automotive-dedicated contract logistics specialists, intermodal rail operators leveraging electrified corridors, and digital freight platforms compressing spot market transaction costs. Competitive moves center on charging infrastructure partnerships along western motorway corridors and warehouse automation investments near Bratislava's saturated industrial zones.
Among Germany-based integrated logistics providers, DACHSER Slovakia a.s. and Rhenus Group exemplify network-density archetypes that anchor cross-border road freight and value-added warehousing operations. Rail Cargo Group represents the state-backed intermodal specialist competing on electrified Hamburg-Žilina container corridors. These three operators occupy positions that reflect the market's structural division between asset-heavy European platforms and nationally focused carriers.
| Leading Market Players |
|---|
| Rhenus Group |
| DACHSER Slovakia a.s. |
| Rail Cargo Group |
| ROHLIG SUUS Logistics S.A. |
| Augustin Quehenberger Group GmbH |
| GEFCO Deutschland GmbH |
| Express Group, a.s. |
| TransLog Slovakia, a.s. |
| A.P. Moller - Maersk A/S |
| Others |
Value Network & Pricing Analysis
EURO VI emission compliance gates both fleet qualification and contract rate differentiation across Slovakia's automotive logistics corridors. Carriers lacking certified equipment face exclusion from Volkswagen and Kia procurement panels while electrified fleets command premium positioning on just-in-time routes.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between automotive OEMs and dedicated fleet operators. Three-tier pricing separates electrified premium services from standard EURO VI diesel fleets and economy-tier spot market capacity. Cost compression in the economy tier is intensifying because e-commerce parcel volumes absorb driver capacity at lower margins. Automotive contract logistics shows least price sensitivity due to penalty clauses for delivery failures, while retail distribution faces acute margin pressure from channel fragmentation.
Supply Chain Analysis
Inventory lead times compress toward four-hour windows for just-in-time component sequencing along the Bratislava-Zilina corridor. Geographic supply concentration centers on Germany for precision automotive components, Czech Republic for electronics assemblies, and Poland for steel and packaging materials. Raw material dependencies span lithium compounds for battery logistics, semiconductor chips for vehicle electronics, and specialized polymers for interior components. Single-source vulnerability sits with Hamburg Port rail connections for containerized imports. Distribution runs through dedicated contract fleets for automotive and fragmented parcel networks for e-commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slovakia's freight market fragments across service tiers, with e-commerce demand volatility creating white-space niches outside traditional automotive contract structures.
For Market Incumbents: Consolidate charging infrastructure partnerships along D1 and D2 motorway corridors before electrification mandates tighten. Acquire mid-sized Slovak carriers with established EU Mobility Package compliance expertise to offset driver shortage pressures. Vertical integration into battery supply chain logistics near InoBat manufacturing anchors defensible positioning. For New Entrants and Emerging Players: Lead with digital freight platforms targeting SME shippers in Košice and Prešov regions where logistics density lags western corridors. Micro-fulfillment placement in eastern Slovakia's underpenetrated e-commerce zones offers lowest competitive intensity. Partner with existing rail terminal operators for intermodal handoff capabilities rather than building asset-heavy road fleets. For Investors and Strategic Acquirers: EU Green Deal emissions trading scheme expansion to road transport reshapes the acquisition landscape toward electrified fleet operators with established automotive contracts. Five-to-ten year viability favors carriers with balance sheet capacity for charging infrastructure deployment alongside warehouse automation near Bratislava's saturated zones. Watch battery-electric truck residual value depreciation curves as inflection signals for fleet asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures corridor electrification along Bratislava-Vienna routes before competitor lock-in. |
| Automotive Contract Consolidation | Absorbs just-in-time penalty risk through dedicated fleet capacity near Kia and Stellantis plants. |
| Eastern Distribution Center Placement | Captures first-mover advantage in Košice-Prešov corridor before logistics density catches western Slovakia. |
| Rail Intermodal Investment | Feeds from Rail Cargo Group's Hamburg-Žilina electrified corridor for modal shift compliance. |
| Digital Freight Platform Launch | Compresses spot market transaction costs for SME shippers outside traditional contract structures. |
Research Methodology
A spread of perspectives from fleet operations managers, automotive procurement leads, rail terminal operators, and customs brokerage specialists converged on the working assumptions for Slovakia's logistics demand modeling. Primary interviews with these stakeholders combined with secondary validation from EU transport regulator filings, Rail Cargo Group corridor data, and automotive production databases. Bottom-up fleet capacity estimates and top-down GDP-trade elasticity models triangulated on segment sizing.
Segmentation dimensions modeled include service type, delivery model, transit mode, and customer vertical across the projection horizon. CAGRs derived from trend extrapolation of electrification investment cycles and e-commerce penetration curves. Industry-specific forecast inputs encompass EU Mobility Package utilization rate constraints and EURO VI fleet turnover schedules.
The analysis sits within stated boundaries; outcomes outside sustained automotive production volumes or accelerated EU emissions trading scheme implementation would require recalibration. Forecasts reflect documented assumptions about modal shift feasibility and charging infrastructure deployment pacing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
UK Logistics Market