
 Wine Cooler and Chest Freezer Market | 2026-2036
Wine Cooler and Chest Freezer Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Cooler and Chest Freezer Market Outlook
Software-defined temperature management is pivoting how manufacturers monetize wine coolers and chest freezers beyond the initial hardware sale. Haier leverages its smart-home ecosystem to bundle connected cooling units with subscription-based monitoring services. Whirlpool anchors its North American position through extensive service networks and extended warranty programs. Danby Products specializes in compact freestanding units for urban residential segments where space constraints dominate purchase decisions.
Wine coolers and chest freezers are thermally insulated appliances designed to maintain precise temperature ranges, with wine coolers typically operating between 45°F and 65°F using compressor or thermoelectric systems, while chest freezers sustain 0°F or below through high-density polyurethane foam insulation and sealed refrigeration circuits. Freestanding units occupy the largest volume position due to lower installation barriers and broader retail availability. The hospitality end-user segment generates premium margin pools as hotels and restaurants specify dual-zone wine coolers with precise humidity control and stainless-steel finishes.
The US Department of Energy enforces minimum efficiency standards that compel compressor redesigns and refrigerant transitions, while the European Ecodesign Directive and F-Gas Regulation restrict high-global-warming-potential refrigerants in imported cooling equipment. China's GB standards and MIIT energy-labeling requirements shape product specifications for manufacturers targeting domestic and export markets. Stakeholders must monitor refrigerant phase-down timelines and efficiency tier migrations when allocating R&D budgets and inventory across regional product lines.
Market Dynamics
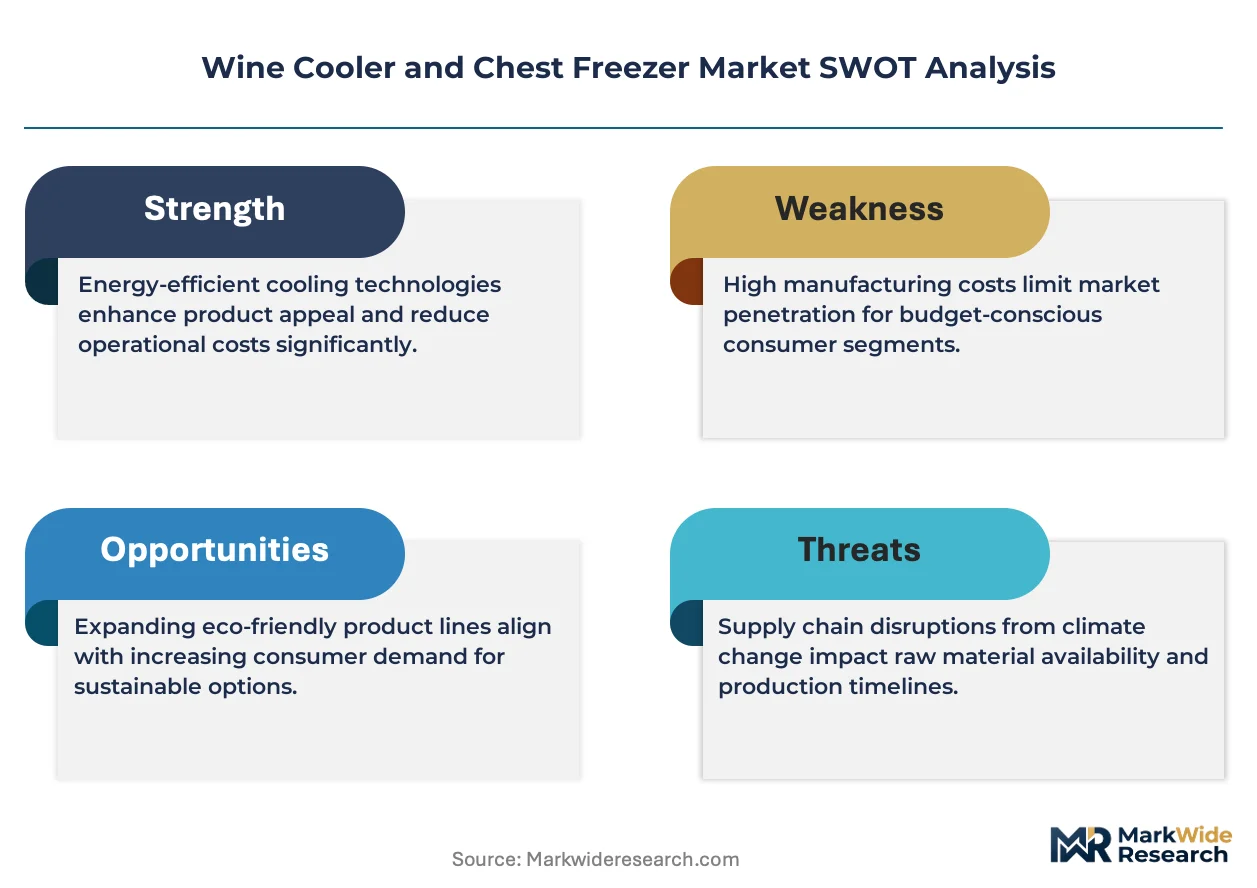
Compressor redesigns driven by refrigerant phase-down mandates under the US Department of Energy and European F-Gas Regulation are forcing manufacturers to absorb R&D costs while maintaining price positions in a margin-compressed environment.
Growth Catalysts
- Residential beverage preservation:Urban consumers in China and the United States are installing dedicated wine storage units as home entertainment infrastructure expands.
- European Ecodesign Directive:Efficiency tier migrations create replacement cycles for legacy cooling equipment across EU member states.
- Polyurethane foam insulation:Advances in high-density thermal barriers improve chest freezer performance metrics and extend holding times during power interruptions.
Market Restraints
- Copper and aluminum volatility:Sealed refrigeration circuit manufacturing faces input cost pressure from commodity metal price swings.
- Compressor supply concentration:Critical refrigeration component production clusters in China, creating single-source vulnerability for Western OEMs.
- Thermoelectric cooling limitations:Peltier systems cannot achieve sub-ambient temperatures required for long-term frozen food preservation.
Strategic Opportunities
- India residential penetration:Organized retail expansion and cold-chain awareness campaigns open first-time buyer segments in tier-2 cities.
- Subscription monitoring services:Connected cooling units bundled with predictive maintenance contracts generate recurring revenue streams.
- Dual-zone hospitality specifications:Hotels and restaurants demand precise humidity control and stainless-steel finishes at premium price points.
Industry Challenges
- Refrigerant certification timelines:Transition to low-global-warming-potential alternatives requires extensive safety testing and approval delays.
- Smart-home integration complexity:Legacy cooling units lack API compatibility with emerging home automation ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Cooler and Chest Freezer Market |
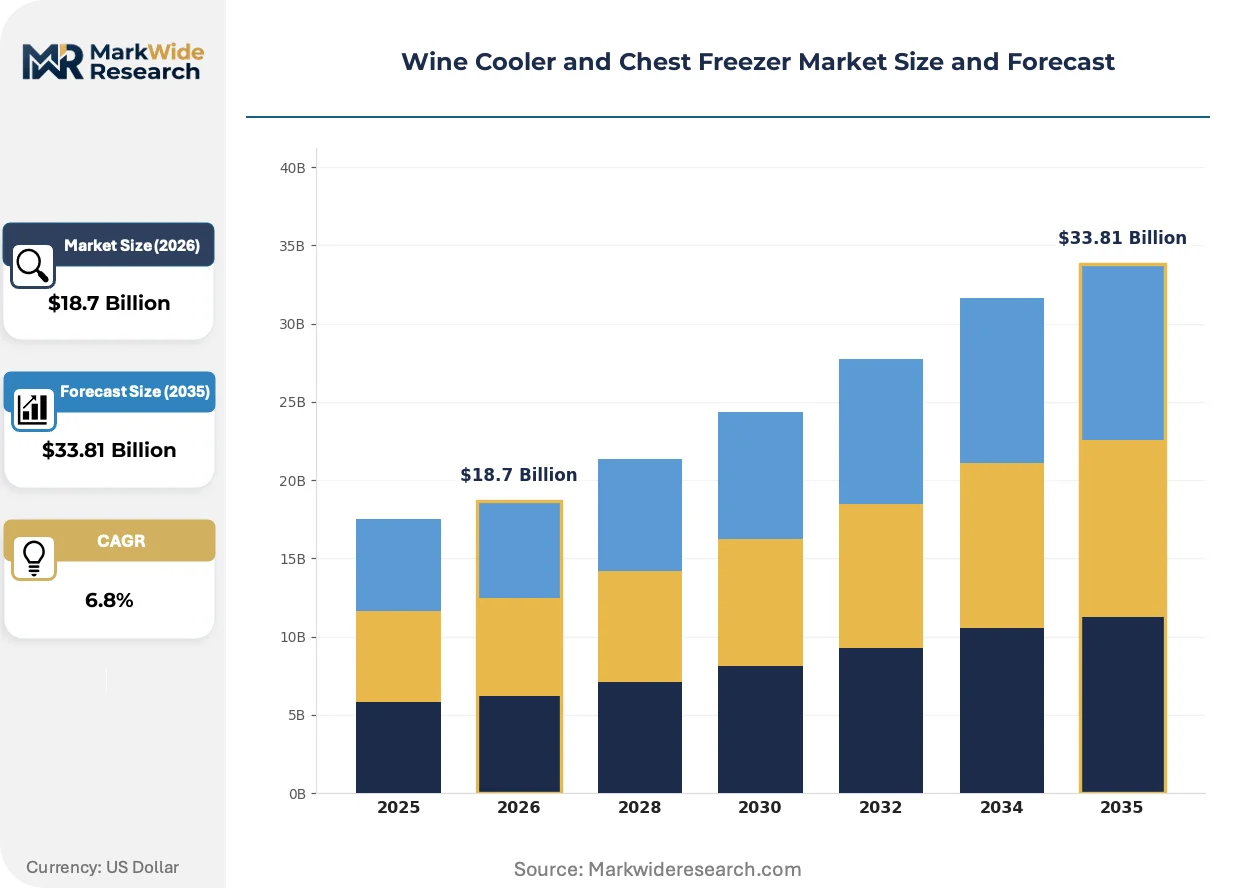
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Freestanding, Mini, Wine Cellar Dimensions: Compact, Standard, Large, Extra Large End User: Residential, Commercial, Hospitality, Retail Cooling Technology: Compressor, Thermoelectric, Dual Zone, Energy Efficient |
| Companies Covered | AB Electrolux, Haier, Whirlpool, The Middleby Corporation, Williams Refrigeration, Rockwell Industries Ltd., Frigidaire, Danby Products, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Cooler and Chest Freezer Market Strategic Shifts
Software-defined temperature management is compressing the traditional hardware-sales model and enabling service-based monetization across residential and commercial segments.
Variable-speed inverter compressors are automating energy consumption optimization by adjusting cooling cycles to thermal load conditions. Hospitality operators in France and Germany are specifying these units for wine cellar applications where temperature stability directly affects inventory value. The technology is automating manual thermostat intervention and reducing spoilage claims.
The European F-Gas Regulation is accelerating refrigerant transitions by banning high-global-warming-potential hydrofluorocarbons in new cooling equipment imports. Manufacturers serving EU markets must redesign sealed circuits around hydrocarbon or hydrofluoroolefin alternatives. Chest freezer product lines face the steepest compliance costs due to larger charge sizes and safety certification requirements.
Direct-to-consumer channel expansion is fragmenting traditional appliance retail relationships. Urban residential buyers in China and the United States are purchasing wine coolers through manufacturer-owned digital storefronts with white-glove delivery options. This bypasses big-box retail markups and captures first-party usage data for subscription service targeting.
Wine Cooler and Chest Freezer Market Segmentation
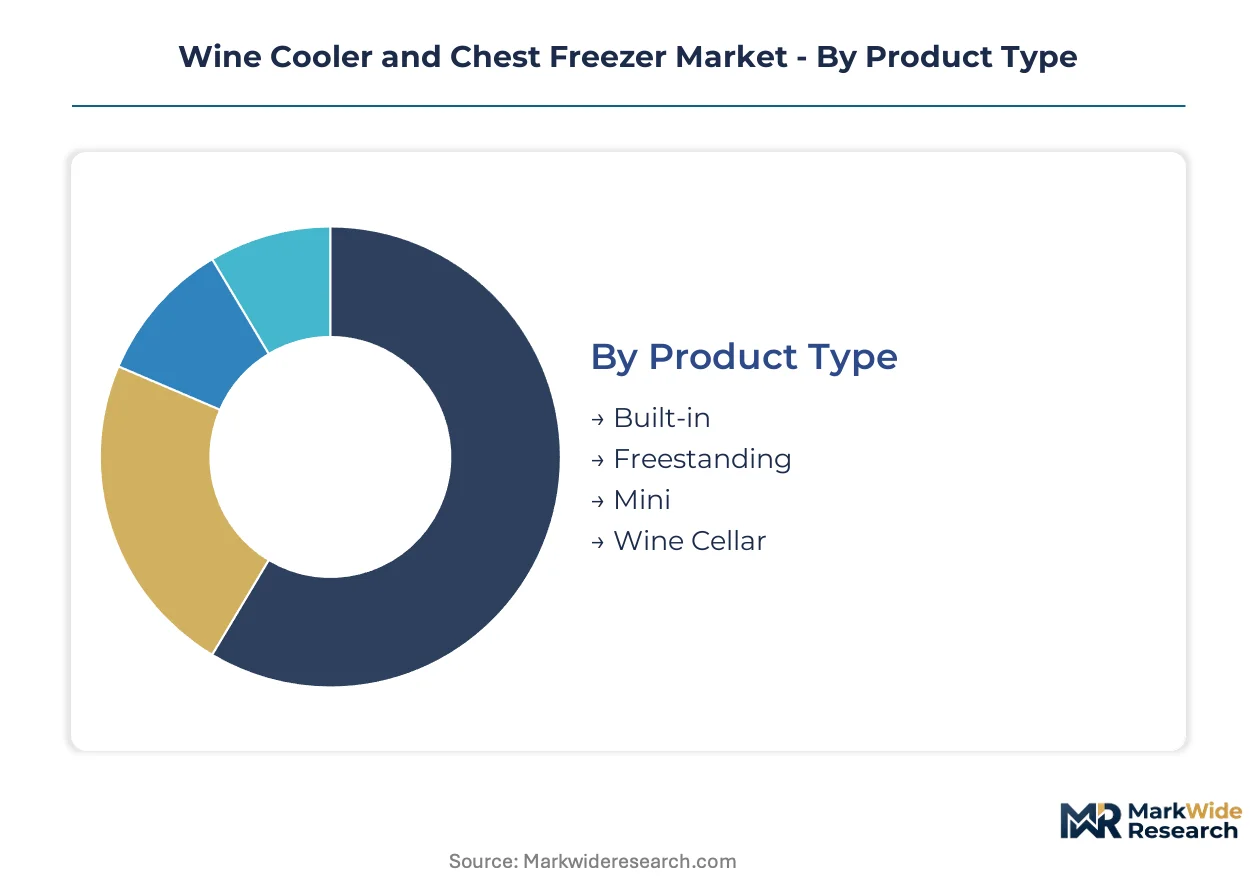
Segmentation in the Wine Cooler and Chest Freezer Market reveals how regulatory complexity, installation constraints, and end-use economics fragment demand across distinct product configurations. Each category carries specific certification burdens that shape manufacturer R&D allocation and regional market entry strategies.
Product Type:
Built-in units face the heaviest certification load under US DOE efficiency mandates and European Ecodesign Directive testing protocols, while freestanding models navigate broader retail compliance requirements across multiple jurisdictions.
- Built-in:These units integrate directly into cabinetry with front-venting compressor systems and zero-clearance side panels. Demand concentrates in upscale residential renovations across Germany and California, where kitchen design firms specify seamless appliance integration as a standard deliverable. The segment absorbs disproportionate R&D spending due to ventilation engineering requirements and UL safety certifications for enclosed installations.
- Freestanding:Self-contained refrigeration circuits with rear or side ventilation enable plug-and-play deployment without contractor involvement. Urban apartment dwellers in Shanghai and New York City drive volume, prioritizing mobility and lower acquisition cost over built-in aesthetics. Retail availability through big-box channels and direct-to-consumer platforms sustains this segment's volume leadership position.
- Mini:Countertop-scale units under 1.5 cubic feet serve dormitory, office, and secondary storage applications with thermoelectric or small-compressor architectures.
- Wine Cellar:Walk-in or large-capacity modular systems replicate professional storage conditions through redundant cooling zones and active humidity management.
Freestanding sits at the top of the volume ranking, with Built-in climbing the fastest.
Dimensions:
Physical footprint directly determines shipping economics, polyurethane foam insulation volume, and compressor sizing—factors that cascade through manufacturing cost structures and retail pricing tiers.
- Compact:Units under 3 cubic feet deploy single-door thermoelectric or mini-compressor systems for constrained spaces. Young professionals in Tokyo and London micro-apartments purchase these for dedicated beverage storage without sacrificing floor area. The segment trades thermal performance for spatial efficiency, limiting freezer applications to short-term holding.
- Standard:Mid-range capacities between 3 and 10 cubic feet balance holding volume with residential space constraints. Suburban homeowners in Texas and Florida favor these for secondary frozen food storage and moderate wine collections. This configuration dominates mass-market retail assortments due to freight efficiency and broad use-case applicability.
- Large:Chest freezers and dual-zone wine coolers exceeding 10 cubic feet require reinforced flooring and dedicated electrical circuits.
- Extra Large:Commercial-scale units above 20 cubic feet serve hospitality bulk storage and institutional foodservice operations.
Standard captures the largest installed base, though Compact is expanding most quickly in dense urban markets.
End User:
Customer type governs warranty expectations, service response requirements, and specification complexity—with hospitality and retail segments demanding enterprise-grade monitoring integration.
- Residential:Individual consumers prioritize acquisition cost, energy labeling visibility, and aesthetic compatibility with existing kitchen or entertainment spaces. First-time buyers in India's tier-2 cities and replacement purchasers across Italy and Spain sustain baseline demand. Purchase decisions hinge on star-rating certifications and manufacturer warranty terms rather than predictive maintenance capabilities.
- Commercial:Small restaurants, cafes, and independent retailers require NSF-certified food contact surfaces and documented temperature logging for health inspection compliance. Operators in France and Japan specify these units for back-of-house wine service and ingredient preservation. The segment accepts premium pricing for durability and service network coverage.
- Hospitality:Hotels and fine-dining establishments demand dual-zone precision, stainless-steel finishes, and API-compatible fleet management systems.
- Retail:Supermarkets and convenience chains deploy chest freezers for open-air frozen merchandise display with glass-top or coffin-style configurations.
Residential maintains volume dominance, while Hospitality commands the steepest margin expansion trajectory.
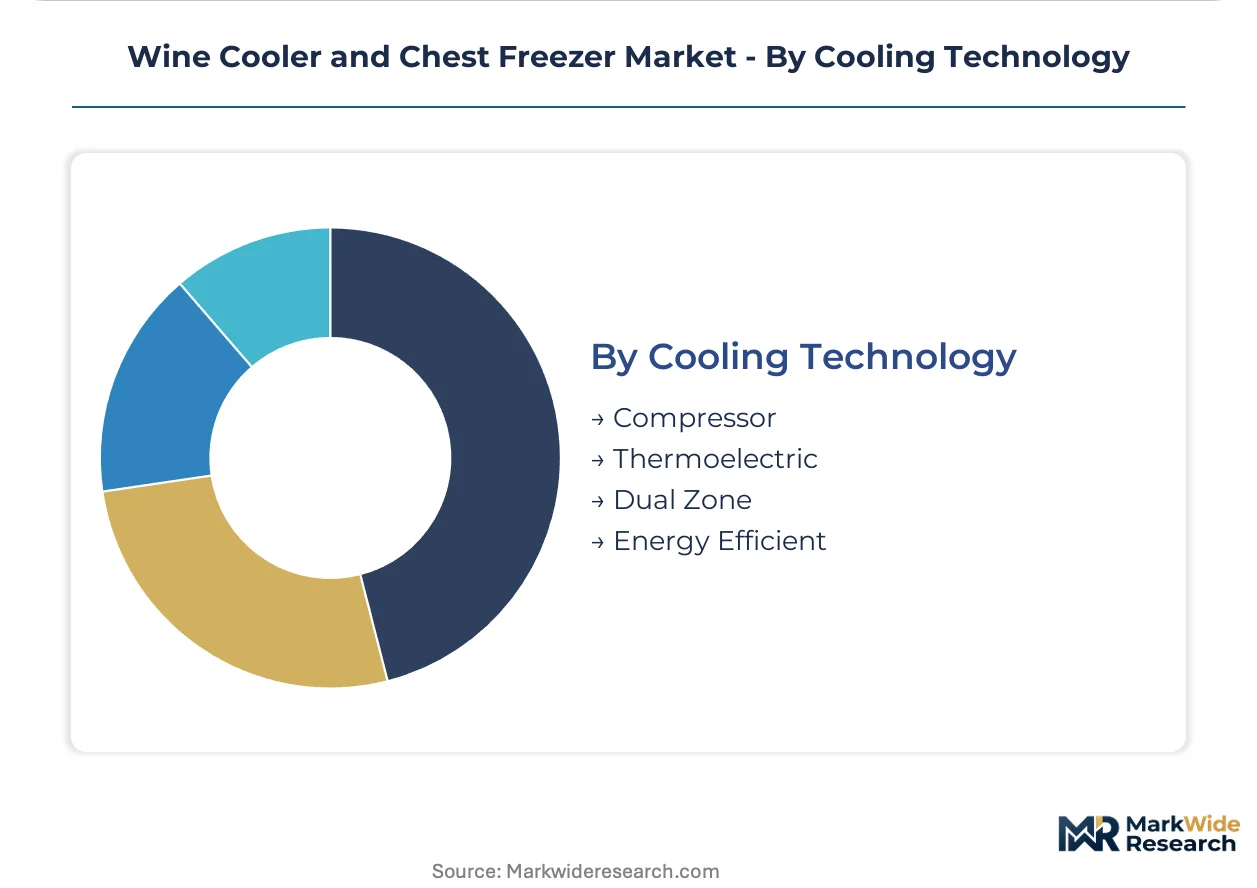
Cooling Technology:
Refrigerant chemistry and compressor architecture determine regulatory compliance timelines, with hydrocarbon and hydrofluoroolefin transitions creating product line segmentation.
- Compressor:Vapor-compression cycles using R600a (isobutane) or R290 (propane) achieve sub-zero temperatures required for long-term frozen food preservation. Manufacturers serving EU markets under F-Gas Regulation phase-down schedules have accelerated hydrocarbon adoption despite safety certification delays. This technology anchors all chest freezer applications and premium wine cooler segments.
- Thermoelectric:Peltier-effect solid-state cooling eliminates moving parts and refrigerant handling but cannot sustain sub-ambient temperatures below 40°F. Enthusiast collectors in Australia and boutique hotel operators deploy these for single-zone wine service where vibration elimination outweighs temperature range limitations. The segment avoids compressor noise and refrigerant regulatory exposure entirely.
- Dual Zone:Independent temperature compartments for red and white wine storage through separate evaporator circuits or insulated dividers.
- Energy Efficient:Variable-speed inverter compressors and enhanced polyurethane foam insulation meeting or exceeding top-tier efficiency certifications.
Compressor technology holds the largest installed base, with Energy Efficient configurations gaining share fastest amid regulatory tier migrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly to jurisdictions with lower refrigerant-handling compliance costs. China's MIIT energy-labeling regime and India's BIS standards create divergent cost structures that influence where sealed-circuit fabrication concentrates.
China
Domestic manufacturers anchor global chest freezer output through integrated compressor supply chains in Qingdao and Guangdong. MIIT's mandatory energy-efficiency labeling tiers accelerate R&D spending on variable-speed inverter systems. Haier and other Qingdao-based producers dominate both domestic distribution and export channels to Southeast Asia and Africa.
United States
Residential wine cooler adoption accelerates in California and Texas as home entertainment infrastructure expands. DOE minimum efficiency standards compel compressor redesigns and refrigerant transitions that raise manufacturing compliance costs. Appliance manufacturing clusters in the Midwest and Southeast absorb these regulatory burdens through captive R&D facilities.
Germany
European Ecodesign Directive efficiency tier migrations drive replacement cycles for legacy cooling equipment across Bavaria and North Rhine-Westphalia. F-Gas Regulation phase-down schedules ban high-GWP hydrofluorocarbons in new equipment imports. Stuttgart-based engineering firms specialize in hydrocarbon refrigerant safety certification for EU-bound product lines.
India
Organized retail expansion in Maharashtra and Karnataka opens first-time buyer segments for compact freestanding units. BIS certification requirements and CEA energy-labeling standards shape product specifications for domestic manufacturers. Tier-2 cities in Gujarat and Tamil Nadu emerge as distribution hubs for cold-chain awareness campaigns targeting residential penetration.
Japan
Premium hospitality specifications in Tokyo and Osaka drive demand for dual-zone wine coolers with precise humidity control. METI efficiency standards and JIS certification protocols maintain high barriers to market entry for imported equipment. Nagoya-based component suppliers specialize in compact compressor architectures for space-constrained urban installations.
Wine Cooler and Chest Freezer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated appliance conglomerates commanding hospitality and retail channels while regional fabricators serve price-sensitive residential tiers. Market structure tilts toward consolidation at the premium end and fragmentation in compact residential categories. Three archetypes dominate: full-line appliance conglomerates with smart-home ecosystems, regional specialists in compact urban formats, and hospitality-focused premium fabricators. Competitive moves concentrate on M&A for connected-platform capabilities and capacity expansion in low-cost manufacturing zones.
Among full-line conglomerates, AB Electrolux and Whirlpool exemplify the scale-driven archetype with extensive service networks and extended warranty programs that lock in commercial accounts. Haier represents the integrated-platform model, leveraging smart-home ecosystems to bundle hardware with subscription-based monitoring services. Danby Products occupies a specialist position within the compact freestanding segment, serving urban residential buyers where space constraints dominate purchase decisions.
| Leading Market Players |
|---|
| AB Electrolux |
| Haier |
| Whirlpool |
| The Middleby Corporation |
| Williams Refrigeration |
| Rockwell Industries Ltd. |
| Frigidaire |
| Danby Products |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Captive compressor production in Qingdao and Guangdong anchors supply positions for Haier and domestic Chinese manufacturers, translating into pricing power through in-house R600a refrigerant handling and zero-margin component markups. This vertical control allows integrated players to absorb European F-Gas Regulation compliance costs while maintaining price positions against Western OEMs dependent on external compressor sourcing.
Pricing Analysis
Retailer markup layers dominate pricing architecture, with big-box channels extracting 25-35 point spreads before final consumer pricing. Three-tier pricing structure across premium, standard, and economy levels separates hospitality-grade dual-zone units with API integration from mass-market freestanding models and compact thermoelectric entry points. Cost compression in the standard tier intensifies because copper and aluminum volatility feeds directly into sealed circuit manufacturing. Residential buyers in tier-2 Indian cities exhibit highest price sensitivity, while hospitality operators in Tokyo and Paris accept premium positioning for fleet management compatibility.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Dallas, and Singapore orchestrate hub-and-spoke patterns for finished goods, with Qingdao, Guangdong, and Mexico anchoring manufacturing concentration. Critical inputs include high-density polyurethane foam insulation, variable-speed inverter compressors, and hydrocarbon refrigerant charges. Single-source vulnerability clusters in Chinese compressor fabrication, exposing Western OEMs to MIIT energy-labeling enforcement disruptions. Distribution runs through manufacturer-owned digital storefronts and traditional appliance retail networks in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine cooler and chest freezer demand compounds steadily through residential beverage preservation infrastructure buildout and regulatory-forced replacement cycles across efficiency tier migrations.
For Market Incumbents: Hedge refrigerant transition risk by accelerating hydrocarbon safety certification investments ahead of F-Gas Regulation phase-down deadlines. Deepen backward integration into compressor architectures to defend margin position against commodity metal volatility. Lock in hospitality accounts through extended warranty bundling that raises switching costs for dual-zone fleet operators. For New Entrants and Emerging Players: Launch via direct-to-consumer digital storefronts targeting compact freestanding demand in dense urban markets where space constraints override brand loyalty. Penetrate India's tier-2 cities through organized retail partnerships before incumbent service networks solidify. Emphasize thermoelectric simplicity to bypass compressor supply concentration entirely. For Investors and Strategic Acquirers: Consolidation pressure builds where smart-home platform integration capabilities fragment across regional specialists. Long-term viability favors full-line appliance conglomerates with captive R&D facilities and subscription service infrastructure. Target acquisition profiles center on compact urban specialists with direct-to-consumer logistics assets. Monitor refrigerant certification timeline delays as inflection signal for margin compression windows.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Inverter Integration | Automates energy optimization under DOE and Ecodesign efficiency mandates. |
| Hydrocarbon Refrigerant Transition | Secures EU market access ahead of F-Gas Regulation import bans. |
| Subscription Monitoring Launch | Generates recurring revenue from Haier-style smart-home ecosystem bundling. |
| Direct-to-Consumer Channel Expansion | Bypasses big-box retail markups and captures first-party usage data. |
| Compact Urban Format Development | Addresses Tokyo and New York City space constraints with sub-3-cubic-foot designs. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each market's stakeholder ecosystem. The research combines structured interviews with appliance manufacturing executives, compressor engineering leads, hospitality procurement directors, retail category buyers, and regulatory affairs specialists with secondary validation through customs trade data, MIIT energy-labeling disclosures, DOE efficiency standard filings, and EEA F-Gas Regulation implementation reports. Bottom-up unit shipment modeling triangulates against top-down value estimates across the projection horizon.
Granularity-level framing applies separate modeling tracks for built-in versus freestanding installation constraints, compressor versus thermoelectric cooling architectures, and residential versus hospitality end-use economics. CAGRs derive from segmented volume projections calibrated to regulatory replacement cycle timing and cold-chain awareness campaign penetration curves. Industry-specific forecast inputs include polyurethane foam insulation cost indices and hydrocarbon refrigerant safety certification pipeline visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt refrigerant phase-down acceleration or compressor supply disruption scenarios. Outputs reflect documented assumptions around efficiency tier migration schedules and MIIT labeling enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Germany Probiotic Drinks Market
Beverages
Fiber Fortified Beverages Market
Beverages
United States Sports and Energy Drinks Market
Beverages
Flavored Powder Drinks Market
Beverages
Beverage Cooler Market
Beverages
Recovery Drinks Market
Beverages
North America Energy Drink Market
Beverages
Chocolate Malt Drink Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Europe Yerba Mate Market
Beverages
India Bottled Water Market
Beverages
Kvass Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Juice Concentrates Market