
 United States Emergency Lighting Market | 2026-2036
United States Emergency Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
United States Emergency Lighting Market Intelligence
California's Title 24 energy standards, mandating higher efficiency in non-residential buildings, is consolidating demand towards advanced, low-power emergency lighting systems. Acuity Brands Inc. leverages its broad portfolio of lighting controls and fixtures to serve large-scale commercial projects. Eaton Corporation plc competes on the resilience of its integrated life safety solutions for industrial and utility customers. Hubbell Incorporated specializes in robust fixtures designed for harsh and hazardous environments.
United States emergency lighting encompasses self-powered or centrally-powered illumination systems designed for activation during a main power failure. These systems must maintain a minimum illumination level, typically one foot-candle, for at least 90 minutes to ensure safe occupant egress from a building. Within the light source segment, LED technology has almost entirely displaced fluorescent and incandescent options due to superior longevity and energy efficiency. While exit signs represent a mature, code-mandated product category, integrated backup lights for commercial buildings are seeing faster adoption in new construction and major retrofits.
The Occupational Safety and Health Administration (OSHA) mandates emergency lighting for workplace safety, referencing standards like NFPA 101. Product compliance is governed by certification bodies such as UL, which tests systems against the UL 924 standard for power equipment and emergency lighting. Future competitive advantage will hinge on developing systems with automated self-testing and network connectivity features that reduce lifetime maintenance costs for facility managers.
Market Dynamics
The United States emergency lighting market is defined by the mandated transition toward energy-efficient LED technology. This shift, enforced by stringent state-level building and energy codes, is the central force compelling upgrades and shaping product development across the industry.
Growth Catalysts
- Stringent Energy Codes:Regulations such as California's Title 24 create non-negotiable demand for high-efficiency, low-power LED emergency lighting and exit signs in new non-residential construction and major retrofits, accelerating the replacement of older technologies.
- Infrastructure Modernization:Federal and state investment in upgrading public infrastructure, especially within transportation hubs like airports and train stations, provides a significant and sustained catalyst for the installation of advanced, code-compliant emergency egress systems.
- Integrated Safety Systems:Facility owners are increasingly specifying emergency lighting that integrates with building automation systems, driving demand for networked products that offer centralized monitoring, automated testing, and streamlined maintenance reporting.
Market Restraints
- High Initial Cost:The upfront capital expenditure for networked, self-diagnostic emergency lighting systems is substantially higher than for basic, standalone battery units, deterring adoption in smaller commercial properties and budget-constrained retrofit projects.
- Integration Complexity:Ensuring seamless interoperability between new emergency lighting systems and legacy building management systems (BMS) in older structures presents a significant technical barrier, often requiring costly custom integration work. li>Component Supply Volatility: The reliance on a concentrated global supply chain for critical electronic components, such as microcontrollers and specialized LED drivers, exposes manufacturers in the United States to price fluctuations and potential availability disruptions.
Strategic Opportunities
- Networked Self-Diagnostics:Developing systems with automated testing and cloud-based reporting capabilities offers a compelling value proposition to facility managers by drastically reducing lifetime maintenance labor costs and improving compliance assurance.
- Public Sector Retrofits:A large installed base of outdated emergency lighting in public facilities, including schools, universities, and municipal buildings across the United States, represents a substantial, underpenetrated market for LED conversion projects.
- Convergence with IoT:Integrating emergency lighting with broader building IoT platforms allows for enhanced functionality, such as dynamic egress routing during emergencies, creating new value streams beyond basic code compliance for smart buildings.
Industry Challenges
- Skilled Labor Scarcity:The market faces a shortage of electricians and technicians who possess the requisite IT and networking skills to properly install, commission, and maintain sophisticated, software-driven emergency lighting control systems.
- Fragmented Code Enforcement:Navigating the complex and often inconsistent patchwork of state and local amendments to national standards like NFPA 101 creates significant compliance burdens and design challenges for manufacturers and installers.
- Interoperability Standards:A lack of universal communication protocols for emergency lighting hinders the plug-and-play integration of fixtures and control panels from different vendors, locking customers into single-vendor ecosystems and limiting flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Emergency Lighting Market |
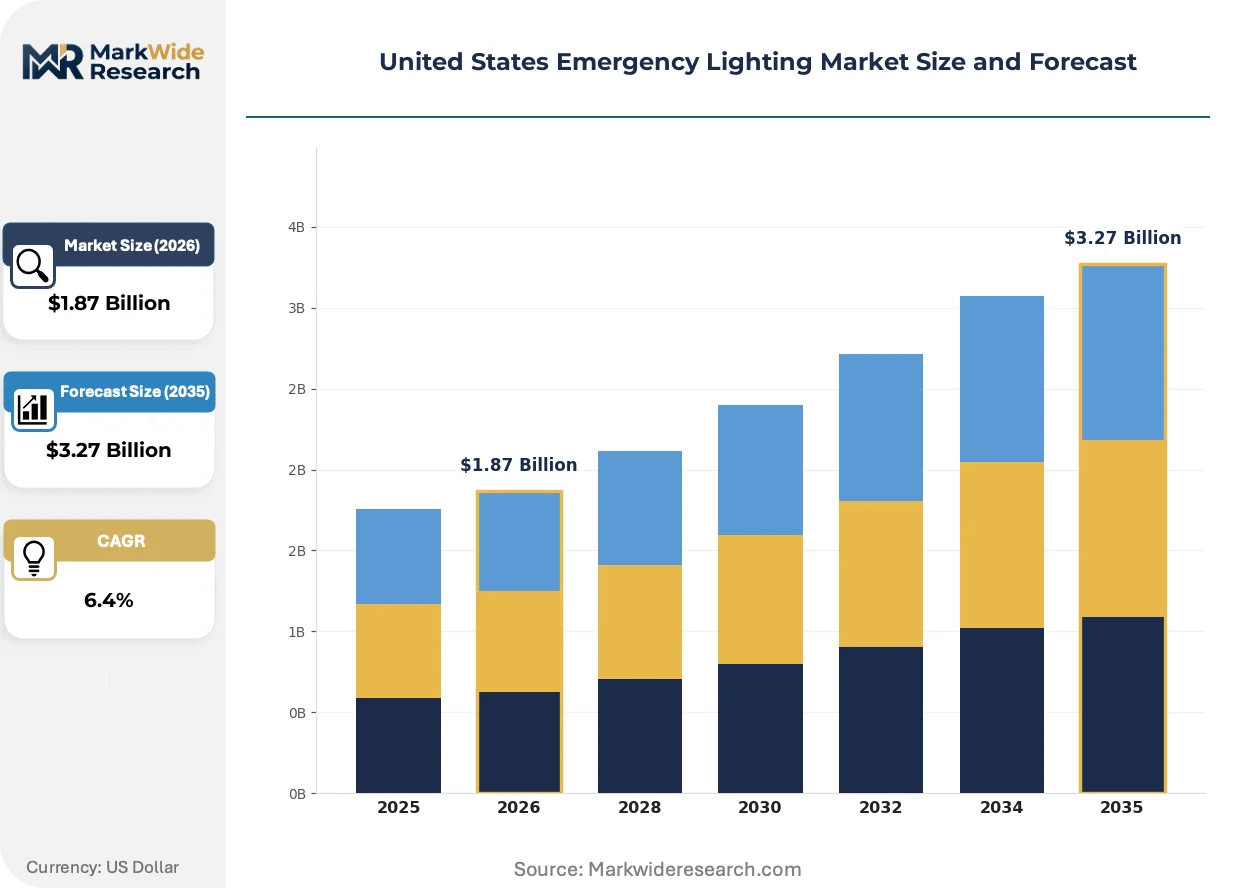
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exit Signs, Backup Lights, Spotlight Fixtures, Strip Lighting, Portable Lanterns Light Source: LED, Fluorescent, Halogen, Incandescent, Xenon Application: Commercial Buildings, Public Spaces, Transportation Terminals, Educational Facilities, Warehouses End User: Facility Managers, Safety Officers, Property Developers, Security Contractors, Emergency Services |
| Companies Covered | Acuity Brands Inc., Eaton Corporation plc, Hubbell Incorporated, ABB Ltd, Signify N.V., Schneider Electric, Emerson Electric Co., Legrand SA, Honeywell International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Emergency Lighting Market Strategic Shifts & Innovations
The market's evolution reflects a fundamental shift from passive, standalone safety hardware to active, intelligent life-safety infrastructure. This transformation is driven by the convergence of solid-state lighting, network connectivity, and a greater emphasis on total cost of ownership over initial purchase price.
Wireless mesh networking technology provides a robust communication backbone for emergency lighting fixtures without requiring dedicated control wiring. Facility operators in large-scale environments like hospitals and university campuses are adopting these systems to simplify installation in complex or historic buildings. This technology is decentralizing system management, shifting control from a single hardwired panel to cloud-based dashboards accessible from any location and improving overall system resilience.
Stricter enforcement of NFPA 101 Life Safety Code requirements by OSHA is compelling a market-wide move toward automated testing. This regulatory pressure makes manual monthly and annual testing of emergency lights economically unviable and unreliable for large facilities. The commercial real estate sector in the United States is most affected, rapidly adopting systems with self-diagnostic capabilities to ensure auditable compliance and reduce operational overhead.
A notable change in purchasing behavior is the pivot from lowest-cost hardware acquisition toward a total cost of ownership (TCO) evaluation. This disrupts the traditional distributor-led sales model that prioritized upfront price, creating an opening for systems that demonstrate lower energy and maintenance expenses over their lifecycle. This trend is most visible among institutional buyers in the United States, such as healthcare systems and government agencies, who manage large property portfolios.
United States Emergency Lighting Market Segmentation
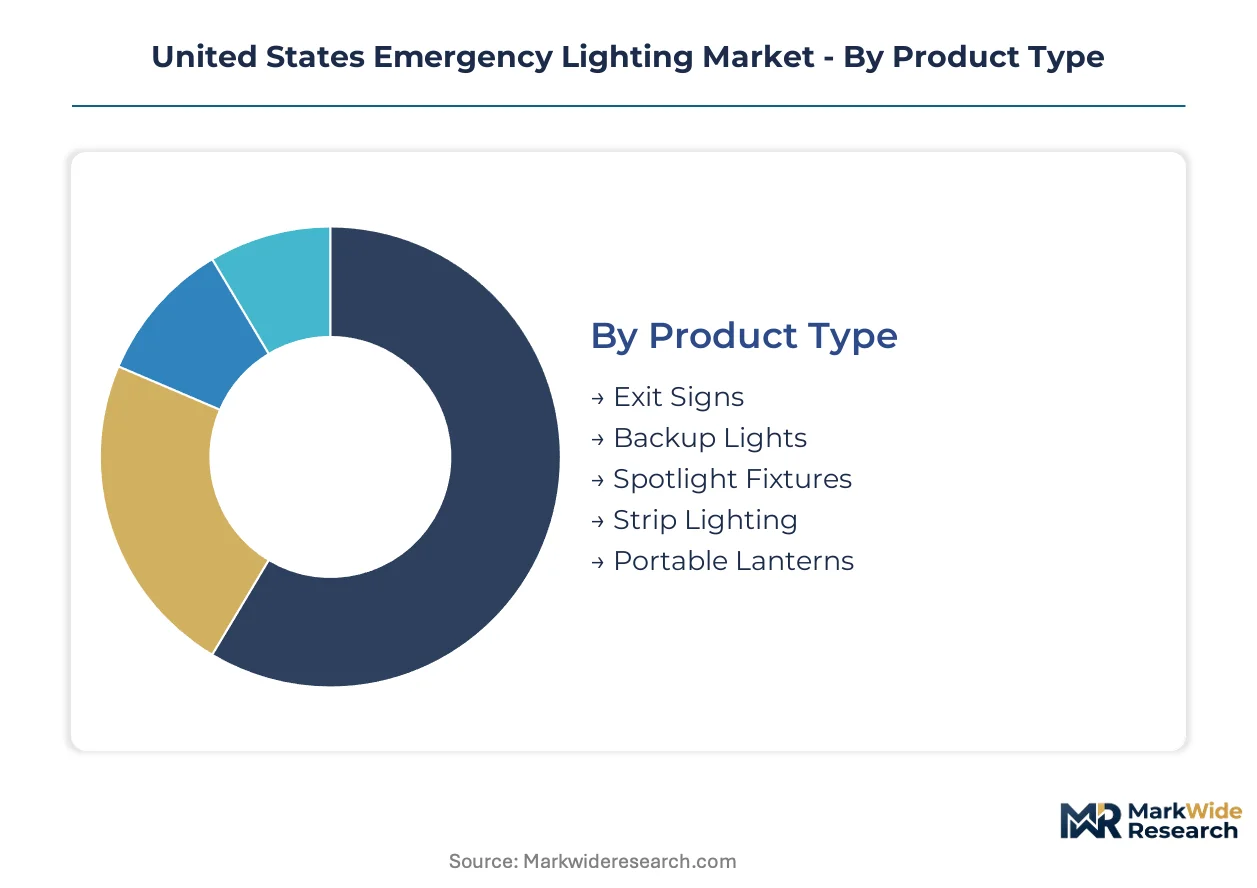
The United States emergency lighting market exhibits diverse needs across various product types, light sources, applications, and end-users. Understanding these segments helps manufacturers tailor solutions and identify specific growth avenues. Each category reveals distinct purchasing criteria and operational demands.
Product Type:
Buyer priorities in the product type segment emphasize specific functionality and compliance requirements for different environments.
- Exit Signs:Exit signs provide illuminated guidance for safe egress during power outages, mandated by safety codes like NFPA 101. Demand concentrates within commercial real estate, driven by stringent building safety regulations and scheduled inspections.
- Backup Lights:Backup lights offer integrated, temporary illumination to maintain minimum light levels when main power fails. New construction projects and major retrofits across the United States drive significant adoption for these advanced systems.
- Spotlight Fixtures:Spotlight fixtures deliver focused emergency illumination for specific critical areas or equipment.
- Strip Lighting:Strip lighting provides continuous, low-profile emergency illumination along corridors and pathways.
- Portable Lanterns:Portable lanterns offer temporary, mobile emergency light sources for immediate localized needs.
Exit Signs leads volumes today; Backup Lights is gaining share fastest.
Light Source:
The market's evolution in light sources reflects a fundamental shift towards energy efficiency and longevity across all applications.
- LED:LED technology utilizes solid-state diodes for highly efficient and long-lasting illumination, consuming significantly less power than traditional sources. Stringent energy codes, including California's Title 24, drive its widespread adoption in new commercial and public buildings.
- Fluorescent:Fluorescent lighting uses gas-discharge tubes to produce light, offering moderate efficiency but shorter lifespans compared to LEDs. Legacy installations in older commercial properties still utilize this technology, though replacement is ongoing.
- Halogen:Halogen lamps provide bright, focused light, primarily used in older spotlight fixtures due to lower efficiency.
- Incandescent:Incandescent bulbs offer basic illumination but are largely phased out due to their low energy efficiency and short operational life.
- Xenon:Xenon lamps deliver intense, bright light for specialized applications, though their use in emergency lighting is limited.
LED technology dominates the market; Fluorescent installations are declining.
Application:
Customer requirements vary significantly across application environments, dictating specific fixture designs and integration needs.
- Commercial Buildings:Commercial buildings encompass offices, retail spaces, and hospitality venues requiring robust, code-compliant emergency lighting systems. Ongoing retrofits and new construction projects in urban centers drive substantial demand.
- Transportation Terminals:Transportation terminals, including airports and train stations, demand durable emergency lighting solutions for high-traffic public areas. Federal and state infrastructure modernization initiatives provide a sustained catalyst for these facilities.
- Public Spaces:Public spaces like museums and convention centers require aesthetically integrated emergency lighting for occupant safety.
- Educational Facilities:Educational facilities such as schools and universities prioritize reliable emergency egress systems for student and staff safety.
- Warehouses:Warehouses need rugged, high-output emergency lighting to ensure safe operations in large industrial environments.
Commercial Buildings command the largest share; Transportation Terminals exhibit the steepest expansion trajectory.
End User:
The purchasing priorities of end-users shape product features and service requirements, focusing on compliance, cost, and operational ease.
- Facility Managers:Facility managers oversee building operations and maintenance, prioritizing emergency lighting systems with automated self-testing and network connectivity. Their focus on total cost of ownership drives demand for solutions reducing lifetime labor expenses.
- Property Developers:Property developers focus on new construction and major renovations, seeking integrated emergency lighting solutions that meet stringent building codes. They value systems that simplify installation and ensure rapid occupancy approval.
- Safety Officers:Safety officers ensure workplace safety and compliance with OSHA regulations, favoring reliable and easily auditable emergency lighting.
- Security Contractors:Security contractors integrate emergency lighting with broader life safety and security systems, valuing interoperability and centralized control.
- Emergency Services:Emergency services personnel require clear egress pathways and reliable illumination during incidents, influencing design for visibility and durability.
Facility Managers drive significant replacement demand; Property Developers are expanding new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States emergency lighting market is significantly shaped by the concentration of skilled electrical and construction professionals. This workforce is crucial for installing and maintaining advanced life safety systems across diverse building types. Their expertise ensures compliance with evolving federal and state regulations, driving demand for sophisticated solutions.
California
California's stringent building safety and energy efficiency regulations drive substantial demand for advanced emergency lighting systems. Title 24 energy standards mandate high-efficiency LED solutions in new non-residential construction and major retrofits across the state. Technology hubs like Silicon Valley and urban centers such as Los Angeles lead in adopting integrated, low-power emergency egress solutions for complex facilities.
New York Metro
New York Metro's dense urban environment and continuous infrastructure modernization create consistent demand for reliable emergency lighting. The New York City Building Code, aligned with NFPA 101, requires robust egress illumination in high-rise commercial and residential structures. Major transportation hubs and commercial districts in Manhattan and Brooklyn are prioritizing networked safety systems with automated testing capabilities.
Texas
Texas experiences robust demand for emergency lighting systems due to its rapid commercial expansion and significant industrial growth. The state's building codes emphasize resilient safety infrastructure for large-scale facilities and public venues. Major metropolitan areas like Houston and Dallas-Fort Worth are seeing substantial installations in new data centers, manufacturing plants, and logistics facilities.
Southeast (Florida/Georgia)
The Southeast region, particularly Florida and Georgia, sees demand from expanding tourism infrastructure and a growing population. Florida Building Code and Georgia State Minimum Standard Codes enforce strict emergency lighting requirements for public and commercial venues. Coastal development in Miami and the logistics hubs around Atlanta are actively adopting advanced LED emergency systems for enhanced safety and compliance.
United States Emergency Lighting Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the United States emergency lighting market, creating a tiered competitive structure. The market exhibits consolidation among established manufacturers, while niche players focus on specialized solutions for specific applications. Archetypes include diversified electrical equipment conglomerates and specialized life safety system providers focusing on compliance. Dominant competitive moves involve strategic partnerships for technology integration and portfolio diversification into smart building automation solutions.
On the premium-tier vector, Acuity Brands Inc. and Eaton Corporation plc represent established players offering comprehensive emergency lighting portfolios. Acuity Brands Inc. occupies a position as a broad lighting controls and fixture provider, serving large-scale commercial projects with advanced systems. Eaton Corporation plc exemplifies integrated life safety solutions for industrial and utility customers, emphasizing system resilience. Hubbell Incorporated, an industrial products manufacturer, anchors a segment specializing in robust fixtures designed for harsh and hazardous environments, catering to specific compliance needs.
| Leading Market Players |
|---|
| Acuity Brands Inc. |
| Eaton Corporation plc |
| Hubbell Incorporated |
| ABB Ltd |
| Signify N.V. |
| Schneider Electric |
| Emerson Electric Co. |
| Legrand SA |
| Honeywell International |
| Others |
Cost & Logistics Intelligence
Diversified electrical equipment conglomerates influence emergency lighting pricing by leveraging captive component supply and integrated solutions. Their scale dictates supply chain efficiency, impacting overall cost structures across the United States market.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences emergency lighting system pricing. Project-based pricing dominates the market, with costs differentiated by certification level, notably UL 924 compliance, and the extent of integrated life safety solutions. Price differentiation also arises from customized solutions for harsh environments and automated self-testing features. Pricing softness stems from intense competition among manufacturers for large commercial and retrofit projects. Smaller commercial properties exhibit higher price sensitivity compared to institutional buyers prioritizing total cost of ownership and compliance.
Supply Chain Analysis
Domestic-content mandates for public infrastructure projects are reshaping emergency lighting component sourcing within the United States. The supply chain draws from concentrated global production centers in China and Southeast Asia for microcontrollers and specialized LED drivers. Component supply volatility, particularly for advanced electronics, poses a significant structural risk for manufacturers. The market relies on materials like aluminum for fixtures and lithium-ion for battery backup units. Distribution runs through a mix of electrical distributors, value-added resellers, and direct sales channels to large facility owners and government agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States emergency lighting market presents a clear margin-expansion story, driven by the increasing shift towards premium, networked self-diagnostic systems.
For Market Incumbents: Anticipate further consolidation through strategic acquisitions of specialized software firms to counter the threat of agile, IoT-focused entrants. Incumbents should invest heavily in R&D for automated self-testing and cloud-based reporting platforms to reduce facility managers' lifetime maintenance costs. Reinforce channel partnerships with electrical contractors capable of installing and commissioning sophisticated, software-driven systems. Focus on integrating life safety solutions with broader building management systems to differentiate from basic hardware providers.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce platforms offer a viable route for new entrants to penetrate the fragmented small to medium-sized commercial property segment. Target underpenetrated public sector retrofits, particularly schools and municipal buildings, with cost-effective, easy-to-install LED conversion kits. Leverage cloud-native software solutions for simplified compliance reporting and remote diagnostics as a key go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional hardware manufacturers lacking integrated software capabilities or strong recurring revenue streams. The long-term viability of this market is strong, extending beyond a five-year window, driven by continuous infrastructure upgrades and evolving safety codes. Seek out companies with proprietary wireless mesh networking technology or strong intellectual property in dynamic egress routing. A signal to watch is the widespread adoption of universal communication protocols for building IoT systems, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Networked Self-Testing Systems | Reduces operational overhead for facility managers and ensures auditable compliance with NFPA 101. |
| Expand Wireless Mesh Networking | Simplifies installation in complex commercial buildings and enhances system resilience for large campuses. |
| Pursue Public Sector Retrofit Contracts | Addresses a substantial, underpenetrated market for LED emergency lighting conversions in schools. |
| Integrate with Building IoT Platforms | Unlocks new value streams like dynamic egress routing for smart commercial buildings. |
| Invest in Skilled Labor Training Programs | Addresses the scarcity of technicians capable of commissioning advanced software-driven systems. |
Research Approach
Coverage spans the United States, with primary inputs from key regions like California, New York Metro, and Texas. This involved combining primary interviews with industry stakeholders, including facility managers, property developers, and electrical engineers, with robust secondary validation. Secondary sources included OSHA mandates, UL certification standards, NFPA 101 code documents, and state-level energy code publications. Bottom-up market sizing and top-down validation ensured comprehensive data triangulation.
Rate-of-change decomposition analyzes market dynamics across the analysis window, projecting future growth. The model segments by product type, light source, application, and end-user, alongside a specific dimension for connectivity features. Compound Annual Growth Rates were derived from historical data trends and projected regulatory impacts. Key forecast inputs included infrastructure spending projections and energy efficiency code adoption rates.
The model assumes a particular technology adoption path; alternative pathways for widespread IoT integration would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and component supply chain resilience. Unforeseen shifts in building codes or major economic downturns represent key risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market