
 Explosion Proof Devices Market | 2026-2036
Explosion Proof Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Proof Devices Market Analytics
The gap between premium certified systems and basic compliance-grade hardware is recalibrating procurement patterns across hazardous industries. Siemens leverages its IECEx-certified automation portfolio to command premium positioning in upstream oil platforms. Eaton Corporation anchors its presence through integrated power distribution solutions purpose-built for Zone 1 environments. R. STAHL specializes in compact flameproof terminal boxes that differentiate on installation footprint in congested chemical plants.
Explosion proof devices are engineered electrical and mechanical systems designed to contain internal ignition and prevent flame transmission into explosive atmospheres, typically rated for gas groups IIA through IIC and temperature classes T1 through T6. Their primary purpose is to sustain continuous operations in environments where flammable gases, vapors, or combustible dusts persist. Sensors and cameras are gaining share fastest as predictive maintenance programs digitize hazardous area monitoring. Lighting remains the most mature product category with replacement-driven demand concentrated in legacy petrochemical installations. Wireless technology is displacing wired infrastructure in retrofit applications where conduit installation proves prohibitively expensive.
ATEX directives in Europe, IECEx schemes administered from Australia, and OSHA standards enforced by the US Department of Labor collectively dictate enclosure design, testing protocols, and market access conditions for manufacturers. These frameworks elevate engineering costs for new entrants while locking in recurring certification revenue for established laboratories. Stakeholders must weigh the capital requirements of dual-certification strategies against the customer concentration risk of single-geo dependence.
Market Dynamics
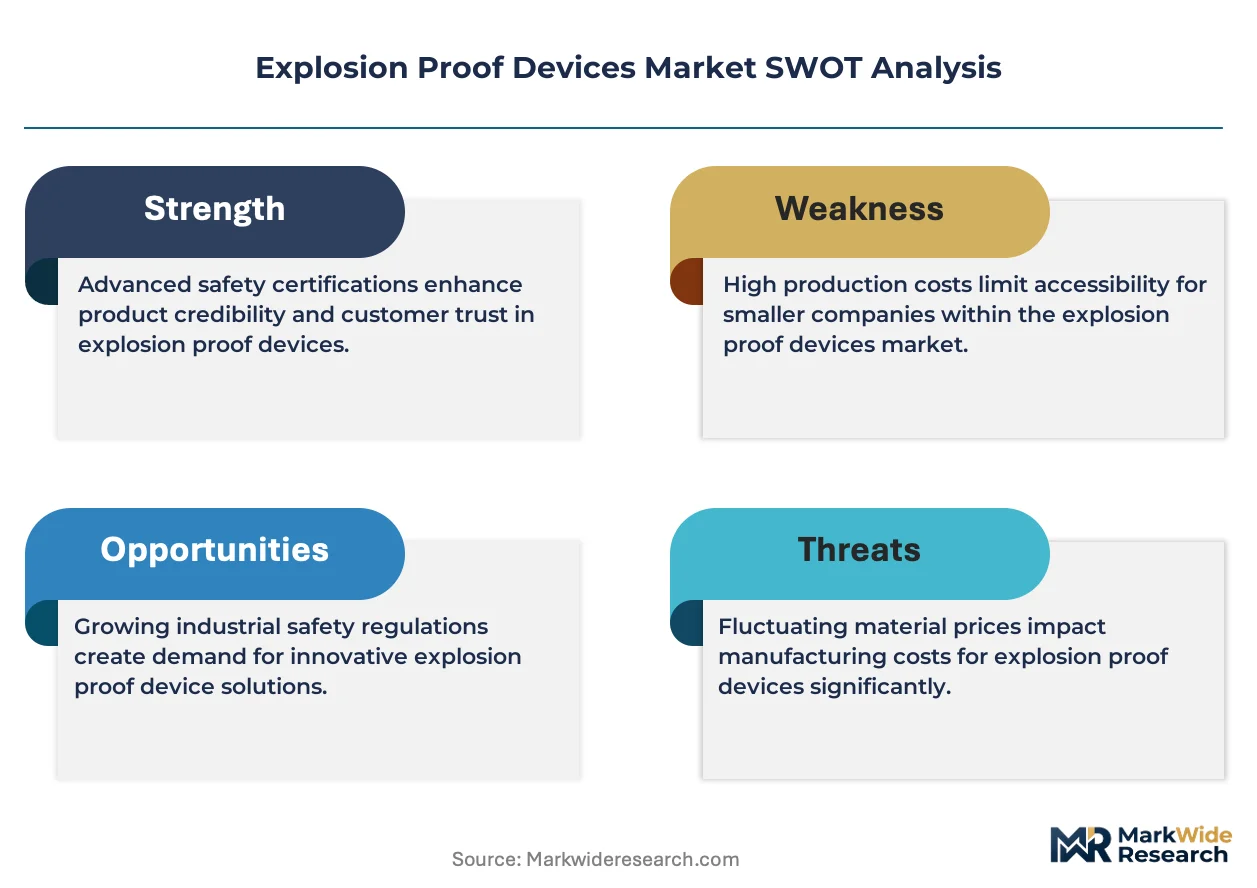
Wireless instrumentation is compressing replacement cycles for wired flameproof infrastructure across petrochemical clusters, forcing incumbent suppliers to re-engineer certification pathways for battery-powered sensors.
Growth Catalysts
- IECEx scheme expansion:Australian-administered mutual recognition agreements are accelerating market access for certified manufacturers into Southeast Asian refining corridors without redundant testing.
- Predictive maintenance digitization:Upstream oil operators are deploying hazardous-area cameras and vibration sensors to reduce unplanned shutdown frequency in offshore platforms.
- China's petrochemical buildout:Ningbo and Dalian cluster expansions are driving replacement demand for legacy flameproof lighting and junction boxes.
Market Restraints
- Copper and aluminum price volatility:Enclosure fabrication costs swing with London Metal Exchange commodity indices, squeezing margin predictability for mid-tier fabricators.
- Dual-certification capital intensity:Simultaneous ATEX and IECEx qualification requires redundant testing at separate notified bodies, elevating engineering overhead for new entrants.
- Intrinsically safe alternatives:Low-power electronics are encroaching on flameproof enclosure applications in Zone 2 environments where ignition probability permits reduced protection levels.
Strategic Opportunities
- India's refinery modernization:Reliance Industries and Indian Oil Corporation are retrofitting aging Gujarat and Maharashtra facilities with IECEx-certified automation.
- Wireless retrofit channel:System integrators are bundling battery-powered sensors with cloud analytics to bypass expensive conduit installation in brownfield chemical plants.
- EU Green Deal alignment:REACH-compliant material substitutions for traditional gasket compounds open premium positioning for certified sustainable enclosure designs.
Industry Challenges
- IECEx competency scarcity:Qualified hazardous area engineers capable of interpreting gas group and temperature class specifications remain concentrated in Germany and the United States.
- Legacy system integration friction:Digital sensor deployments must interface with 4-20mA analog control loops prevalent in 1990s-era petrochemical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Proof Devices Market |
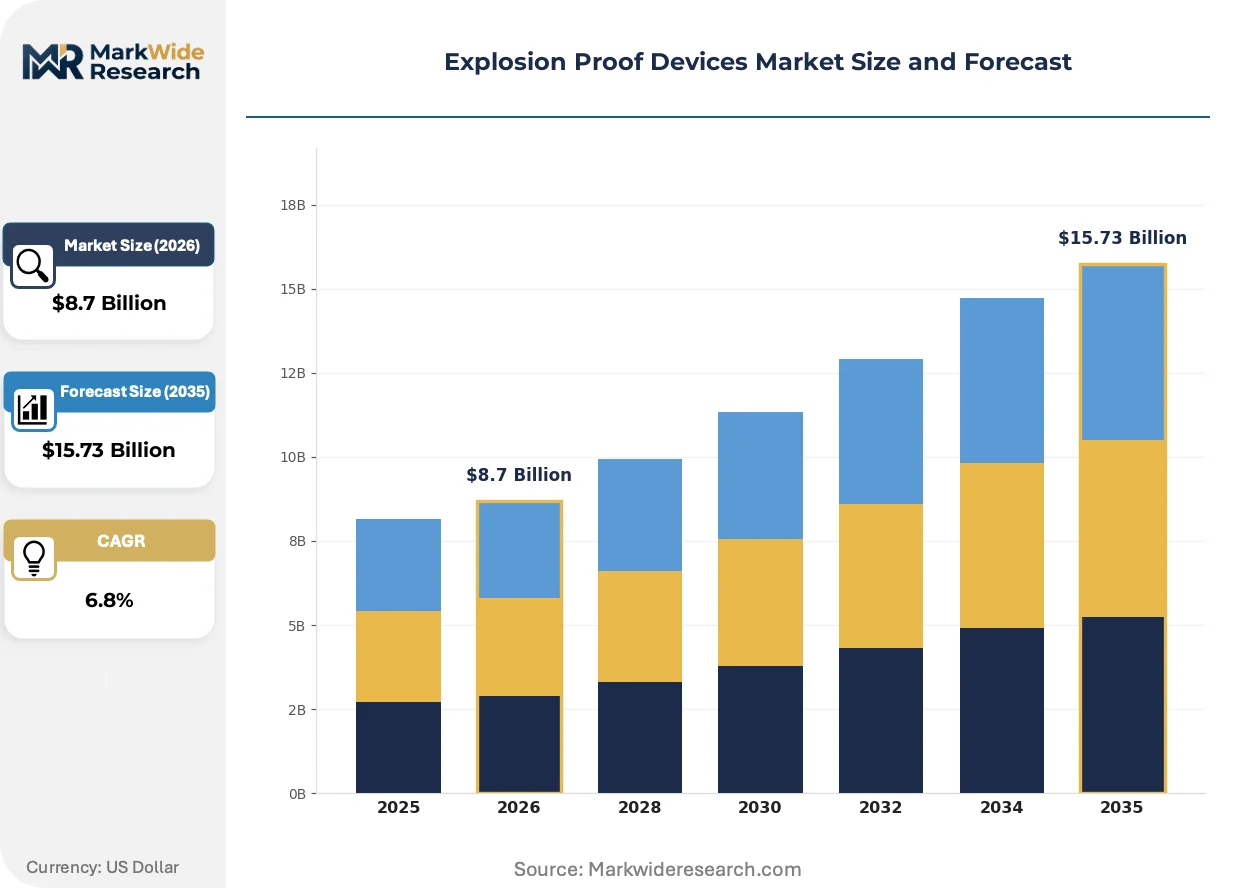
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Sensors, Cameras, Lighting Application: Oil & Gas, Chemical Processing, Pharmaceuticals, Mining End User: Industrial, Commercial, Construction, Marine Technology: Wired, Wireless, Intrinsic Safety, Non-Incendive |
| Companies Covered | Siemens, Honeywell International, ABB, Rockwell Automation, Eaton Corporation, Emerson Electric, Schneider Electric, R. STAHL, Pepperl+Fuchs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Proof Devices Market Evolving Landscape
Digital thread technologies are threading hazardous area instrumentation into enterprise asset management platforms, collapsing the historical separation between field devices and central control systems.
Intrinsically safe wireless sensor networks are unifying power-limited circuit design with mesh radio protocols to eliminate conduit runs in congested process skids. Offshore platform operators in the North Sea are deploying these systems to reduce installation labor by half. The technology is unifying previously siloed safety and process control budgets under single capital approvals.
OSHA's updated enforcement posture on combustible dust hazards is compelling grain handling and pharmaceutical facilities to upgrade from general-purpose to dust-ignition-proof enclosures. Inspectors are citing NFPA 652 compliance gaps with greater frequency. Food processing plants in the Midwest United States are accelerating replacement timelines for legacy motor control centers.
Specification authority is migrating from plant engineering departments to centralized procurement functions with standardized vendor lists. EPC contractors are losing influence over device selection as owner-operators consolidate supplier relationships. This concentration is most visible in German chemical conglomerates where framework agreements now cover multi-site instrumentation purchases.
Explosion Proof Devices Market Segmentation
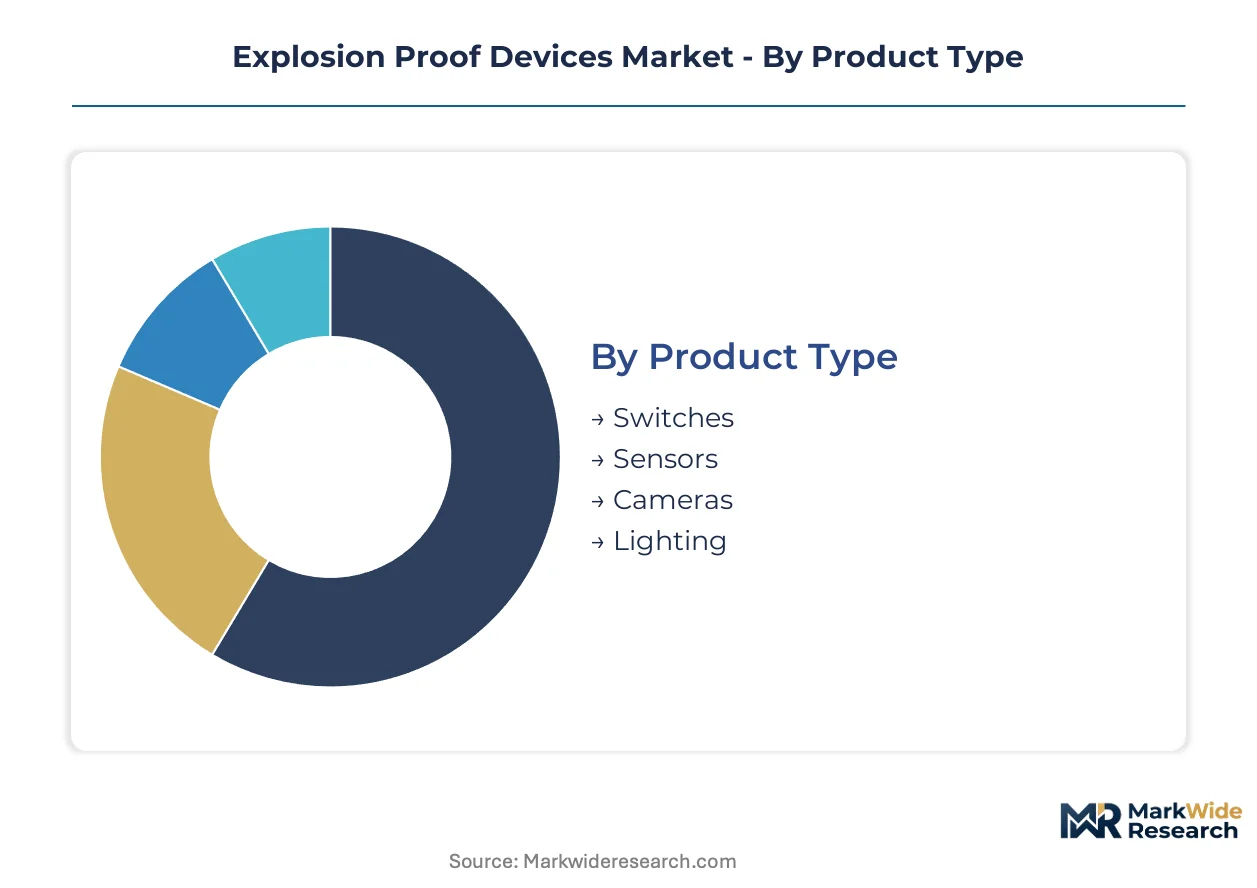
Explosion proof device procurement diverges sharply across product categories, with certification grade and connectivity architecture driving fundamentally different sourcing economics. Buyers in hazardous industries weight replacement cycles against integration complexity when allocating capital across these segment boundaries.
Product Type:
Certification tier and installation density determine how buyers prioritize capital allocation across hardware categories.
- Sensors:Vibration, temperature, and gas detection units engineered for Zone 1 and Zone 2 deployment with IECEx-certified housings. Demand concentrates in offshore platforms operated by Equinor and BP in the North Sea, where predictive maintenance programs digitize asset monitoring to reduce unplanned shutdown frequency.
- Cameras:Fixed and pan-tilt-zoom units with flameproof enclosures rated for gas groups IIB and IIC. Refinery operators in the US Gulf Coast are deploying these for remote visual inspection of distillation columns, bypassing confined entry permits and reducing personnel exposure.
- Switches:Pushbutton, selector, and limit switch assemblies with explosion-proof contact blocks. Chemical plants in Germany specify these for motor control stations in solvent handling areas.
- Lighting:LED and fluorescent luminaires with flameproof or increased safety protection. Legacy petrochemical installations in China drive replacement demand as Ningbo and Dalian clusters upgrade aging high-pressure sodium fixtures.
Volume sits with Lighting; growth tilts toward Cameras.
Application:
Hazard severity and regulatory inspection frequency shape procurement patterns across industrial verticals.
- Oil & Gas:Upstream drilling platforms, midstream pipelines, and downstream refining units requiring ATEX and IECEx dual certification. US Gulf Coast operators face intensified OSHA enforcement on combustible dust in coker units, accelerating enclosure replacement timelines.
- Chemical Processing:Continuous process plants handling flammable solvents and reactive intermediates. German chemical conglomerates consolidate instrumentation purchases under framework agreements spanning multiple Ludwigshafen and Leverkusen sites.
- Pharmaceuticals:Solvent recovery and hydrogenation suites with stringent containment requirements. FDA inspection protocols for active pharmaceutical ingredient facilities elevate documentation burdens for device qualification.
- Mining:Underground coal and metal ore operations with methane and combustible dust hazards. Australia's Queensland coal seams drive demand for dust-ignition-proof switchgear.
Revenue concentrates in Oil & Gas; Chemical Processing shows the steepest expansion trajectory as capacity buildouts accelerate in India and China.
End User:
Capital intensity and in-house engineering capability separate procurement behaviors across buyer categories.
- Industrial:Petrochemical, refining, and bulk chemical manufacturers with dedicated hazardous area engineering teams. Owner-operators in Saudi Arabia's Jubail Industrial City specify IECEx-certified automation for integrated control system upgrades.
- Commercial:Fuel storage terminals, paint manufacturing, and coating operations with outsourced maintenance. US Midwest grain elevators face NFPA 652 compliance deadlines for dust-ignition-proof motor control centers.
- Construction:Temporary power distribution and lighting for tank cleaning and turnaround projects. Rental fleet operators in the US Gulf Coast stock explosion-proof panels for refinery maintenance campaigns.
- Marine:Offshore supply vessels, tankers, and LNG carriers with Class Society certification requirements. Singapore shipyards specify compact flameproof junction boxes for engine room instrumentation.
Industrial buyers command volume; Commercial segment procurement is accelerating as OSHA enforcement tightens on smaller facilities.
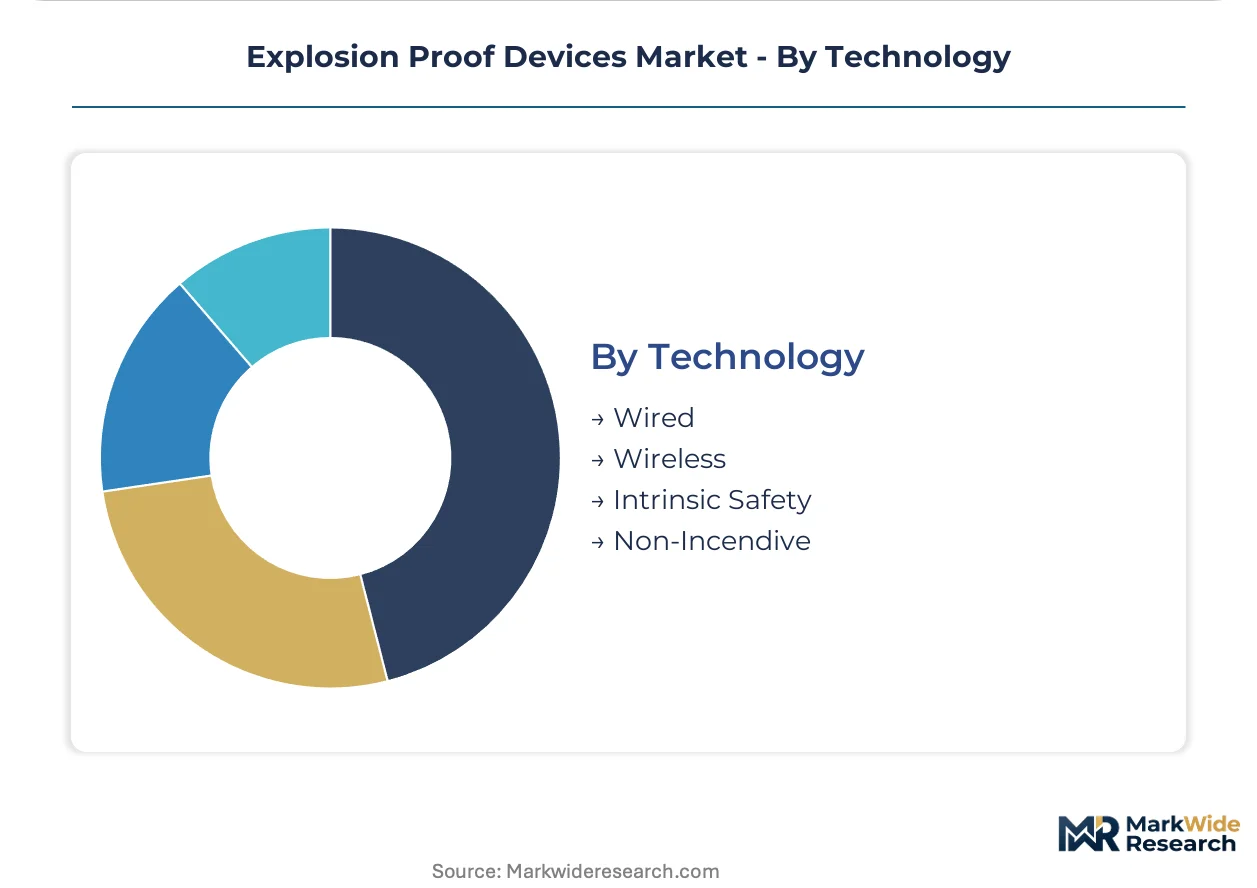
Technology:
Power architecture and certification pathway determine integration cost and deployment flexibility.
- Wireless:Battery-powered sensors with mesh radio protocols eliminating conduit runs. North Sea platform operators deploy these to reduce installation labor by half in congested process skids.
- Intrinsic Safety:Power-limited circuits with energy storage restrictions preventing ignition capable energy release. Pharmaceutical cleanrooms in Switzerland favor these for hydrogenation suite instrumentation.
- Wired:Traditional conduit and cable gland installations with flameproof or increased safety protection. Legacy 4-20mA analog loops in 1990s-era plants constrain digital migration timelines.
- Non-Incendive:Normal operation spark prevention without containment requirements, restricted to Zone 2 applications. Chemical warehouses in the Netherlands specify these for solvent storage monitoring where ignition probability permits reduced protection levels.
Wired infrastructure retains installed base dominance; Wireless is gaining share fastest as brownfield retrofit economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo anchors the largest concentration of petrochemical cluster expansion driving flameproof device procurement, with Dalian and Shanghai forming secondary demand nodes in China's eastern coastal corridor.
United States
OSHA enforcement on combustible dust hazards in Gulf Coast refineries accelerates enclosure replacement timelines. The Department of Labor cites NFPA 652 compliance gaps with greater frequency during inspections. Houston and Corpus Christi petrochemical complexes drive demand for Zone 1 certified switchgear as coker unit upgrades proceed.
Germany
Ludwigshafen and Leverkusen chemical conglomerates consolidate instrumentation purchases under multi-site framework agreements. ECHA REACH compliance requirements elevate material qualification burdens for gasket compound substitutions. BASF and Bayer facility clusters prioritize IECEx-certified automation for integrated control system upgrades.
China
Ningbo and Dalian petrochemical buildouts drive replacement demand for legacy flameproof lighting and junction boxes. MIIT industrial safety directives tighten certification requirements for hazardous area electrical equipment. Sinopec and PetroChina facility expansions in the Yangtze River Delta concentrate procurement authority under centralized procurement functions.
India
Reliance Industries and Indian Oil Corporation retrofit aging Gujarat and Maharashtra facilities with IECEx-certified automation systems. BIS alignment with international standards accelerates market access for foreign-certified manufacturers. Jamnagar and Vadodara refinery modernization programs bundle wireless sensor deployments with cloud analytics platforms.
Saudi Arabia
Jubail Industrial City owner-operators specify IECEx-certified automation for integrated control system upgrades across petrochemical complexes. The Saudi Standards, Metrology and Quality Organization enforces conformity assessment requirements for hazardous area equipment imports. SABIC affiliate facilities drive demand for flameproof terminal boxes in congested process skids.
Explosion Proof Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and integration depth, with dual-certified portfolios commanding pricing power in oil and gas procurement. The vendor base stratifies into three tiers: diversified industrial conglomerates with full automation portfolios, electrical specialists with deep hazardous area expertise, and regional fabricators competing on installation footprint. Two dominant competitive moves define positioning: strategic partnerships between automation vendors and system integrators for wireless retrofit bundling, and portfolio diversification into predictive maintenance software to capture recurring revenue streams.
Among diversified industrial conglomerates, Siemens and ABB occupy positions exemplifying the premium-tier archetype through integrated automation portfolios. Honeywell International anchors the North American demand vector with hazardous area instrumentation expertise. R. STAHL represents the specialist tier, with German engineering heritage concentrated in compact flameproof enclosure design for chemical plant congestion constraints.
| Leading Market Players |
|---|
| Siemens |
| Honeywell International |
| ABB |
| Rockwell Automation |
| Eaton Corporation |
| Emerson Electric |
| Schneider Electric |
| R. STAHL |
| Pepperl+Fuchs |
| Others |
Value Network & Pricing Analysis
Dual-certification premium tiers separate IECEx-ATEX qualified hardware from single-standard commodity enclosures, concentrating pricing power with German and US engineering houses while Chinese fabricators compete on installation footprint and copper sourcing efficiency. This bifurcation feeds directly into supply chain configurations: premium vendors maintain captive testing relationships with notified bodies in Frankfurt and Sydney, whereas cost-optimized players source aluminum castings from Yangtze River Delta foundries and gasket compounds from domestic chemical suppliers.
Pricing Analysis
Uptime guarantees and unplanned shutdown avoidance anchor value-based pricing for Zone 1 automation systems, with Siemens and ABB bundling predictive maintenance software to capture recurring revenue streams. Three-tier pricing structure across premium dual-certified, standard single-certified, and economy-grade regional hardware reflects certification depth and after-sales engineering support. Cost compression in the mid-tier is intensifying because Indian and Southeast Asian fabricators are achieving IECEx equivalence at lower engineering overhead. Commercial grain elevators and paint manufacturers exhibit highest price sensitivity, while offshore platform operators prioritize certification pedigree over unit economics.
Supply Chain Analysis
Freight cost volatility from Hamburg and Rotterdam to Singapore and Houston is compressing margins for enclosure fabricators dependent on European aluminum billet and Chinese LED component imports. Manufacturing concentrates in Germany for precision flameproof castings, China for high-volume junction box fabrication, and the United States for integrated power distribution assemblies. Supply chains draw from London Metal Exchange-indexed copper and aluminum, specialized elastomer gasket compounds, and IECEx-certified cable glands. Single-source vulnerability sits with Australian-administered testing laboratory capacity for dual-certification programs. Distribution runs through EPC contractors and system integrators serving petrochemical clusters, with direct procurement consolidation bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Explosion proof device supply is constrained by qualified hazardous area engineer scarcity concentrated in Germany and the United States, propping premium-tier pricing as owner-operators compete for certified integration capacity.
For Market Incumbents: To counter wireless sensor entrants compressing replacement cycles for wired infrastructure, Siemens and ABB should deepen backward integration into battery-powered sensor certification pathways and lock EPC contractors into exclusive framework agreements spanning multi-site instrumentation purchases. Captive control over IECEx testing relationships in Frankfurt and Sydney preserves margin structure against emerging Asian competitors. For New Entrants and Emerging Players: Mid-sized US grain elevators facing NFPA 652 compliance deadlines represent an underserved buyer archetype with fragmented procurement and limited in-house hazardous area expertise. Wireless retrofit bundling with cloud analytics platforms offers a penetrable entry vector, bypassing the certification capital intensity required for offshore platform Tier 1 supplier status. Direct sales bypassing traditional EPC channels captures margin otherwise lost to systems integrator markups. For Investors and Strategic Acquirers: Re-rating potential sits with compact flameproof enclosure specialists given EU Green Deal alignment for REACH-compliant material substitutions and predictive maintenance software attach rates. Long-term viability over the investment horizon favors targets with dual-certified portfolios and recurring revenue streams from hazardous area monitoring platforms. The signal to watch is OSHA enforcement intensity on combustible dust in Midwest food processing and grain handling facilities as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| IECEx Certification Expansion | Australian mutual recognition agreements accelerate Southeast Asian refinery market access without redundant testing. |
| Wireless Retrofit Channel Development | Battery-powered sensor bundling with cloud analytics bypasses expensive conduit installation in brownfield plants. |
| REACH-Compliant Material Transition | Sustainable gasket compound substitutions open premium positioning for EU Green Deal-aligned enclosure designs. |
| Predictive Maintenance Software Integration | Digital thread technologies collapse separation between field devices and enterprise asset management platforms. |
| Multi-Site Framework Agreement Consolidation | German chemical conglomerates concentrate procurement authority under standardized vendor lists spanning Ludwigshafen and Leverkusen. |
Research Methodology
Multi-period observation of IECEx certification issuance rates, hazardous area instrumentation procurement cycles, and copper price volatility anchored the trend analysis, supplemented by interviews with plant engineering directors at North Sea offshore platforms, procurement leads at German chemical conglomerates, EPC contractors specializing in refinery turnarounds, and hazardous area compliance officers at notified bodies. Secondary validation drew from OSHA enforcement databases, MIIT industrial safety directives, BIS standard alignment notifications, SEC 10-K filings from diversified industrial conglomerates, and customs records for flameproof enclosure imports. Bottom-up segment sizing triangulated against top-down petrochemical capital expenditure tracking.
Input-output matrices modeled demand across product type, protection technology, application vertical, and regional regulatory cluster throughout the forecast period. CAGRs were derived from segment-level growth rate blending weighted by revenue concentration. Industry-specific forecast inputs included wireless sensor adoption curves in brownfield retrofit applications and replacement cycle compression from predictive maintenance digitization programs.
Revisions become necessary when OSHA enforcement posture shifts on combustible dust, when copper and aluminum price volatility exceeds historical bands, or when IECEx scheme expansion accelerates beyond current mutual recognition agreement trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market