
 Scuba Gloves Market | 2026-2036
Scuba Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Scuba Gloves Market Analytics
The EU Green Deal is recalibrating material sourcing across the scuba gloves supply chain by restricting petrochemical-based neoprene feedstocks. Cressi leverages its vertically integrated manufacturing in Italy to control neoprene alternative development. Henderson Aquatics anchors North American distribution through specialty dive shop networks. Scubapro differentiates via thermal insulation technology leadership in cold-water expedition segments.
Scuba gloves are protective hand coverings manufactured from neoprene, latex, rubber, or synthetic fiber in thicknesses ranging from 1mm to 5mm, designed to maintain dexterity while preventing thermal loss, abrasion, and marine punctures during submersion. Neoprene formulations dominate commercial volume due to established supply chains, though synthetic fiber blends represent the fastest-growing material category as plant-based elastomers mature. Professional divers command premium pricing for cut-resistant 5mm configurations, while recreational scuba generates the largest unit volume across 2mm and 3mm thermal insulation SKUs.
FDA oversees latex allergen labeling for US-bound products, while REACH regulates chemical composition across European imports. The EU F-Gas Regulation indirectly shapes neoprene manufacturing by restricting blowing agents used in foam production. Thailand's central environmental regulator enforces marine equipment standards for coastal commercial operators. Stakeholders must monitor evolving chemical compliance thresholds as bio-based material certifications fragment across jurisdictions.
Market Dynamics
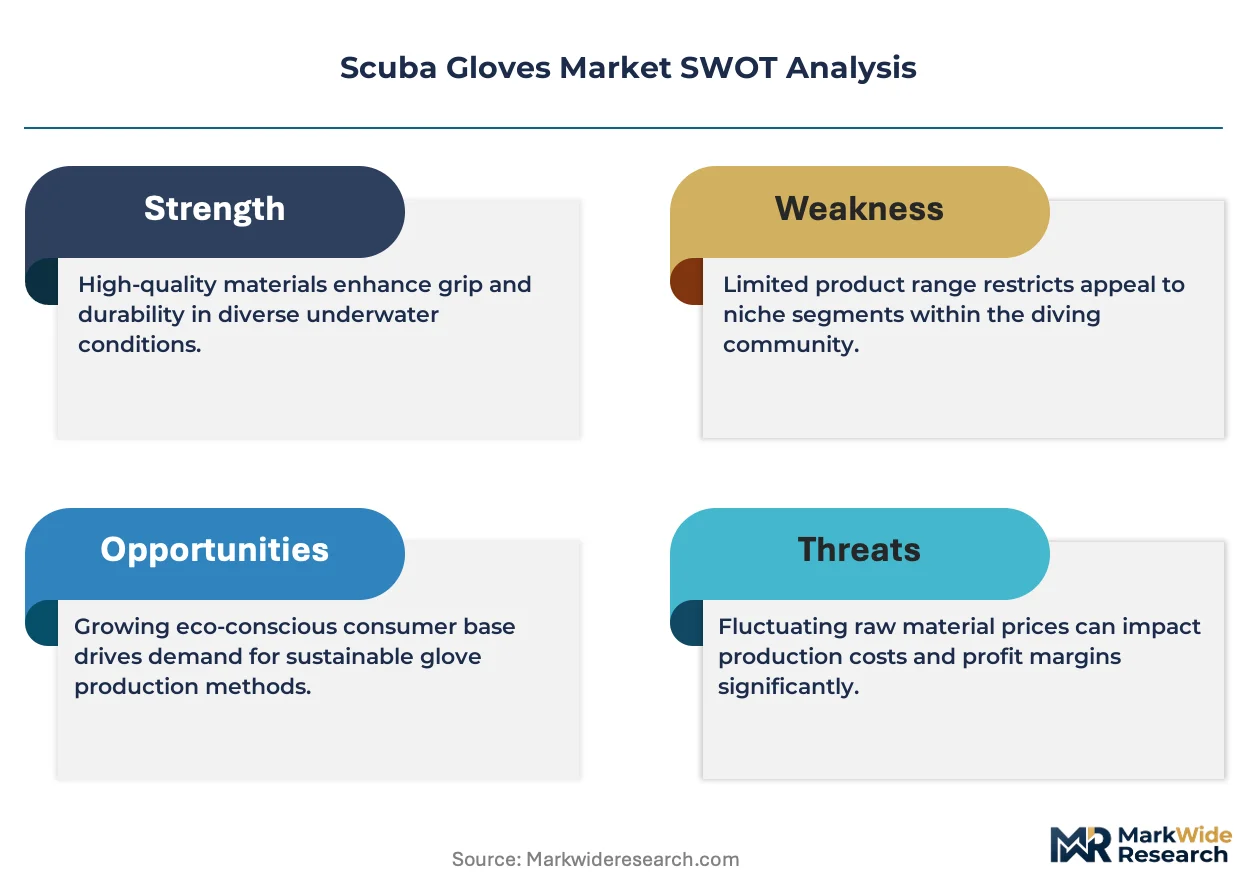
The EU Green Deal's chemical restrictions on neoprene production are forcing manufacturers to reconfigure material sourcing and production processes across the scuba gloves supply chain.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on blowing agents in foam production are accelerating adoption of plant-based elastomer alternatives in neoprene manufacturing.
- Southeast Asian dive tourism:Liveaboard operations and certification schools in Thailand's coastal provinces are generating concentrated glove demand from recreational divers.
- Synthetic fiber blends:Plant-based and recycled synthetic alternatives represent the fastest-growing material category as bio-based elastomers mature technically.
Market Restraints
- Petrochemical feedstock volatility:Neoprene production remains tethered to oil-derived chloroprene monomer pricing, creating margin pressure for manufacturers.
- REACH compliance costs:European chemical composition regulations impose testing and documentation burdens that disadvantage smaller producers.
- Natural rubber substitution threat:Latex gloves compete on price for warm-water recreational segments where thermal protection demands are minimal.
Strategic Opportunities
- Cold-water expedition segments:Premium 5mm cut-resistant configurations command pricing power from professional divers in Arctic and Antarctic waters.
- Bio-based material certifications:Fragmenting jurisdictional standards create first-mover advantage for manufacturers achieving multi-territory compliance.
- Specialty dive shop networks:Direct distribution partnerships bypass commoditized mass retail channels and build brand loyalty among serious divers.
Industry Challenges
- Multi-jurisdictional certification timelines:FDA latex allergen labeling, REACH chemical thresholds, and Thailand's marine equipment standards require parallel compliance tracks.
- Legacy neoprene supply chain reconfiguration:Decades of petrochemical-based supplier relationships must unwind as bio-alternative feedstocks scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scuba Gloves Market |
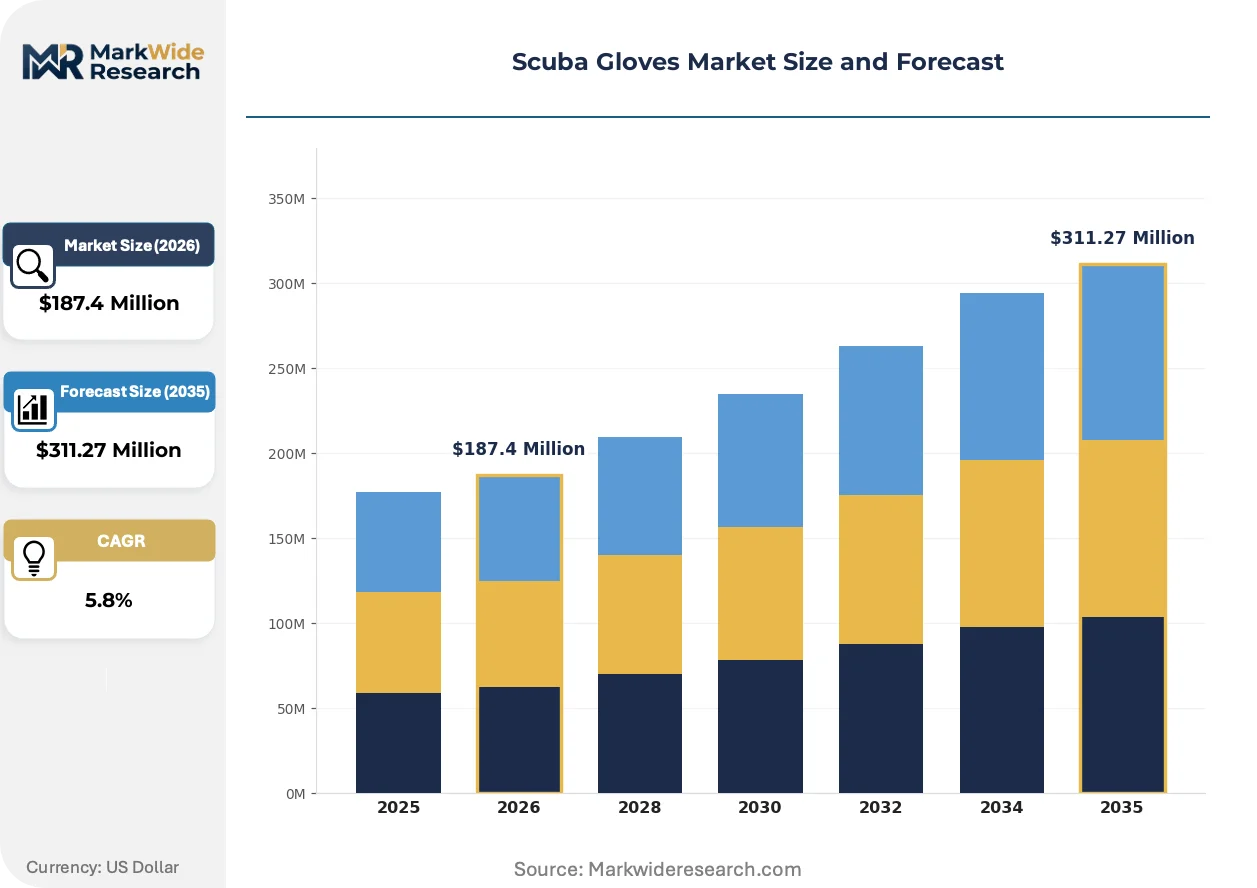
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Neoprene, Latex, Rubber, Synthetic Fiber Thickness: 1mm, 2mm, 3mm, 5mm End User: Professional Divers, Recreational Scuba, Snorkelers, Underwater Photographers Feature: Thermal Insulation, Cut Resistance, Grip, Flexibility |
| Companies Covered | Aqua Lung International, Scubapro, Cressi, Mares, Beuchat International, Baresports Company, Henderson Aquatics, Waterproof USA, AKONA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scuba Gloves Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape competitive positioning in thermal protection equipment for subaquatic activities.
Plant-based elastomer formulations are expanding into commercial neoprene replacement applications. These bio-derived polymers maintain thermal insulation properties while eliminating petrochemical dependency. Cold-water expedition operators and environmentally certified dive centers are adopting these alternatives at accelerating rates. This technology is expanding into premium product tiers previously reserved for petroleum-based neoprene.
REACH chemical composition standards are tightening allowable substance thresholds across European imports. ECHA enforcement actions are compelling manufacturers to reformulate adhesives, dyes, and foam additives. Professional-grade 5mm configurations face the steepest reformulation costs due to multi-layer construction complexity.
Certification-driven procurement preferences are displacing price-first purchasing among dive schools and liveaboard operators. PADI and SSI affiliated centers now specify thermal protection compliance in vendor selection criteria. Thailand's coastal provinces exhibit this shift most visibly, where environmental accreditation affects tourism licensing.
Scuba Gloves Market Segmentation
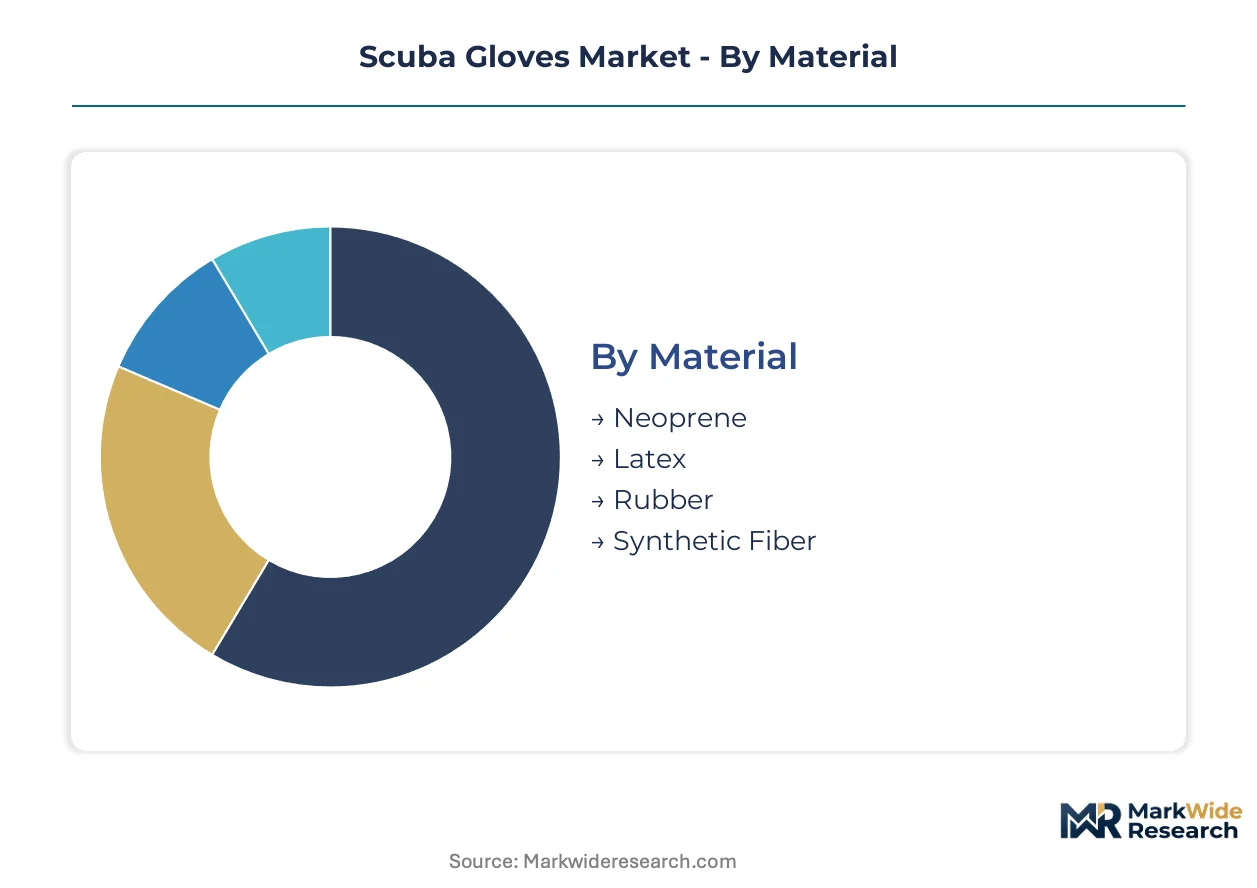
Material thickness and thermal performance specifications determine pricing architecture across scuba glove procurement channels. Certification requirements and dive environment conditions create distinct demand clusters that manufacturers must address through targeted SKU development.
Material:
Neoprene formulations anchor commercial volume through established petrochemical supply chains, though bio-based alternatives are gaining technical validation.
- Neoprene:Chloroprene-based foam dominates manufacturing scale due to proven thermal insulation performance and supplier network maturity. Thailand's liveaboard operators and certification schools in Phuket and Krabi provinces source neoprene gloves in bulk volumes for rental inventory replacement cycles.
- Synthetic Fiber:Plant-based elastomer blends eliminate petrochemical dependency while maintaining dexterity specifications for warm-water recreational use. Southeast Asian dive tourism operators seeking environmental accreditation are adopting these alternatives at accelerating procurement rates.
- Latex:Natural rubber compounds compete on unit cost for tropical recreational segments where thermal demands remain minimal.
- Rubber:Solid rubber formulations serve puncture-critical applications in commercial and military diving operations.
Mature deployment sits with Neoprene. Newer deployment is concentrated in Synthetic Fiber.
Thickness:
Millimeter ratings directly correlate with water temperature exposure limits and professional certification tier requirements.
- 3mm:The recreational standard balances thermal protection with manual dexterity for temperate water diving. Certification schools in Thailand's coastal provinces specify 3mm configurations as baseline equipment for Open Water training programs.
- 5mm:Cold-water expedition operators in Arctic and Antarctic waters demand these configurations for professional ice diving and technical wreck penetration. Cut-resistant layering adds structural complexity that commands premium procurement pricing from commercial diving contractors.
- 2mm:Tropical warm-water recreational diving minimizes insulation requirements while maximizing tactile feedback for photography and marine life interaction.
- 1mm:Minimal protection suits snorkelers and surface swimmers in high-ambient-temperature environments where thermal loss is negligible.
Volume concentration favors 3mm. Margin expansion is steepest in 5mm.
End User:
Professional certification standards and liability exposure create divergent procurement specifications across user categories.
- Recreational Scuba:The largest unit volume segment driven by PADI and SSI certification pipelines. Thailand's coastal provinces generate concentrated demand through liveaboard operations and dive resort equipment rental programs.
- Professional Divers:Commercial contractors, military units, and scientific research teams specify cut-resistant 5mm configurations with documented compliance to occupational safety standards.
- Snorkelers:Surface-oriented users prioritize UV protection and abrasion resistance over thermal insulation in shallow tropical waters.
- Underwater Photographers:Dexterity-critical applications demand thin-gauge materials that preserve camera control sensitivity during extended bottom times.
Procurement standardization is highest among Professional Divers. Brand switching is most frequent in Recreational Scuba.
Feature:
Functional prioritization varies by dive environment hazard profile and equipment integration requirements.
- Thermal Insulation:Core performance metric across all water temperatures, with thickness-to-warmth ratios determining competitive positioning in cold-water expedition segments.
- Cut Resistance:Kevlar and Dyneema reinforcement layers protect against coral abrasion, wreck metal edges, and fishing line entanglement in technical diving applications.
- Grip:Textured palm surfaces enhance tool and equipment handling security for commercial divers operating hydraulic systems and lift bags.
- Flexibility:Material engineering targets joint articulation preservation for photographers and videographers requiring precise manual control.
Specification maturity centers on Thermal Insulation. Technical differentiation is accelerating in Cut Resistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phuket anchors the recreational diving equipment trade, with liveaboard operators and certification schools clustering along Thailand's Andaman coast. This concentration pattern repeats across four additional countries where dive tourism infrastructure and regulatory frameworks shape distinct procurement environments.
United States
Florida's dive charter fleet and California's technical diving community sustain steady glove replacement cycles. FDA latex allergen labeling requirements shape import documentation for Asian-manufactured products. Henderson Aquatics maintains distribution partnerships with specialty retailers concentrated in San Diego and Fort Lauderdale.
Germany
The Baltic Sea wreck diving circuit and North Sea commercial operations generate demand for cold-water rated configurations. REACH chemical composition thresholds and the EU F-Gas Regulation restrict blowing agents in neoprene foam production. Manufacturers in Baden-Württemberg reformulate adhesives to maintain European market access.
Italy
Genoa and Livorno harbor dive equipment fabrication clusters serving Mediterranean recreational markets. The EU Green Deal's petrochemical feedstock restrictions accelerate plant-based elastomer testing at Cressi's vertically integrated Genoa facility. Certification schools in Sardinia and Sicily specify thermal protection compliance in rental equipment procurement.
Japan
Okinawa's subtropical reefs and the Izu Peninsula's temperate waters create dual demand profiles for thin-gauge and 3mm configurations. METI industrial standards and JIS certification requirements govern commercial diving contractor specifications. Tokyo-based distributors coordinate bulk purchasing for domestic liveaboard operators.
Australia
The Great Barrier Reef tourism corridor and Tasmanian cold-water sites generate segmented demand across thickness categories. TGA medical device oversight applies to latex-containing products for professional applications. Cairns and Port Douglas equipment suppliers stock seasonal inventory for international dive tourism peaks.
Scuba Gloves Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists controlling neoprene alternative development. Mid-scale manufacturers compete on REACH compliance documentation and multi-territory certification speed. Three archetypes dominate: Italian integrated fabricators, North American distribution specialists, and Asian volume producers. Capacity expansion and bio-based material partnerships constitute the primary competitive moves as petrochemical feedstock restrictions tighten.
Among heritage European manufacturers, Cressi and Scubapro occupy positions anchored by decades of thermal protection engineering, while Henderson Aquatics represents the North American distribution-focused archetype. These companies exemplify divergent responses to EU chemical restrictions—Cressi through captive neoprene alternative development, Scubapro via cold-water technical specialization, and Henderson Aquatics through specialty retail channel control.
| Leading Market Players |
|---|
| Aqua Lung International |
| Scubapro |
| Cressi |
| Mares |
| Beuchat International |
| Baresports Company |
| Henderson Aquatics |
| Waterproof USA |
| AKONA |
| Others |
Value Network & Pricing Analysis
Captive neoprene alternative development at vertically integrated Italian facilities anchors supply position and pricing power for heritage manufacturers responding to EU Green Deal chemical restrictions. This integration choice insulates premium-tier producers from petrochemical feedstock volatility while forcing mid-scale competitors to absorb REACH compliance documentation costs that erode margin.
Pricing Analysis
Value-based pricing anchors on thermal protection outcomes measured by water temperature exposure limits and certification compliance. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade 5mm cut-resistant configurations from recreational 3mm rental inventory and thin-gauge tropical alternatives. Cost compression in standard-tier neoprene SKUs intensifies because latex substitution threatens warm-water recreational segments. Certification schools and liveaboard operators exhibit lowest price sensitivity; mass retail channels face highest.
Supply Chain Analysis
Single-source vulnerability sits with chloroprene monomer feedstocks concentrated in China, Japan, and the United States. Plant-based elastomer development draws from agricultural supply chains in Southeast Asia and European biopolymer refineries. Tariff exposure on Asian-manufactured finished goods entering US and European markets compounds risk for non-integrated brands. Distribution runs through specialty dive shop networks in San Diego, Fort Lauderdale, and Phuket rather than commoditized mass retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a materials-transition phase as plant-based elastomer formulations displace petroleum-derived neoprene in thermal protection equipment. Bio-based polymer maturity is replacing legacy petrochemical dependency across certification-driven procurement channels.
For Market Incumbents: Anticipate REACH threshold tightening by accelerating multi-territory certification documentation before ECHA enforcement actions escalate reformulation costs. Prioritize captive supply of neoprene alternatives through backward integration into Italian or Southeast Asian biopolymer partnerships. Defend against synthetic fiber blend entrants by locking exclusive distribution with PADI and SSI affiliated certification schools in Thailand's coastal provinces.
For New Entrants and Emerging Players: Specialty dive shop networks represent the most penetrable channel archetype for bypassing entrenched retail relationships. Target warm-water recreational segments in Southeast Asian dive tourism corridors where environmental accreditation requirements favor bio-based material alternatives. Pursue white-label manufacturing partnerships with Thai liveaboard operators seeking rental inventory replacement cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to heritage European equipment manufacturers seeking bio-based material capabilities. Long-term viability favors vertically integrated specialists with captive neoprene alternative development and multi-jurisdictional certification speed. Watch plant-based elastomer cost parity with petroleum-derived neoprene as the inflection signal for accelerated market share displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polymer Supply | Captive plant-based elastomer production insulates margins from EU F-Gas Regulation compliance costs. |
| Multi-Territory Certification Investment | Parallel FDA, REACH, and Thailand marine equipment tracks accelerate market access velocity. |
| Specialty Dive Shop Network Expansion | Direct distribution partnerships in San Diego and Phuket build brand loyalty among serious divers. |
| Cold-Water Technical Specialization | 5mm cut-resistant configurations for Arctic expedition operators command premium pricing power. |
| Sustainability Repositioning | Environmental accreditation alignment captures procurement preference shifts at Thailand certification schools. |
Research Methodology
Trade databases, customs records, and equipment manufacturer SEC filings formed the secondary backbone for volume and value estimation. Primary interviews with dive equipment procurement managers at Thailand liveaboard operators, specialty retail buyers in San Diego and Fort Lauderdale, and regulatory affairs leads at Italian manufacturers combined with secondary validation. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate trade flow data.
Bottom-up modeling built demand from certification school enrollment rates, liveaboard fleet capacity, and rental inventory replacement cycles across the projection horizon. Segmentation dimensions included material thickness, thermal performance tier, end-user category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates. Industry-specific inputs incorporated PADI and SSI certification pipeline data and EU F-Gas Regulation implementation timelines.
Caveats apply where REACH threshold revisions or bio-based material cost parity acceleration could materially shift the outlook. Forecasts reflect assumptions about dive tourism recovery trajectories and petrochemical feedstock price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market