
 Gloves Market | 2026-2036
Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Gloves Market Outlook
Healthcare end-user demand is hardening as hospitals and laboratories expand infection-control protocols. Ansell Limited leverages its dual medical-industrial portfolio to sustain cross-sector resilience. Hartalega Holdings Berhad anchors Malaysia's synthetic nitrile dominance through advanced thin-gauge manufacturing. Honeywell International Inc. competes in industrial safety channels with specialized chemical-resistant glove lines.
Gloves are hand-worn protective barriers manufactured from elastomeric films or woven substrates, typically ranging from 3 to 15 mil in thickness depending on chemical or biological hazard ratings. Their primary purpose is to prevent dermal exposure to pathogens, solvents, and mechanical abrasions across occupational and clinical environments. Disposable nitrile gloves lead volume pools due to latex-allergy mitigation and superior puncture resistance, while reusable industrial gloves in neoprene command premium margins for chemical-processing applications. Material-grade segmentation increasingly favors nitrile over latex as healthcare procurement shifts toward hypoallergenic synthetic alternatives.
FDA governs medical glove biocompatibility and quality-system compliance in the United States, while OSHA mandates hand-protection standards under 29 CFR 1910.138 for general industry. EU MDR and REACH collectively tighten material-safety documentation and clinical-performance claims for gloves distributed in Europe. Stakeholders must monitor evolving nitrile butadiene rubber supply dynamics and regulatory harmonization pressures as sustainability disclosures reshape supplier qualification criteria.
Market Dynamics
Malaysian production concentration for nitrile butadiene rubber gloves creates supply vulnerability as healthcare procurement hardens infection-control standards across hospital and laboratory networks.
Growth Catalysts
- FDA Biocompatibility Enforcement:United States medical device regulations mandate quality-system compliance for clinical glove imports, filtering substandard suppliers from hospital procurement pools.
- OSHA 29 CFR 1910.138:General industry hand-protection standards expand industrial glove deployment across chemical-handling and mechanical-risk occupations in manufacturing facilities.
- Nitrile Thin-Gauge Manufacturing:Advanced synthetic elastomer processing enables 3-mil medical-grade barrier films that match latex tactile sensitivity without allergen exposure risks.
Market Restraints
- Butadiene Monomer Volatility:Petrochemical feedstock price swings compress nitrile glove margins when crude oil benchmarks fluctuate above sustainable contract levels.
- Peninsular Malaysia Concentration:Over 60 percent of global nitrile capacity clusters within Klang Valley industrial zones, exposing buyers to single-country logistics and labor disruptions.
- Latex Protein Sensitivity:Natural rubber residual allergens prevent hospital reversion to lower-cost Hevea brasiliensis alternatives despite price advantages.
Strategic Opportunities
- EU MDR Transition:European Medical Device Regulation clinical-performance documentation requirements create certification barriers that favor established suppliers with notified-body relationships.
- Industrial Chemical-Processing:Neoprene and butyl reusable glove segments command premium positioning in petrochemical and semiconductor fabrication cleanroom applications.
- Direct Hospital Contracting:Bypassing distributor markups through group purchasing organization consolidation reduces landed costs for high-volume tertiary care networks.
Industry Challenges
- Notified-Body Queue Congestion:EU MDR technical documentation reviews stretch 12-18 months, delaying new product introductions for manufacturers without legacy CE certificates.
- Automation Capex Burden:Labor-cost pressures in Malaysian glove manufacturing require continuous dipping-line and packing-robot investments to maintain unit economics against emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gloves Market |
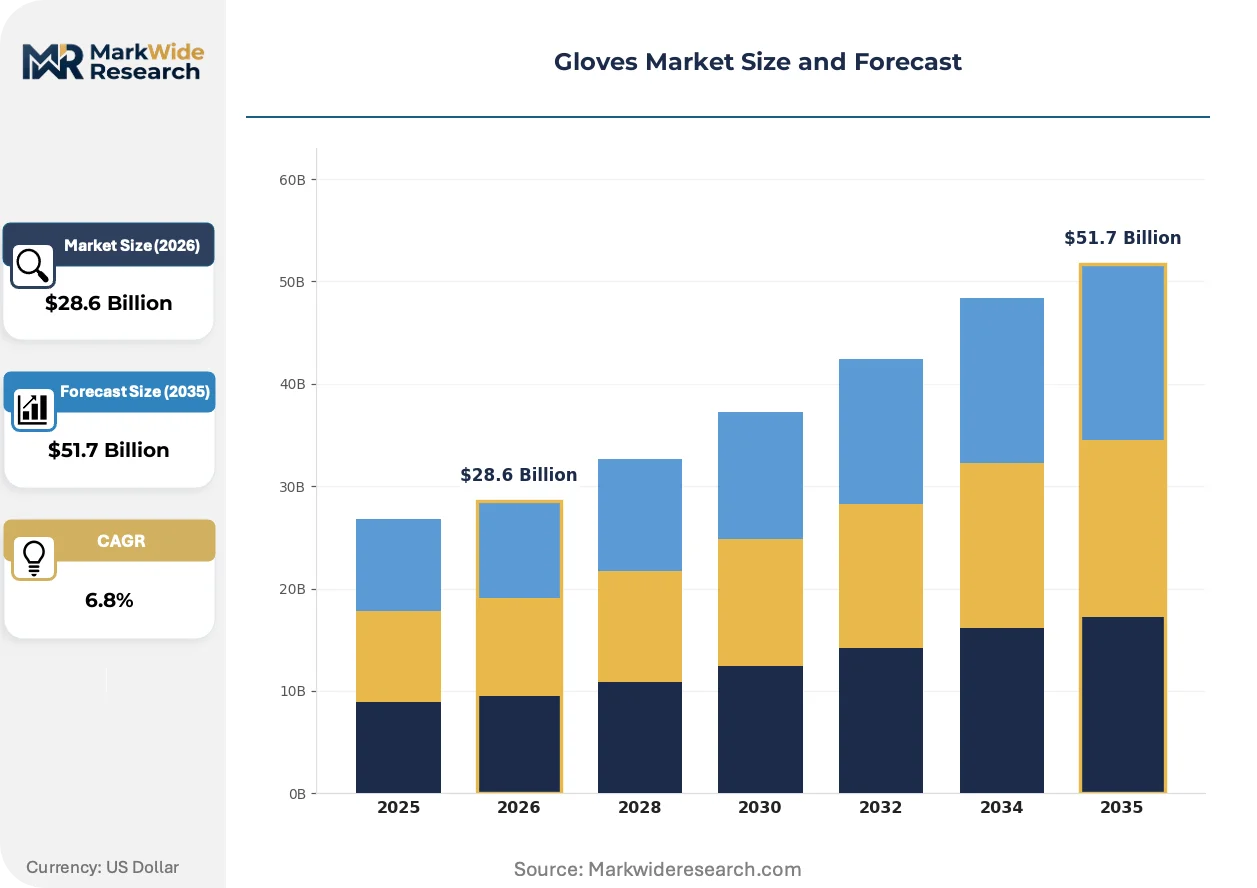
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Industrial, Medical Material: Latex, Nitrile, Vinyl, Neoprene Application: Healthcare, Food Handling, Automotive, Construction End User: Hospitals, Restaurants, Manufacturing, Laboratories |
| Companies Covered | Top Glove Corporation Berhad, Ansell Limited, Hartalega Holdings Berhad, Supermax Corporation Berhad, Kossan Rubber Industries Bhd, Honeywell International Inc., 3M Company, Kimberly-Clark Corporation, Protective Industrial Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gloves Market Strategic Shifts
Material science advances and regulatory documentation burdens are compressing competitive timelines while reshaping how buyers evaluate barrier-performance claims across clinical and industrial segments.
Chlorination surface treatment technology is integrating into nitrile glove finishing lines to reduce surface friction and enable powder-free donning without cornstarch lubricants. Hospital sterile processing departments are adopting these treated films at accelerated replacement cycles. The technology is integrating downstream quality control with upstream polymer formulation, collapsing traditional supplier-tier boundaries.
REACH substance-of-very-high-concern screening now extends to glove accelerators and processing aids used in European-distributed products. Industrial chemical-handling buyers face reformulation mandates for thiuram and carbamate-based cure packages. German automotive and French pharmaceutical manufacturing clusters are driving fastest compliance adoption, pressuring Asian exporters to revalidate material safety data sheets.
Consolidated procurement through integrated delivery networks now dominates United States hospital glove purchasing, displacing fragmented distributor relationships. Group purchasing organizations negotiate multi-year sole-source contracts with penalty clauses for supply interruptions. This concentration is most visible in Texas and California health systems, where three IDNs control regional tertiary care supply chains.
Gloves Market Segmentation
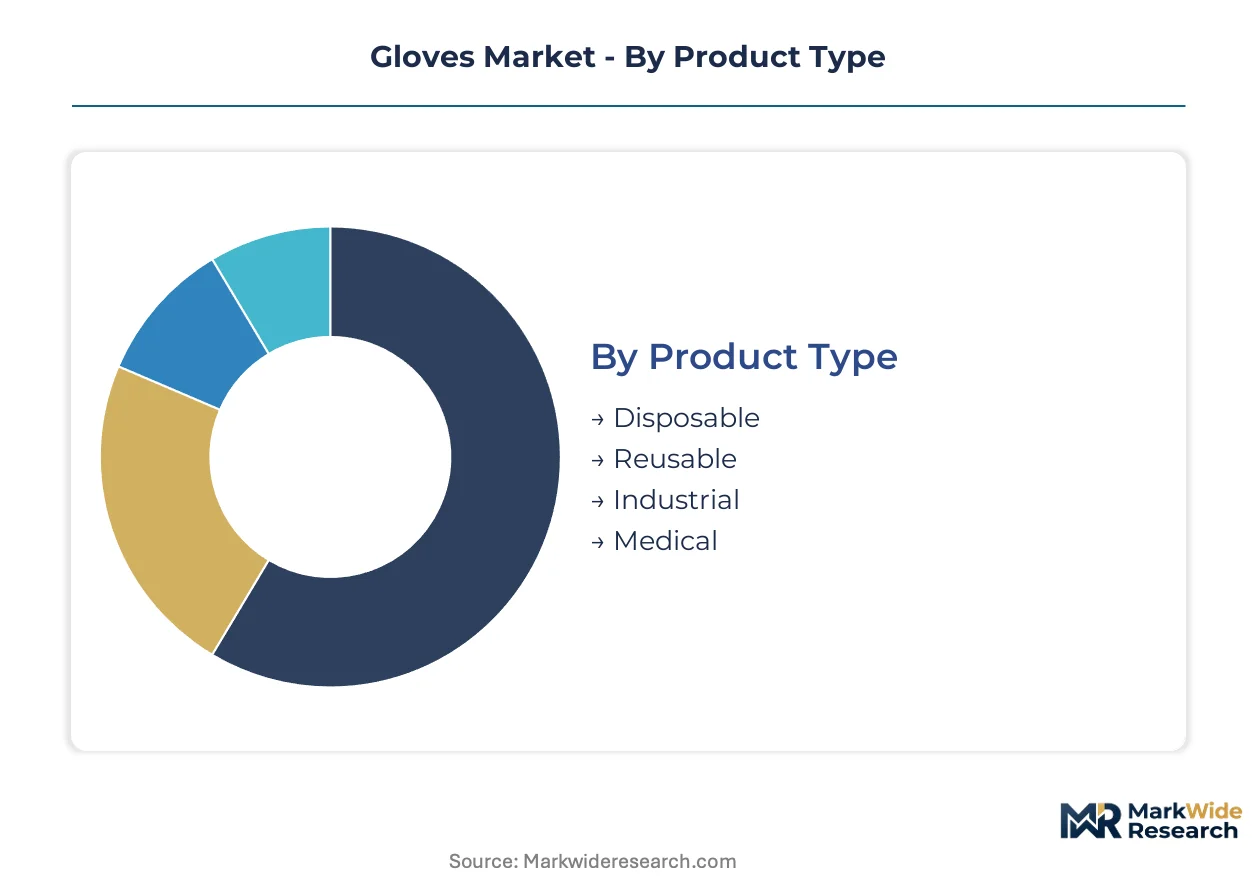
Gloves serve divergent hazard profiles across clinical sterility requirements and industrial chemical exposure. Segmentation reveals how material science and regulatory compliance create tiered value pools that reshape procurement strategies.
Product Type:
Volume concentrates in single-use formats while premium margins attach to certified reusable systems.
- Disposable:Nitrile and latex films dominate hospital and food-service procurement with 3-5 mil thickness specifications. FDA biocompatibility enforcement filters substandard suppliers from United States hospital networks while Malaysian production clusters expose buyers to logistics concentration risk.
- Reusable:Neoprene and butyl rubber gloves withstand repeated chemical exposure cycles in semiconductor fabrication and petrochemical processing. German automotive manufacturing clusters drive fastest compliance adoption for REACH substance-of-very-high-concern screening.
- Industrial:Heavy-gauge formulations meet OSHA 29 CFR 1910.138 mechanical-risk standards across chemical-handling occupations.
- Medical:Sterile and non-sterile variants differentiate surgical suites from examination room deployment.
Mature deployment sits with Disposable. Newer deployment is concentrated in Reusable.
Material:
Cost tiers separate petrochemical synthetics from natural rubber alternatives with distinct allergen profiles.
- Nitrile:Acrylonitrile-butadiene copolymer delivers superior puncture resistance and eliminates latex protein sensitivity. Healthcare procurement across Texas and California health systems hardens infection-control protocols around thin-gauge 3-mil barriers.
- Latex:Hevea brasiliensis natural rubber retains tactile sensitivity advantages but residual allergens prevent hospital reversion despite price premiums.
- Vinyl:Polyvinyl chloride formulations serve cost-sensitive food handling with lower mechanical performance thresholds.
- Neoprene:Chloroprene polymer commands premium positioning in chemical-processing applications requiring extended solvent resistance.
Established supply chains favor Latex. Steepest expansion trajectory belongs to Nitrile.
Application:
End-use concentration determines barrier-performance certification requirements and replacement-cycle economics.
- Healthcare:FDA quality-system compliance and EU MDR clinical-performance documentation create certification barriers favoring established suppliers with notified-body relationships.
- Food Handling:Vinyl and polyethylene gloves dominate high-turnover restaurant and processing plant procurement with minimal regulatory friction.
- Automotive:Chemical-resistant neoprene and nitrile blends protect against solvent exposure in paint and assembly operations.
- Construction:Cut-resistant and impact-protection gloves integrate woven substrates with elastomeric coatings for mechanical hazard mitigation.
Regulatory intensity peaks in Healthcare. Volume scale concentrates in Food Handling.
End User:
Customer-type procurement sophistication separates integrated delivery networks from fragmented distributor relationships.
- Hospitals:Group purchasing organization consolidation in United States tertiary care networks enables multi-year sole-source contracts with penalty clauses for supply interruptions.
- Restaurants:High-turnover vinyl and polyethylene glove consumption prioritizes landed cost over performance specifications.
- Manufacturing:OSHA-mandated hand-protection standards expand deployment across chemical-handling and mechanical-risk occupations.
- Laboratories:Sterile nitrile barriers and chemical-resistant formulations serve research and diagnostic testing protocols.
Procurement consolidation advances fastest in Hospitals. Price sensitivity dominates Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Klang Valley free-trade zones concentrate over sixty percent of global nitrile capacity, drawing chemical feedstock through Port Klang and Penang logistics corridors. This single-country concentration creates systemic exposure for healthcare procurement networks across three continents.
United States
Texas and California integrated delivery networks consolidate multi-year sole-source contracts with penalty clauses for supply interruptions. FDA biocompatibility enforcement under 21 CFR 880.6250 filters substandard imports from hospital procurement pools. Houston and Dallas health systems anchor regional tertiary care supply chains with centralized sterile processing departments.
Germany
Automotive manufacturing clusters in Bavaria and Baden-Württemberg drive fastest compliance adoption for REACH substance-of-very-high-concern screening on glove accelerators. ECHA documentation requirements extend to thiuram and carbamate-based cure packages in industrial chemical-handling applications. Stuttgart and Munich procurement offices revalidate material safety data sheets from Asian exporters.
China
Yangtze River Delta pharmaceutical manufacturing expands nitrile glove consumption for sterile barrier applications in biologics production. NMPA medical device registration rules tighten quality-system documentation for imported elastomeric films. Shanghai and Suzhou industrial zones host semiconductor fabrication cleanrooms requiring chemical-resistant hand protection.
Japan
Tokyo and Osaka metropolitan health systems maintain stringent JIS T 9116 standards for medical-grade barrier performance. METI industrial safety guidelines expand nitrile deployment across precision electronics assembly operations. Chubu region automotive suppliers adopt thin-gauge synthetic gloves for paint-shop solvent exposure protocols.
United Kingdom
NHS Supply Chain consolidation shifts hospital procurement toward framework agreements with notified-body-certified suppliers. MHRA post-Brexit medical device regulations create parallel compliance tracks to EU MDR for Northern Ireland and Great Britain distribution. London and Manchester procurement hubs negotiate volume commitments with Malaysian manufacturers.
Gloves Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with medical-grade certification creating tiered supplier access to hospital networks. The vendor base organizes around three strategic archetypes: Malaysian volume producers with integrated dipping-line operations, diversified industrial safety conglomerates with cross-sector portfolios, and regional contract manufacturers serving private-label distributor channels. Dominant competitive moves include backward integration into nitrile butadiene rubber compounding and automation capex programs targeting labor-cost parity.
Among Malaysia-based producers, Top Glove Corporation Berhad, Hartalega Holdings Berhad, and Kossan Rubber Industries Bhd exemplify the scale-driven archetype with concentrated Klang Valley production footprints. Ansell Limited and Honeywell International Inc. occupy positions within the diversified industrial safety tier, leveraging cross-sector resilience through medical-industrial portfolio breadth. These five entities represent distinct competitive positions without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Top Glove Corporation Berhad |
| Ansell Limited |
| Hartalega Holdings Berhad |
| Supermax Corporation Berhad |
| Kossan Rubber Industries Bhd |
| Honeywell International Inc. |
| 3M Company |
| Kimberly-Clark Corporation |
| Protective Industrial Products, Inc. |
| Others |
Value Chain & Pricing Dynamics
Skilled Malaysian dipping-line technicians concentrated in Klang Valley industrial zones anchor labor-cost differentials that spread pricing tiers between premium FDA-certified medical grades and economy food-service vinyl alternatives.
Pricing Analysis
Short lead-time premiums separate hospital procurement contracts from spot-market inventory discounts in distributor channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA biocompatibility enforcement filtering substandard imports from United States hospital networks. Cost compression in economy vinyl tiers intensifies because crude oil volatility feeds directly into polyvinyl chloride resin costs. Restaurants exhibit highest price sensitivity, while integrated delivery networks in tertiary care systems accept premium positioning for assured supply continuity.
Supply Chain Analysis
Certification gating through FDA quality-system compliance and EU MDR notified-body relationships restricts supplier access to hospital procurement pools. Manufacturing concentrates in Malaysia, Thailand, and China, with nitrile butadiene rubber compounding drawing from petrochemical feedstocks anchored in Singapore and South Korea. Single-country concentration risk in Peninsular Malaysia exposes buyers to logistics chokepoint vulnerability through Port Klang. Distribution runs through group purchasing organizations and integrated delivery networks that consolidate fragmented hospital purchasing into multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR documentation burdens and automation capex requirements are forcing subscale manufacturers toward exit, creating consolidation opportunity for capitalized survivors.
For Market Incumbents: Extend backward integration into nitrile butadiene rubber compounding to secure feedstock cost parity against emerging competitors. Build automation capacity in Vietnamese or Indonesian zones to diversify labor-cost exposure beyond Klang Valley concentration. FDA biocompatibility enforcement and notified-body queue congestion favor established suppliers with legacy CE certificates and technical documentation libraries. For New Entrants and Emerging Players: Enter via specialty chemical-resistant reusable glove segments serving semiconductor fabrication and petrochemical processing, where neoprene and butyl premium margins offset lower volume scale. Target German automotive manufacturing clusters demanding REACH-compliant accelerator-free formulations. Pursue direct hospital contracting through regional integrated delivery networks bypassing distributor markups. For Investors and Strategic Acquirers: Re-rating potential sits with Malaysian volume producers possessing notified-body relationships and dipping-line automation given EU MDR transition extending certification barriers. Long-term viability over a five-to-ten year window favors suppliers with dual medical-industrial portfolios that buffer sector-specific demand shocks. Watch nitrile butadiene rubber spot price spreads against crude oil benchmarks as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Butadiene Rubber Compounding | Captive supply of acrylonitrile-butadiene copolymer insulates margin pressure from petrochemical feedstock volatility. |
| Automation Capex in Dipping-Line and Packing Operations | Robotic integration maintains unit economics against labor-cost inflation in Malaysian manufacturing zones. |
| EU MDR Notified-Body Certification Investment | Technical documentation capabilities create twelve-to-eighteen month barriers delaying competitor market entry. |
| Direct Hospital Contracting Through IDN Consolidation | Multi-year sole-source agreements with penalty clauses lock in volume commitments across Texas and California health systems. |
| Accelerator-Free Formulation Development | Thiuram and carbamate elimination satisfies REACH substance-of-very-high-concern screening for German automotive clusters. |
Study Parameters
Independent corroboration across primary interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and Malaysian plant operations directors, alongside secondary validation through FDA 510(k) filings, EU MDR notified-body certificates, customs trade data, and SEC 10-K disclosures, underwrites the qualitative findings. Bottom-up triangulation across end-user demand signals and top-down supply capacity assessments from Klang Valley production zones converge on volume estimates.
Comparable-period anchoring to pre-pandemic baseline utilization rates and post-surge normalization patterns structures the forecast window across the analysis window. Segmentation dimensions span product type, material grade, application, and end-user procurement sophistication, with CAGRs derived from elasticity modeling against healthcare expenditure trends and industrial safety mandate expansion. Nitrile butadiene rubber supply dynamics and regulatory harmonization pressures feed directly into scenario-weighted projections.
Revisions become necessary when butadiene monomer price volatility exceeds historical bands or when EU MDR technical documentation queues extend beyond eighteen months. Forecasts reflect assumptions around Malaysian production stability and REACH substance screening scope expansion. A model refresh is warranted upon material change in integrated delivery network consolidation pace or FDA biocompatibility enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market