
 United States Nuclear Power Plant Equipment Market | 2026-2036
United States Nuclear Power Plant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Nuclear Power Plant Equipment Market Analytics
Nuclear welder and quality assurance inspector availability is rotating toward shortage as aging specialists retire faster than training pipelines replenish. Westinghouse Electric Company LLC leverages its Pittsburgh engineering base to sustain pressure vessel fabrication expertise. GE Hitachi Nuclear Energy anchors its Wilmington, North Carolina campus as a hub for BWR component manufacturing. BWX Technologies Inc dominates naval-to-commercial crossover welding protocols that few competitors replicate.
United States nuclear power plant equipment encompasses reactor pressure vessels, steam generators, turbine-generator sets, and digital instrumentation governed by ASME Section III nuclear quality standards and 10 CFR Part 50 design certification requirements. Pressurized Water Reactor technology occupies the largest installed base while Small Modular Reactor designs attract the fastest-growing engineering investment pool. Utility Companies represent the dominant procurement channel, though Government Agencies command premium pricing for national laboratory and defense-linked reactor systems.
The NRC enforces equipment qualification under 10 CFR Part 50 Appendix B while the DOE's Loan Programs Office shapes financing access for first-of-a-kind deployments. ASME N-stamp certification creates structural barriers for foreign suppliers seeking direct market entry. Stakeholders must monitor how Part 53 risk-informed licensing evolves equipment testing requirements for advanced reactor architectures.
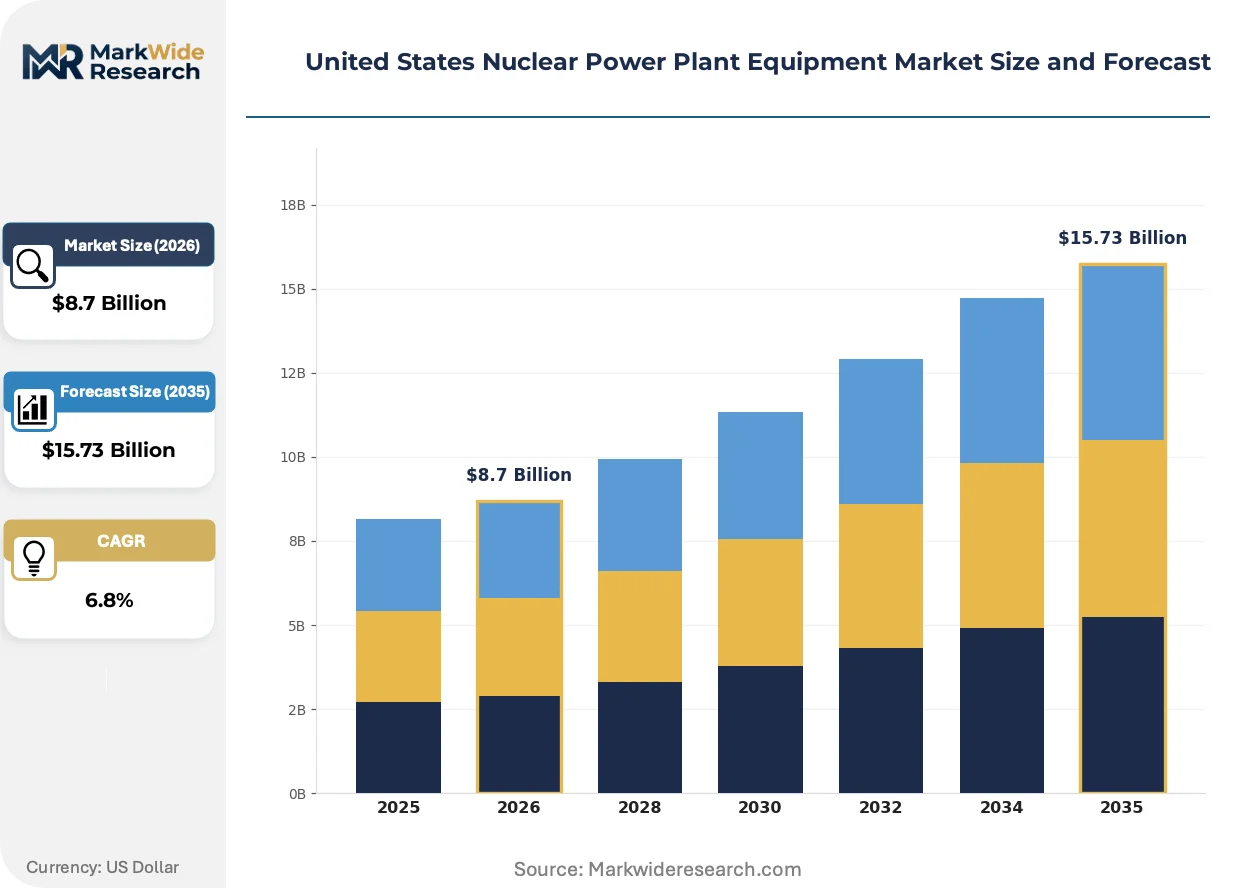
Market Dynamics
The United States nuclear power plant equipment market is being restructured by the NRC's Part 52 licensing framework, which compresses qualification timelines for advanced reactor designs while simultaneously tightening documentation burdens on traditional suppliers.
Growth Catalysts
- Part 52 Licensing:The NRC's framework for advanced reactors accelerates equipment qualification pathways, reducing time-to-deployment for first-of-a-kind systems.
- Southeast Procurement Cluster:Vogtle Unit 3 and 4 completions, plus planned SMR deployments in Georgia and Tennessee, concentrate demand for reactor pressure vessels and steam generators.
- Naval-to-Commercial Welding Transfer:Defense-linked fabrication protocols developed for submarine reactor programs are being adapted for civilian nuclear applications, expanding qualified supplier pools.
Market Restraints
- ASME N-Stamp Concentration:Foreign suppliers face structural barriers to direct market entry without domestic certification infrastructure, limiting price competition.
- Specialized Welder Scarcity:Nuclear-qualified welders and quality assurance inspectors are retiring faster than training pipelines replenish, constraining fabrication capacity.
- First-of-a-Kind Cost Risk:SMR and advanced reactor designs carry unproven construction cost profiles that deter utility procurement committees from early adoption.
Strategic Opportunities
- DOE Loan Programs Office:Financing access for novel reactor architectures creates pathways for equipment suppliers to secure long-term offtake agreements with developers.
- Digital Instrumentation Retrofit:Aging analog control systems in the existing PWR fleet create demand for cybersecurity-hardened replacement platforms.
- Part 53 Risk-Informed Licensing:Evolving testing requirements for advanced reactor architectures will favor suppliers with probabilistic risk assessment capabilities.
Industry Challenges
- 10 CFR Part 50 Appendix B Compliance:Equipment qualification documentation requirements extend procurement cycles and strain engineering resources at mid-tier suppliers.
- Legacy System Integration:Digital upgrades must interface with 1970s-era analog infrastructure without triggering full license amendment reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Nuclear Power Plant Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactors, Turbines, Heat Exchangers, Control Systems Technology: Pressurized Water Reactor, Boiling Water Reactor, Advanced Gas-cooled Reactor, Fast Breeder Reactor Application: Electricity Generation, Research, Medical Isotope Production, Training Simulators End User: Utility Companies, Government Agencies, Research Institutions, Contractors |
| Companies Covered | Westinghouse Electric Company LLC, GE Hitachi Nuclear Energy, BWX Technologies Inc, Mitsubishi Heavy Industries Ltd, Doosan Corporation, Babcock & Wilcox Company, Framatome Inc, Holtec International, NuScale Power Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Nuclear Power Plant Equipment Market Evolving Landscape
Equipment supply in the United States nuclear sector is splitting between two incompatible logics: massive custom fabrication for gigawatt-scale plants versus standardized module production for emerging SMR designs.
Additive manufacturing is bifurcating the supply base for complex reactor components. Laser powder bed fusion now produces nickel-alloy heat exchanger headers with internal geometries impossible through conventional machining. Duke Energy and Southern Company are qualifying these parts for non-safety applications first, creating a pathway toward pressure-boundary acceptance. This technology is compressing lead times for prototype components from 18 months to 6 weeks.
The NRC is advancing a risk-informed, technology-inclusive regulatory framework under 10 CFR Part 53. This shifts equipment testing from prescriptive deterministic methods toward performance-based probabilistic standards. Advanced reactor developers including Kairos Power and X-energy are engaging the NRC earlier in design certification, forcing equipment suppliers to front-load quality assurance documentation.
Utility procurement committees are unbundling long-term service agreements from initial equipment supply. Exelon and Dominion Energy now negotiate turbine-generator maintenance separately from capital purchases, opening market entry for specialized aftermarket providers. This pattern is most visible in the Midwest and Mid-Atlantic states where merchant plant economics pressure operating cost reduction.
United States Nuclear Power Plant Equipment Market Segmentation
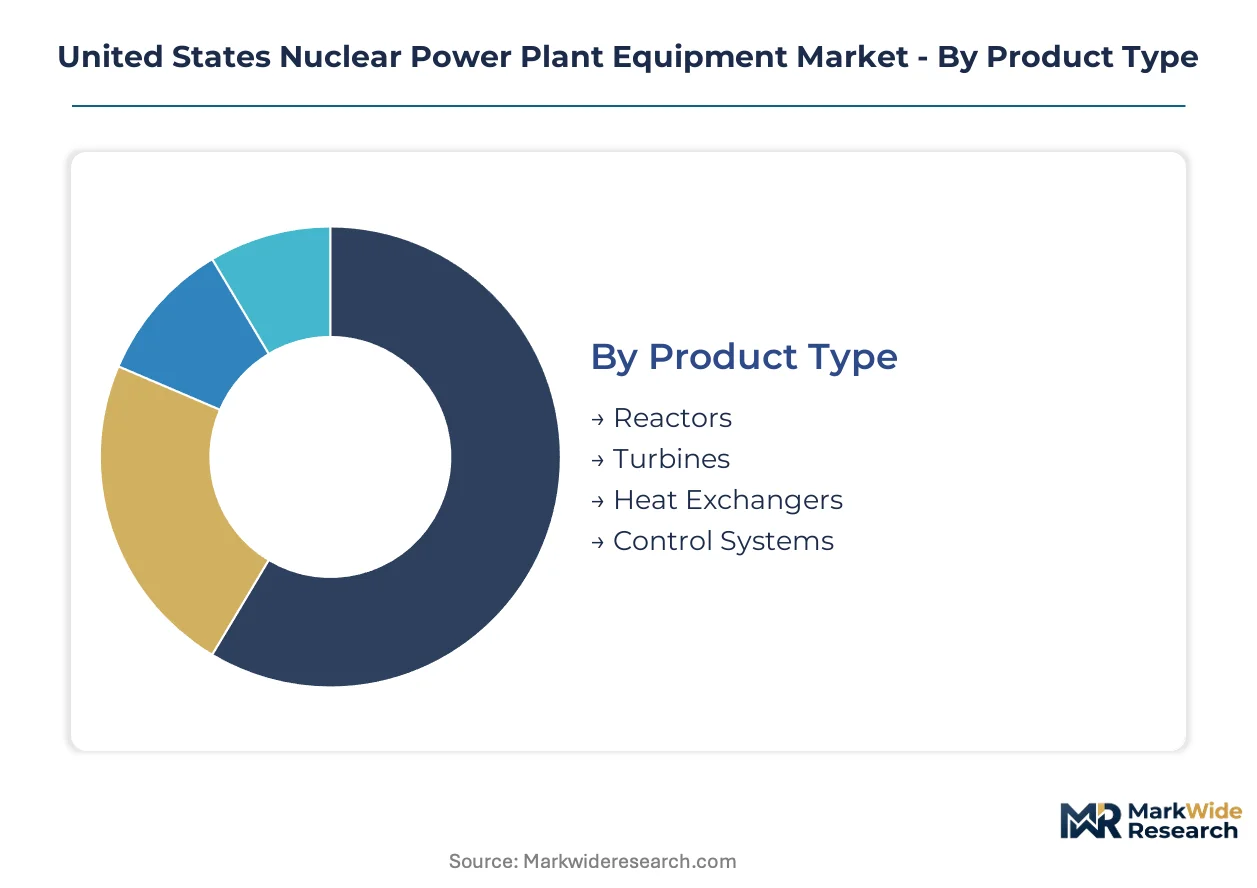
Equipment procurement patterns in the United States nuclear sector diverge sharply across reactor scale, regulatory pathway, and end-use mission. Segmentation reveals where specialized fabrication competes against commoditized supply, and which customer types absorb premium qualification costs.
Product Type:
Reactors face the most acute substitution pressure as SMR developers pursue factory-fabricated alternatives to field-welded pressure vessels. Heat exchangers and control systems occupy more defensible positions due to ASME N-stamp barriers and cybersecurity hardening requirements.
- Reactors:Reactor pressure vessels and steam generators demand SA-508 Grade 3 steel forgings with neutron fluence resistance specifications. Procurement clusters at Vogtle and planned Clinch River SMR anchor demand in Georgia and Tennessee, though first-of-a-kind cost risk slows utility commitment cycles.
- Turbines:Turbine-generator sets rotate at 1,800 RPM for 60 Hz grid synchronization with moisture-separator reheaters upstream. Merchant plant operators in the Midwest and Mid-Atlantic unbundle long-term service agreements from capital purchases, opening aftermarket entry points.
- Heat Exchangers:Nickel-alloy tubing resists chloride stress corrosion in secondary loops.
- Control Systems:Digital instrumentation platforms require 10 CFR Part 73 cybersecurity compliance for safety-related functions.
Reactors anchor the volume base while control systems gain share at the steepest rate.
Technology:
Cost tier stratification separates mature designs with established supply chains from advanced architectures requiring new qualification pathways. Pressurized Water Reactor equipment commands the deepest supplier bench; Fast Breeder Reactor components face the steepest fabrication learning curves.
- Pressurized Water Reactor:PWR technology dominates the installed base with Westinghouse and Framatome fuel assembly designs. Southeast utilities at Vogtle and V.C. Summer replacement studies sustain demand for replacement steam generators and reactor vessel heads.
- Boiling Water Reactor:GE Hitachi's BWR designs concentrate in the Midwest and Northeast where Exelon and Constellation operate legacy fleets. Recirculation pump replacements and control rod drive overhauls drive recurring equipment demand.
- Advanced Gas-cooled Reactor:Graphite-moderated designs remain experimental in the United States.
- Fast Breeder Reactor:Sodium-cooled fast reactor development at TerraPower and Natrium faces unproven fuel fabrication scale-up.
PWR equipment captures the largest revenue pool while Fast Breeder Reactor supply chains expand most quickly.
Application:
Customer mission type determines specification stringency and procurement timeline flexibility. Electricity generation imposes the tightest cost discipline; national laboratory research programs absorb extended qualification schedules.
- Electricity Generation:Baseload power applications require 90% capacity factor reliability with 18-month fuel cycles. Merchant plant economics in Texas and Illinois pressure equipment suppliers to reduce installed cost per kilowatt.
- Research:National laboratory reactors at Oak Ridge and Idaho National Laboratory prioritize neutron flux performance over commercial economics.
- Medical Isotope Production:Molybdenum-99 irradiation targets require high-enrichment uranium conversion to low-enriched alternatives.
- Training Simulators:Control room replica systems use non-nuclear hardware with software fidelity specifications.
Electricity generation anchors the volume base while medical isotope production gains share at the steepest rate.
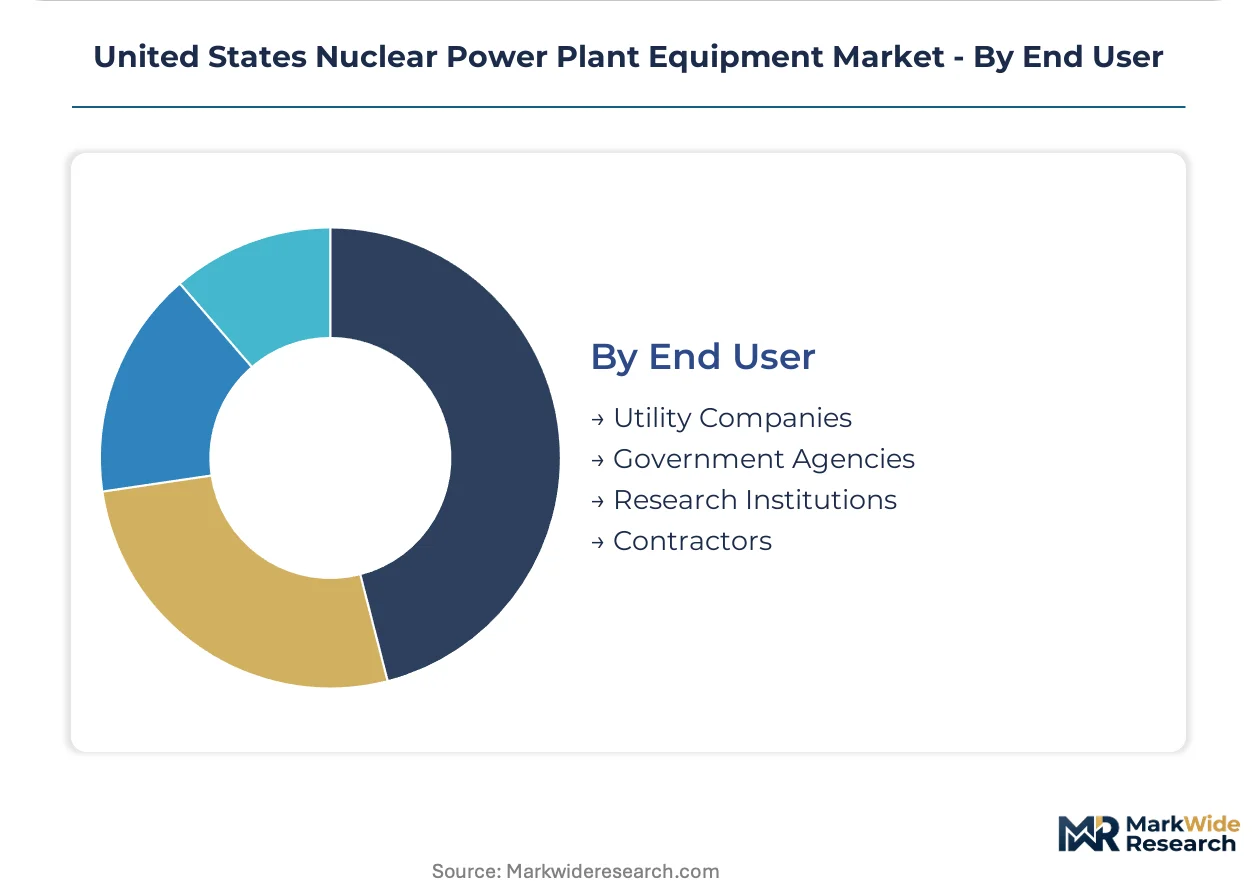
End User:
Procurement authority concentration varies dramatically across customer type, with utility companies driving standardization and government agencies demanding customization. Research institutions occupy intermediate positions with peer-review-driven specification processes.
- Utility Companies:Exelon, Constellation, and Southern Company dominate procurement volume with centralized engineering review boards. Fleet-wide standardization programs pressure suppliers to qualify single designs across multiple plant sites.
- Government Agencies:DOE national security programs and NASA space reactor development command premium pricing for defense-linked fabrication protocols.
- Research Institutions:University reactor operators at MIT and University of Missouri face constrained capital budgets.
- Contractors:Engineering-procurement-construction firms aggregate equipment packages for turnkey delivery.
Utility companies anchor the volume base while government agencies gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement intensity varies sharply across U.S. sub-regions, with the Southeast absorbing the bulk of new-build pressure vessel demand while the Midwest concentrates on legacy fleet maintenance and digital retrofits.
Southeast
Vogtle Units 3 and 4 anchor the nation's only recent commercial reactor completions, sustaining demand for reactor pressure vessels and steam generators. The NRC's Part 52 licensing framework accelerates equipment qualification for planned SMR deployments at the Clinch River site in Tennessee. Southern Company and Duke Energy procurement committees dominate regional supply chain coordination from Atlanta and Charlotte engineering hubs.
Midwest
Exelon and Constellation operate the densest concentration of aging BWR and PWR fleets, driving recurring demand for recirculation pump replacements and control rod drive overhauls. FERC merchant plant economics in Illinois and Ohio pressure equipment suppliers to reduce installed cost per kilowatt. GE Hitachi maintains BWR component manufacturing expertise at its Wilmington, North Carolina campus serving Midwest utility customers.
Northeast
Merchant nuclear operators in New York and New England prioritize digital instrumentation retrofits over major capital equipment replacement. The NRC enforces 10 CFR Part 73 cybersecurity compliance for safety-related control system upgrades. Framatome Inc and Westinghouse Electric Company LLC sustain engineering support offices in the Pennsylvania-New Jersey corridor for fleet-wide standardization programs.
Southwest
Arizona and Texas host Palo Verde and Comanche Peak generating stations with concentrated procurement for replacement steam generators and reactor vessel heads. DOE national laboratory linkages at Sandia and Los Alamos create demand for research reactor equipment with defense-linked fabrication protocols. NuScale Power Corporation engages utilities in Utah and Idaho for first-of-a-kind SMR deployment planning.
Pacific Northwest
Hanford Site remediation and Columbia Generating Station operations sustain specialized procurement for unique reactor architectures. The DOE's Loan Programs Office shapes financing access for advanced reactor developers including X-energy and TerraPower with Pacific Northwest engineering presence. BWX Technologies Inc leverages naval reactor fabrication protocols from its Idaho operations for emerging commercial crossover opportunities.
United States Nuclear Power Plant Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fabrication scale and ASME N-stamp certification creating durable competitive moats. The market structure rewards vertical integration into pressure vessel forging and specialized welding protocols that few competitors replicate. Strategic archetypes include defense-linked naval suppliers pivoting to commercial applications, established reactor vendors sustaining engineering ecosystems, and emerging SMR developers building captive supply chains. Dominant competitive moves center on qualification documentation investments for Part 52 licensing pathways and strategic partnerships with utility procurement committees for long-term service agreement unbundling.
Within the integrated engineering tier, Westinghouse Electric Company LLC and GE Hitachi Nuclear Energy exemplify archetypes of established reactor vendors sustaining multi-decade fabrication expertise. BWX Technologies Inc occupies a distinctive position bridging defense and commercial nuclear supply chains. These three anchors represent how certification infrastructure and welding protocol mastery create structural barriers that limit direct market entry for foreign competitors lacking domestic ASME N-stamp qualification.
| Leading Market Players |
|---|
| Westinghouse Electric Company LLC |
| GE Hitachi Nuclear Energy |
| BWX Technologies Inc |
| Mitsubishi Heavy Industries Ltd |
| Doosan Corporation |
| Babcock & Wilcox Company |
| Framatome Inc |
| Holtec International |
| NuScale Power Corporation |
| Others |
Value Network & Pricing Analysis
Eighteen-month lead times for SA-508 Grade 3 steel forgings concentrate pricing power among domestic ASME N-stamp holders while compressing margins for mid-tier fabricators without captive forging capacity. This supply concentration reinforces long-term offtake contracting as the dominant procurement mode for reactor pressure vessels and steam generators.
Pricing Analysis
Long-term offtake agreements dominate equipment procurement, with utility procurement committees negotiating multi-year contracts that bundle engineering support with fabrication delivery. Price differentiation hinges on ASME Section III certification tier and welding protocol sophistication, with defense-linked suppliers commanding premiums for naval-to-commercial crossover expertise. Cost compression in standard heat exchanger categories intensifies as foreign competitors with indirect certification pathways gain indirect market access. Merchant plant operators in the Midwest exhibit the highest price sensitivity, while DOE national security programs absorb premium pricing for specialized fabrication protocols.
Supply Chain Analysis
Domestic forging capacity at Pittsburgh and Charlotte anchors supply for pressure-boundary components, with Japan and France providing specialized alloy inputs for corrosion-resistant applications. The supply chain draws from nickel-alloy tubing manufacturers in Germany and South Korea for steam generator bundles, while digital instrumentation modules source from domestic cybersecurity-hardened fabricators. Single-source vulnerability concentrates in large-diameter forging presses capable of reactor vessel manufacture, with only three North American facilities qualified for nuclear-grade work. Distribution runs through engineering-procurement-construction firms that aggregate equipment packages for turnkey utility delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment procurement fragmentation creates entry niches as utility committees unbundle long-term service agreements from initial capital purchases, opening aftermarket specialization opportunities for qualified welders and digital retrofit providers.
For Market Incumbents: Consolidate welding protocol expertise through targeted acquisition of naval-certified fabrication shops facing defense budget cyclicality, securing capacity that SMR developers will need for factory-fabricated module production. Deepen backward integration into nickel-alloy tubing supply through exclusive offtake arrangements with specialty steel producers, defending margin position against foreign competitors with indirect ASME certification pathways. For New Entrants and Emerging Players: ASME N-stamp fast-track programs for former naval welders create immediate qualification pathways into steam generator maintenance and recirculation pump overhaul segments. Target the Midwest merchant plant cluster where Exelon and Constellation unbundle service contracts, offering specialized digital instrumentation retrofit capabilities that incumbent reactor vendors have deprioritized. Lead with cybersecurity compliance documentation as the go-to-market differentiator for control system upgrades. For Investors and Strategic Acquirers: Carve-out targets emerge from defense prime contractors seeking to monetize non-core nuclear fabrication assets with dormant commercial certification. Frame long-term viability around the five-to-ten year SMR deployment window, prioritizing suppliers with transferable welding protocols and existing NRC engagement history. Watch NRC Part 53 rulemaking progress as the signal for which equipment testing methodologies will dominate advanced reactor qualification.| Strategic Initiative | Industry Significance |
|---|---|
| ASME N-Stamp Certification Investment | Creates structural barriers against foreign competitors lacking domestic qualification infrastructure. |
| Naval-to-Commercial Welding Transfer | Expands qualified supplier pools by adapting defense-linked fabrication protocols for civilian applications. |
| Digital Instrumentation Retrofit Specialization | Captures demand from aging analog control systems requiring 10 CFR Part 73 cybersecurity compliance. |
| Long-Term Service Agreement Unbundling | Opens aftermarket entry points as utility procurement committees separate maintenance from capital purchases. |
| SMR Module Factory Fabrication Partnership | Positions suppliers for standardized production volumes at Clinch River and planned Tennessee deployments. |
Research Methodology
Cross-validation between NRC licensing database records and DOE Loan Programs Office disclosure documents anchors the qualitative findings on equipment qualification pathways. Primary interviews with utility procurement officers, ASME certification auditors, naval reactor program managers, and EPC project directors combined with secondary analysis of 10-K filings, FERC interconnection queues, and EIA reactor status reports. Bottom-up fabrication capacity surveys triangulate against top-down utility capital expenditure projections.
Sensitivity analysis around SMR deployment timelines and Part 53 regulatory finalization shapes the forecast framework across the projection horizon. Segmentation dimensions include reactor scale, regulatory pathway, end-use mission, and customer procurement authority concentration. CAGRs derive from equipment unit economics modeled against announced project development pipelines, with inputs from welding labor availability curves and specialty steel price indices.
Underlying assumptions cover NRC licensing velocity, utility commitment cycle duration, and welder training pipeline replenishment rates, with deviation risk concentrated in first-of-a-kind construction cost overruns and advanced reactor design certification delays. Practitioners should keep alternative scenarios live as Part 53 risk-informed testing requirements and DOE financing access conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Japan Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Thorium Market