
 Nuclear Steam Generator Market | 2026-2036
Nuclear Steam Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Steam Generator Market Analysis
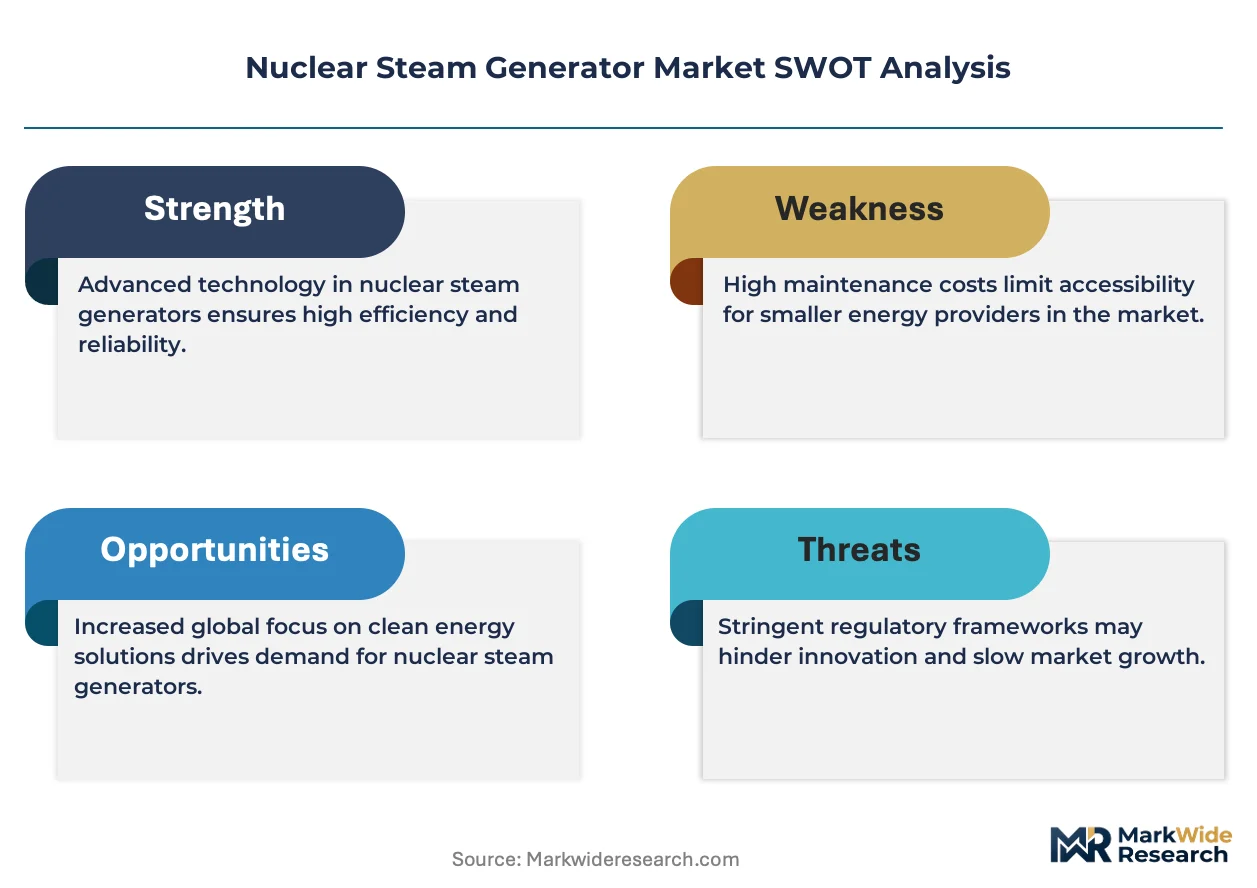
Power purchase agreement-backed project finance is tilting procurement authority toward independent power producers and away from traditional state-owned utilities. Doosan Enerbility leverages its integrated forging and fabrication complex in Changwon to anchor large-diameter shell orders. Westinghouse Electric Company sustains competitive positioning through its AP1000 design certification portfolio across multiple regulatory jurisdictions. Mitsubishi Heavy Industries specializes in thermal-hydraulic optimization for pressurized water reactor configurations.
A nuclear steam generator is a heat exchanger that transfers thermal energy from a reactor's primary coolant loop to the secondary loop, producing dry steam at pressures typically ranging from 5 to 7 MPa for turbine-driven electricity generation. The device employs thousands of U-bend tubes manufactured from thermally treated Alloy 690 or titanium to withstand primary-side borated water chemistry and secondary-side steam conditions over forty-year design lives. Vertical steam generators dominate existing installed capacity across pressurized water reactor fleets, while modular compact designs are gaining traction in small modular reactor development programs where footprint constraints and factory fabrication economics reshape procurement specifications. Alloy 690 tube bundles command premium positioning due to superior stress-corrosion cracking resistance compared with legacy S304 and S316 alloys.
The US Nuclear Regulatory Commission enforces 10 CFR Part 50 quality assurance standards that govern steam generator tube integrity and in-service inspection intervals, while France's ASN and South Korea's NSSC impose comparable material certification and welding procedure mandates that extend supplier qualification timelines. China's National Nuclear Safety Administration and India's Atomic Energy Regulatory Board operate parallel certification frameworks that restrict market access to pre-qualified fabricators with demonstrated heavy component manufacturing records. Stakeholders must monitor regulatory harmonization progress between Western and Asian certification regimes to anticipate qualification cost structures and supplier pool eligibility for upcoming replacement steam generator campaigns.
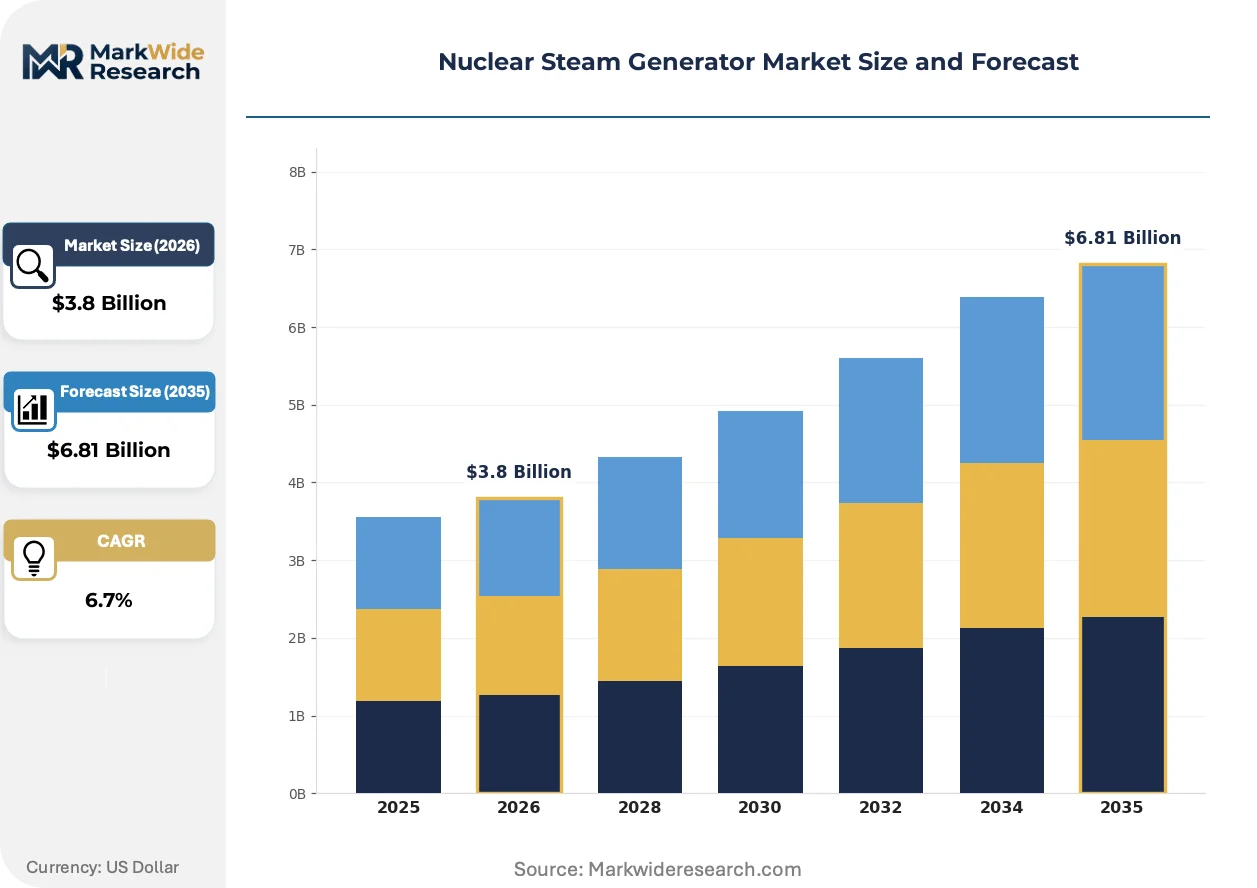
Market Dynamics
The nuclear steam generator market faces acute pressure from accident-tolerant fuel cladding standards that are tightening material specifications and disqualifying legacy suppliers from new-build qualification programs.
Growth Catalysts
- AP1000 Design Certification:Westinghouse's reactor platform has secured regulatory validation across multiple jurisdictions, creating standardized procurement specifications that streamline supplier pre-qualification for utilities in China and the United States.
- Alloy 690 Tube Adoption:Superior stress-corrosion cracking resistance is rendering thermally treated Alloy 690 the default specification for replacement steam generator campaigns, displacing legacy S304 and S316 alloys from active procurement lists.
- Small Modular Reactor Programs:Factory fabrication economics and footprint constraints are driving demand for compact vertical steam generator designs in emerging nuclear markets.
Market Restraints
- Supplier Pool Concentration:Heavy forging capacity for reactor pressure vessels and steam generator shells concentrates in South Korea's Changwon industrial complex and Japan's Kobe Steel operations, creating single-source vulnerability for large-diameter components.
- Extended Qualification Timelines:China's National Nuclear Safety Administration and India's Atomic Energy Regulatory Board impose parallel certification frameworks that restrict market access to fabricators with demonstrated heavy component manufacturing records, extending pre-qualification periods beyond thirty-six months.
- Legacy Fleet Decommissioning:Premature reactor closures in Germany and Belgium are compressing replacement steam generator demand in Western Europe while Asian markets absorb available fabrication capacity.
Strategic Opportunities
- India's Pressurized Heavy Water Reactor Expansion:The Department of Atomic Energy's indigenous 700 MWe PHWR program creates demand for horizontal steam generator configurations distinct from Western PWR designs, opening procurement channels for specialized fabricators.
- 10 CFR Part 50 Harmonization:Alignment between US Nuclear Regulatory Commission quality assurance standards and South Korea's NSSC certification frameworks could reduce dual-qualification costs for suppliers serving both markets.
- Titanium Tube Bundle Applications:Corrosion-resistant titanium alloys are penetrating coastal nuclear installations where secondary-side seawater cooling accelerates material degradation in conventional tube bundles.
Industry Challenges
- Welding Procedure Qualification:ASME Section IX and RCC-M code compliance for Alloy 690 tube-to-tubesheet joints requires specialized automated narrow-groove welding equipment that few fabricators possess, constraining qualified supplier expansion.
- In-Service Inspection Protocols:Eddy current testing intervals mandated by France's ASN and the US NRC require steam generator designs with accessible tube bundles and removable headers, complicating compact modular configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Steam Generator Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Modular, Compact Material: S304, S316, Alloy 690, Titanium End User: Utilities, Power Plants, Research Institutions, Government Facilities Application: Electricity Generation, Heat Recovery, Industrial Processes, Chemical Manufacturing |
| Companies Covered | Babcock & Wilcox Enterprises, Doosan Enerbility, GE-Hitachi Nuclear Energy, Larsen & Toubro, Japan Steel Works, Westinghouse Electric Company, China National Nuclear Corporation, Bharat Heavy Electricals Limited, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Steam Generator Market Emerging Trajectories
Digital twin deployment and additive manufacturing are reshaping how steam generator components are designed, qualified, and maintained across pressurized water reactor fleets. These technologies compress development cycles while tightening quality assurance requirements.
Compact vertical steam generators with integral economizer sections are rendering obsolete traditional separate-component configurations in small modular reactor designs. NuScale Power and Rolls-Royce SMR programs specify these integrated units for factory fabrication. The structural consequence is collapsing the distinction between nuclear island and conventional island equipment suppliers.
France's ASN has tightened stress-corrosion cracking surveillance requirements through enhanced eddy current testing protocols that mandate shorter inspection intervals for plants operating beyond forty years. This regulatory pressure is accelerating replacement steam generator procurement for aging French and Belgian PWR fleets. Utilities are responding with life-extension engineering studies that justify major capital investments in secondary-side component replacement.
Independent power producers backed by power purchase agreements are displacing traditional state-owned utility procurement authority in emerging nuclear markets. These financiers demand standardized equipment specifications and multi-unit order commitments to secure project debt. The shift is most visible in Poland and the Czech Republic, where first-of-a-kind reactor projects require vendor consortia to assume equipment performance guarantees previously borne by national utilities.
Nuclear Steam Generator Market Segmentation
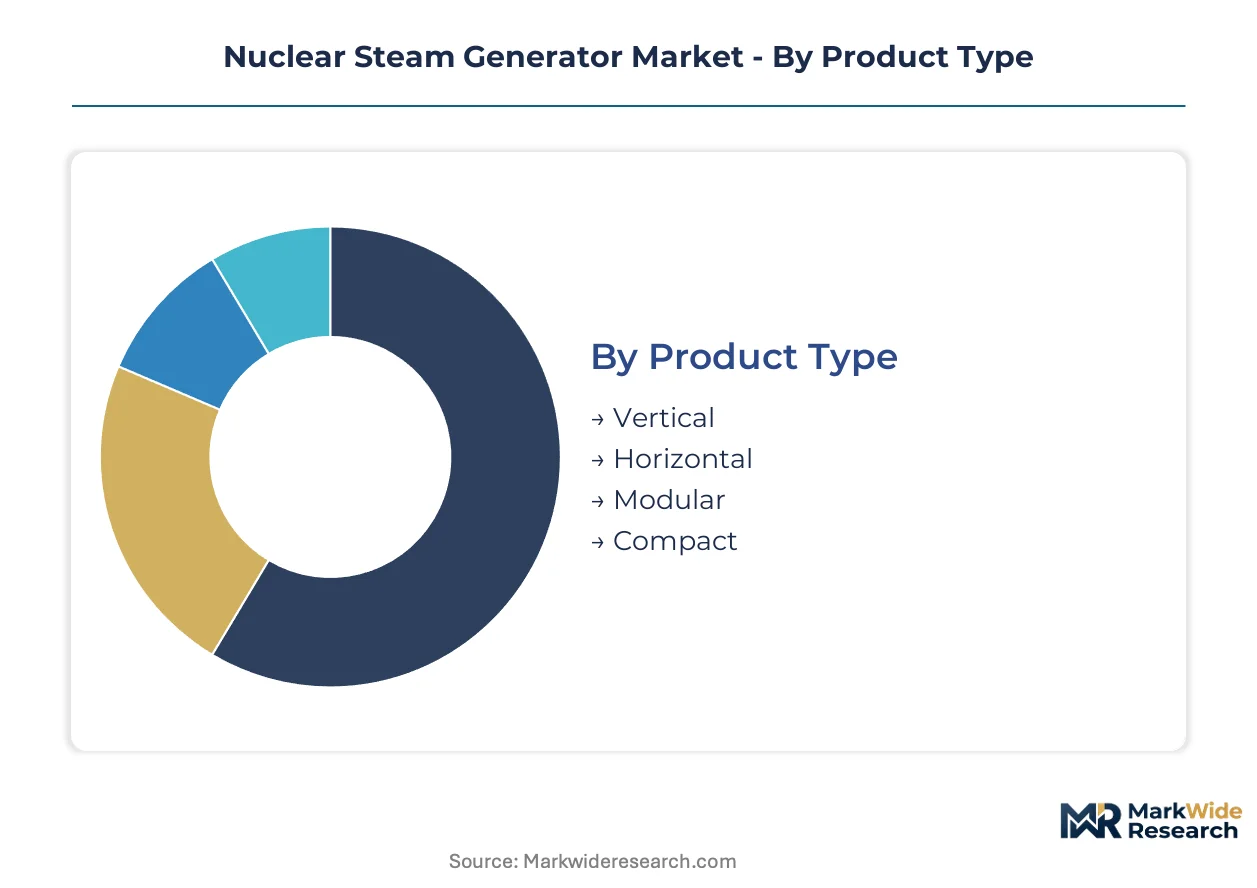
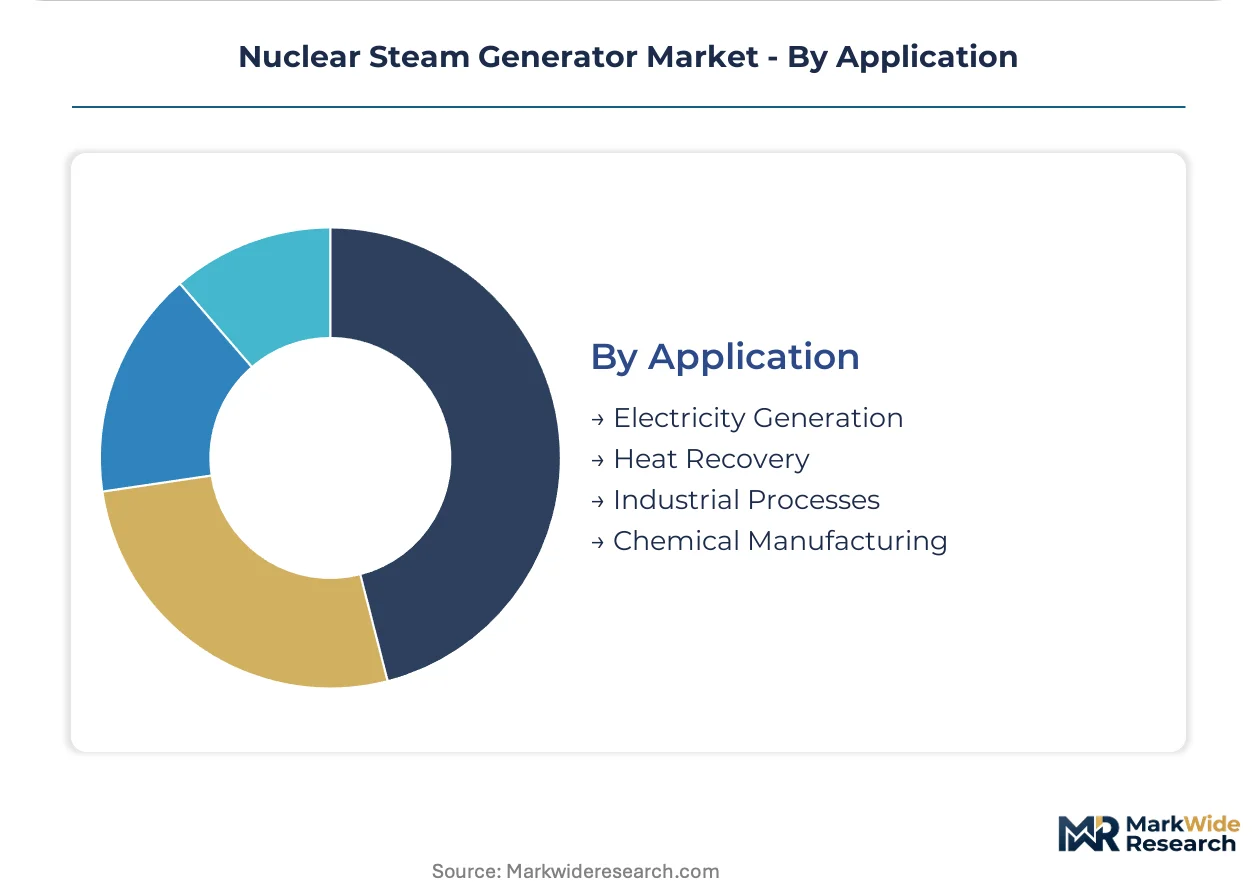
Steam generator procurement patterns diverge sharply across reactor generations, with legacy pressurized water reactor fleets favoring proven vertical designs while small modular reactor developers specify compact factory-fabricated units. Material selection and end-user financing structures further fragment supplier qualification pathways.
Product Type:
Mature reactor fleets anchor demand for conventional configurations, while emerging SMR programs are reshaping fabrication economics through modular specifications.
- Vertical:Dominant across existing installed capacity in pressurized water reactor fleets, these units employ U-bend tube bundles arranged in cylindrical shells with diameters exceeding four meters. Demand concentrates in replacement campaigns for French and Belgian utilities operating beyond forty-year design lives, driven by ASN-mandated stress-corrosion cracking surveillance intervals.
- Horizontal:Configured for pressurized heavy water reactor applications with tube bundles arranged perpendicular to the primary coolant flow axis. India's Department of Atomic Energy specifications for indigenous 700 MWe PHWR units create specialized procurement channels distinct from Western PWR supply chains.
- Modular:Factory-fabricated units sized for transport by rail or barge to reactor sites. NuScale Power specifications favor these designs.
- Compact:Integral economizer configurations collapsing nuclear and conventional island boundaries. Rolls-Royce SMR programs specify these units.
Vertical configurations handle the majority of throughput; compact designs are gaining share fastest.
Material:
Cost tiers separate legacy specifications from premium corrosion-resistant alloys, with qualification timelines widening the gap between approved and aspirational suppliers.
- Alloy 690:Thermally treated nickel-chromium alloy delivering superior resistance to primary-side stress-corrosion cracking in borated water chemistry. Replacement steam generator campaigns in the United States and France specify this material exclusively, displacing legacy stainless grades from active procurement lists.
- Titanium:Corrosion-resistant alloy penetrating coastal nuclear installations where secondary-side seawater cooling accelerates degradation. South Korean and Chinese utilities with coastal siting constraints drive adoption.
- S304:Legacy austenitic stainless steel specified in early PWR builds. Decommissioning schedules in Germany and Belgium compress remaining demand.
- S316:Molybdenum-enhanced stainless with improved chloride resistance. Limited to specific secondary-side applications in older fleets.
Alloy 690 commands the premium tier on qualification barriers; titanium is climbing fastest on coastal deployment trends.
End User:
Customer type determines financing structures, with power purchase agreement-backed independent producers displacing traditional state-owned utility procurement authority.
- Utilities:State-owned and investor-owned entities operating nuclear generation assets. Chinese and Indian national utilities dominate new-build procurement volumes.
- Power Plants:Merchant generators and independent power producers securing project finance through long-term offtake contracts. Polish and Czech first-of-a-kind reactor projects exhibit this shift.
- Research Institutions:Universities and national laboratories operating test reactors and materials irradiation facilities. Limited volume, high specification diversity.
- Government Facilities:Naval propulsion and defense-related nuclear programs with classified procurement protocols. US Naval Reactors program maintains separate supply chains.
Utilities retain dominant procurement volumes; power plants are expanding most quickly on PPA-backed project finance.
Application:
Volume concentration in electricity generation contrasts with specialized industrial segments requiring custom thermal-hydraulic configurations.
- Electricity Generation:Primary application driving steam generator specifications, with turbine inlet conditions of 5-7 MPa and dry steam requirements. Chinese, Indian, and South Korean reactor construction timelines concentrate demand.
- Heat Recovery:Cogeneration applications extracting secondary-side thermal energy for district heating or industrial process heat. Russian VVER deployments in Eastern Europe favor this configuration.
- Industrial Processes:Dedicated steam supply for petrochemical and desalination facilities. Saudi Arabia and UAE nuclear programs evaluate these applications.
- Chemical Manufacturing:Specialized high-purity steam requirements for pharmaceutical and specialty chemical production. Niche volume, stringent chemistry controls.
Electricity generation absorbs the dominant share; industrial processes show steepest expansion trajectory on process heat applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean and Chinese fabrication yards while European utilities absorb premium costs from extended qualification timelines. Component procurement authority tilts toward Asia-Pacific suppliers as Western decommissioning schedules compress regional demand. Regulatory divergence between certification regimes widens cost spreads across procurement jurisdictions.
China
China National Nuclear Corporation drives new-build demand through indigenous Hualong One deployments and AP1000 completions. The National Nuclear Safety Administration enforces parallel certification frameworks that restrict market access to pre-qualified fabricators with demonstrated heavy component manufacturing records. Changzhou and Shanghai industrial clusters host specialized tube bundle fabrication facilities serving domestic reactor construction timelines.
United States
Vogtle Unit 3 completion and subsequent AP1000 deployments sustain replacement steam generator procurement for pressurized water reactor fleets. The Nuclear Regulatory Commission enforces 10 CFR Part 50 quality assurance standards governing tube integrity and in-service inspection intervals. Pittsburgh and Charlotte engineering centers concentrate design certification expertise for vendor qualification programs.
South Korea
Doosan Enerbility anchors regional supply through its integrated forging and fabrication complex in Changwon. The Nuclear Safety and Security Commission imposes material certification and welding procedure mandates comparable to Western regulatory frameworks. Changwon's heavy industrial zone concentrates large-diameter shell manufacturing capacity for export markets.
India
The Department of Atomic Energy's indigenous 700 MWe pressurized heavy water reactor program creates specialized demand for horizontal steam generator configurations. The Atomic Energy Regulatory Board operates certification frameworks that extend supplier qualification timelines beyond thirty-six months. Hazira and Mumbai fabrication facilities serve domestic PHWR construction schedules with distinct thermal-hydraulic specifications.
France
Autorité de Sûreté Nucléaire tightened stress-corrosion cracking surveillance requirements through enhanced eddy current testing protocols for plants operating beyond forty years. This regulatory pressure accelerates replacement steam generator procurement for aging French and Belgian PWR fleets. Le Creusot and Saint-Marcel heavy forging facilities concentrate specialized component manufacturing for European utilities.
Nuclear Steam Generator Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower qualification portfolios. The vendor base concentrates around heavy forging capacity holders and nuclear-certified fabricators with demonstrated regulatory track records. Three archetypes dominate: integrated reactor vendors with design certification portfolios, heavy component manufacturers with forging and fabrication complexes, and specialized tube bundle suppliers with alloy-specific welding qualifications. Competitive positioning hinges on dual-qualification cost reduction and factory fabrication economics for modular designs.
Among Asia-Pacific fabricators, Doosan Enerbility and Mitsubishi Heavy Industries occupy positions within the integrated component tier, while Westinghouse Electric Company anchors the platform-integrator segment through its AP1000 design certification portfolio. These entities exemplify the structural divide between reactor vendors bearing system-level performance guarantees and upstream specialists delivering certified subsystems under extended qualification protocols.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises |
| Doosan Enerbility |
| GE-Hitachi Nuclear Energy |
| Larsen & Toubro |
| Japan Steel Works |
| Westinghouse Electric Company |
| China National Nuclear Corporation |
| Bharat Heavy Electricals Limited |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Changwon industrial complex capacity utilization above eighty percent is compressing lead times for large-diameter steam generator shells while elevating pricing power among South Korean fabricators serving replacement campaigns in France and Belgium. This tightness propagates through procurement timelines, forcing utilities to commit to multi-year offtake structures or absorb premium expediting fees.
Pricing Analysis
Configured-to-order pricing for replacement steam generator campaigns commands spreads of thirty to fifty percent above standardized AP1000 unit pricing, reflecting Alloy 690 tube bundle customization and site-specific welding procedure qualification. Three-tier pricing structure across premium, standard, and economy levels separates thermally treated Alloy 690 specifications from legacy S304 grades and titanium coastal variants. Price differentiation hinges on certification tier—NRC 10 CFR Part 50 validation carries material premiums over China's NNSA-only qualification—and volume scale, with four-unit commitments unlocking standard pricing. Cost compression in the economy tier is intensifying because Indian PHWR horizontal designs are fragmenting procurement volumes across smaller batch sizes. State-owned utilities in China and India exhibit lowest price sensitivity, while PPA-backed independent power producers in Poland and the Czech Republic negotiate aggressively on performance guarantee terms.
Supply Chain Analysis
Extended payment terms stretching to twenty-four months post-delivery are becoming standard for first-of-a-kind SMR projects, with supply-chain finance facilities increasingly deployed by South Korean and Japanese heavy forging houses to bridge working capital gaps. Geographic supply concentration rests on South Korea's Changwon complex, Japan's Kobe Steel operations, and China's Changzhou tube bundle clusters. Raw material dependencies draw from nickel-chromium feedstock for Alloy 690, heavy forging ingots from Japan Steel Works, and specialized eddy current testing equipment from French and US suppliers. Single-source vulnerability pervades large-diameter shell manufacturing, where Doosan Enerbility and Mitsubishi Heavy Industries control qualified capacity. Distribution runs through direct utility contracting for replacement campaigns, with EPC-integrated procurement emerging for greenfield AP1000 and SMR deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small modular reactor factory fabrication economics are disrupting traditional site-construction cost structures, with regulatory harmonization between US NRC and South Korean NSSC frameworks poised to compress dual-qualification timelines and unlock cross-border supplier mobility.
For Market Incumbents: Insulate qualified supplier status by accelerating ASME Section IX welding procedure investments for automated narrow-groove Alloy 690 tube-to-tubesheet joints, a capability gap that threatens to disqualify legacy fabricators from replacement campaigns. Deepen backward integration into thermally treated Alloy 690 tube production to capture margin pools currently flowing to specialized metallurgical suppliers. Prioritize Changwon or Kobe Steel capacity reservations for large-diameter shell forging, locking out emerging competitors from qualified heavy component supply. For New Entrants and Emerging Players: Pursue horizontal steam generator specialization for India's 700 MWe PHWR program, where distinct thermal-hydraulic specifications have fragmented procurement away from entrenched PWR supply chains. Target titanium tube bundle fabrication for coastal nuclear installations in South Korea and China, a penetration point where corrosion-resistant specifications outpace incumbent Alloy 690 capacity. Deploy joint venture structures with established heavy forging houses to bypass thirty-six-month qualification timelines imposed by India's AERB and China's NNSA. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across SMR compact steam generator manufacturing, where factory fabrication automation and modular assembly lines demand front-loaded equipment investment before revenue recognition. Long-term viability over the next decade favors fabricators with dual NRC-NSSC qualification pathways and demonstrated heavy component track records. Acquisition targets should display alloy-specific welding certifications and established regulatory dossiers. The signal to monitor is progress on 10 CFR Part 50 harmonization with Asian certification regimes, which would revalue qualified supplier portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Alloy 690 Welding Automation Investment | ASME Section IX compliance for tube-to-tubesheet joints secures replacement campaign eligibility against narrow-groove equipment scarcity. |
| Dual NRC-NSSC Qualification Pathway | Harmonization progress reduces pre-qualification costs for suppliers serving both US and South Korean reactor construction timelines. |
| SMR Factory Fabrication Scale-Up | NuScale and Rolls-Royce compact designs collapse nuclear-conventional island boundaries, reshaping supplier tier structures. |
| Titanium Tube Bundle Capacity Addition | Coastal siting constraints in South Korea and China accelerate corrosion-resistant specifications beyond incumbent Alloy 690 focus. |
| PHWR Horizontal Design Specialization | India's indigenous 700 MWe program creates procurement channels distinct from Western PWR supply chain concentration. |
Methodological Framework
The analysis maps vertical, horizontal, modular, and compact steam generator configurations, each validated through utility procurement officers, EPC contractor engineering leads, heavy component fabrication managers, and regulatory affairs specialists at national safety administrations. Primary interviews with reactor vendor platform engineers and NSSC certification auditors combined with secondary validation from NRC 10 CFR Part 50 filings, ASN surveillance protocol updates, IEA nuclear generation databases, and customs records for heavy forging equipment trade. Bottom-up unit economics for tube bundle and shell fabrication triangulated against top-down market sizing from reactor construction timelines and replacement campaign schedules.
Fixed assumptions across the projection horizon include sustained regulatory divergence between Western and Asian certification regimes, continued Alloy 690 displacement of legacy stainless grades, and SMR factory fabrication economics achieving cost parity with site construction. Segmentation dimensions modeled encompass product type, material specification, end-user financing structure, and application thermal-hydraulic configuration. CAGRs derive from reactor fleet expansion schedules, decommissioning timelines, and replacement steam generator procurement patterns. Industry-specific inputs include eddy current testing interval mandates from France's ASN and the US NRC, plus AP1000 design certification portability across jurisdictions.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting project finance structures or commodity price volatility for nickel-chromium feedstock would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress, qualification timeline stability, and SMR commercialization schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Thorium Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Global Nuclear Reactor Construction Market