
 Helium-3 Market | 2026-2036
Helium-3 Market Size, Share, and Industry Trends Forecast 2026-2036
Helium-3 Market Outlook
Buyer concentration around government fusion agencies and national laboratories is hardening across the helium-3 procurement landscape. Rosatom sustains vertical integration from tritium decay production through isotope enrichment, giving it captive supply control. Air Liquide SA leverages cryogenic logistics networks to dominate distribution into European research institutions. Linde Plc anchors North American supply through long-term isotope management contracts with the US Department of Energy.
Helium-3 is a rare stable isotope of helium with one neutron and two protons, distinguished by an ultra-low boiling point of 3.2 Kelvin and pronounced superfluid properties below 2.5 millikelvin, which make it indispensable for dilution refrigeration and neutron detection systems. Nuclear fusion applications command the largest share of current demand as tokamak and stellarator programs consume bulk isotope supplies for plasma fueling experiments. Neutron detection represents the fastest-expanding application segment, driven by homeland security screening upgrades and non-proliferation monitoring protocols. Raw Helium-3 commands premium pricing relative to blended mixtures due to purification complexity and stockpile scarcity.
The US Nuclear Regulatory Commission and Department of Energy jointly govern isotope allocation, export licensing, and strategic reserve thresholds, while the International Atomic Energy Agency coordinates safeguards compliance for cross-border helium-3 transfers. The European Union's F-Gas Regulation and REACH framework impose reporting obligations and usage restrictions that constrain cryogenic application expansion. Stakeholders must monitor regulatory stockpile release schedules against fusion project commissioning timelines to anticipate supply-demand imbalances.
Market Dynamics
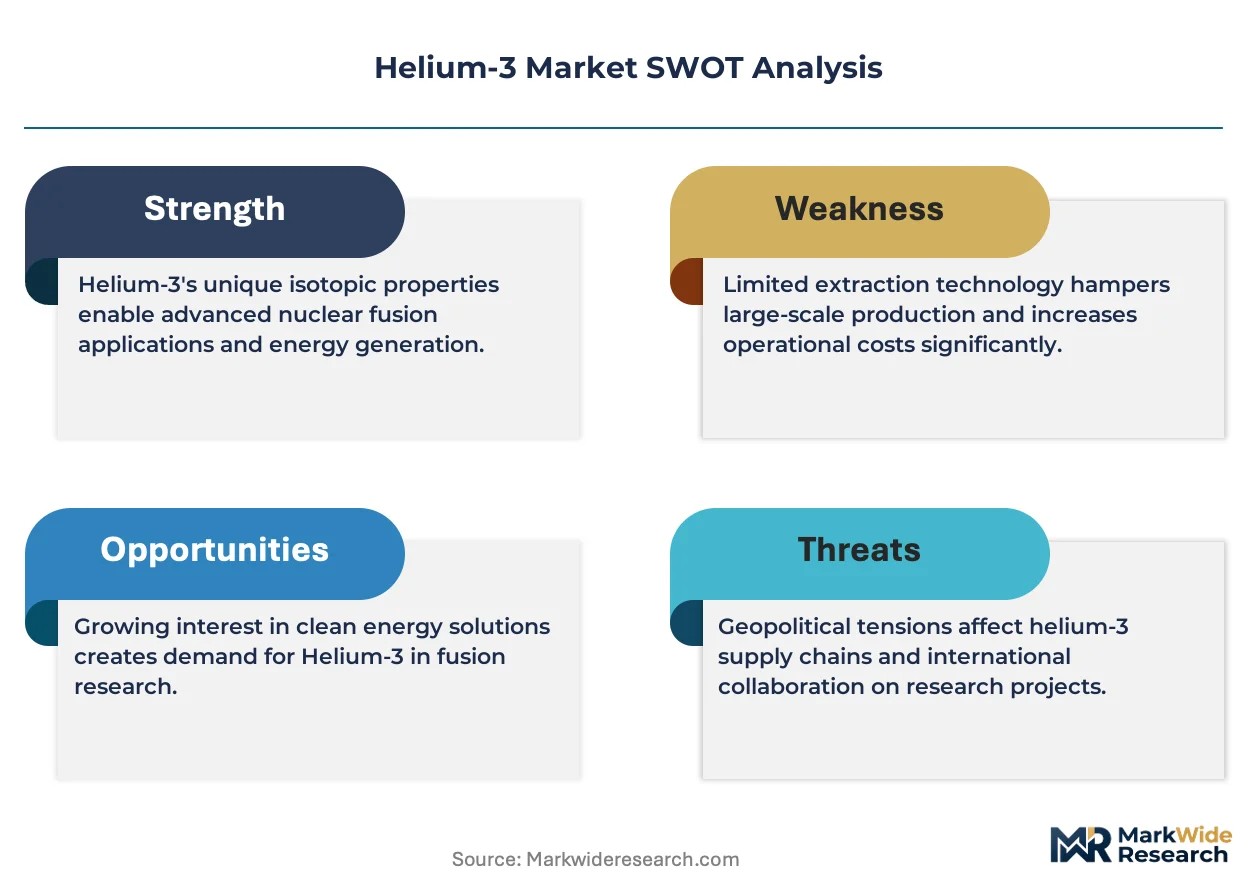
Fusion research programs are consolidating procurement power around national laboratories, compressing supplier margins while amplifying spot price volatility for non-contracted volumes.
Growth Catalysts
- ITER Procurement Commitments:The international tokamak project is locking in multi-year helium-3 supply agreements, validating demand visibility for producers.
- EU F-Gas Regulation Phase-Down:Restrictions on conventional refrigerants are accelerating dilution refrigerator upgrades that require helium-3 superfluid cooling systems.
- Homeland Security Screening Mandates:Radiation portal monitor deployments at border crossings and ports are expanding neutron detection hardware consumption.
Market Restraints
- Tritium Decay Supply Concentration:Over 80% of helium-3 derives from aging nuclear weapons stockpile tritium, creating single-source dependency on government release schedules.
- Purification Cost Escalation:Isotope separation from natural helium or nuclear byproducts requires cryogenic distillation infrastructure with 24-36 month commissioning timelines.
- Helium-4 Substitution in Cryogenics:Research institutions are retrofitting systems to operate at higher temperatures where standard helium-4 suffices, capping premium isotope demand growth.
Strategic Opportunities
- Lunar Regolith Extraction:China's Chang'e sample return missions and NASA Artemis planning are validating in-situ helium-3 production concepts for 2040+ supply diversification.
- Quantum Computing Cryogenics:Superconducting qubit architectures require millikelvin operating temperatures that only helium-3 dilution refrigerators can sustain reliably.
- India PLI Scheme for Isotopes:Production-linked incentives for domestic nuclear materials processing are attracting enrichment joint ventures with foreign technology partners.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Dilution refrigerator design and maintenance requires specialized expertise concentrated at fewer than a dozen global institutions.
- IAEA Safeguards Certification Delays:Cross-border helium-3 transfers face 6-12 month licensing reviews that disrupt just-in-time supply chains for research programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helium-3 Market |
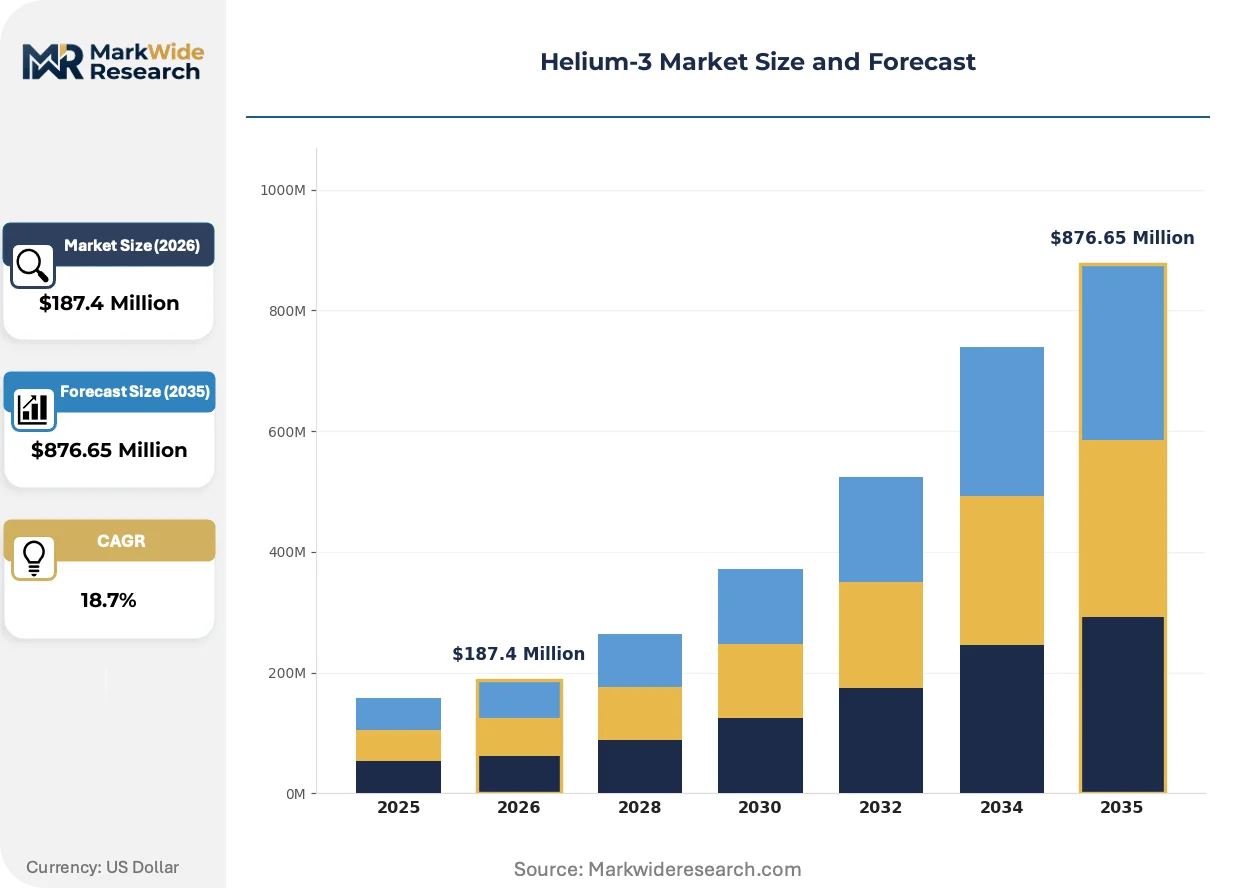
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Helium-3, Helium-3 Mixtures, Cryogenic Helium-3, Advanced Propellant Application: Nuclear Fusion, Medical Imaging, Cryogenics, Neutron Detection End User: Government Agencies, Research Institutions, Healthcare Facilities, Industrial Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | Messer SE and Co. KGaA, Rosatom, Air Liquide SA, PJSC Gazprom, Chemgas Shipping GmbH, Air Products and Chemicals Inc, Iwatani Corp., Raims, Ltd., Linde Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helium-3 Market Strategic Shifts
Helium-3 markets are experiencing a technology pivot where supply security concerns are accelerating investment in alternative production pathways and demand-side efficiency improvements.
Closed-cycle dilution refrigeration is unifying neutron detection and quantum computing cooling architectures around recoverable helium-3 systems. National laboratories in Germany and Japan are retrofitting static consumption models with gas recovery loops that recapture 90% of isotope inventory. This technology compression is extending effective supply by reducing per-experiment consumption rates without sacrificing cooling performance.
The US Department of Energy's Isotope Program has formalized strategic reserve release protocols that prioritize domestic fusion research over export sales. This policy tightening follows Congressional directives to reduce foreign dependency for critical isotopes. European research institutions are responding by accelerating consortia negotiations with Rosatom-affiliated suppliers despite geopolitical friction.
Long-term contracting is displacing spot market purchases as national fusion agencies secure 10-year supply agreements with fixed escalation clauses. This procurement compression is marginalizing smaller research programs that lack volume commitments to qualify for tier-one pricing. The shift is most pronounced in North America, where the DOE acts as central purchasing agent for university and national laboratory demand.
Helium-3 Market Segmentation
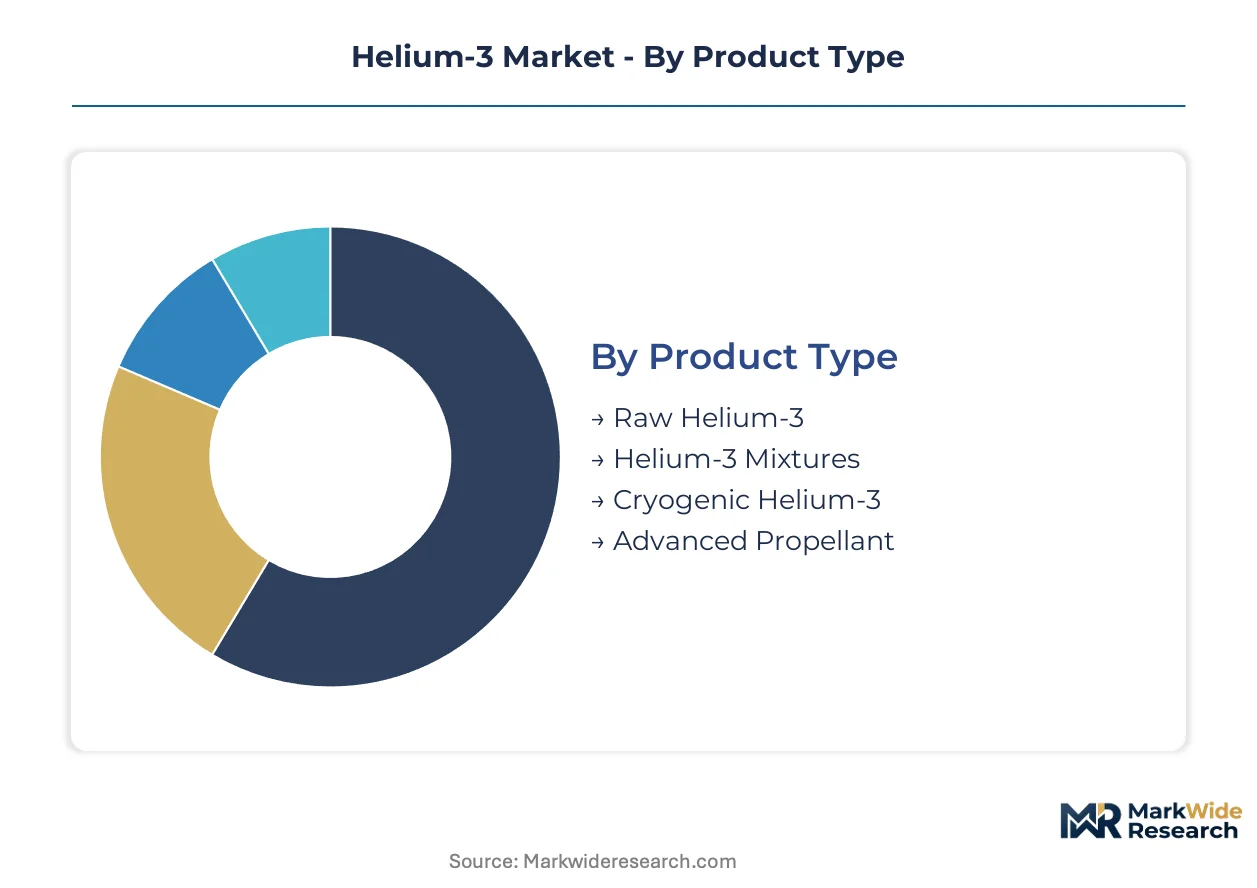
Helium-3 procurement patterns diverge sharply across product grades and end-use specifications, with fusion research programs demanding ultra-high purity while security applications tolerate blended formulations. Understanding these segment boundaries clarifies where supply constraints bite hardest and where substitution risks emerge.
Product Type:
Upgrade cycles in dilution refrigeration and neutron detection hardware are forcing institutions to reassess which helium-3 grade matches their thermal performance requirements against budget constraints.
- Raw Helium-3:Ultra-pure isotope exceeding 99.9% concentration, produced through cryogenic distillation of tritium decay stockpiles. National fusion laboratories in the United States and Germany command priority allocation for tokamak fueling experiments, with supply rationing intensifying as weapons stockpile tritium ages.
- Helium-3 Mixtures:Blended formulations with helium-4 or other carrier gases, reducing unit costs for large-volume neutron detection deployments. Homeland Security screening mandates at US ports of entry are accelerating procurement of mixed-isotope detectors that balance sensitivity against procurement budgets.
- Cryogenic Helium-3:Pre-conditioned for immediate dilution refrigerator charging, eliminating on-site purification steps. Research institutions in Japan and Switzerland favor this format to bypass cryogenic engineering talent shortages.
- Advanced Propellant:Specialized formulations for proposed nuclear thermal propulsion concepts. NASA and CNSA mission planning groups are evaluating helium-3 variants for deep-space thrust applications, though commercial demand remains nascent.
Raw Helium-3 sits at the top of the volume ranking, with Cryogenic Helium-3 climbing the fastest as institutions prioritize operational simplicity.
Application:
Cost tier differentiation separates mission-critical fusion investments from commoditized security hardware, with middle-tier cryogenics facing the strongest substitution pressure.
- Nuclear Fusion:Plasma fueling for tokamak and stellarator confinement experiments, consuming bulk isotope supplies in single experimental campaigns. ITER procurement commitments are locking in decade-long supply agreements that validate producer investment in purification capacity.
- Neutron Detection:Radiation portal monitors and non-proliferation verification equipment, representing the application category gaining share fastest. EU border agencies and US Customs are deploying helium-3-based systems to meet enhanced screening protocols for cargo containers.
- Cryogenics:Millikelvin cooling for quantum computing substrates and condensed matter physics. Google Quantum AI and IBM Research facilities are installing dilution refrigerators that specify helium-3 superfluid properties below 2.5 millikelvin.
- Medical Imaging:Specialized magnetic resonance applications and polarized gas lung imaging. University hospital networks in the United Kingdom and Canada maintain limited procurement for research-grade pulmonary diagnostics.
Nuclear Fusion commands the largest committed expenditure, while Neutron Detection exhibits the steepest expansion trajectory as security infrastructure upgrades proliferate.
End User:
Customer type determines contract structure, with government purchasers leveraging sovereign bargaining power against spot-market exposure faced by smaller research programs.
- Government Agencies:National laboratories and defense departments operating under strategic reserve allocation protocols. The US Department of Energy centralizes purchasing for domestic fusion research, compressing supplier margins through volume aggregation.
- Research Institutions:University physics departments and materials science centers with fragmented, small-lot procurement needs. German Max Planck Institutes and Japanese RIKEN facilities are consortiating orders to qualify for tier-one pricing.
- Healthcare Facilities:Specialized imaging centers with intermittent, low-volume requirements. Canadian hospital networks are exploring helium-3 polarized gas alternatives to xenon-129 for cost-sensitive lung ventilation studies.
- Industrial Manufacturers:Semiconductor metrology equipment builders and cryogenic system integrators. Air Liquide and Linde maintain dedicated supply contracts with industrial end users for calibrated mixture formulations.
Government Agencies anchor procurement volume, with Research Institutions gaining negotiating leverage through collective purchasing arrangements.
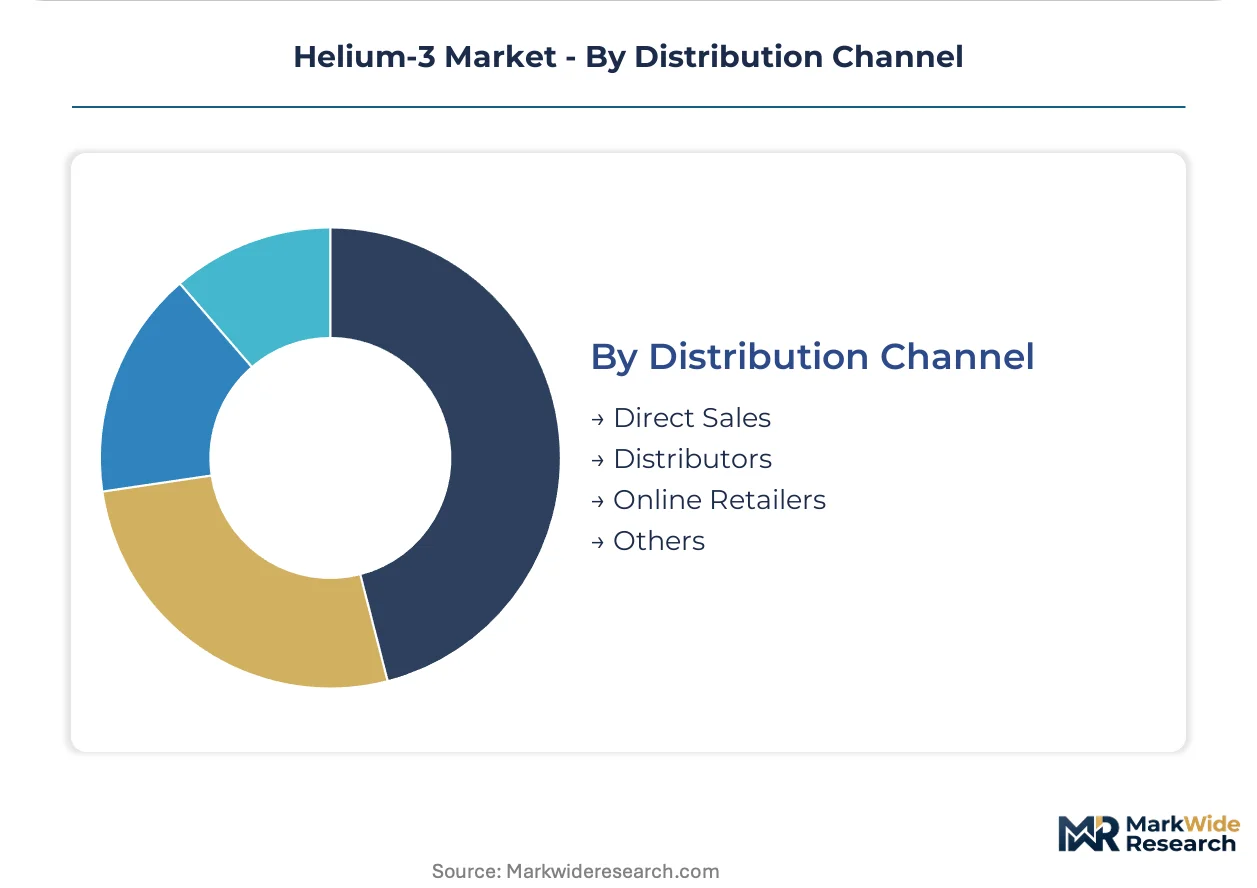
Distribution Channel:
Supply chain configuration determines delivery reliability for time-sensitive isotope transfers, with direct relationships prized for strategic programs and distributor networks filling geographic gaps.
- Direct Sales:Long-term isotope management contracts between producers and national laboratories. Rosatom and the US Department of Energy operate bilateral agreements that bypass intermediaries for tritium-derived supply.
- Distributors:Specialized cryogenic gas handlers with IAEA safeguards certification for cross-border transfers. Air Liquide's European logistics network manages inventory pooling for research consortia across France, Germany, and Switzerland.
- Online Retailers:Limited to standard helium-4 products and accessories; helium-3 isotope sales require export licensing incompatible with e-commerce platforms.
- Others:Brokered spot market transactions for emergency replenishment, subject to IAEA review delays of 6-12 months that disrupt just-in-time supply chains.
Direct Sales handles the majority of committed volume, with Distributors expanding fastest as European institutions seek supply diversification beyond bilateral government channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Russia operate contrasting supply architectures for helium-3, with Washington centralizing procurement through federal stockpile management while Moscow leverages captive tritium decay production. Germany and Japan pursue supply diversification through research consortia, while China advances lunar extraction concepts. India is attracting enrichment joint ventures through production-linked incentives.
United States
The Department of Energy anchors domestic helium-3 allocation through strategic reserve release protocols that prioritize national fusion programs over export sales. The Nuclear Regulatory Commission governs isotope licensing alongside the DOE, creating dual-agency oversight for cross-border transfers. National laboratories in California and New Mexico concentrate tokamak fueling experiments that consume bulk isotope inventories.
Russia
Rosatom sustains vertical integration from tritium decay production through isotope enrichment, granting Moscow captive supply control independent of Western stockpiles. The state atomic energy corporation operates under federal strategic materials regulations that classify helium-3 as a controlled export commodity. Siberian nuclear facilities anchor tritium storage and decay extraction operations that feed European research demand through bilateral contracts.
Germany
Max Planck Institutes consortiate procurement orders to qualify for tier-one pricing as domestic fusion research expands stellarator programs. The EU F-Gas Regulation imposes reporting obligations and usage restrictions that constrain cryogenic application expansion while accelerating dilution refrigerator upgrades. Research clusters in Bavaria and North Rhine-Westphalia retrofit static consumption models with gas recovery loops that recapture isotope inventory.
Japan
RIKEN facilities and university physics departments aggregate demand through collective purchasing arrangements to bypass fragmented small-lot procurement disadvantages. METI coordinates national isotope strategy under Japan's critical materials security framework. Tokyo and Osaka metropolitan areas concentrate quantum computing cryogenics installations requiring millikelvin helium-3 dilution refrigerators.
China
Chang'e sample return missions validate in-situ helium-3 production concepts from lunar regolith for 2040-plus supply diversification. The national space administration coordinates with atomic energy authorities under dual-use materials regulations governing isotope research. Beijing-Tianjin-Hebei research corridors anchor fusion energy institutes advancing tokamak plasma fueling experiments.
Helium-3 Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across helium-3 supply chains, creating a tiered structure where scale advantages concentrate in hands with cryogenic logistics networks. Industrial gas majors leverage existing distribution infrastructure while nuclear materials handlers control upstream tritium decay feedstocks. Strategic archetypes include stockpile-integrated government contractors, cryogenic logistics specialists, and research-facing isotope distributors. Capacity expansion and strategic partnerships dominate competitive moves as producers secure long-term offtake agreements with national fusion agencies.
Among industrial gas conglomerates, Air Liquide SA and Linde Plc exemplify the logistics-anchored archetype through cryogenic distribution networks serving European and North American research institutions respectively. Rosatom occupies a distinct position as a state-integrated vertical supplier controlling tritium decay production from weapons stockpile management through isotope enrichment. These three entities represent the primary competitive poles: commercial gas majors with research channel penetration, state atomic energy corporations with captive feedstock control, and specialized isotope handlers bridging procurement gaps for smaller programs.
| Leading Market Players |
|---|
| Messer SE and Co. KGaA |
| Rosatom |
| Air Liquide SA |
| PJSC Gazprom |
| Chemgas Shipping GmbH |
| Air Products and Chemicals Inc |
| Iwatani Corp. |
| Raims, Ltd. |
| Linde Plc |
| Others |
Value Chain & Pricing Dynamics
Cryogenic distillation energy costs cascade through helium-3 pricing tiers, with tritium decay stockpile scarcity in the United States and Russia amplifying premiums for ultra-pure grades demanded by ITER and national tokamak programs. Government release schedules function as the dominant price-setting mechanism, compressing margins for non-contracted spot volumes while fixed-escalation long-term agreements anchor tier-one procurement.
Pricing Analysis
Capacity additions in Russia are reshaping price floors for European research institutions seeking supply diversification beyond bilateral DOE channels. Contract-based long-term offtake dominates, with price differentiation driven by isotope purity grade and IAEA safeguards certification tier. Cost compression in blended helium-3 mixtures is intensifying because homeland security agencies prioritize sensitivity-per-dollar metrics over raw isotope concentration. Government fusion laboratories exhibit least price sensitivity, while fragmented university physics departments face acute budget constraints.
Supply Chain Analysis
IAEA safeguards certification gates cross-border transfers, creating 6-12 month licensing reviews that disrupt just-in-time research supply chains. Production concentrates in the United States, Russia, and China, with raw material dependencies on aging weapons stockpile tritium, cryogenic distillation infrastructure, and specialized dilution refrigerator charging equipment. Single-source vulnerability around government release schedules represents the dominant structural risk. Distribution runs through direct bilateral agreements for strategic programs, with specialized cryogenic gas handlers filling geographic gaps for smaller European and Japanese research consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The helium-3 market functions as a regulatory compounder, with the EU F-Gas Regulation phase-down accelerating dilution refrigerator upgrades that lock in decade-long superfluid cooling demand.
For Market Incumbents: Cement captive tritium decay supply through long-term isotope management contracts with the US Department of Energy and Rosatom, insulating against IAEA safeguards certification delays that disrupt competitor logistics. Deepen backward integration into cryogenic distillation infrastructure to bypass 24-36 month commissioning bottlenecks that constrain rival capacity additions. Prioritize gas recovery loop technology deployment to extend effective supply and defend margin position against closed-cycle system retrofits. For New Entrants and Emerging Players: The EU F-Gas Regulation opens a window for specialized cryogenic helium-3 pre-conditioning services targeting Japanese and Swiss research institutions facing acute engineering talent shortages. Target consortiated procurement orders from German Max Planck Institutes and RIKEN facilities seeking tier-one pricing leverage through collective purchasing. Pursue joint venture structures with Indian production-linked incentive schemes for domestic nuclear materials processing. For Investors and Strategic Acquirers: Roll-up economics work for cryogenic logistics specialists because IAEA safeguards certification scarcity creates durable moats around cross-border distribution capabilities. Five-to-ten year viability hinges on lunar regolith extraction technology maturation and quantum computing cryogenics demand expansion. Watch for DOE strategic reserve release protocol tightening as the primary inflection signal for supply-constrained pricing environments.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Isotope Supply Agreement | ITER procurement commitments validate decade-long demand visibility for purification capacity investments. |
| Gas Recovery Loop Deployment | German national laboratories recapture 90% of helium-3 inventory, extending effective supply. |
| IAEA Safeguards Certification Investment | Air Liquide's European logistics network manages inventory pooling across France, Germany, and Switzerland. |
| Lunar Extraction Technology Partnership | China's Chang'e missions validate in-situ production concepts for 2040-plus supply diversification. |
| Cryogenic Engineering Talent Development | Japan's METI coordinates national isotope strategy under critical materials security framework. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged cryogenic engineering directors, national laboratory procurement officers, IAEA safeguards specialists, and dilution refrigerator maintenance technicians. Secondary sources included DOE isotope program disclosures, Rosatom strategic materials regulations, EU F-Gas compliance filings, and customs trade data. Bottom-up demand aggregation from fusion research programs and top-down supply assessment from tritium decay stockpiles were triangulated.
Rate-of-change decomposition across the analysis window separated volume growth from price escalation effects. Segmentation dimensions modeled include isotope grade tier, application category, end-user type, and regional regulatory cluster. CAGRs were derived from procurement commitment timelines against purification capacity commissioning schedules. Forecast inputs incorporated ITER milestone schedules and quantum computing facility buildout trajectories.
Revisions become necessary when DOE strategic reserve release protocols tighten or lunar extraction technology demonstrations accelerate. Forecasts reflect assumptions about tritium stockpile aging rates and cryogenic engineering talent pipeline constraints. A model refresh is warranted upon material change in IAEA safeguards certification processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Reactor Construction Market