
 Europe Nuclear Reactor Decommissioning Market | 2026-2036
Europe Nuclear Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuclear Reactor Decommissioning Market Foresight
The EU Green Deal and the F-Gas Regulation is repositioning decommissioning from deferred liability to active infrastructure priority across European utilities. Orano leverages its integrated fuel cycle capabilities to anchor long-term waste management contracts in France. Babcock International Group PLC sustains reactor dismantling expertise through specialized engineering teams focused on graphite-moderated gas-cooled reactors in the United Kingdom. Studsvik AB competes in the Nordic region by concentrating on decontamination technologies and radioactive waste treatment services.
Nuclear reactor decommissioning encompasses the engineered dismantlement of irradiated structures, systems, and components following permanent reactor shutdown, requiring remote handling tools, shielded containment, and radiological characterization to achieve site release criteria. The primary purpose is to eliminate radiation hazards and restore land for unrestricted use or alternative industrial deployment. Waste Management commands structural priority within service type segmentation because spent fuel conditioning and intermediate-level waste conditioning absorb the majority of program budgets over thirty-year horizons. Pressurized Water Reactor decommissioning dominates reactor type demand owing to the installed fleet concentration in France, while Site Restoration represents the emerging margin pool as regulators tighten final status survey requirements.
The European Nuclear Safety Regulators Group and the Euratom Waste Directive shape decommissioning standards across member states, with national regulators such as the French Nuclear Safety Authority and Germany's Federal Office for the Safety of Nuclear Waste Management enforcing site-specific licensing conditions. REACH and the EU Green Deal's sustainable finance taxonomy increasingly channel capital toward certified low-carbon decommissioning methodologies. Stakeholders must monitor evolving waste disposal site availability and national funding assurance mechanisms to secure program continuity across multi-decade dismantling schedules.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing decommissioning timelines across European utilities, transforming deferred liabilities into immediate capital allocation priorities. France, Germany, and the United Kingdom now face simultaneous reactor end-of-life waves requiring coordinated dismantling capacity.
Growth Catalysts
- Aging reactor fleets:Pressurized water and boiling water reactors installed during the 1970s-1980s expansion are reaching 40-50 year operational limits. Utilities in France and Germany must activate decommissioning protocols.
- EU Green Deal capital redirection:The sustainable finance taxonomy classifies certified decommissioning as eligible green expenditure. Institutional investors channel funds toward waste management and site restoration programs.
- Radioactive waste conditioning demand:Spent fuel pools and intermediate-level waste vaults require immediate processing. Orano and specialized contractors secure multi-decade conditioning contracts.
Market Restraints
- Deep geological repository uncertainty:Finland's Onkalo facility remains the only licensed spent fuel repository in Europe. Germany's Konrad mine and France's Cigéo project face decade-long licensing delays.
- Specialized labor scarcity:Radiological engineers, remote handling technicians, and shielded containment specialists require 8-12 year training pipelines. France's INSTN and Germany's GRS training centers operate at capacity.
- Long-duration cost inflation:Decommissioning programs span 20-30 years. Fixed-price contracts expose contractors to wage and material cost volatility across multi-decade horizons.
Strategic Opportunities
- Eastern European expansion:Bulgaria's Kozloduy and Slovakia's Bohunice reactors require staged dismantling. These markets lack indigenous decommissioning capacity and import French and German expertise.
- Site restoration specialization:Final status survey requirements are tightening under the European Nuclear Safety Regulators Group guidelines. Contractors developing radiological characterization capabilities capture premium margins.
- Robotics and remote tooling convergence:Underwater cutting lasers and teleoperated manipulators reduce worker exposure. Swedish and Finnish utilities pilot autonomous segmentation systems for reactor pressure vessels.
Industry Challenges
- Intergenerational funding assurance:German utilities E.ON and RWE transferred decommissioning liabilities to state-managed funds. Provisions must cover 30-year dismantling schedules plus centuries of waste storage.
- Graphite-moderated reactor complexity:United Kingdom's Magnox and Advanced Gas-Cooled Reactor fleets contain irradiated graphite cores. Windscale Pile 1 decommissioning demonstrates 50-year timelines for this reactor class.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuclear Reactor Decommissioning Market |
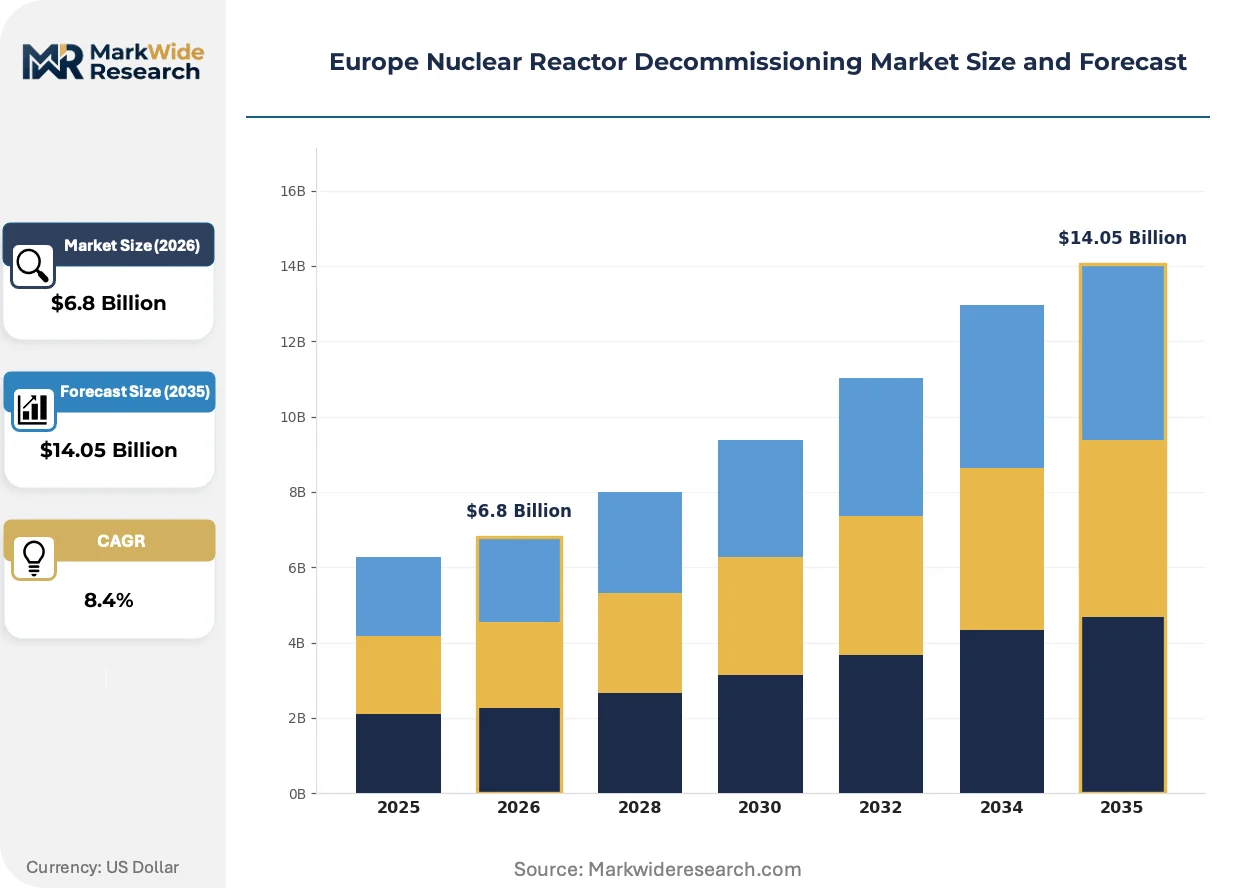
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Decontamination, Dismantling, Waste Management, Site Restoration Reactors Type: Pressurized Water Reactor, Boiling Water Reactor, Gas-Cooled Reactor, Fast Neutron Reactor Stage: Planning, Implementation, Post-Decommissioning, Monitoring Client Type: Government, Utility Company, Contractors, Research Institutions |
| Companies Covered | Cavendish Nuclear Ltd, Electricite de France SA, Babcock International Group PLC, Orano, Studsvik AB, Fluor Corporation, GE Hitachi Nuclear Services, AECOM, Westinghouse Electric Company LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuclear Reactor Decommissioning Market Shifts & Advancements
Remote handling technologies and digital twin modeling are compressing decommissioning schedules while reducing worker radiation exposure. European regulators are mandating stricter final status documentation.
Underwater plasma arc cutting systems are automating reactor pressure vessel segmentation. EDF deploys these tools at the Brennilis and Chooz-A sites, reducing segmentation time from 18 months to 7 months. The technology is automating labor-intensive dismantling phases previously requiring manual thermal cutting.
The EU F-Gas Regulation and national phase-out laws are accelerating reactor closure schedules. Germany's AtG amendment forced immediate shutdown of three remaining nuclear plants in April 2023. French utilities are responding by pre-positioning dismantling contracts before ASN licensing deadlines.
Utility procurement teams are unbundling engineering-procurement-construction contracts into specialized service packages. EDF and Vattenfall now separately tender radiological characterization, waste conditioning, and site restoration phases. This fragmentation is most visible in France, where Orano, Onet Technologies, and Assystem compete for discrete work packages rather than integrated programs.
Europe Nuclear Reactor Decommissioning Market Segmentation
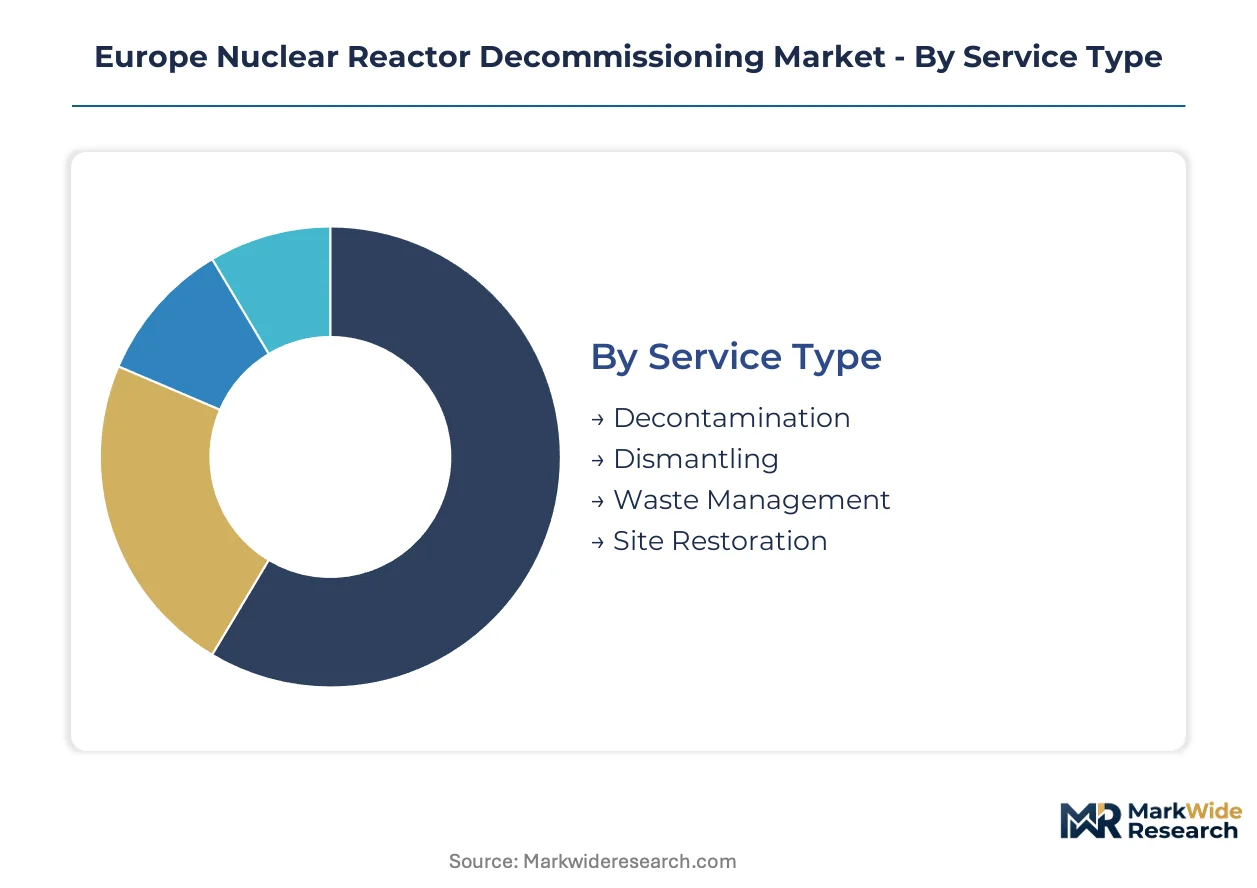
Decommissioning programs fragment into specialized service packages as European utilities unbundle multi-decade contracts. Procurement teams now tender discrete phases separately, reshaping contractor competitive dynamics across France, Germany, and the United Kingdom.
Service Type:
Buyers prioritize budget absorption capacity over technical novelty, with multi-decade waste liability driving contract structures.
- Waste Management:Spent fuel conditioning and intermediate-level waste vault processing consume the majority of program budgets across thirty-year horizons. Demand concentrates in France and Germany where the largest irradiated fuel inventories require immediate packaging for interim storage.
- Dismantling:Engineered segmentation of reactor pressure vessels, steam generators, and biological shields employs remote plasma arc cutting and underwater abrasive waterjet systems. The United Kingdom's graphite-moderated gas-cooled reactor fleet demands specialized thermal segmentation techniques extending timelines to fifty years.
- Decontamination:Chemical and mechanical surface treatment of irradiated structures reduces radiological classification for material release.
- Site Restoration:Final status surveys and land remediation for unrestricted use or industrial redeployment.
Waste Management leads volumes today; Site Restoration is gaining share fastest.
Reactor Type:
Installed fleet concentration determines geographic demand distribution, with pressurized water reactor density in France creating procurement gravity.
- Pressurized Water Reactor:Dominant European fleet type with standardized containment designs enabling modular dismantling approaches. France's EDF operates the continent's largest installed base requiring staged decommissioning across multiple sites simultaneously.
- Gas-Cooled Reactor:Irradiated graphite core management defines decommissioning complexity for the United Kingdom's Magnox and Advanced Gas-Cooled Reactor fleets. Graphite waste volume and tritium inventory extend programs across intergenerational timelines with uncertain disposal routes.
- Boiling Water Reactor:German and Swedish utilities operate compact units with integrated containment structures requiring specialized segmentation sequencing.
- Fast Neutron Reactor:Limited commercial deployment with sodium coolant handling requirements creating unique decommissioning protocols.
Pressurized Water Reactor commands current volumes; Gas-Cooled Reactor programs are expanding most quickly.
Stage:
Regulatory licensing phases segment buyer procurement timing, with implementation contracts awarded only after exhaustive characterization.
- Implementation:Physical dismantling, waste conditioning, and active decommissioning operations constitute the capital-intensive execution phase. French and German regulators enforce staged licensing with hold points between major dismantling campaigns.
- Planning:Characterization, option studies, and licensing documentation preparation absorbing five to ten years pre-shutdown.
- Post-Decommissioning:Institutional control periods and restricted site use pending final repository availability.
- Monitoring:Long-term surveillance of residual contamination and engineered barrier performance.
Implementation drives current contract value; Planning is climbing the fastest as utilities accelerate pre-positioning.
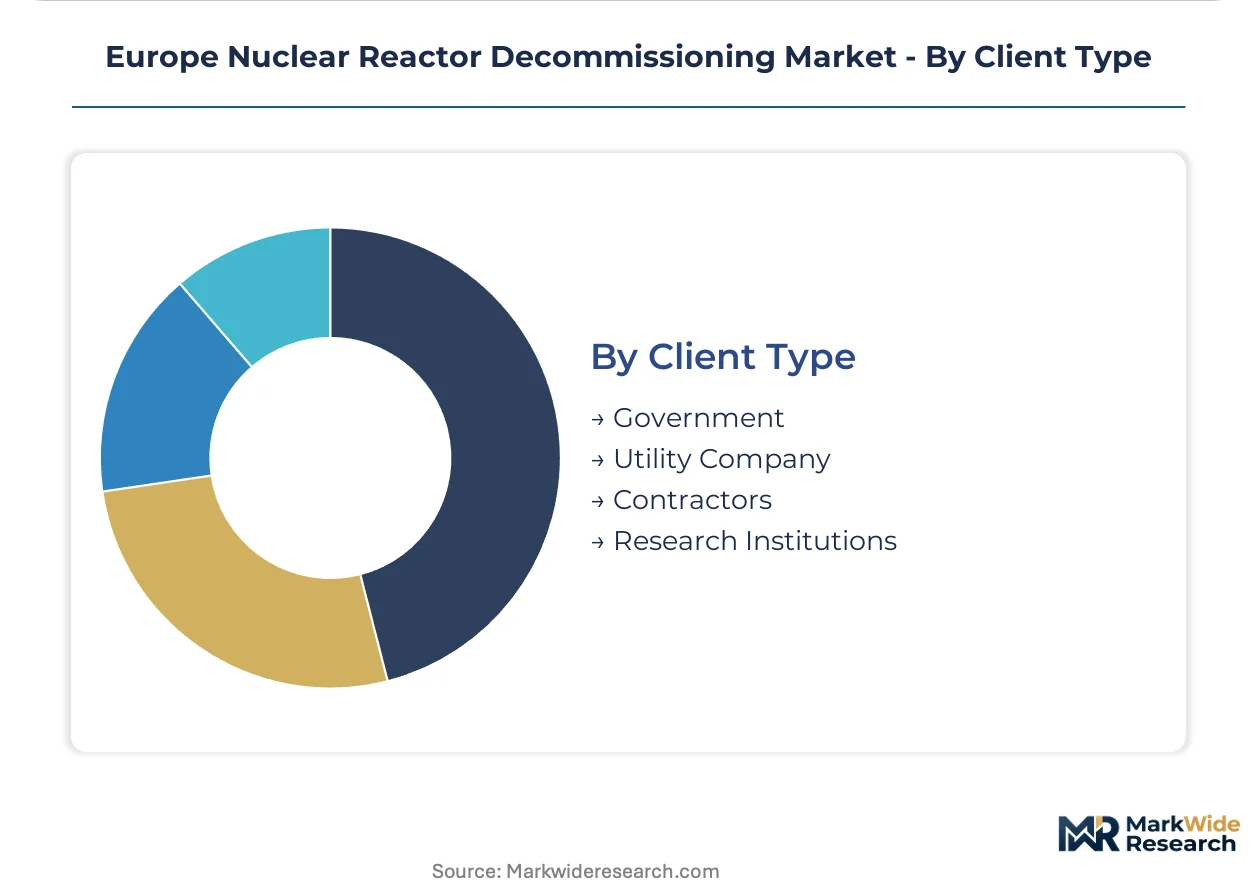
Client Type:
Liability ownership structures determine procurement authority, with state-mandated fund transfers reshaping buyer composition in Germany.
- Utility Company:EDF, Vattenfall, and remaining private operators retain direct procurement responsibility for reactor dismantling. German utilities transferred waste management liabilities to state funds while retaining operational decommissioning contracts.
- Government:State-owned decommissioning funds and national waste management organizations in Germany and Sweden now control major procurement decisions.
- Contractors:Tier-one engineering firms subcontracting specialized radiological services to regional specialists.
- Research Institutions:Limited procurement for prototype and experimental reactor dismantling.
Utility Company retains dominant procurement volume; Government entities are capturing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiological engineers and remote handling specialists cluster around legacy reactor sites in France, Germany, and the United Kingdom. These workforce concentrations anchor procurement decisions and shape dismantling timelines across national programs.
France
EDF operates the continent's largest pressurized water reactor fleet with simultaneous decommissioning campaigns at Brennilis, Chooz-A, and Bugey. The French Nuclear Safety Authority enforces staged licensing with hold points between major dismantling phases. Orano's fuel cycle complex at La Hague and engineering clusters around Paris anchor waste conditioning and characterization services.
Germany
E.ON, RWE, and EnBW transferred decommissioning liabilities to state-managed funds following the AtG amendment that forced immediate shutdown of remaining nuclear plants in April 2023. The Federal Office for the Safety of Nuclear Waste Management oversees Konrad mine licensing for low-level waste disposal. GRS training centers in Cologne and Munich operate at capacity developing radiological specialists.
United Kingdom
Magnox and Advanced Gas-Cooled Reactor decommissioning dominates procurement with graphite core management extending programs across fifty-year horizons. The Nuclear Decommissioning Authority manages site license companies at Sellafield and Dounreay. Babcock International sustains specialized engineering teams focused on graphite-moderated reactor complexity.
Sweden
Vattenfall and Fortum operate compact boiling water reactor units requiring integrated containment segmentation sequencing. The Swedish Radiation Safety Authority mandates stricter final status documentation under evolving guidelines. Studsvik AB concentrates decontamination technologies and radioactive waste treatment services at its Nyköping facility.
Finland
TVO and Fortum advance decommissioning planning with regulatory precedents set by Onkalo, the continent's only licensed spent fuel repository. The Radiation and Nuclear Safety Authority positions Finland as a testbed for autonomous segmentation systems. Remote tooling pilots at Olkiluoto reduce worker exposure through teleoperated manipulators for reactor pressure vessel dismantling.
Europe Nuclear Reactor Decommissioning Market Competitive Landscape
Capital-heavy integrated service providers compete with asset-light specialized engineering firms for discrete work packages across European decommissioning programs. The vendor base organizes around three tiers: full-cycle contractors managing waste conditioning through site restoration, technology specialists delivering radiological characterization and remote tooling, and regional engineering houses capturing localized dismantling contracts. Two competitive moves dominate: unbundling of engineering-procurement-construction contracts into specialized service packages, and pre-positioning dismantling contracts before regulatory licensing deadlines compress procurement windows.
Within the integrated service tier, Orano and Babcock International Group PLC exemplify contrasting geographic anchors—French fuel cycle integration versus United Kingdom graphite reactor expertise. Studsvik AB occupies a position among Nordic technology specialists concentrating decontamination and waste treatment capabilities. These three entities represent archetypes visible across the competitive landscape: vertically integrated fuel cycle operators, national engineering champions with reactor-specific heritage, and regional technology specialists capturing discrete technical phases.
| Leading Market Players |
|---|
| Cavendish Nuclear Ltd |
| Electricite de France SA |
| Babcock International Group PLC |
| Orano |
| Studsvik AB |
| Fluor Corporation |
| GE Hitachi Nuclear Services |
| AECOM |
| Westinghouse Electric Company LLC |
| Others |
Supply & Pricing Matrix
The EU Green Deal's sustainable finance taxonomy gates qualified supply and premium-tier pricing access for decommissioning contractors, as institutional capital flows exclusively toward certified green expenditure programs that meet stringent waste management standards.
Pricing Analysis
The bundled-vs-unbundled service split now defines contract economics across European decommissioning programs. Project-based long-term contracts dominate integrated waste conditioning through site restoration, while discrete work packages for radiological characterization and remote tooling command premium rates tied to certification level and technical complexity. Price differentiation stems from regulatory compliance tier and after-sales service bundling. Cost compression in standard dismantling phases is intensifying because utilities fragment procurement into competitive tenders. Government-funded waste management entities in Germany exhibit highest price sensitivity; specialized robotics contractors serving Finnish autonomous segmentation pilots face least.
Supply Chain Analysis
Workforce availability constraints in French and German engineering clusters anchor supply chain configuration for European decommissioning programs. Manufacturing and technical service concentration centers on France, Germany, and the United Kingdom, where radiological engineers and remote handling specialists cluster around legacy reactor sites. The supply chain draws from irradiated graphite cores, spent fuel assemblies, and shielded containment materials as critical inputs. Single-source vulnerability runs through Finland's Onkalo as the continent's only licensed spent fuel repository. Distribution runs through utility procurement teams unbundling engineering-procurement-construction contracts into specialized service packages tendered separately.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story as robotics and remote tooling convergence compress labor-intensive dismantling phases, enabling contractors to capture premium pricing for reduced-exposure technologies while standard service tiers face cost compression.
For Market Incumbents: Lock in multi-decade waste conditioning contracts before regulatory licensing deadlines compress procurement windows. Deepen backward integration into radiological characterization capabilities to defend against specialized engineering firms capturing discrete work packages. Prioritize certification investment under the EU Green Deal's sustainable finance taxonomy to maintain capital access. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in site restoration services creates entry opportunity for contractors developing final status survey capabilities. Eastern European markets including Bulgaria's Kozloduy and Slovakia's Bohunice lack indigenous decommissioning capacity and import French and German expertise. Pursue joint venture structures with established waste conditioning providers to accelerate regulatory credibility. For Investors and Strategic Acquirers: Roll-up economics work for regional engineering houses because national decommissioning programs require localized dismantling contracts with reactor-specific heritage. The five-to-ten year viability window favors acquisition of Nordic technology specialists concentrating decontamination capabilities. Watch for licensing acceleration at France's Cigéo and Germany's Konrad as inflection indicators for waste disposal route certainty.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics and Remote Tooling Investment | Autonomous segmentation systems at Finnish Olkiluoto reduce worker exposure and compress dismantling timelines. |
| Waste Conditioning Capacity Expansion | Orano's La Hague complex anchors multi-decade spent fuel packaging contracts for French EDF reactor fleets. |
| Site Restoration Specialization | Tightened European Nuclear Safety Regulators Group guidelines on final status surveys create premium margin pools. |
| Eastern European Joint Ventures | Bulgarian and Slovak reactor operators import French and German expertise for staged dismantling programs. |
| Green Certification Program | EU Green Deal taxonomy eligibility channels institutional capital toward certified low-carbon decommissioning methodologies. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down contractor capacity tracking forms the analytical core of this study. Primary interviews with decommissioning fund managers, nuclear safety authority licensing officers, EPC procurement leads, and radiological engineering directors combined with secondary validation from ASN licensing records, Bundesamt für kerntechnische Entsorgungssicherheit documentation, and European Nuclear Safety Regulators Group guidelines. Top-down trade data and national decommissioning fund disclosures triangulate against bottom-up contract award tracking.
The input-output matrix framing connects reactor shutdown schedules to service demand across waste management, dismantling, and site restoration phases. Segmentation dimensions modeled include service type, reactor type, decommissioning stage, and client liability structure across the projection horizon. CAGRs derive from utility capital allocation trajectories under EU Green Deal capital redirection policies and national phase-out law implementation timelines. Forecast inputs incorporate spent fuel inventory volumes and repository licensing progression.
Caveats apply where deep geological repository licensing delays or intergenerational funding assurance disputes could materially shift the outlook. Forecasts reflect assumptions regarding regulatory hold-point timing and waste disposal site availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Thorium Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Europe Nuclear Reactor Construction Market