
 Germany Health Insurance Market | 2026-2036
Germany Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Health Insurance Market Insights
Market Dynamics and Competitive Landscape
CE marking for cross-border health service portability is unwinding competitive barriers between statutory and private insurers. Techniker Krankenkasse leverages digital health platforms to streamline claims processing and member engagement. Barmer anchors its position through extensive branch networks across eastern German states. DKV Deutsche Krankenversicherung differentiates via specialized occupational health products for corporate clients.
Technical Definition and Segment Structure
Germany health insurance constitutes a dual-system framework comprising statutory health insurance (Gesetzliche Krankenversicherung) and private health insurance (Private Krankenversicherung), with premiums calculated through income-percentage contributions for statutory members and actuarial risk assessments for private enrollees. The system finances preventive care, acute treatment, rehabilitation, and pharmaceutical provision through centralized health fund mechanisms and individual insurer reserves. Public health insurance dominates enrollment volumes due to mandatory membership thresholds, while private health insurance captures higher-margin segments among affluent professionals and civil servants. Supplemental insurance is expanding fastest as statutory members seek dental, vision, and alternative therapy coverage beyond baseline benefits.
Regulatory Environment and Strategic Outlook
The Federal Joint Committee (G-BA) and Federal Financial Supervisory Authority (BaFin) govern benefit catalogues and insurer solvency requirements respectively, with SGB V mandating minimum coverage standards that limit product differentiation. The EU AI Act and Germany's Digital Healthcare Act impose algorithmic transparency requirements on automated claims systems and telemedicine platforms. Stakeholders must monitor how prospective risk-structure equalization reforms redistribute capital flows between high-utilization and low-utilization insurer pools.
Market Dynamics
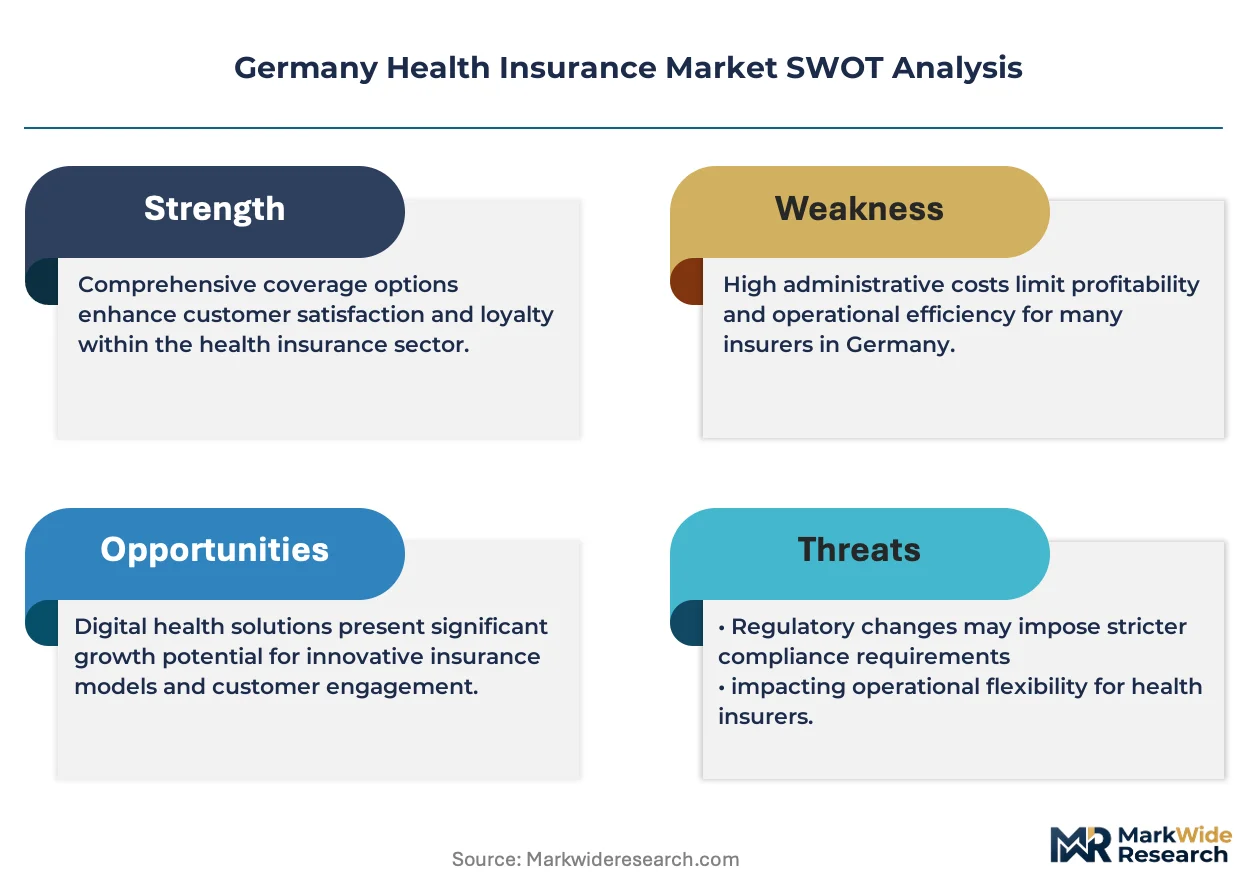
The German health insurance sector faces structural pressure from the Digital Healthcare Act's mandated interoperability standards, which compel insurers to overhaul legacy IT architectures while maintaining statutory service obligations under SGB V.
Growth Catalysts
- Telemedicine reimbursement expansion:The Digital Healthcare Act permanently integrated video consultations into statutory benefit catalogues, accelerating platform investments by sickness funds.
- Employer wellness mandates:Occupational health screening requirements under the Occupational Safety Act drive corporate demand for preventive coverage add-ons.
- Aging population concentration:Eastern German states exhibit elevated chronic disease prevalence, expanding risk-pool enrollment and care management service volumes.
Market Restraints
- Contribution rate ceilings:The Health Fund's income-percentage formula caps revenue elasticity when wage growth stagnates, compressing operating margins during economic downturns.
- Pharmaceutical cost inflation:Patent-protected biologics and ATMP therapies strain centralized reimbursement negotiations, forcing supplementary premium adjustments.
- Regional provider consolidation:Hospital mergers in Bavaria and Baden-Württemberg reduce insurer bargaining power in tariff negotiations.
Strategic Opportunities
- Supplemental dental-vision bundles:Statutory members in North Rhine-Westphalia demonstrate willingness-to-pay for cosmetic and orthodontic services excluded from G-BA baseline coverage.
- AI-driven risk stratification:Predictive analytics integration with electronic health records enables targeted chronic disease intervention programs.
- Cross-border service portability:CE marking harmonization permits insurers to offer standardized products to mobile EU professionals posted in German metropolitan labor markets.
Industry Challenges
- Interoperability standard compliance:The gematik-specified TI 2.0 infrastructure demands multi-year legacy system migrations with uncertain ROI timelines.
- Actuarial talent scarcity:Specialized expertise in risk-structure equalization modeling concentrates among incumbent statutory funds, constraining private insurer analytical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Health Insurance Market |
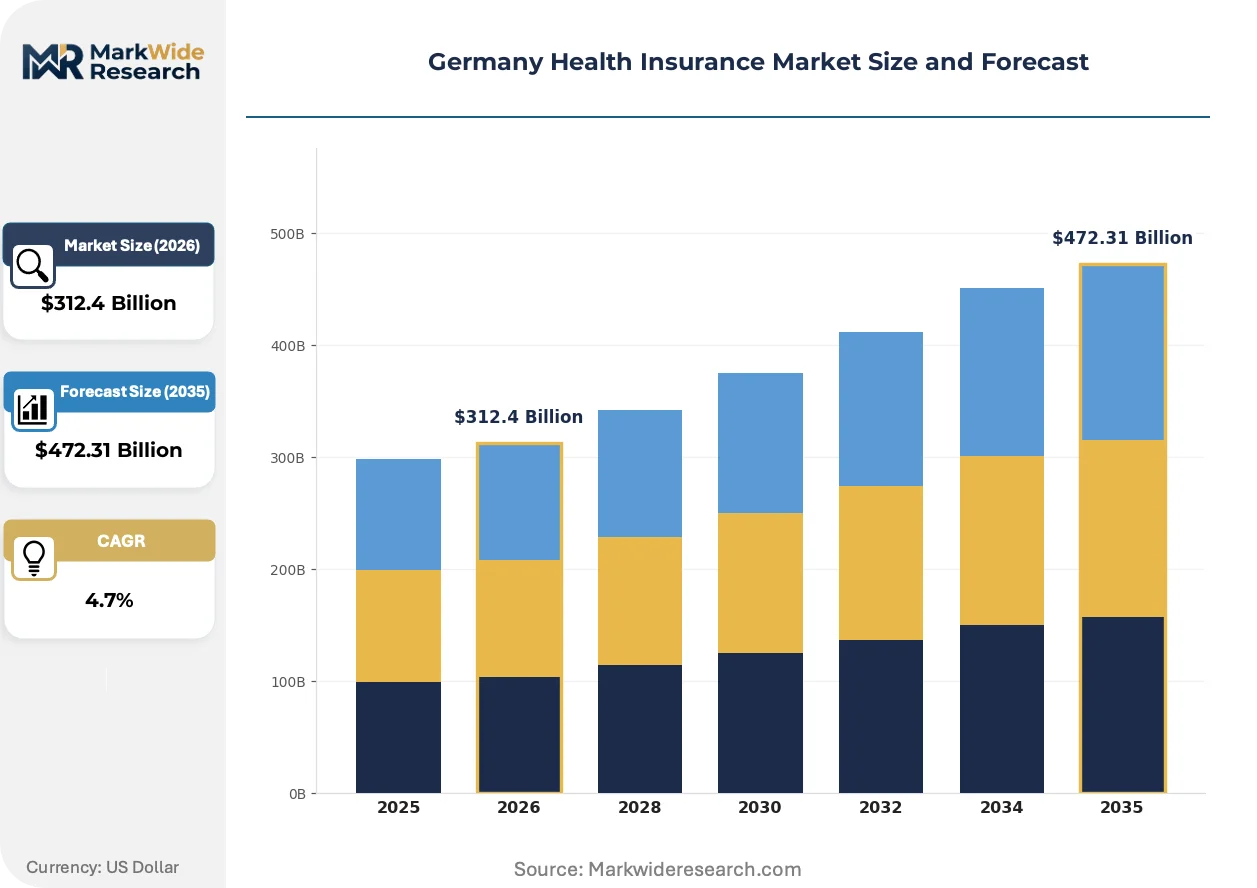
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $472.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Public Health Insurance, Private Health Insurance, Supplemental Insurance, Long-term Care Insurance End User: Individuals, Families, Employers, Senior Citizens Coverage Type: Comprehensive, Basic, Catastrophic, Preventive Premium Model: Flat-rate, Income-based, Age-based, Health-status-based |
| Companies Covered | Techniker Krankenkasse (TK), AOK – Die Gesundheitskasse, Barmer, DAK-Gesundheit, Debeka Krankenversicherung, DKV Deutsche Krankenversicherung, Allianz Private Krankenversicherung, Signal Krankenversicherung, Barmenia Krankenversicherung, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Health Insurance Market Trends and Innovations
Algorithmic decision systems and decentralized care delivery models are restructuring how German insurers engage members, process claims, and allocate capital across preventive and acute service categories.
Claims automation through machine learning is bifurcating operational efficiency between technology-leader funds and legacy-dependent competitors. Techniker Krankenkasse and Barmer have deployed natural language processing for invoice validation, reducing manual review queues by half. This capability compression is widening cost-to-serve spreads across the statutory landscape, pressuring mid-tier funds toward consolidation or vendor partnerships.
Germany's implementation of the EU AI Act imposes algorithmic transparency mandates on automated claims denial systems and diagnostic recommendation engines. BaFin has issued supplementary guidance requiring documented human-in-the-loop protocols for high-risk health AI applications. Private insurers with actuarial pricing algorithms face the steepest compliance burdens, as risk-scoring models must now expose decision logic to regulatory audit.
Subscription-based wellness platforms are displacing traditional agent-driven enrollment for younger statutory members. Ottonova and similar digital-native intermediaries bundle fitness tracking, mental health coaching, and telemedicine access into flat monthly fees. This channel disruption concentrates in Berlin and Hamburg, where mobile-first demographics exhibit lower brand loyalty to established sickness funds and higher switching elasticity during open enrollment periods.
Germany Health Insurance Market Segmentation
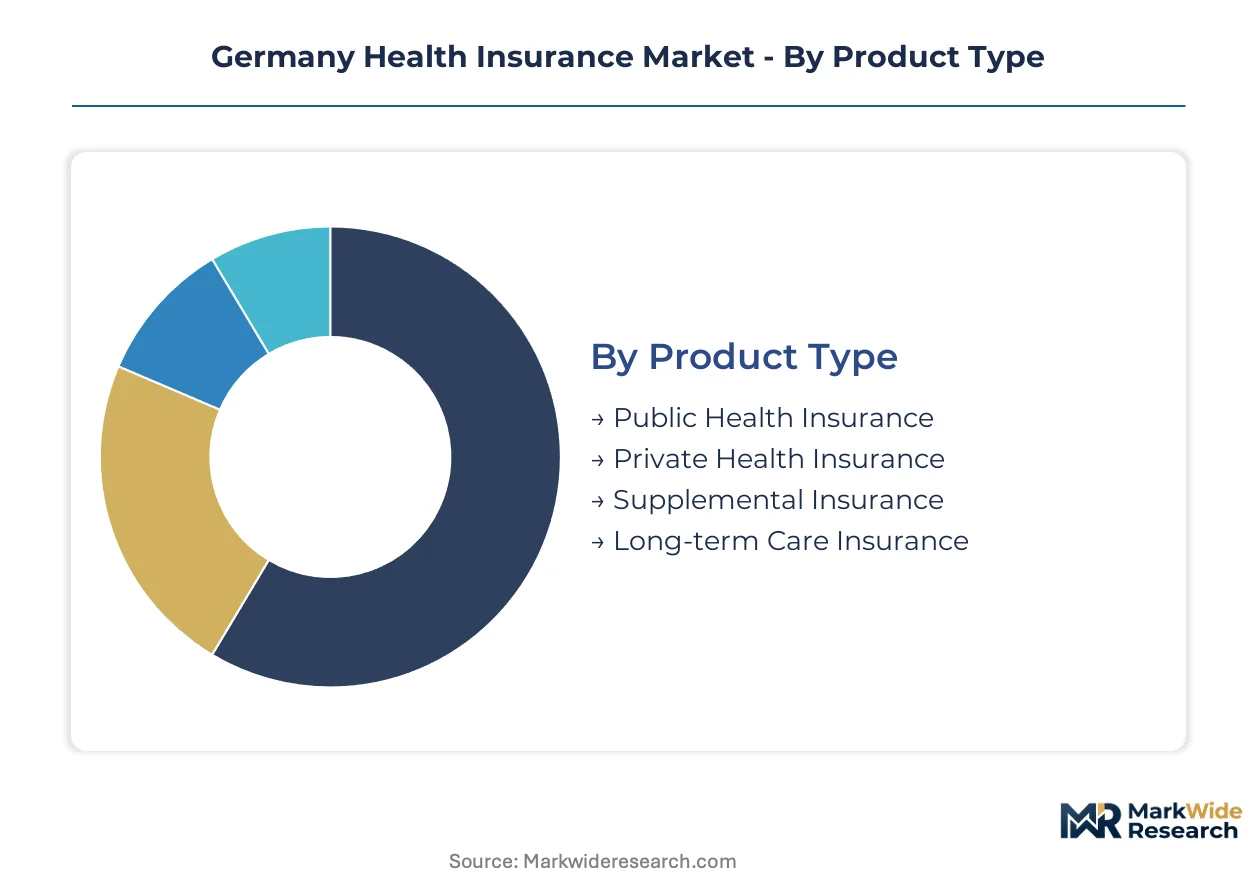
Germany's dual-system architecture fragments the market across statutory-private boundaries, with each segment carrying distinct regulatory obligations under SGB V and divergent margin profiles. Understanding these divides reveals where capital flows concentrate and where new entrants can circumvent incumbent scale advantages.
Product Type:
Domestic enrollment patterns dominate all product categories, with cross-border portability only recently enabled through CE marking harmonization for mobile EU professionals.
- Public Health Insurance:Statutory sickness funds (Gesetzliche Krankenversicherung) collect income-percentage contributions capped by federal thresholds, covering approximately 90% of residents through risk-pool equalization mechanisms. Demand concentrates in North Rhine-Westphalia and Bavaria, where industrial employment density sustains mandatory enrollment volumes and employer-matched contribution flows.
- Private Health Insurance:Actuarial risk-rated premiums serve affluent professionals, civil servants, and self-employed earners above the compulsory insurance threshold, with reserves held individually rather than pooled. Berlin and Hamburg exhibit elevated switching elasticity among younger demographics attracted to digital-native intermediaries.
- Supplemental Insurance:Dental, vision, and alternative therapy riders attach to statutory base coverage, capturing out-of-pocket willingness-to-pay for services excluded from G-BA benefit catalogues.
- Long-term Care Insurance:Mandatory Pflegeversicherung operates as a separate pillar with tiered dependency assessments, financing home and institutional care through pay-as-you-go structures alongside private supplementary options.
Public Health Insurance commands the established base. The steepest expansion runs through Supplemental Insurance.
End User:
Cost-tier stratification separates premium-absorbing corporate segments from price-sensitive individual purchasers.
- Individuals:Solo statutory enrollees and private insurance purchasers navigate open enrollment periods with varying degrees of digital engagement, from branch-dependent seniors to app-native millennials.
- Families:Non-contributory dependent coverage under statutory rules creates sticky multi-year contracts, with family policies driving dental-vision bundle attachment rates in metropolitan zones.
- Employers:Corporate group contracts and occupational health mandates generate institutional volume with negotiated rate structures, particularly in automotive and chemical sectors with established works council relationships.
- Senior Citizens:Chronic disease prevalence and long-term care dependency concentrate demand in eastern German states, expanding risk-pool enrollment and care management service volumes.
Individuals anchor volume concentration. Employers deliver the fastest margin expansion through wellness mandate attachment.
Coverage Type:
Application-driven differentiation separates acute intervention from preventive engagement models.
- Comprehensive:Full-spectrum inpatient, outpatient, and pharmaceutical coverage dominates statutory benefit catalogues and high-tier private tariffs, with utilization rates tracking regional provider density.
- Basic:Stripped-down hospital and emergency-only plans serve cost-minimizing segments, though regulatory minimums under SGB V limit how thin coverage can run.
- Catastrophic:High-deductible structures with stop-loss protection appear primarily in private market niches, absorbing rare but severe acute episodes.
- Preventive:Screening, vaccination, and wellness program coverage expands under Digital Healthcare Act mandates, with telemedicine integration accelerating platform investments by sickness funds.
Comprehensive coverage holds the dominant share. Preventive benefits are climbing the fastest as reimbursement frameworks mature.
Premium Model:
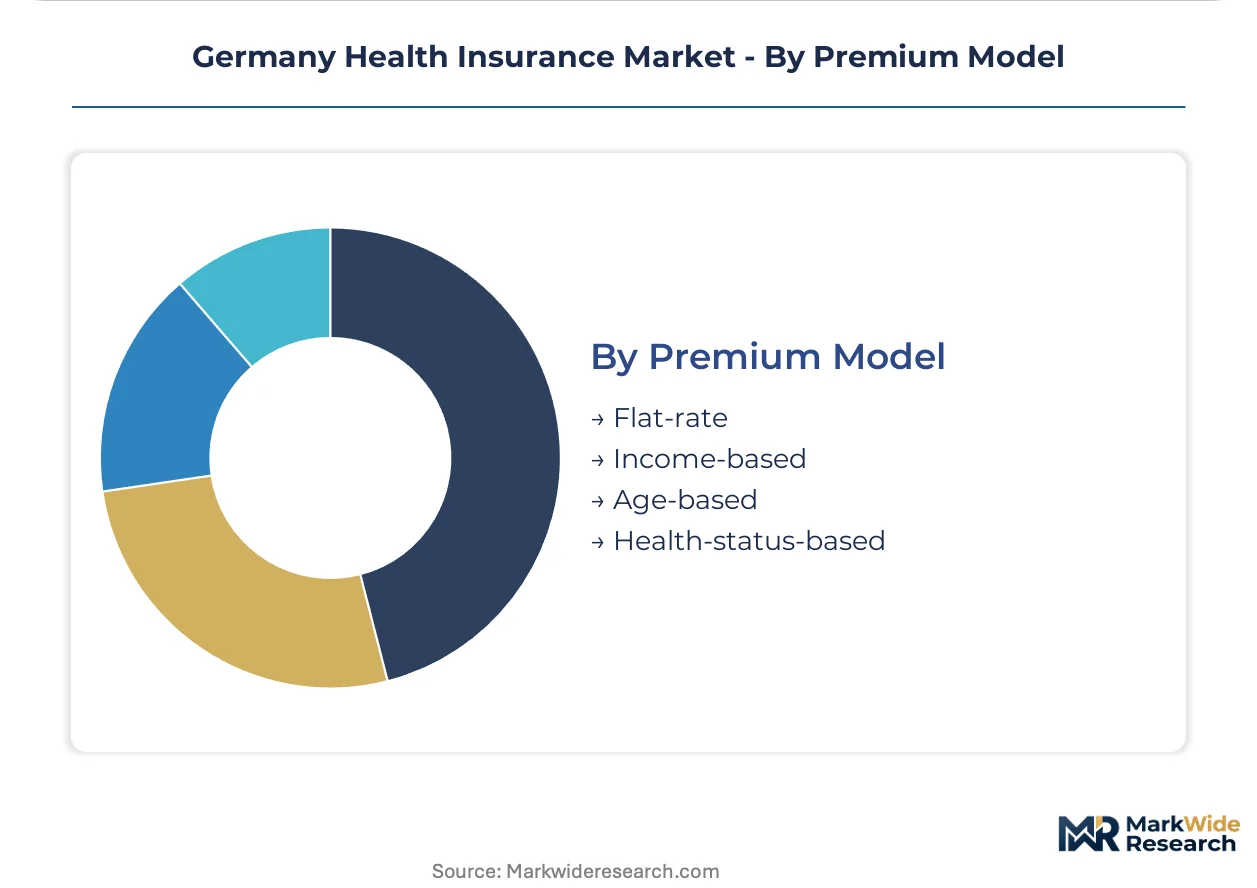
Customer-type alignment determines whether pricing responds to income, age, or health status signals.
- Flat-rate:Fixed monthly premiums decoupled from utilization characterize select private insurance tiers and supplemental riders, simplifying budgeting for self-directed purchasers.
- Income-based:Percentage-of-wage contributions fund statutory sickness funds through employer-employee splits, with contribution rate ceilings compressing margin elasticity during wage stagnation.
- Age-based:Entry-age rating in private insurance creates lifetime premium trajectories that reward early enrollment, with aging reserves building across decades.
- Health-status-based:Medical underwriting and risk surcharges apply to private market entrants, though pre-existing condition exclusions face tightening regulatory scrutiny.
Income-based structures dominate enrollment. Health-status-based pricing is gaining share fastest among private market product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Joint Committee's risk-structure equalization reforms and Bavaria's digital health infrastructure subsidies are redistributing insurer capital flows across German states, with metropolitan enrollment density shaping regional competitive positioning.
Bavaria
Automotive sector employment density and Siemens Healthineers' Munich headquarters sustain employer-matched contribution volumes for statutory funds. The Bavarian Hospital Association's tariff consolidation reduces insurer bargaining leverage in provider negotiations. Nuremberg and Augsburg cluster occupational health service demand from manufacturing works councils.
North Rhine-Westphalia
Chemical industry concentration in the Ruhr Valley and Cologne's reinsurance sector generate dual-track demand for statutory and private coverage. The state's Hospital Structural Reform Act accelerates provider mergers in Düsseldorf and Essen. Dortmund's aging steelworker populations expand chronic disease management enrollment for Techniker Krankenkasse.
Baden-Württemberg
Porsche and Bosch corporate headquarters anchor group insurance contracting in Stuttgart and Mannheim. The state's Medical Devices Act implementation tightens digital health platform compliance requirements. Heidelberg's university hospital network concentrates specialized acute care referrals from across southwestern Germany.
Berlin-Brandenburg
Startup ecosystem density and gig-economy employment patterns elevate switching elasticity among younger statutory enrollees. The Digital Healthcare Act's telemedicine mandates face implementation delays in Brandenburg's rural counties. Potsdam's proximity to federal regulators attracts insurer compliance operations.
Hamburg
Port logistics employment and Hapag-Lloyd's corporate health programs sustain maritime-sector occupational coverage demand. The city's dense outpatient provider network enables capitation model experiments by Barmer. Ottonova's digital-native subscriber base concentrates in Hamburg's millennial-heavy districts.
Germany Health Insurance Market Competitive Landscape
Player mix skews toward statutory sickness funds with risk-pool equalization obligations, while private insurers occupy niche premium tiers. Scale advantages concentrate among funds with legacy branch networks and employer-works council relationships. Two strategic archetypes dominate: technology-leader funds deploying AI claims automation, and relationship-dependent funds leveraging occupational health mandates. Competitive moves center on telemedicine platform licensing and dental-vision bundle diversification.
Within the statutory fund tier, Techniker Krankenkasse and Barmer exemplify divergent operational models, with the former representing digital-first claims processing and the latter anchoring branch-network density in eastern states. DKV Deutsche Krankenversicherung occupies a position among private-market specialists targeting corporate occupational health segments. These three entities collectively illustrate how regulatory fragmentation between statutory and private frameworks creates distinct competitive arenas requiring separate capitalization and distribution strategies.
| Leading Market Players |
|---|
| Techniker Krankenkasse (TK) |
| AOK – Die Gesundheitskasse |
| Barmer |
| DAK-Gesundheit |
| Debeka Krankenversicherung |
| DKV Deutsche Krankenversicherung |
| Allianz Private Krankenversicherung |
| Signal Krankenversicherung |
| Barmenia Krankenversicherung |
| Others |
Pricing and Supply Chain Analysis
Capitation contracts with integrated care networks lock in both provider access and premium stability for statutory funds operating under SGB V. These arrangements tie reimbursement flows to population health outcomes, compressing price volatility while embedding sickness funds into regional provider hierarchies. The Health Fund's income-percentage formula further constrains pricing elasticity, capping revenue upside during wage stagnation cycles.
Pricing Analysis
Risk-rated entry-age bands create the primary spread between statutory and private insurance tiers, with younger enrollees building aging reserves that compound across decades. Income-percentage contributions dominate statutory enrollment, while actuarial health-status assessments govern private market pricing. Cost compression in statutory segments intensifies as pharmaceutical inflation outpaces contribution rate adjustments. Price sensitivity concentrates among solo statutory enrollees navigating open enrollment, whereas corporate group purchasers exhibit lower elasticity due to employer-matched contribution structures.
Supply Chain Analysis
Just-in-time care delivery models predominate in metropolitan zones, while eastern German states maintain strategic capacity buffers for chronic disease management. Healthcare service provisioning draws from domestic hospital networks concentrated in Bavaria and North Rhine-Westphalia, with pharmaceutical inputs sourcing from Switzerland, Ireland, and domestic manufacturing clusters. Single-source vulnerability runs through patent-protected biologics and ATMP therapies subject to centralized G-BA reimbursement negotiations. Distribution feeds from regional hospital associations into outpatient networks, with telemedicine platforms disrupting traditional geographic catchment boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across statutory-private boundaries and regional risk-pool disparities creates multiple niche entry points. Digital-native intermediaries exploiting switching elasticity among younger demographics exemplify how demand-side channel shifts open competitive whitespace.
For Market Incumbents: Fortify digital claims infrastructure against algorithmic transparency mandates under the EU AI Act. Invest in telemedicine platform licensing to preempt Ottonova-style channel displacement. Deepen employer-works council relationships in automotive and chemical sectors to secure sticky group contract volumes against mid-tier fund consolidation pressure. For New Entrants and Emerging Players: Lead with supplemental dental-vision bundles targeting statutory members in North Rhine-Westphalia, where willingness-to-pay for cosmetic services exceeds national baselines. Capture switching elasticity during Berlin and Hamburg open enrollment periods through subscription-based wellness platforms. Deploy mobile-first enrollment to circumvent incumbent branch-network scale advantages. For Investors and Strategic Acquirers: Capital is best deployed toward technology-leader statutory funds with demonstrated AI claims automation capabilities and proven telemedicine integration. Long-term viability hinges on compliance infrastructure readiness for evolving BaFin solvency requirements and G-BA benefit catalogue expansions. Monitor risk-structure equalization reform progress as the signal indicating capital flow redistribution between high-utilization and low-utilization insurer pools.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Licensing | Digital Healthcare Act mandates accelerate sickness fund investments in video consultation infrastructure. |
| AI Claims Automation Deployment | BaFin algorithmic transparency requirements favor funds with documented human-in-the-loop protocols. |
| Supplemental Dental-Vision Bundle Expansion | G-BA baseline exclusions drive statutory member willingness-to-pay for cosmetic and orthodontic riders. |
| Employer Wellness Program Integration | Occupational Safety Act screening mandates generate corporate demand for preventive coverage add-ons. |
| Cross-Border CE Marking Harmonization | EU portability frameworks enable standardized product offerings to mobile professionals in metropolitan labor markets. |
Research Methodology
Desk research of BaFin solvency disclosures, G-BA benefit catalogue determinations, and statutory fund annual reports preceded structured interviews with sickness fund actuarial directors, hospital procurement managers, and occupational health service providers. Secondary validation drew from Federal Statistical Office enrollment data, gematik interoperability specifications, and EU AI Act implementation guidance. Bottom-up segmentation modeling triangulated against top-down Health Fund revenue aggregates.
Variance decomposition across product type, premium model, and regional risk-pool dimensions anchored the analytical framework over the projection horizon. Modeled segments spanned statutory-private boundaries, coverage tier stratification, and metropolitan-rural enrollment density differentials. CAGRs derived from historical contribution rate trajectories, pharmaceutical cost inflation baselines, and demographic aging curves. Forecast inputs incorporated telemedicine reimbursement expansion schedules and risk-structure equalization reform scenarios.
The analysis sits within stated boundaries; outcomes outside sustained wage growth or stable pharmaceutical pricing corridors would require recalibration. Forecasts reflect documented assumptions regarding regulatory stability and employer contribution compliance. Revision becomes warranted when G-BA benefit catalogue expansions or BaFin solvency requirement adjustments cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
US Group Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
Healthcare Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
Health Insurance Market
Health Insurance
UAE Health Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
United States Health and Medical Insurance Market