
 Digital Mammography Market | 2026-2036
Digital Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Mammography Market Intelligence
Buyer concentration among hospital networks is broadening as integrated delivery systems consolidate radiology procurement across multiple sites. Hologic leverages its installed base of 3D mammography systems to sustain recurring revenue from service contracts and software upgrades. Siemens Healthineers competes through advanced imaging platforms that integrate artificial intelligence into workflow optimization. GE Healthcare anchors its position with comprehensive digital breast imaging portfolios spanning screening and diagnostic modalities.
Digital mammography captures X-ray images of breast tissue using solid-state detectors, converting photons into electronic signals with spatial resolution typically exceeding 70 micrometers per pixel for microcalcification detection. The technology replaces analog film-screen systems to enable immediate image review, computer-aided analysis, and electronic storage for longitudinal comparison. Digital breast tomosynthesis leads product type segments by capturing three-dimensional tissue slices that reduce overlapping structure artifacts in dense breast imaging. Computer-aided detection technology is gaining fastest adoption as regulatory clearances expand its role in secondary reads and workflow prioritization. Screening applications occupy the largest volume share while diagnostic follow-up commands premium pricing due to specialized protocol requirements.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and commercial access for digital mammography manufacturers. ISO 13485 quality management standards and DICOM interoperability requirements further constrain system design and data exchange capabilities. Stakeholders must monitor evolving reimbursement policies for 3D tomosynthesis screening as payor coverage decisions increasingly determine technology adoption velocity.
Market Dynamics
Hospital network consolidation across the United States is compressing procurement cycles and forcing manufacturers to restructure sales organizations around enterprise account management rather than individual site relationships.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification processes for computer-aided detection software are shortening commercialization timelines for AI-integrated mammography systems.
- Dense breast tissue notification laws:State-level mandates in California, New York, and Connecticut require patient disclosure of breast density, driving demand for 3D tomosynthesis systems that improve visualization in dense tissue.
- Screening program modernization:The National Breast and Cervical Cancer Early Detection Program is replacing aging analog infrastructure with digital systems across federally qualified health centers.
Market Restraints
- Detector manufacturing concentration:Amorphous selenium and cesium iodide detector production concentrates among a handful of Asian suppliers, creating vulnerability to supply disruptions.
- EU MDR conformity costs:The transition from MDD to MDR has extended certification timelines and doubled notified body assessment fees for European market access.
- CT-based breast imaging alternatives:Dedicated breast CT systems are emerging as competing modalities for dense breast evaluation in research settings.
Strategic Opportunities
- Rural health clinic penetration:Mobile screening units and teleradiology partnerships can extend digital mammography access to underserved counties in Texas, Mississippi, and Alaska.
- Artificial intelligence workflow integration:Convergence of deep learning algorithms with PACS systems is creating new software subscription revenue streams independent of hardware sales.
- CMS reimbursement expansion:Proposed national coverage determination for 3D tomosynthesis screening would standardize payment parity across Medicare Advantage plans.
Industry Challenges
- Clinical physicist shortage:Qualified medical physicists for mammography unit calibration and MQSA compliance are scarce in secondary markets, delaying site certifications.
- Legacy PACS interoperability:DICOM conformance variations between vintage storage systems and new acquisition devices complicate enterprise imaging consolidation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Mammography Market |
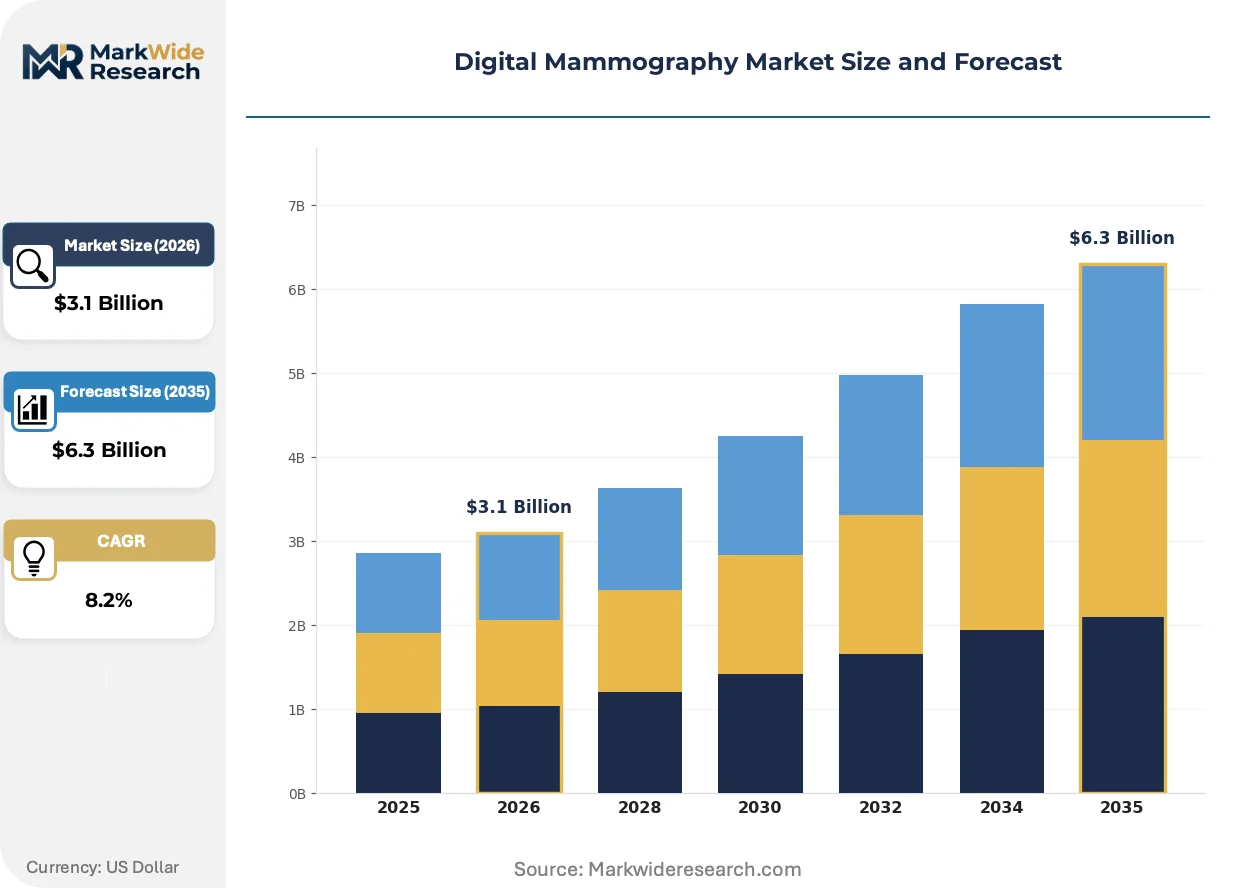
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.3 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Field Mammography, Digital Breast Tomosynthesis, Portable Mammography Units, Smart Phone-Based Devices End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Mobile Units Technology: X-ray, Optical Imaging, 3D Imaging, Computer-Aided Detection Application: Screening, Diagnostics, Breast Cancer Detection, Follow-up Care |
| Companies Covered | Koninklijke Philips, Planmed, Hologic, Canon, Carestream, GE Healthcare, Fujifilm Holdings, Metaltronica, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Mammography Market Strategic Shifts & Innovations
Artificial intelligence is restructuring competitive advantage around software capabilities rather than hardware specifications, with algorithm performance becoming the primary procurement evaluation criterion for integrated delivery networks.
Photon-counting detector technology is expanding into screening applications through improved dose efficiency and spectral imaging capabilities. Academic medical centers in Massachusetts and Minnesota are piloting these systems for high-risk patient cohorts. The technology is expanding into mainstream screening protocols as manufacturers validate performance against FFDM benchmarks.
The FDA's Total Product Life Cycle advisory program is accelerating breakthrough device designations for AI-based lesion detection algorithms. This regulatory pathway compresses premarket review timelines and enables earlier commercial dialogue with payors. Device manufacturers are responding by restructuring quality systems around real-world performance monitoring.
Enterprise procurement teams are consolidating imaging equipment decisions under centralized value analysis committees. Independent imaging centers and smaller hospitals are losing negotiating leverage as purchasing authority migrates to regional system headquarters. This concentration is most visible in the Midwest, where Catholic health initiatives and for-profit chains dominate market share.
Digital Mammography Market Segmentation
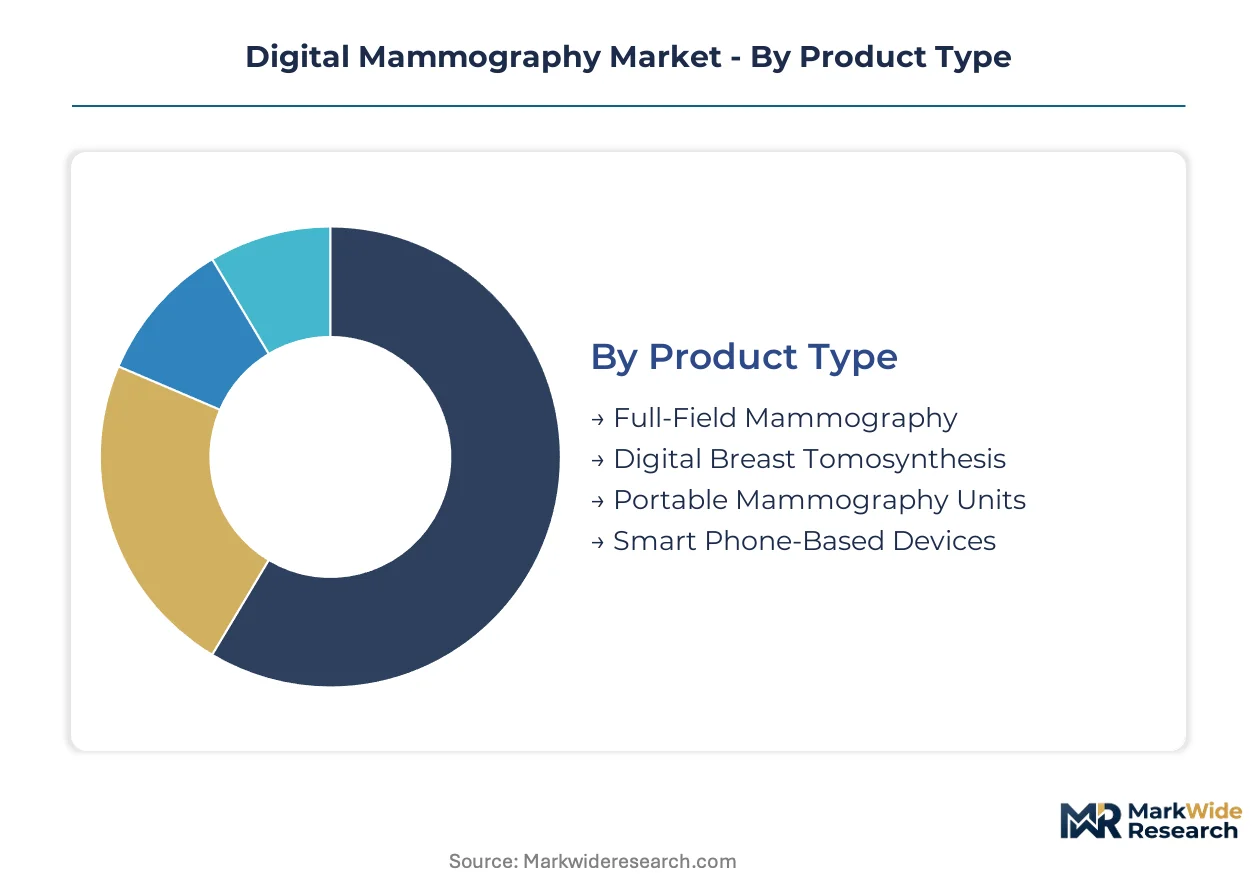
Segmentation in digital mammography reveals how procurement authority, imaging modality, and clinical setting determine technology selection. Supply concentration in detector manufacturing and software development creates divergent margin structures across product tiers.
Product Type:
Detector supply concentration among Asian manufacturers shapes availability and cost structures across hardware categories.
- Full-Field Mammography:Flat-panel digital detectors capture two-dimensional projection images using amorphous selenium or cesium iodide scintillators. United States hospital networks favor these systems for high-volume screening programs where throughput and reliability outweigh advanced feature requirements.
- Digital Breast Tomosynthesis:Multi-angle X-ray acquisition reconstructs three-dimensional breast tissue slices at 1mm intervals, reducing structural overlap artifacts in dense tissue. State-level density notification laws in California, Connecticut, and New York accelerate replacement demand for these premium systems.
- Portable Mammography Units:Compact gantry designs enable deployment in mobile screening vehicles and rural clinic settings.
- Smart Phone-Based Devices:Experimental optical adjunct technologies target low-resource screening environments with smartphone-connected sensors.
Full-field mammography absorbs the bulk of installed capacity; digital breast tomosynthesis is expanding most quickly.
End User:
Procurement consolidation among integrated delivery networks is compressing vendor negotiation dynamics across facility types.
- Hospitals:Academic medical centers and community hospitals operate centralized breast imaging departments with MQSA-certified radiologists and dedicated breast surgeons. Enterprise procurement teams at United States health systems now consolidate multi-site equipment decisions under value analysis committees.
- Diagnostic Centers:Freestanding imaging facilities compete on appointment availability and radiologist subspecialization. These centers in Texas and Florida face margin pressure as hospital networks build captive outpatient capacity.
- Outpatient Clinics:Federally qualified health centers replace aging analog systems through federal screening program modernization grants.
- Mobile Units:Trailer-mounted systems extend screening access to underserved counties with limited permanent imaging infrastructure.
Hospitals command the largest equipment budgets; diagnostic centers are gaining share fastest as patients seek appointment convenience.
Technology:
Algorithm development concentration among AI specialists is restructuring competitive advantage away from hardware specifications.
- X-ray:Conventional bremsstrahlung X-ray sources with molybdenum or rhodium target filtration dominate screening protocols. FDA 510(k) pathway familiarity accelerates clearance timelines for incremental hardware improvements.
- Optical Imaging:Near-infrared spectroscopy and diffuse optical tomography investigate tissue oxygenation and hemoglobin concentration as adjunct diagnostic markers.
- 3D Imaging:Tomosynthesis reconstruction algorithms require substantial computational infrastructure for real-time slice generation.
- Computer-Aided Detection:Deep learning algorithms for lesion identification and workflow prioritization create software subscription revenue independent of hardware sales.
X-ray technology carries the installed base; computer-aided detection is climbing the fastest as regulatory clearances expand.
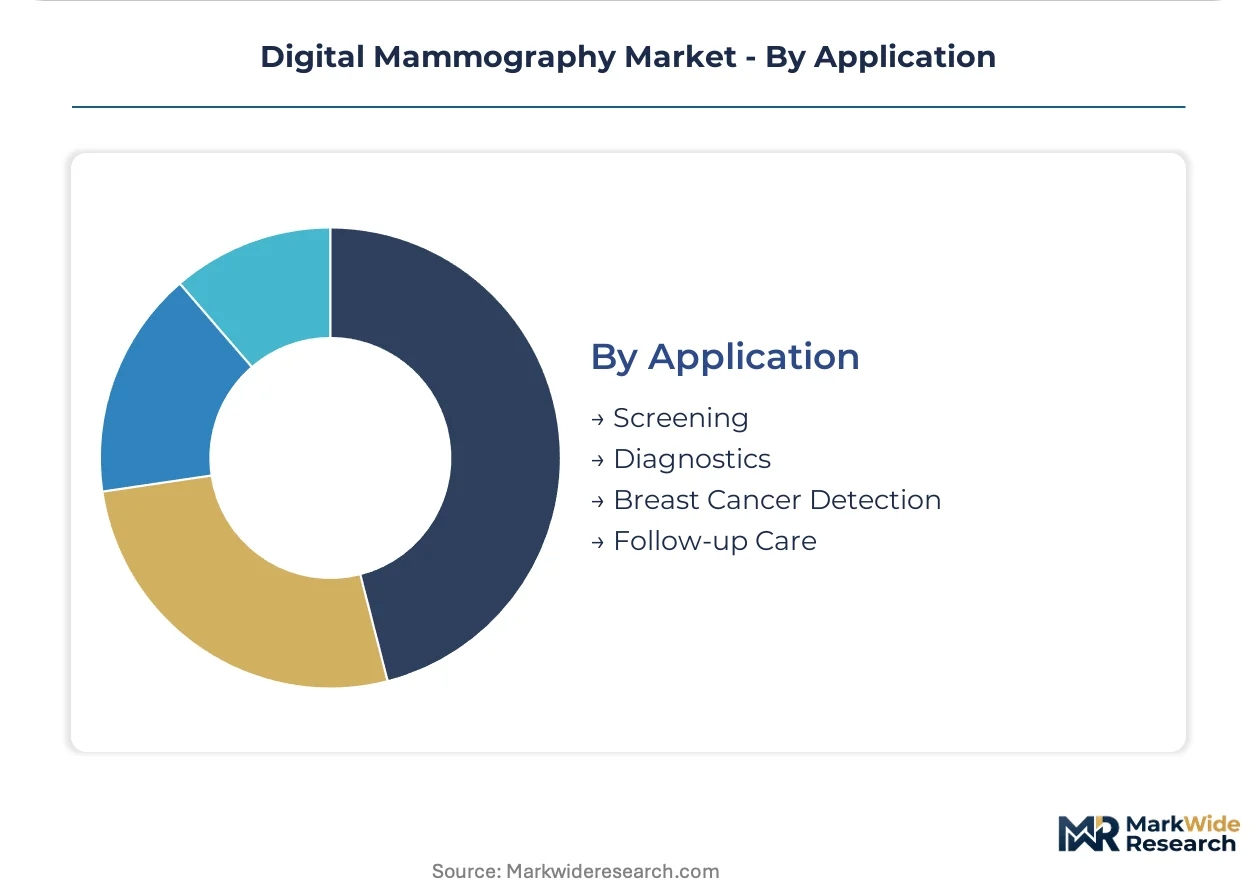
Application:
Reimbursement rate differentials between screening and diagnostic protocols drive equipment utilization patterns and capital allocation priorities.
- Screening:Asymptomatic patient evaluation at standardized intervals generates high exam volumes with compressed per-procedure margins. CMS reimbursement policies for 3D tomosynthesis screening determine adoption velocity across Medicare Advantage plans.
- Diagnostics:Symptomatic evaluation and problem-solving examinations command premium technical fees due to specialized views, magnification, and contrast protocols.
- Breast Cancer Detection:Primary lesion identification workflows integrate CAD marks with radiologist interpretation for sensitivity optimization.
- Follow-up Care:Post-treatment surveillance and neoadjuvant therapy monitoring require longitudinal comparison capabilities across multiple imaging modalities.
Screening applications dominate exam volume; diagnostic follow-up commands the steepest pricing premiums per procedure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital network consolidation concentrates procurement authority in select metropolitan clusters. Federal screening program modernization and density notification legislation drive replacement cycles for aging analog infrastructure. Regulatory clearance pathways vary substantially across national health systems.
United States
Academic medical centers in Massachusetts and Minnesota pilot photon-counting detectors for high-risk cohorts. The FDA's Total Product Life Cycle advisory program accelerates breakthrough device designations for AI-based lesion detection algorithms. Hospital networks in the Midwest consolidate radiology procurement under Catholic health initiatives and for-profit chains.
Germany
Siemens Healthineers anchors advanced imaging platform development with artificial intelligence workflow optimization. The EU MDR transition from MDD has extended certification timelines and doubled notified body assessment fees for market access. Industrial concentration in Bavaria and Baden-Württemberg supports precision manufacturing for detector components.
China
Domestic hospital procurement prioritizes cost-efficient digital systems for expanding screening coverage. The NMPA maintains streamlined premarket notification pathways for incremental hardware improvements. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta concentrate amorphous selenium and cesium iodide detector production.
Japan
Metropolitan screening programs in Tokyo and Osaka drive demand for high-throughput full-field systems. METI standards and PMDA oversight shape quality benchmarks for 3D tomosynthesis devices. Fujifilm Holdings leverages domestic installed bases to sustain service contract revenue.
United Kingdom
NHS breast screening program modernization replaces aging analog infrastructure across England and Scotland. MHRA conformity assessments align with EU MDR requirements post-Brexit. London-based research hospitals evaluate computer-aided detection integration with PACS systems for workflow prioritization.
Digital Mammography Market Key Industry Players
United States producers anchor one tier with integrated digital breast imaging portfolios; European specialists hold advanced platform positions with AI-integrated workflow optimization. The vendor structure concentrates around three strategic archetypes: comprehensive modality suppliers, detector technology specialists, and software-centric workflow integrators. Capacity expansion and strategic partnerships dominate competitive moves as hospital network consolidation compresses procurement cycles.
Within the comprehensive portfolio tier, Hologic and GE Healthcare exemplify integrated delivery network positioning through recurring revenue from service contracts and software upgrades. Siemens Healthineers occupies the advanced platform vector with artificial intelligence workflow optimization. These three anchors represent distinct competitive positioning strategies without implying specific market share claims.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Planmed |
| Hologic |
| Canon |
| Carestream |
| GE Healthcare |
| Fujifilm Holdings |
| Metaltronica |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Photon-counting detector migration from academic pilots to mainstream screening protocols is compressing manufacturing economics for legacy amorphous selenium and cesium iodide sensor production while concentrating supply authority among Asian component specialists. This technology transition forces tiered pricing stratification across detector generations as hospital networks weigh dose efficiency premiums against capital budget constraints.
Pricing Analysis
High-volume screening programs absorb the bulk of unit shipments while diagnostic follow-up configurations command margin premiums. Three-tier pricing structure across premium tomosynthesis systems, standard full-field digital units, and economy analog replacements reflects FDA certification tier and after-sales service bundling. Price differentiation stems from AI software integration depth and MQSA compliance support levels. Pricing pressure intensifies in the standard tier as Chinese manufacturers enter with cost-optimized flat-panel detectors. Federally qualified health centers exhibit highest price sensitivity; academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Direct-to-hospital-network channels handle enterprise procurement volume while distributor relationships serve independent diagnostic centers and rural clinics. Amorphous selenium and cesium iodide crystal production concentrates in China, Japan, and South Korea, with gantry assembly anchored in Germany and the United States. Detector substrate manufacturing draws from specialized glass and ceramic foundries in the Yangtze River Delta. Single-source vulnerability in scintillator material refining creates exposure to export control fluctuations. Distribution runs through manufacturer-direct sales organizations for integrated delivery networks and regional imaging equipment distributors for fragmented outpatient settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital network consolidation is compressing vendor counts as procurement authority migrates to centralized value analysis committees, forcing subscale manufacturers toward exit or acquisition.
For Market Incumbents: Hedge against photon-counting detector commoditization by securing captive supply agreements with Asian substrate manufacturers and accelerating AI workflow software subscription models. Backward integration into detector refurbishment services preserves margin pools as hardware replacement cycles lengthen. Defensive positioning requires locking multi-site service contracts with Midwest Catholic health initiatives and for-profit chains before competitive displacement. For New Entrants and Emerging Players: Begin with mobile screening unit deployments in rural Texas, Mississippi, and Alaska counties lacking permanent imaging infrastructure. Teleradiology partnerships with federally qualified health centers offer lowest competitive intensity for initial installed base accumulation. Software-only CAD algorithm licensing to legacy PACS vendors bypasses capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by comprehensive modality suppliers seeking AI capabilities or detector technology specialists. Five-to-ten year viability hinges on reimbursement policy alignment for 3D tomosynthesis screening. Target acquisition archetype: computer-aided detection software firms with FDA breakthrough device designations and pilot contracts with academic medical centers in Massachusetts or Minnesota. Signal to monitor: CMS national coverage determination timing for Medicare Advantage tomosynthesis parity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for AI lesion detection algorithms and enables earlier payor dialogue. |
| Hospital System Partnership | Secures multi-site enterprise procurement decisions under consolidated value analysis committee authority. |
| Software Companion Development | Creates recurring subscription revenue streams independent of capital hardware replacement cycles. |
| CE Marking Pathway | Unlocks EU MDR-compliant market access despite extended notified body assessment timelines and doubled fees. |
| Reimbursement Strategy | Aligns product positioning with CMS coverage determinations and state-level density notification law compliance. |
Research Approach
FDA 510(k) clearance databases, CMS reimbursement filings, and hospital procurement contract records formed the secondary backbone, supplemented by EU MDR notified body assessment documentation and Japanese PMDA submission data. Primary interviews with radiology department chairs, biomedical equipment procurement managers, GPO contracts specialists, and medical physicists validated demand assumptions and pricing dynamics. Bottom-up unit shipment estimates triangulated against top-down healthcare capital expenditure allocations across the analysis window.
Bottom-up modeling segmented volume and value across product type, end user facility category, technology generation, and application protocol. The analytical framework incorporated detector technology transition curves, replacement cycle timing for analog infrastructure, and AI software attach rate assumptions. CAGRs derived from logistic diffusion modeling of tomosynthesis penetration against full-field digital installed base saturation. Forecast inputs included state-level density notification law adoption timelines and federal screening program modernization grant disbursement patterns.
Underlying measurement precision varies by segment; hospital network procurement data carries tighter precision than independent diagnostic center estimates. Forecasts reflect assumptions regarding FDA clearance pathway velocity, EU MDR certification timeline normalization, and CMS reimbursement policy stability. Periodic stress-testing of base assumptions is recommended against detector supply disruption scenarios and payor coverage determination shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
Digital Radiology Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Italy Computed Tomography Market