
 ID Verification Market | 2026-2036
ID Verification Market Size, Share, and Industry Trends Forecast 2026-2036
ID Verification Market Outlook
North American cloud infrastructure providers is shifting toward sovereign data architectures for biometric processing. Jumio leverages liveness detection patents across Latin American fintech corridors. Onfido sustains document forensics leadership through synthetic identity resistance testing. Mitek Systems anchors mobile capture SDK distribution among tier-one retail banks.
ID verification encompasses the automated validation of government-issued credentials, biometric templates, and behavioral signals against authoritative databases, typically operating with false acceptance rates below one percent in production environments. The technology serves to bind digital transactions to verified human identities, reducing synthetic fraud losses and regulatory non-compliance penalties. Biometric authentication now leads technology deployment as facial recognition SDKs integrate into native mobile operating systems. Cloud-based solutions capture the fastest expansion within solution architecture as financial institutions retire legacy on-premises identity stacks. Document verification retains mature margin pools due to persistent manual review requirements for edge-case credential formats.
The EU AI Act classifies remote biometric identification as high-risk, mandating conformity assessments before market deployment. The FDA regulates biometric devices with medical-adjacent applications, while India's UIDAI governs Aadhaar-based authentication protocols for private sector access. Stakeholders must monitor evolving cross-border data localization mandates that fragment unified identity verification architectures.
Market Dynamics
Biometric liveness detection patents are concentrating competitive advantage among algorithm vendors while cloud infrastructure sovereignty mandates fragment unified deployment architectures across national borders.
Growth Catalysts
- EU AI Act high-risk classification:Remote biometric identification systems now require conformity assessments before European market entry, creating certified vendor ecosystems and compliance-driven procurement.
- Financial services AML mandates:Anti-money laundering directives across Germany, the United States, and India are accelerating document verification deployment for digital customer onboarding.
- Aadhaar authentication protocols:India's UIDAI governs private sector access to biometric authentication, standardizing identity verification infrastructure for fintech and telecom applications.
Market Restraints
- Cross-border data localization:Sovereign data architecture requirements in the European Union, India, and China fragment unified identity verification stacks and inflate operational complexity.
- Edge-case credential manual review:Persistent document forensics requirements for non-standard identity formats sustain margin pressure from human-in-the-loop processing costs.
- Synthetic identity fraud sophistication:Deepfake-enabled presentation attacks erode confidence in facial recognition systems and demand continuous algorithm retraining investment.
Strategic Opportunities
- Behavioral biometrics convergence:Keystroke dynamics and device fingerprinting integration with facial recognition creates multi-modal authentication white space in mobile banking.
- Latin American fintech corridors:Underpenetrated digital onboarding markets in Brazil and Mexico present expansion targets for liveness detection SDK providers.
- Medical-adjacent biometric devices:FDA regulatory pathways for health-monitoring authentication hardware open wellness and insurance verticals beyond traditional financial services.
Industry Challenges
- Algorithmic transparency documentation:EU AI Act explainability requirements demand technical documentation capabilities scarce among mid-tier verification vendors.
- Legacy identity stack migration:Financial institutions face integration complexity retiring on-premises systems for cloud-native biometric architectures without disrupting live transaction flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ID Verification Market |
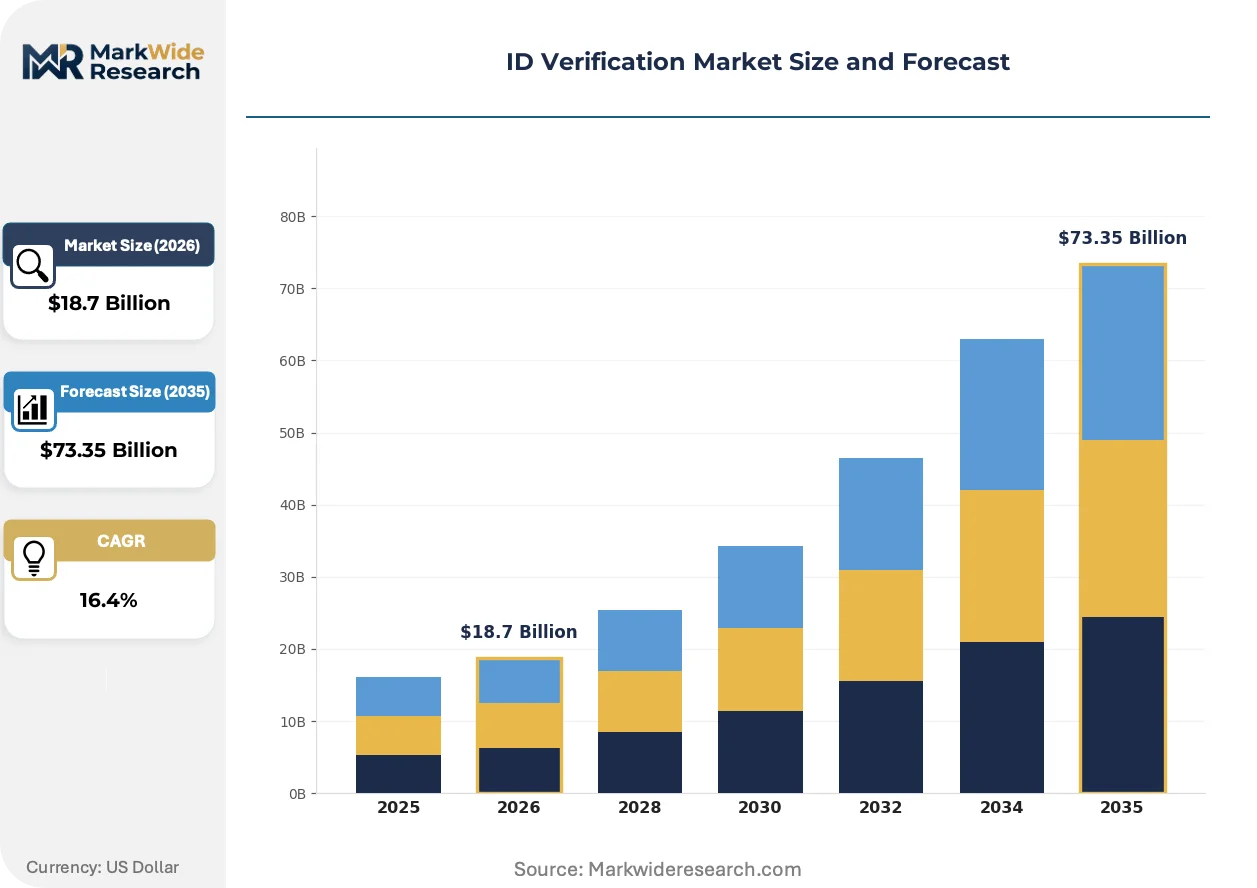
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Facial Recognition, Fingerprint Scanning, Document Verification, Biometric Authentication Application: Telecommunications, Financial Services, E-Commerce, Public Sector End User: Retailers, Government, Banks, Online Platforms Solution: Identity as a Service, On-Premises Solutions, Cloud-Based Solutions, Mobile Verification |
| Companies Covered | Jumio, Onfido, Mitek Systems, Trulioo, GBG, Experian, Equifax, Thales Group, IDEMIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ID Verification Market Strategic Shifts
Facial recognition SDKs embedded in native mobile operating systems are compressing hardware dependency while algorithmic transparency mandates reshape vendor documentation obligations.
Passive liveness detection is automating presentation attack detection without user gesture requirements. Tier-one retail banks in the United States and Germany are deploying these SDKs for frictionless account opening. The technology is automating the elimination of dedicated biometric hardware from mobile-first verification workflows.
The EU AI Act's high-risk classification for remote biometric identification mandates conformity assessments before European deployment. Industrial consequence includes mandatory human oversight protocols and algorithmic audit trails. Financial services and border control applications across France, Germany, and the Netherlands are restructuring procurement specifications to embed these compliance requirements.
Consumption patterns among enterprise buyers are compressing vendor selection cycles from multi-year framework agreements to pilot-to-production timelines under six months. Systems integrators and direct vendor relationships are displacing traditional reseller channels. This acceleration is most visible in Indian fintech and German neobank procurement where regulatory deadlines enforce rapid deployment decisions.
ID Verification Market Segmentation
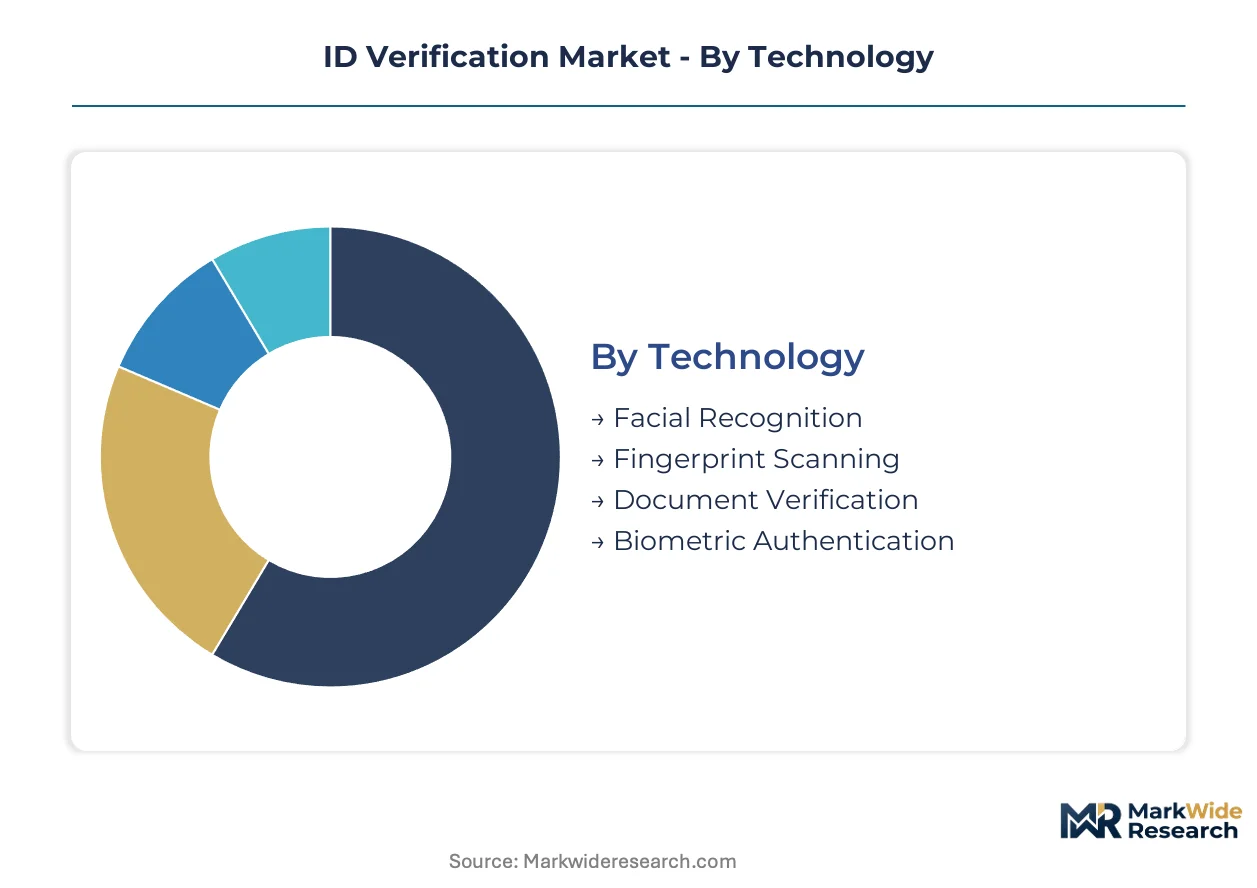
ID verification vendors configure product portfolios around four intersecting dimensions that determine deployment architecture and margin structure. Technology selection drives hardware requirements, while solution delivery models dictate recurring revenue potential versus perpetual license capture.
Technology:
Biometric modalities split between high-volume commodity capture and premium algorithmic differentiation, with liveness detection patents concentrating competitive advantage among facial recognition specialists.
- Facial Recognition:Passive liveness detection SDKs embedded in native mobile operating systems eliminate dedicated hardware from onboarding workflows. Tier-one retail banks in the United States and Germany deploy these for frictionless account opening, though deepfake presentation attacks demand continuous retraining investment.
- Biometric Authentication:Multi-modal fusion of facial templates with behavioral signals creates authentication resilience for high-value transactions. Indian fintech and telecom applications under UIDAI governance standardize on this layer for Aadhaar-linked verification.
- Fingerprint Scanning:Legacy modality retains deployment in physical access control and point-of-sale authentication where device fingerprint sensors exist.
- Document Verification:Forensic analysis of government-issued credentials sustains margin pools through persistent manual review requirements for edge-case formats.
Today's leader: Biometric Authentication. Tomorrow's challenger: Facial Recognition.
Application:
End-use concentration follows regulatory enforcement intensity, with financial compliance mandates generating procurement velocity that consumer-facing sectors cannot match.
- Financial Services:Anti-money laundering directives across Germany, the United States, and India mandate document verification deployment for digital customer onboarding. Procurement cycles compress from multi-year frameworks to pilot-to-production timelines under six months.
- Telecommunications:Subscriber identity verification for SIM registration drives biometric authentication volumes, particularly in Indian and Latin American markets where prepaid penetration remains elevated.
- E-Commerce:Account takeover prevention and seller verification create demand for low-friction identity binding without checkout abandonment.
- Public Sector:Border control and benefit distribution applications face EU AI Act high-risk classification requirements that restructure procurement specifications.
Financial Services commands current procurement velocity; E-Commerce represents the steepest expansion trajectory as marketplace fraud losses mount.
End User:
Customer archetypes diverge by integration complexity tolerance, with regulated institutions accepting longer deployment cycles for compliance documentation.
- Banks:Tier-one institutions anchor mobile capture SDK distribution while retiring legacy on-premises identity stacks for cloud-native architectures.
- Government:Border control and national ID programs demand algorithmic audit trails and human oversight protocols under EU AI Act mandates.
- Online Platforms:Marketplace operators prioritize speed-to-integration over forensic depth, favoring API-first verification orchestration.
- Retailers:Point-of-sale age verification and loyalty program enrollment drive lightweight biometric deployment without backend infrastructure investment.
Banks dominate contract value; Online Platforms are gaining share fastest through embedded finance expansion.
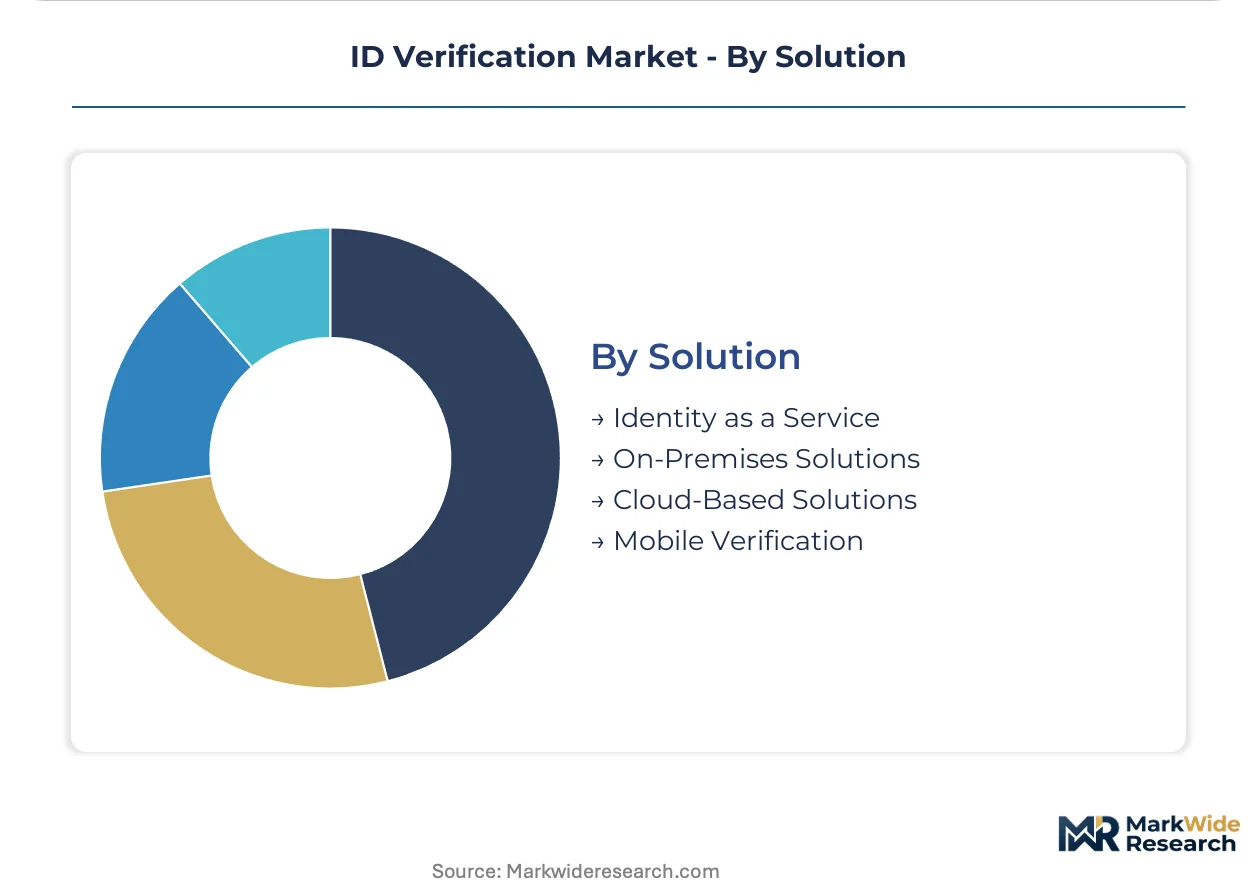
Solution:
Delivery architecture determines capital intensity and data sovereignty exposure, with sovereign cloud mandates fragmenting unified deployment stacks.
- Cloud-Based Solutions:Financial institutions accelerate migration from legacy on-premises systems, though cross-border data localization requirements in the European Union, India, and China inflate operational complexity.
- Identity as a Service:Subscription orchestration layers aggregate multiple verification modalities through single API contracts, displacing traditional reseller channels.
- Mobile Verification:Native SDK distribution captures device fingerprinting and behavioral biometrics without server-side processing latency.
- On-Premises Solutions:Regulated entities in defense and critical infrastructure retain air-gapped deployments despite higher total cost of ownership.
Cloud-Based Solutions anchor current deployment momentum; Identity as a Service models are climbing the fastest as procurement shifts toward outcome-based verification pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as compliance cost differentials between jurisdictions drive infrastructure localization decisions. Financial institutions now fragment unified identity stacks across sovereign data boundaries rather than consolidate under single cloud architectures.
United States
Tier-one retail banks accelerate cloud-native biometric migration while the FDA governs medical-adjacent authentication devices. Anti-money laundering directives from FinCEN compress procurement cycles below six months. The New York-Washington corridor anchors document forensics demand as neobanks displace legacy onboarding workflows.
Germany
Neobank procurement velocity exceeds traditional institutions as the KBA enforces automotive-grade identity verification for embedded finance. EU AI Act conformity assessments restructure vendor selection criteria before market entry. Frankfurt's fintech cluster concentrates liveness detection SDK deployment for frictionless account opening.
India
UIDAI-governed Aadhaar authentication protocols standardize biometric verification for fintech and telecom applications. The RBI mandates digital KYC for payment bank licensing. Mumbai and Bangalore anchor the fastest-growing mobile verification consumption as prepaid subscriber identity verification volumes surge.
Brazil
Underpenetrated digital onboarding markets attract liveness detection expansion as central bank regulations tighten payment provider identity requirements. Data localization mandates fragment cross-border verification architectures. São Paulo's fintech corridor concentrates API-first identity orchestration deployment for marketplace lending.
United Arab Emirates
MOHAP and central bank frameworks converge on biometric standards for health-finance integrated services. Free zone data sovereignty rules create hybrid deployment models. Dubai's digital government cluster anchors facial recognition procurement for border control and benefit distribution applications.
ID Verification Market Competitive Environment
United States vendors anchor the cloud-native tier; European specialists hold algorithmic differentiation through regulatory certification depth. Market structure concentrates around three tiers: identity-as-a-service orchestrators, document forensics incumbents, and biometric algorithm specialists. Strategic archetypes include API-first platforms, hardware-agnostic SDK providers, and vertically integrated security conglomerates. Competitive moves center on sovereign cloud partnerships and continuous algorithm retraining investment against synthetic fraud.
Within the document forensics tier, Mitek Systems and Onfido exemplify divergent positioning around mobile capture versus synthetic identity resistance. Jumio occupies the liveness detection patent concentration. These three anchors illustrate how vendor selection now hinges on EU AI Act documentation capabilities rather than feature parity alone.
| Leading Market Players |
|---|
| Jumio |
| Onfido |
| Mitek Systems |
| Trulioo |
| GBG |
| Experian |
| Equifax |
| Thales Group |
| IDEMIA |
| Others |
Value Chain & Pricing Dynamics
Algorithm engineering talent clusters in Bangalore and Tel Aviv compress development cost differentials between premium biometric SDK providers and mid-tier document forensics vendors, widening pricing-tier spreads as liveness detection patents concentrate competitive advantage.
Pricing Analysis
Distributor margins on identity-as-a-service orchestration layers typically capture 15-20 percent before enterprise end-user pricing, though direct API contracts displace traditional reseller channels. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified biometric suites from non-conformity-assessed alternatives and commodity document capture tools. Price differentiation hinges on algorithmic audit trail depth and cross-border data localization compliance coverage. Cost compression in the mid-tier document verification segment intensifies because persistent manual review requirements for edge-case credential formats sustain human-in-the-loop processing overhead. Banks and government entities exhibit lowest price sensitivity due to regulatory penalty exposure, while online platforms and retailers prioritize speed-to-integration over forensic depth.
Supply Chain Analysis
Facial recognition algorithm training data rests on annotated image datasets sourced from India, the United States, and Israel, with synthetic identity generation capabilities concentrated among specialized cybersecurity vendors in the United Kingdom and Singapore. Cloud compute infrastructure for biometric processing draws from hyperscaler regions in the United States, Germany, and India, though sovereign data mandates fragment unified deployment architectures. Single-source vulnerability in liveness detection patent licensing creates supply chain concentration risk for vendors lacking in-house algorithm development. Distribution runs through systems integrators and direct vendor relationships displacing traditional reseller channels, with procurement cycles compressing below six months in Indian fintech and German neobank segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ID verification market functions as a regulatory compounder where the EU AI Act's high-risk classification for remote biometric identification mandates conformity assessments that create certified vendor ecosystems and compliance-driven procurement velocity.
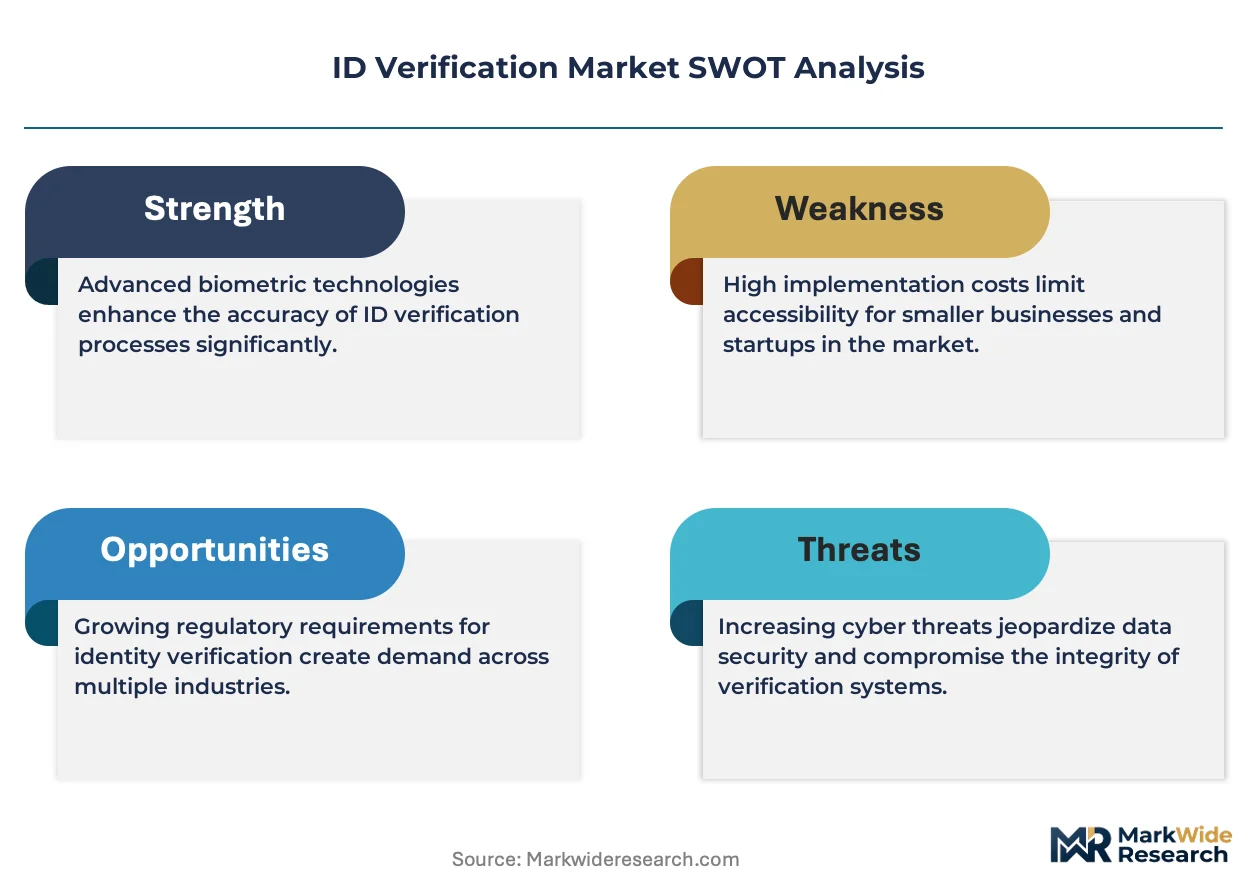
For Market Incumbents: Anticipate synthetic identity fraud sophistication eroding confidence in facial recognition systems by accelerating continuous algorithm retraining investment and securing liveness detection patent concentrations. Vertical integration into behavioral biometrics fusion creates defensive moats against API-first challengers. Cloud-native architecture migration without disrupting live transaction flows anchors retention of tier-one retail banking relationships. For New Entrants and Emerging Players: The EU AI Act in Germany, France, and the Netherlands opens a window for algorithmic transparency documentation capabilities scarce among mid-tier verification vendors. Latin American fintech corridors in Brazil and Mexico present the most penetrable geography for liveness detection SDK expansion. Go-to-market through embedded finance partnerships with neobanks bypasses lengthy traditional bank procurement frameworks. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking biometric algorithm capabilities to anchor sovereign data architectures. Over the medium-term horizon, target archetypes include document forensics vendors with synthetic identity resistance testing depth and passive liveness detection patent portfolios. The signal to watch is cross-border data localization mandate proliferation fragmenting unified identity stacks.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Mandatory certification before European market entry restructures vendor selection criteria across financial services and border control applications. |
| Passive Liveness Detection SDK Launch | Embedded native mobile operating system integration eliminates dedicated biometric hardware from tier-one retail bank onboarding workflows. |
| Sovereign Cloud Partnership | Data localization mandates in India, Germany, and the United Arab Emirates fragment unified deployment architectures across national boundaries. |
| Behavioral Biometrics Acquisition | Keystroke dynamics and device fingerprinting fusion creates multi-modal authentication white space in mobile banking transaction security. |
| Aadhaar Authentication Protocol Integration | UIDAI-governed standardization anchors biometric verification infrastructure for Indian fintech and telecom prepaid subscriber volumes. |
Study Parameters
Coverage spans the United States, Germany, India, Brazil, and the United Arab Emirates, with primary inputs from each market combining structured interviews with identity verification vendors, financial services compliance officers, biometric algorithm engineers, and systems integration specialists with secondary validation. Bottom-up demand modeling triangulates against top-down regulatory spend estimates using SEC filings from publicly traded identity technology vendors, UIDAI authentication volume disclosures, EU AI Act implementation guidance documents, and central bank digital KYC mandate announcements.
Granularity-level modeling disaggregates the projection horizon across biometric modality, solution delivery architecture, end-use application intensity, and regional regulatory enforcement stage. CAGRs derive from segment-level demand elasticity analysis against compliance deadline clustering. Forecast inputs incorporate Aadhaar authentication protocol adoption curves, neobank digital onboarding penetration rates, and synthetic identity fraud incident trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement timelines or sovereign data localization mandate proliferation beyond currently announced jurisdictions. A small set of named triggers warrants ongoing watch: deepfake presentation attack sophistication breakthroughs, cross-border biometric data transfer restriction expansions, and legacy identity stack migration disruption events at tier-one financial institutions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Global Biometrics Middleware Market