
 Global Personal Identity Management Market | 2026-2036
Global Personal Identity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Identity Management Market Foresight
Modular bundling of identity verification with fraud detection and access management is shifting enterprise procurement patterns toward integrated suites rather than point solutions. Okta leverages its workforce identity platform to anchor cloud-native deployments across mid-market and enterprise segments. Microsoft Corporation extends its Azure Active Directory ecosystem into consumer-facing and B2B identity orchestration. Socure differentiates through AI-native document and biometric verification tailored for financial services onboarding.
Personal Identity Management encompasses the technical systems, protocols, and governance frameworks that authenticate, authorize, and maintain persistent identity records across digital and physical channels, incorporating biometric hashing, cryptographic credential binding, and federated trust architectures to secure transactions and regulatory compliance. Identity verification solutions dominate current revenue pools due to KYC and AML mandates, while cloud-based deployment models represent the fastest-expanding structural segment as organizations retire legacy on-premises directories. Hybrid deployments occupy a narrowing but strategically important margin pool for regulated industries requiring data residency controls.
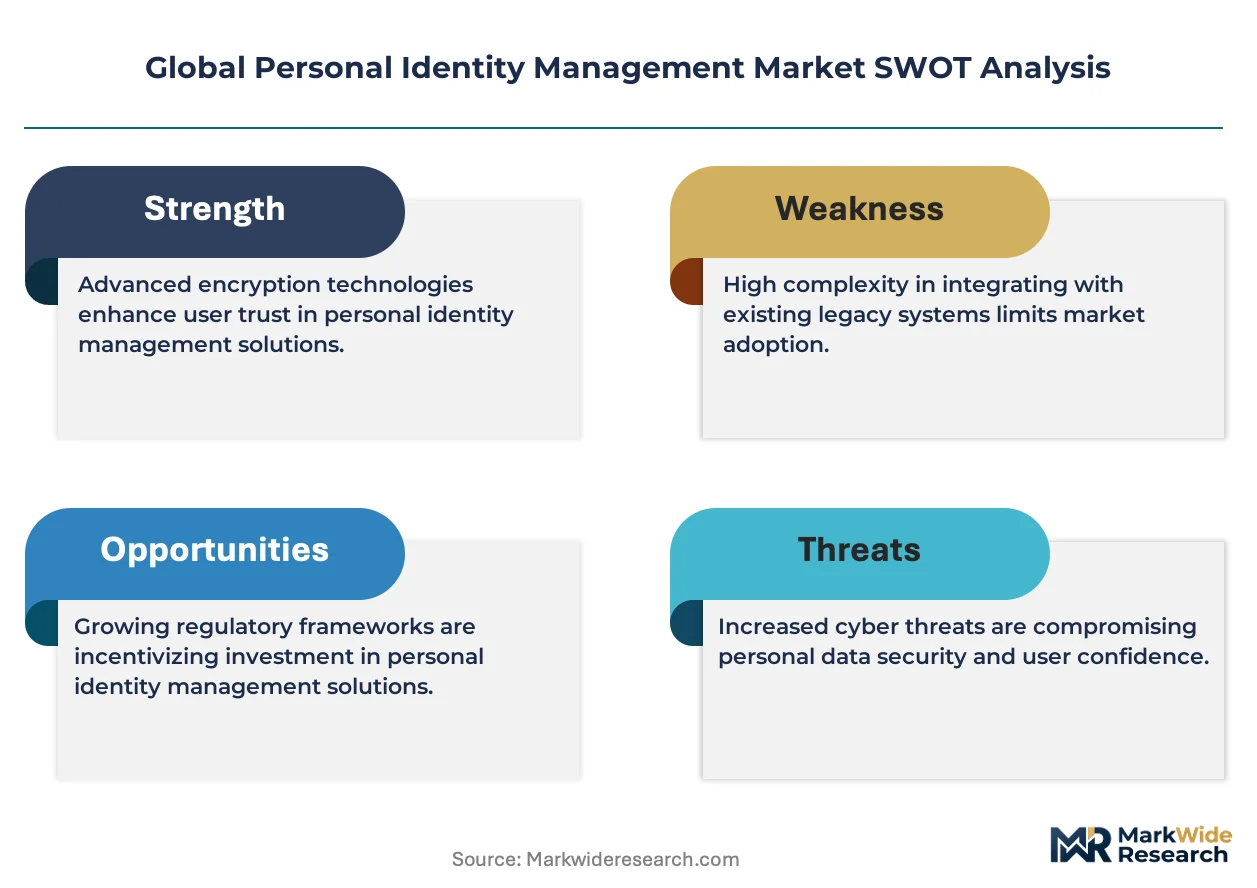
FDA oversight of biometric data in healthcare applications, GDPR data minimization requirements enforced by CNIL and other EU data protection authorities, and the EU AI Act's risk classification for automated identity systems collectively elevate compliance costs and reshape product roadmaps. ISO/IEC 27001 and NIST SP 800-63 standards further constrain architecture choices for vendors seeking cross-border certification. Stakeholders must monitor evolving interoperability mandates between national digital identity wallets and private-sector credential providers to anticipate channel displacement.
Market Dynamics
Modular identity verification suites are compressing procurement cycles as enterprises abandon fragmented point solutions for unified platforms that bundle biometric authentication, fraud detection, and access governance into single vendor relationships.
Growth Catalysts
- GDPR Article 7 Consent Frameworks:Financial services institutions across France, Germany, and Italy are expanding procurement of verifiable credential systems to demonstrate explicit user consent for automated identity processing.
- Biometric Hashing Maturation:Template protection algorithms now enable irreversible biometric storage that satisfies data minimization mandates while preserving matching accuracy for high-volume onboarding.
- Cloud-Native Directory Retirement:Mid-market enterprises in the United States are accelerating migration from on-premises Active Directory instances to SaaS identity fabrics.
Market Restraints
- EU AI Act Compliance Burden:Risk classification requirements for automated biometric identification systems impose documentation and human oversight costs that compress margins for verification vendors.
- Silicon Supply Concentration:Specialized secure element manufacturing for hardware security modules concentrates in Taiwan and South Korea, creating single-source vulnerability for cryptographic credential binding.
- Interoperability Fragmentation:Divergent national digital wallet specifications across EU member states prevent standardized API integration and force redundant certification investments.
Strategic Opportunities
- Brazil ANVISA Healthcare Pathway:Biometric patient identification for pharmaceutical dispensing remains underpenetrated relative to KYC saturation in banking.
- Zero-Trust Architecture Convergence:Identity orchestration platforms that unify workforce and consumer contexts are capturing budget previously siloed between HR and customer experience departments.
- India Digital Public Infrastructure:Aadhaar-linked verifiable credentials create regulatory tailwind for private-sector wallet providers integrating with the Open Network for Digital Commerce.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:Shortage of specialists capable of implementing NIST SP 800-63B authenticator assurance level 3 architectures delays product roadmaps.
- Legacy Mainframe Integration Friction:Core banking systems running COBOL-based identity registries resist API-native connectivity, forcing expensive middleware layers.
- Cross-Border Certification Timelines:ISO/IEC 27001 and SOC 2 Type II attestation cycles extend 14-18 months, gating revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Identity Management Market |
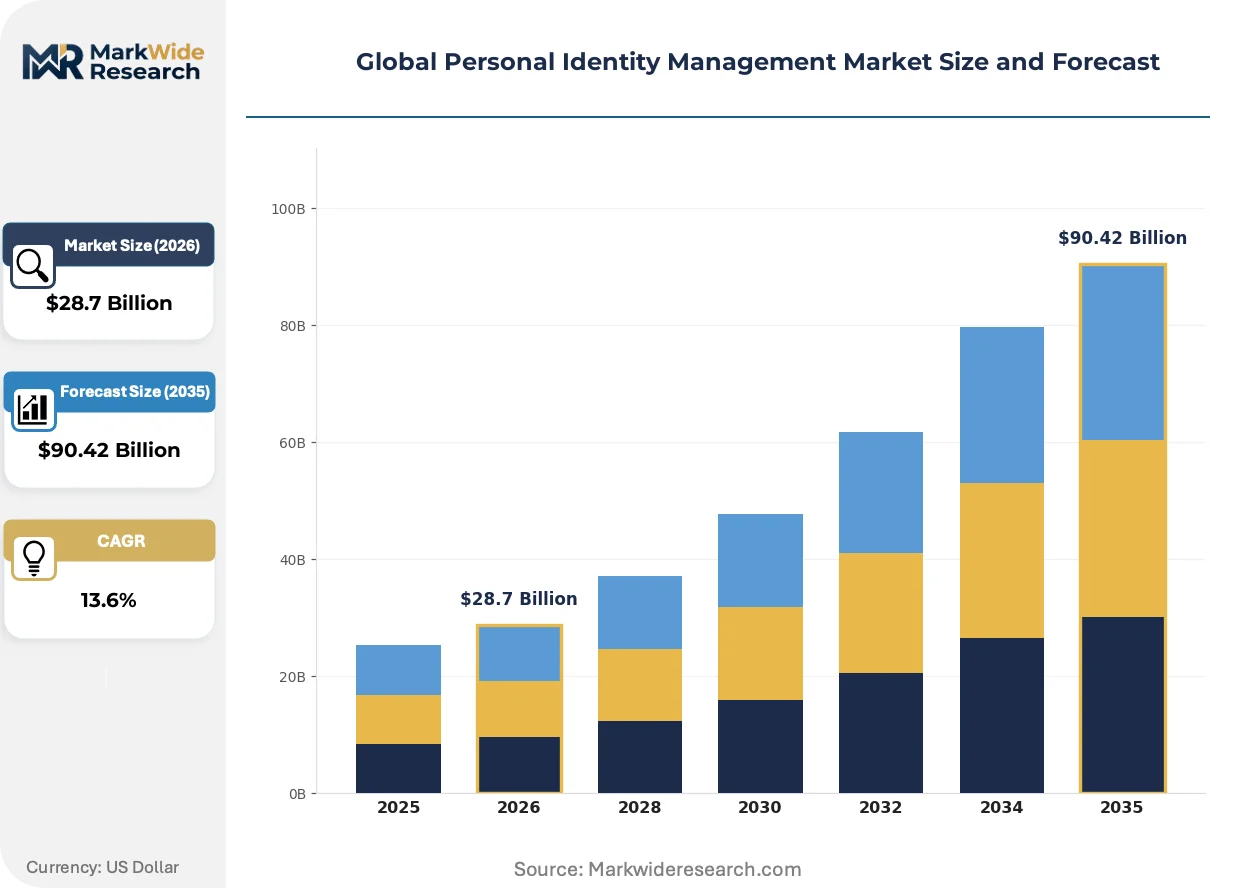
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $90.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
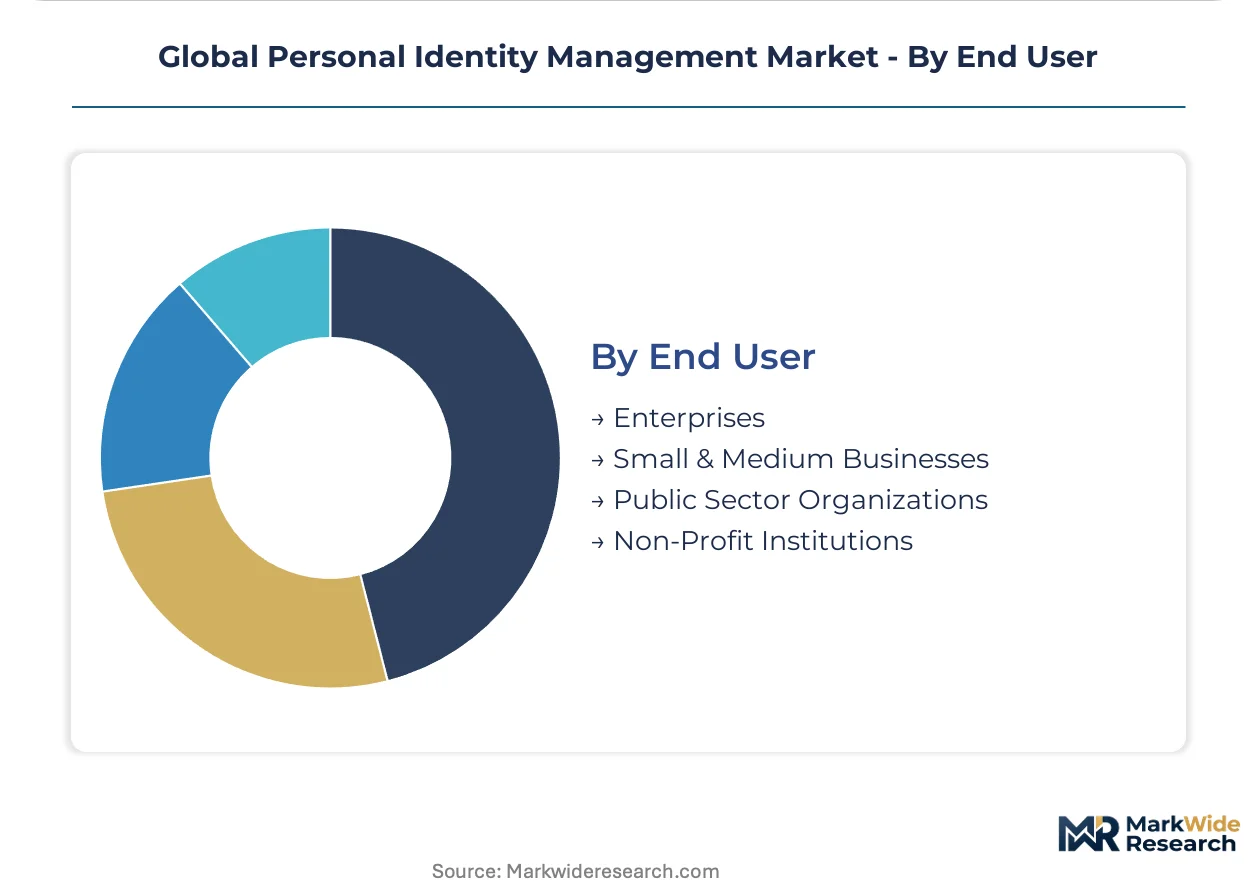
| Segmentation | Solution Type: Identity Verification, Access Management, Data Protection, Authentication Services, Fraud Detection Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services Application: Financial Services, Government Agencies, Telecommunications, Education, Hospitality End User: Enterprises, Small & Medium Businesses, Public Sector Organizations, Non-Profit Institutions |
| Companies Covered | Trulioo, ID.me, Okta, PXL Vision AG, SentiLink, Microsoft Corporation, Socure, CyberArk, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Identity Management Market Shifts & Advancements
Decentralized identity architectures are redistributing trust from centralized identity providers to user-controlled credential wallets, forcing incumbents to reposition around verification rather than custody.
Decentralized identifiers (DIDs) anchored on distributed ledger infrastructure are integrating selective disclosure protocols that let users prove attribute possession without revealing underlying data. Financial services onboarding teams in Singapore and Switzerland are piloting these flows for creditworthiness verification. This compression of data exposure is integrating privacy-by-design directly into authentication workflows rather than treating it as a compliance overlay.
The EU AI Act's risk-based classification system mandates conformity assessments for biometric identification systems deployed in publicly accessible spaces. Vendors must now maintain technical documentation, human oversight protocols, and accuracy benchmarking that exceed previous GDPR accountability requirements. High-risk system providers are responding by segmenting product lines between EU-compliant and non-EU variants to isolate certification scope.
Enterprise buyers are consolidating vendor relationships around platforms that unify workforce identity, customer identity, and privileged access management under single administrative consoles. This pattern displaces best-of-breed procurement that previously separated these functions across Okta, SailPoint, and CyberArk deployments. Manufacturing and energy verticals in Germany and Japan exhibit the strongest concentration momentum as operational technology convergence demands unified identity governance across IT and OT environments.
Global Personal Identity Management Market Segmentation

Segmentation in personal identity management reveals how procurement priorities diverge across technical architectures, regulatory exposures, and operational scale. Understanding these fault lines enables vendors to align R&D investment with segments where compliance mandates and security postures create durable pricing power.
Solution Type:
Capital intensity concentrates in biometric infrastructure and cryptographic key management systems, where specialized hardware and certification cycles demand substantial upfront commitment before revenue recognition becomes possible.
- Identity Verification:Document authentication, biometric matching, and liveness detection form the technical core. Financial services institutions in France and Germany are expanding procurement under GDPR Article 7 consent frameworks and the EU AI Act's risk classification requirements for automated biometric systems.
- Access Management:Directory services, single sign-on orchestration, and privileged session governance dominate enterprise IT budgets. Mid-market enterprises across the United States are accelerating cloud-native migrations as legacy on-premises Active Directory instances reach end-of-support timelines.
- Data Protection:Encryption key lifecycle management and tokenization services secure credential vaults. Healthcare providers face FDA oversight of biometric patient data alongside HIPAA security rule compliance.
- Authentication Services:Multi-factor credential delivery and passwordless FIDO2 implementations reduce phishing exposure. Telecommunications carriers in India integrate Aadhaar-linked verification for SIM registration mandates.
- Fraud Detection:Behavioral biometrics and device intelligence identify synthetic identity attacks. Brazilian banks deploy these layers against document fraud in credit onboarding workflows.
Identity verification absorbs the bulk of installed capacity; fraud detection is expanding most quickly as real-time transaction monitoring becomes mandatory across payment networks.
Deployment Model:
Operational complexity and data residency requirements create sharp divergence in total cost of ownership across deployment architectures, with compliance-sensitive industries maintaining hybrid configurations despite higher management overhead.
- Cloud-Based:SaaS identity fabrics deliver elastic scaling and continuous feature updates without infrastructure ownership. United States mid-market enterprises are retiring on-premises directories fastest, though EU AI Act documentation requirements complicate vendor selection.
- On-Premises:Dedicated hardware security modules and air-gapped credential storage satisfy classified government requirements. German manufacturing and energy verticals retain these deployments for operational technology convergence where IT-OT isolation remains non-negotiable.
- Hybrid:Split processing keeps sensitive biometric templates on-premises while leveraging cloud orchestration for authentication logic. Swiss financial institutions favor this architecture to satisfy FINMA data localization expectations without sacrificing agility.
- Managed Services:Third-party administration of identity infrastructure offloads scarce cryptographic engineering talent. Japanese enterprises utilize these arrangements to address NIST SP 800-63B authenticator assurance level 3 implementation gaps.
Cloud-based deployments capture the steepest expansion trajectory; hybrid configurations retain strategic importance in regulated European markets where data minimization mandates intersect with operational continuity requirements.
Application:
Regulatory enforcement intensity varies dramatically across verticals, with financial services and government agencies facing mandatory compliance timelines that accelerate procurement velocity relative to discretionary security spending in hospitality and education.
- Financial Services:KYC and AML mandates drive continuous identity verification investment. Singaporean banks pilot decentralized identifier flows for creditworthiness verification while maintaining MAS technology risk management compliance.
- Government Agencies:National digital identity wallets and border control systems demand sovereign credential infrastructure. India's Open Network for Digital Commerce creates integration opportunities for private-sector wallet providers linking to Aadhaar.
- Telecommunications:Subscriber identity verification for SIM registration and fraud prevention. Brazilian ANATEL enforcement of biometric activation requirements expands addressable market for document verification vendors.
- Education:Campus access control and student credential lifecycle management. Australian universities deploy these systems for international student visa compliance verification.
- Hospitality:Guest check-in automation and loyalty program identity binding. UAE hospitality operators integrate with federal digital identity infrastructure for streamlined border-crossing guest experiences.
Financial services maintains the largest committed budget pool; government agencies are gaining share fastest as national digital wallet programs accelerate procurement timelines.
End User:
Organizational scale determines procurement sophistication, with enterprises demanding unified platforms and smaller entities prioritizing cost-efficient point solutions despite integration friction.
- Enterprises:Unified workforce and consumer identity governance under single administrative consoles. Manufacturing conglomerates in Japan consolidate previously siloed Okta, SailPoint, and CyberArk deployments as OT convergence demands consistent policy enforcement.
- Small & Medium Businesses:Cloud-native SaaS identity suites with minimal configuration overhead. United States mid-market firms select these solutions to avoid on-premises hardware refresh cycles and scarce IT security hiring.
- Public Sector Organizations:Sovereign credential systems with domestic data residency guarantees. South Korean government agencies align procurement with resident registration number protection requirements under Personal Information Protection Act amendments.
- Non-Profit Institutions:Grant-funded security implementations with donor transparency obligations. European NGOs navigate GDPR accountability requirements for beneficiary data processing with limited compliance staffing.
Enterprises command the deepest vendor relationships and longest contract tenures; small and medium businesses are climbing the fastest as self-service SaaS procurement eliminates traditional enterprise sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solution development concentrates in the United States and Germany while consumption spreads across financial centers demanding localized compliance. European data residency requirements fragment deployment architectures. Asian markets scale national identity infrastructure ahead of private-sector integration maturity.
United States
Mid-market enterprises accelerate cloud-native directory retirement and SaaS identity procurement. NIST SP 800-63B guidelines shape authenticator assurance architectures for federal contractors. Silicon Valley vendors anchor workforce identity platform development while New York financial institutions drive fraud detection integration.
Germany
Manufacturing and energy verticals demand unified IT-OT identity governance for operational technology convergence. GDPR Article 7 consent frameworks and BSI technical guidelines enforce verifiable credential standards. Industrial clusters in Bavaria and North Rhine-Westphalia retain hybrid deployments for data residency compliance.
Singapore
Banks pilot decentralized identifier flows for creditworthiness verification while maintaining MAS technology risk management compliance. The Monetary Authority of Singapore mandates robust customer due diligence for digital onboarding. Financial institutions in the Marina Bay district integrate biometric liveness detection into retail banking applications.
India
Aadhaar-linked verifiable credentials create procurement tailwinds for private-sector wallet providers. RBI guidelines enforce video KYC for remote account opening. Technology vendors in Bangalore and Hyderabad develop API-native integrations with the Open Network for Digital Commerce infrastructure.
Switzerland
FINMA data localization expectations drive hybrid architecture adoption among private banking institutions. Swiss financial centers prioritize cryptographic credential binding for cross-border wealth management. Zurich and Geneva house specialized vendors serving vault-grade identity custody requirements.
Global Personal Identity Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across modular platform and point solution categories. Cloud-native workforce identity platforms command premium positioning against legacy directory vendors. Three strategic archetypes dominate: integrated suite providers, AI-native verification specialists, and privileged access incumbents. M&A activity concentrates on fraud detection capability acquisition and geographic expansion into regulated European markets.
Within the integrated platform tier, Microsoft Corporation and Okta occupy positions anchoring enterprise cloud migrations. Socure exemplifies the AI-native verification specialist archetype targeting financial services onboarding workflows. These three entities represent divergent strategic bets on bundling breadth versus algorithmic depth in customer acquisition.
| Leading Market Players |
|---|
| Trulioo |
| ID.me |
| Okta |
| PXL Vision AG |
| SentiLink |
| Microsoft Corporation |
| Socure |
| CyberArk |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Enterprise procurement consolidation around unified identity suites is compressing vendor margins and forcing specialization trade-offs, with cloud-native platforms absorbing pricing power while point solution providers retreat to premium certification tiers or exit.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects buyer consolidation onto Microsoft and Okta platforms, while premium pricing persists for AI-native verification specialists serving financial services compliance mandates. Three-tier pricing structure across enterprise, mid-market, and developer API levels stratifies by integration complexity and regulatory certification depth, with EU AI Act conformity documentation commanding substantial premiums. Cost-down pressure on legacy on-premises directory vendors accelerates as cloud migration deadlines approach, rendering perpetual license models increasingly untenable. Small and medium businesses exhibit highest price sensitivity, prioritizing per-seat subscription predictability over feature depth.
Supply Chain Analysis
Specialized secure element manufacturing for hardware security modules rests on concentrated fabrication capacity in Taiwan and South Korea, with cryptographic processor foundries drawing from advanced lithography nodes and tamper-resistant packaging expertise. Raw material dependencies span silicon wafers, rare earth elements for magnetic sensors, and specialized substrates for biometric sensor arrays. Single-source vulnerability in secure element supply creates exposure to geopolitical disruption and export control expansion. Distribution runs through direct enterprise sales forces for large deployments, supplemented by cloud marketplace channels and systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance documentation requirements and cloud platform consolidation are forcing weaker point solution vendors toward acquisition or exit, creating a narrowing window for strategic positioning.
For Market Incumbents: To counter decentralized identity architecture displacement, anchor cloud-native platforms with verifiable credential interoperability and deepen backward integration into biometric sensor supply chains. Prioritize certification investment for EU AI Act high-risk system conformity assessments to isolate compliant product lines from regulatory scope creep. For New Entrants and Emerging Players: Systems integrator partnerships offer the fastest path to enterprise procurement cycles without direct platform competition. Target Brazilian healthcare biometric patient identification and Indian Aadhaar-linked wallet integration as underpenetrated verticals where regulatory tailwinds outpace incumbent coverage. Lead with API-first developer tooling to bypass entrenched salesforce disadvantages. For Investors and Strategic Acquirers: The window for entry favors AI-native verification specialists with financial services density and existing EU certification coverage. Long-term viability hinges on platform consolidation plays that bridge workforce and consumer identity contexts. Watch for MAS or RBI regulatory announcements mandating specific biometric standards as inflection triggers for geographic expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | High-risk system documentation enables continued European market access for biometric verification vendors. |
| Cloud-Native Directory Migration | SaaS identity fabric procurement accelerates as United States mid-market Active Directory instances reach end-of-support. |
| Biometric Hashing R&D Investment | Template protection algorithms satisfy GDPR data minimization mandates while preserving matching accuracy. |
| Aadhaar Wallet Integration | Private-sector credential providers capture procurement tailwinds from India's Open Network for Digital Commerce expansion. |
| IT-OT Convergence Platform Development | Unified governance across manufacturing operational technology environments addresses German BSI technical guidelines. |
Research Methodology
Document review covered regulatory filings from FDA, EMA, and EU AI Act implementation guidance, complemented by interviews with identity platform CTOs, financial services compliance officers, biometric sensor procurement leads, and cloud marketplace channel partners. Secondary validation drew from SEC 10-K disclosures, NIST SP 800-63 documentation, and hyperscaler identity service revenue segment reporting. Bottom-up deployment model sizing and top-down enterprise IT budget allocation analysis were cross-referenced for triangulation.
Historical spending patterns across cloud migration cycles were cross-referenced against panel input from identity vendor sales leadership and enterprise architecture consultants. Segmentation dimensions modeled include solution type, deployment architecture, organizational scale tier, vertical regulatory exposure, and regional certification requirement intensity. CAGRs were derived from elasticity-adjusted adoption curves and compliance mandate enforcement timelines, with biometric hashing maturation and decentralized identifier pilot scale serving as technology-specific forecast inputs.
Caveats apply where EU AI Act enforcement intensity, secure element supply disruption, or national digital wallet interoperability standardization could materially shift the outlook. Forecasts reflect assumptions around procurement cycle duration and certification timeline stability. A small set of named triggers—ANVISA biometric healthcare mandates, MAS decentralized identifier guidance, and Taiwan semiconductor export controls—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
China Mobile Biometrics Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market