
 Mobile Biometrics Market | 2026-2036
Mobile Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Biometrics Market Outlook
OEM-direct licensing is reconfiguring how biometric algorithms reach smartphone manufacturers and enterprise mobility platforms. Apple Inc. controls its entire Face ID supply chain through proprietary sensor and neural engine design. Qualcomm Technologies Inc. competes by embedding fingerprint and iris capabilities directly into Snapdragon mobile platforms. NEC Corporation anchors large-scale government identity programs with its multimodal biometric engine.
Mobile biometrics encompasses fingerprint, facial, iris, and voice recognition modalities deployed on smartphones, tablets, and wearable devices for identity verification and access control. Systems typically operate through dedicated secure elements or trusted execution environments with match-on-sensor architectures to isolate biometric templates from host operating systems. Fingerprint recognition sustains the largest installed base due to mature capacitive and ultrasonic sensor economics, while facial recognition is displacing legacy modalities in premium handset tiers. Voice recognition occupies emerging niches in call center authentication and hands-free vehicle access, though accuracy constraints limit its role in high-assurance applications.
The EU AI Act classifies remote biometric identification as high-risk, forcing providers to maintain conformity assessment documentation and human oversight protocols. In the United States, NIST testing frameworks shape federal procurement criteria for mobile biometric accuracy and presentation attack detection. India's BIS certification and Aadhaar-linked digital identity infrastructure create a regulated demand channel for domestic and foreign vendors. Stakeholders must monitor divergence between privacy-first European standards and performance-centric Asian market requirements as deployment architectures fragment across jurisdictions.
Market Dynamics
The mobile biometrics sector is restructuring around secure element isolation architectures as regulatory mandates for data protection harden across jurisdictions. Vendors must now engineer match-on-sensor designs that keep biometric templates entirely off host processors to satisfy emerging certification requirements.
Growth Catalysts
- India's Aadhaar-linked digital identity infrastructure:The government's biometric enrollment program generates sustained procurement demand for multimodal authentication systems integrated with national ID databases.
- Fingerprint sensor economics:Mature capacitive and ultrasonic manufacturing processes have collapsed unit costs, enabling mid-tier smartphone penetration previously restricted to premium handsets.
- EU AI Act high-risk classification:The conformity assessment and human oversight mandates for remote biometric identification are forcing enterprise buyers toward certified vendor solutions with documented audit trails.
Market Restraints
- Secure element supply concentration:Taiwan and South Korea dominate fabrication of dedicated biometric security chips, creating single-source vulnerability for sensor-integrated designs.
- Presentation attack detection complexity:Deepfake and synthetic biometric spoofing techniques outpace liveness detection algorithm updates, degrading trust in facial recognition for high-assurance transactions.
- GDPR biometric data friction:The regulation's strict purpose limitation and storage minimization requirements impose architectural constraints that increase system integration costs for European deployments.
Strategic Opportunities
- Voice recognition in automotive access:Hands-free cabin entry and ignition authentication represent an underdeveloped application where accuracy trade-offs are acceptable against convenience gains.
- Germany's digital identity wallet rollout:The eIDAS 2.0 implementation creates regulatory tailwind for mobile biometric integration with sovereign credential systems.
- Convergence of iris and facial modalities:Multimodal fusion architectures combining near-infrared iris capture with RGB facial analysis are compressing false acceptance rates for border control and financial onboarding.
Industry Challenges
- Biometric algorithm engineer scarcity:The specialized mathematics and signal processing expertise required for template extraction and matching functions commands premium compensation, constraining vendor R&D scaling.
- ISO/IEC 30107-3 certification timelines:The presentation attack detection evaluation framework requires extended laboratory testing cycles that delay product launches and compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Biometrics Market |
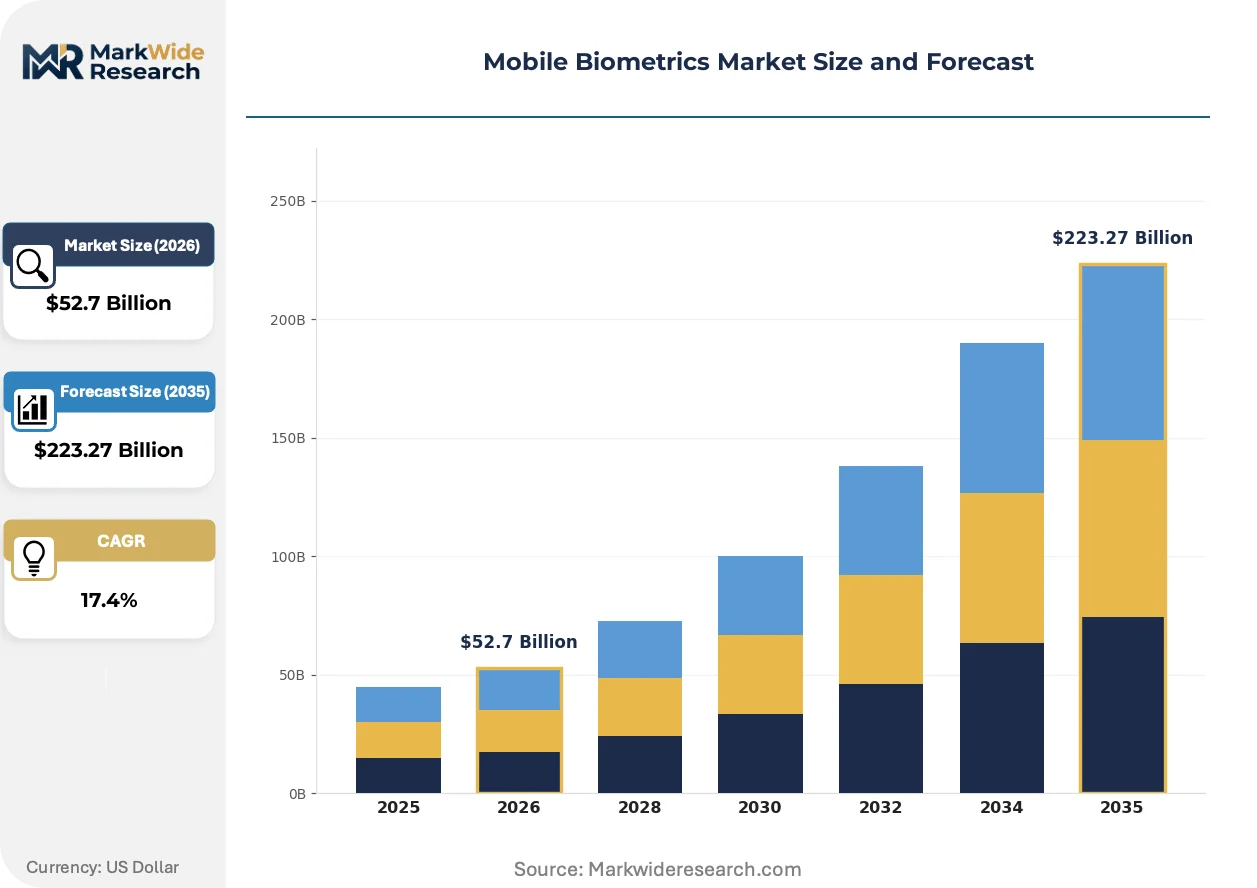
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $223.27 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint, Facial Recognition, Iris Recognition, Voice Recognition End User: Government, Healthcare, Finance, Retail Deployment: Cloud, On-Premises, Hybrid, Mobile Application: Access Control, Identity Verification, Payment Authentication, Time Tracking |
| Companies Covered | Apple Inc., NEC Corporation, Qualcomm Technologies Inc., IDEMIA, Aware Inc., Precise Biometrics AB, M2SYS Technology, HID Global Corporation, Fingerprint Cards AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Biometrics Market Strategic Shifts
Algorithm deployment models are fragmenting as on-device inference competes with cloud-based matching, forcing vendors to recalibrate hardware-software integration strategies. The tension between latency requirements and security architecture is driving heterogeneous computing designs.
Trusted execution environments are virtualizing secure biometric processing by isolating template storage and matching operations within hardware-enclaves separate from rich operating systems. Financial institutions in the United States are adopting these architectures for mobile payment authentication to satisfy FFIEC guidance on strong customer authentication. The approach compresses attack surfaces while complicating vendor certification against Common Criteria and GlobalPlatform standards.
The EU AI Act's high-risk classification for remote biometric identification mandates conformity assessment documentation, human oversight protocols, and fundamental rights impact assessments before deployment. Industrial consequence includes forced restructuring of vendor sales cycles to accommodate notified body review timelines. Cloud-based biometric service providers targeting European enterprise customers are responding by segmenting product lines between on-premise and SaaS delivery models with divergent compliance packaging.
Enterprise mobility buyers are consolidating vendor relationships around integrated platform providers capable of multimodal enrollment and cross-device synchronization. Traditional point-solution biometric specialists face displacement by OEMs and mobility platform vendors offering bundled authentication stacks. This concentration is most visible in North American financial services procurement, where CISOs prioritize single-source accountability for identity assurance across mobile and desktop endpoints.
Mobile Biometrics Market Segmentation
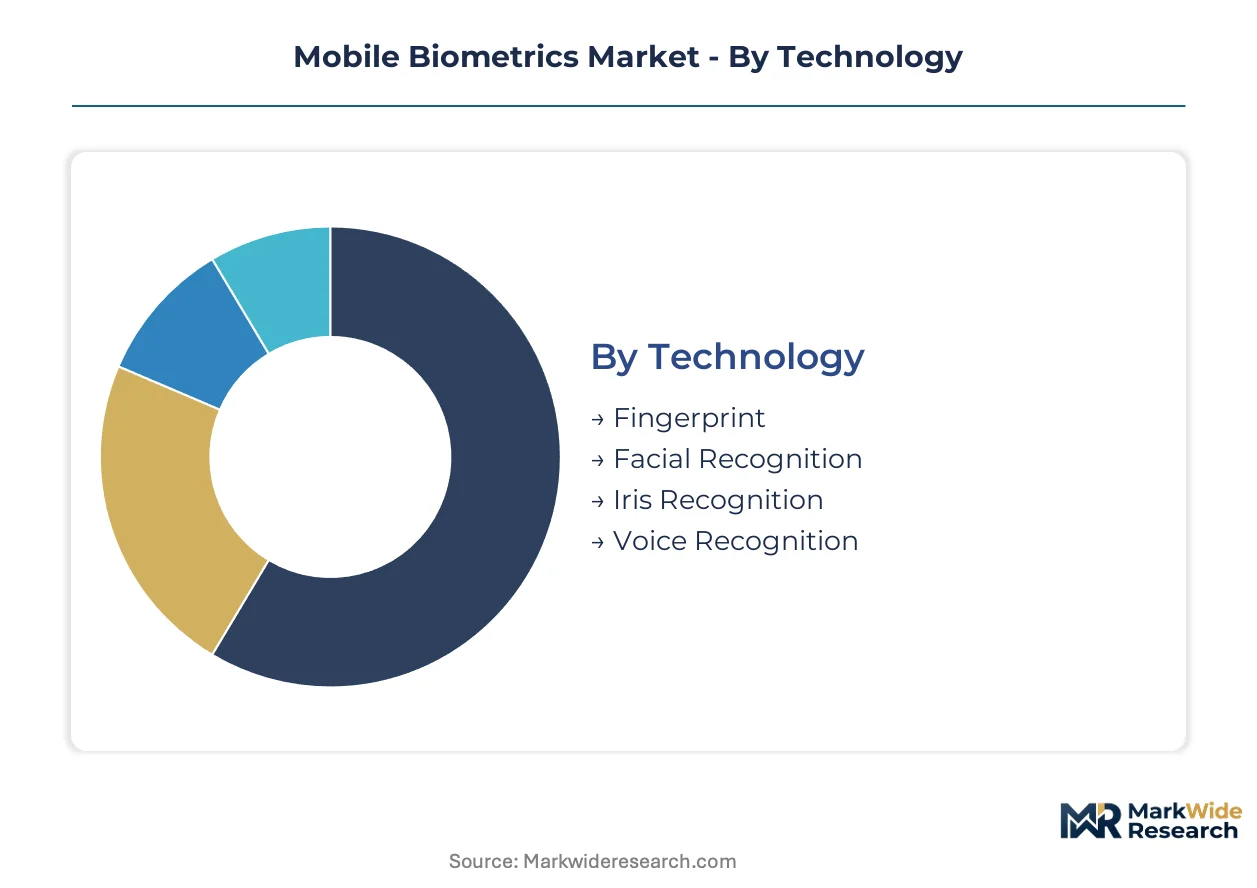
Mobile biometric architectures fragment across hardware modalities, regulatory environments, and integration depths. Understanding these segment boundaries clarifies where vendors must specialize versus where platform consolidation is compressing margins.
Technology:
Use cases span from high-throughput consumer unlocking to sovereign-grade identity assurance, with each modality carrying distinct sensor economics and spoofing vulnerability profiles.
- Fingerprint:Capacitive and ultrasonic sensors dominate smartphone integration due to mature fabrication economics. Mid-tier handset manufacturers in India and Southeast Asia drive procurement volume as unit costs collapse below premium-tier thresholds.
- Facial Recognition:Structured light and time-of-flight depth sensing enable 3D facial mapping for payment-grade assurance. Financial institutions in the United States and Germany favor this modality for mobile banking authentication under FFIEC and BSI guidance.
- Iris Recognition:Near-infrared capture delivers low false acceptance rates for border control and national ID programs. NEC Corporation and Idemia anchor government deployments in India and the Middle East.
- Voice Recognition:Text-dependent and text-independent algorithms target hands-free automotive and call center access. Accuracy constraints limit penetration to convenience-tier applications where liveness detection requirements are relaxed.
Established volume favors fingerprint; emerging adoption favors facial recognition.
End User:
Customer procurement authority varies from centralized federal tenders to distributed enterprise IT budgets, reshaping vendor sales motion and certification burden.
- Government:National ID programs and border control systems demand multimodal enrollment with sovereign data residency. India's Aadhaar infrastructure and Germany's eIDAS 2.0 wallet generate sustained procurement pipelines.
- Finance:Mobile payment authentication and KYC onboarding require ISO/IEC 30107-3 PAD certification and audit trail documentation. US banks under FFIEC guidance and EU institutions under EBA SCA rules drive compliance-heavy purchasing.
- Healthcare:Patient identity matching and prescription access control balance HIPAA privacy requirements against clinical workflow speed. US hospital systems lead adoption of palm-vein and facial modalities for EHR integration.
- Retail:Loyalty program enrollment and frictionless checkout prioritize speed over assurance. Convenience store chains and quick-service restaurants in Japan and South Korea pilot facial payment terminals.
Finance concentrates R&D investment; retail is expanding most quickly as sensor costs enable mass-market deployment.
Deployment:
Architecture choices determine where biometric templates reside, with direct consequences for latency, breach exposure, and regulatory compliance scope.
- Cloud:Centralized matching enables cross-device synchronization and rapid algorithm updates. EU AI Act high-risk classification forces European enterprise buyers toward human oversight protocols and fundamental rights impact assessments.
- On-Premises:Air-gapped installations satisfy data sovereignty requirements in defense and intelligence contexts. Germany and France mandate this architecture for sensitive federal biometric databases.
- Hybrid:Edge enrollment with cloud backup balances performance against compliance flexibility. US financial institutions favor this model to satisfy FFIEC guidance while enabling mobile scalability.
- Mobile:Match-on-sensor and trusted execution environment architectures isolate templates from host operating systems. Smartphone OEMs and enterprise mobility platforms standardize on this approach for consumer and workforce authentication.
Mobile dominates consumer volume; hybrid gains share fastest in regulated enterprise segments.
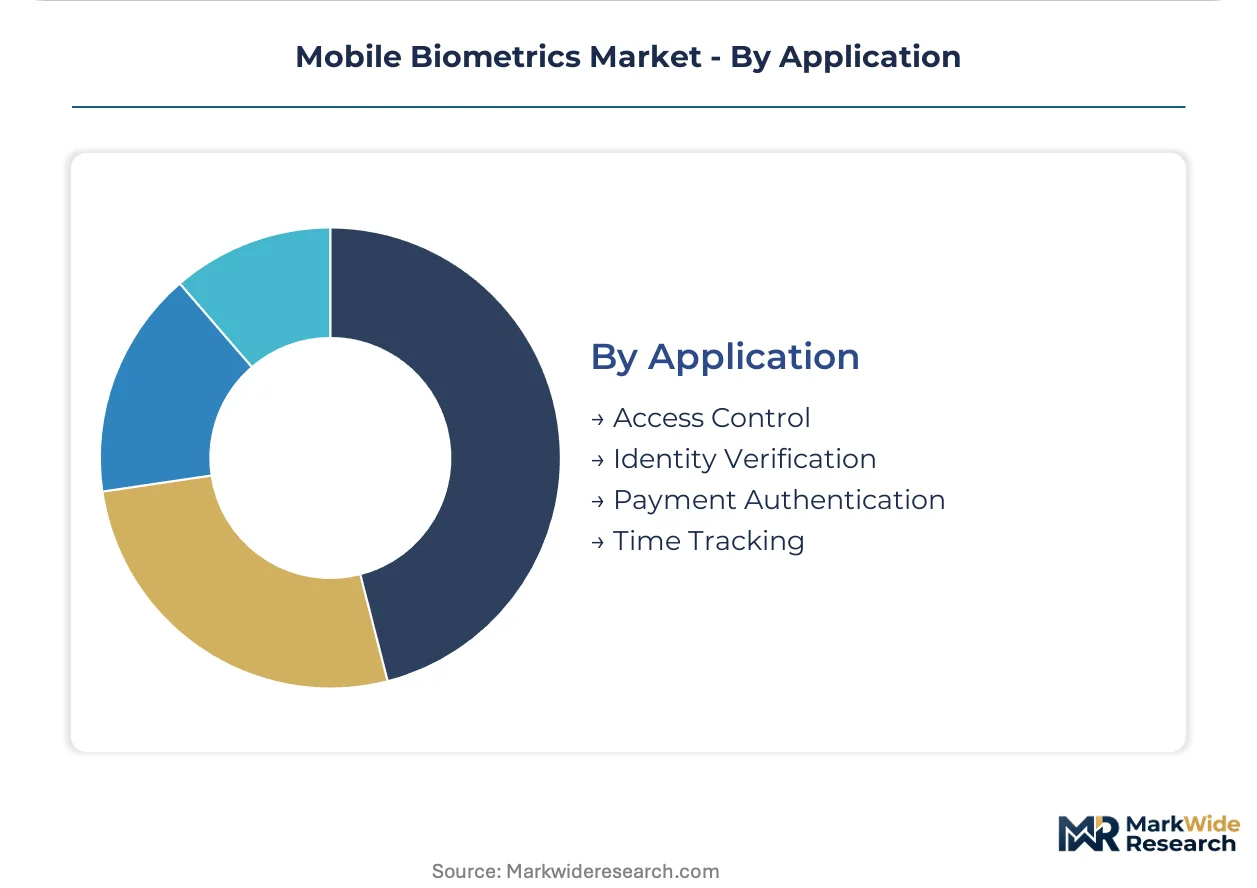
Application:
Functional requirements range from sub-second unlocking to forensic-grade identity binding, with each use case imposing distinct accuracy and audit specifications.
- Access Control:Physical and logical entry systems prioritize throughput and anti-tailgating measures. Corporate campuses and data centers in the United States and Germany deploy multimodal gates for workforce entry.
- Identity Verification:1:1 and 1:N matching against government databases underpins digital onboarding and border crossing. India's DigiYatra and EU EES entry-exit systems anchor large-scale deployments.
- Payment Authentication:Strong customer authentication under PSD2 and equivalent frameworks drives mobile wallet integration. US card networks and Indian UPI infrastructure mandate biometric verification for high-value transactions.
- Time Tracking:Workforce attendance and shift management emphasize cost minimization over spoofing resistance. Construction and logistics sectors in Brazil and Mexico adopt fingerprint terminals for payroll integration.
Access control holds mature installed base; payment authentication shows steepest expansion trajectory as regulatory mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by substantial margins, reflecting divergent certification burdens and enterprise procurement sophistication. German buyers command premium-tier vendor attention through sovereign digital identity mandates. Chinese smartphone OEMs compress component costs through captive sensor fabrication.
United States
Financial institutions under FFIEC guidance drive enterprise-grade facial recognition procurement for mobile banking authentication. NIST testing frameworks shape federal procurement criteria for accuracy and presentation attack detection. California's technology corridor hosts development centers for multimodal fusion architectures serving card networks and federal agencies.
Germany
eIDAS 2.0 wallet implementation creates regulatory tailwind for biometric integration with sovereign credential systems. BSI technical guidelines mandate liveness detection standards for payment-grade deployments. Berlin-Brandenburg clusters concentrate vendors engineering trusted execution environments for European financial institutions.
India
Aadhaar-linked digital identity infrastructure generates sustained procurement demand for multimodal authentication systems. BIS certification requirements and RBI mobile payment rules shape vendor qualification pathways. Karnataka's Bangalore corridor anchors domestic engineering centers serving national ID database integration projects.
China
Smartphone OEMs drive volume procurement of ultrasonic fingerprint sensors through captive supply chain control. MIIT cybersecurity standards mandate local data residency for biometric template storage. Shenzhen's Pearl River Delta manufacturing ecosystem dominates capacitive sensor module assembly for mid-tier handset exports.
Japan
METI industrial standards guide automotive biometric adoption for hands-free cabin entry systems. JIS certification requirements structure vendor qualification for financial services deployments. Tokyo-Osaka metropolitan corridors host integration specialists serving convenience store facial payment terminal pilots.
Mobile Biometrics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in sensor and algorithm licensing. The structure concentrates around OEM-direct relationships and government identity program anchors. Three archetypes dominate: proprietary ecosystem owners, multimodal engine specialists, and sensor-integrated semiconductor platforms. Competitive moves center on strategic partnerships for certification bundling and geographic licensing expansion into regulated national ID programs.
Within the proprietary ecosystem tier, Apple Inc. exemplifies closed-loop control over biometric hardware-software integration. NEC Corporation anchors large-scale government identity deployments through its multimodal engine specialization. Qualcomm Technologies Inc. occupies a position bridging semiconductor platforms and embedded biometric capabilities for Android OEMs.
| Leading Market Players |
|---|
| Apple Inc. |
| NEC Corporation |
| Qualcomm Technologies Inc. |
| IDEMIA |
| Aware Inc. |
| Precise Biometrics AB |
| M2SYS Technology |
| HID Global Corporation |
| Fingerprint Cards AB |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's Pearl River Delta manufacturing ecosystem anchors capacitive fingerprint sensor module assembly, with its capacity utilization rates directly compressing unit economics for mid-tier smartphone OEMs and downstream biometric system integrators.
Pricing Analysis
The customization-premium spread separates ISO/IEC 30107-3 PAD-certified multimodal engines from commodity fingerprint licensing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales algorithm update commitments. Pricing pressure stems from Indian and Southeast Asian handset manufacturers demanding sub-dollar sensor economics. Government and finance segments show least price sensitivity due to sovereign data residency mandates.
Supply Chain Analysis
Supplier-financing facilities from Taiwan and South Korean foundries extend 90-120 day payment terms to sensor-integrated security chip designers. Component flows draw from Taiwan, South Korea, and China for secure element fabrication, with sapphire cover glass and near-infrared emitters as critical inputs. Single-source vulnerability concentrates in TSMC-class foundry capacity for match-on-sensor ASICs. Distribution runs through OEM-direct licensing and government tender channels rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm update subscriptions and certified integration services are expanding faster than hardware royalties, creating durable recurring revenue layers for vendors with conformance assessment documentation capabilities.
For Market Incumbents: Entrench multimodal fusion architectures through backward integration into secure element design, countering Qualcomm's Snapdragon-embedded biometric capabilities. Lock in government identity program anchors with sovereign data residency architectures before eIDAS 2.0 wallet procurement accelerates. Certification investment in EU AI Act conformity assessment pathways represents the critical defensive lever. For New Entrants and Emerging Players: Voice recognition modules for automotive cabin access in Japan and Germany represent the most penetrable entry point, given relaxed liveness detection requirements and METI/BSI regulatory tailwinds. Mid-tier Indian smartphone OEMs seeking Aadhaar-compatible fingerprint sensors offer second-mover licensing opportunities. Go-to-market should emphasize royalty-based algorithm licensing rather than capital-intensive sensor manufacturing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors trusted execution environment specialists with Common Criteria certification pipelines. Long-term viability hinges on convergence toward multimodal platforms serving regulated finance and government segments. Acquisition targets should demonstrate documented audit trails and notified body relationships. Watch ISO/IEC 30107-3 certification backlogs as an inflection signal for vendor revenue recognition compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Qualcomm's Snapdragon biometric embedding forces OEM licensing consolidation across Android ecosystems. |
| Regulatory Certification Pathway | EU AI Act conformity assessment documentation separates bankable vendors from compliance-lagged competitors. |
| Strategic Partnership | NEC's government identity program anchors create defensive moats against semiconductor platform entrants. |
| Acquisition of Specialist Firm | Voice recognition algorithm shops enable automotive biometric diversification for Tier 1 suppliers. |
| Geographic Expansion | Germany's eIDAS 2.0 wallet rollout demands Berlin-Brandenburg engineering presence for BSI compliance. |
Study Parameters
The analysis maps fingerprint, facial, iris, and voice recognition modalities, each validated through biometric algorithm engineers, smartphone OEM procurement leads, government identity program managers, and financial services CISOs. Primary interviews with these stakeholders combined with secondary validation against NIST test reports, EU notified body documentation, BIS certification records, and SEC semiconductor filings. Bottom-up sensor shipment triangulation against top-down authentication transaction estimates anchored market sizing.
Assumption sets held regulatory enforcement timelines and smartphone penetration curves fixed while varying enterprise mobility adoption rates and presentation attack detection algorithm advancement. The projection horizon spans technology, end user, deployment, and application dimensions alongside regional regulatory cluster differentiation. CAGRs derived from logistic diffusion curves fitted to modality-specific replacement cycles and national ID program procurement pipelines. Match-on-sensor architecture adoption and multimodal fusion penetration served as key forecast inputs.
Stress conditions across EU AI Act implementation rigor, secure element foundry capacity constraints, and deepfake spoofing sophistication were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic downturn affecting enterprise IT security budgets, regulatory fragmentation between privacy-first European and performance-centric Asian standards, or breakthrough liveness detection algorithms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Global Personal Identity Management Market