
 Asia-Pacific Government and Security Biometrics Market | 2026-2036
Asia-Pacific Government and Security Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Government and Security Biometrics Market Insights
Government procurement channels across the Asia-Pacific are reshaping how biometric vendors engage with defense and homeland security buyers. NEC Corporation leverages its longstanding relationships with Japanese law enforcement agencies to sustain dominant positioning in facial recognition deployments. Fujitsu Ltd anchors its regional footprint through specialized palm-vein authentication systems for high-security government facilities. IDEMIA competes aggressively on manufacturing scale, supplying fingerprint enrollment kits to immigration authorities across multiple jurisdictions.
Government and security biometrics encompass automated identity verification systems that capture, process, and match physiological or behavioral characteristics against enrolled templates, typically operating with false acceptance rates below 0.001% for critical access control applications. These systems serve primary functions of secure identity assertion, forensic investigation support, and border management automation across public sector environments. Fingerprint recognition retains the largest installed base among technology segments due to legacy infrastructure and cost efficiency, though facial recognition captures the fastest growth trajectory driven by contactless deployment mandates. Among end users, immigration control generates the most concentrated margin pools as agencies prioritize multimodal systems capable of operating across diverse demographic populations and environmental conditions.
Australia's TGA-equivalent data governance frameworks, India's UIDAI operational standards, and China's SAMR certification requirements collectively determine product eligibility and data handling protocols for biometric vendors serving Asia-Pacific governments. Compliance with these overlapping regimes necessitates localized engineering investment and fragmented certification pathways that favor established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving cross-border data flow restrictions and sovereign cloud mandates that threaten to bifurcate previously integrated regional supply chains.
Market Dynamics
Contactless biometric deployment mandates across Asia-Pacific immigration authorities are compressing procurement cycles and favoring vendors with pre-certified multimodal platforms over point-solution specialists.
Growth Catalysts
- Australia's defense modernization:Canberra's strategic capability investments are generating sustained demand for high-assurance biometric access control across military installations and classified facilities.
- India's UIDAI operational standards:The authority's authentication transaction volumes exceeding billions annually create recurring infrastructure refresh requirements for fingerprint and iris matching hardware.
- Facial recognition algorithms:Accuracy improvements in liveness detection and demographic equity are enabling deployment across outdoor border checkpoints previously limited to controlled indoor environments.
Market Restraints
- Semiconductor supply concentration:Specialized image sensors and edge AI processors for biometric terminals depend heavily on Taiwan and South Korea fabrication capacity, exposing procurement timelines to geopolitical disruption.
- China's SAMR certification complexity:National standard GB/T 26237 compliance testing for biometric data protection extends vendor onboarding by 12-18 months versus non-regulated markets.
- Template storage costs:Multimodal systems generating multiple biometric signatures per enrollment strain sovereign cloud infrastructure budgets in Indonesia and Vietnam.
Strategic Opportunities
- Vietnam's national ID rollout:The country's chip-based identity card program represents underpenetrated volume for fingerprint enrollment kits and secure personalization equipment.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis layered atop physiological modalities offer continuous authentication for critical government network access.
- Japan's JIS standards harmonization:METI-led alignment of domestic biometric specifications with international frameworks reduces export friction for compliant vendors.
Industry Challenges
- Algorithm bias remediation:Training data deficiencies for South Asian and Southeast Asian demographic groups require sustained R&D investment to meet equity thresholds in Australian and Indian tenders.
- Cross-border data flow restrictions:Fragmenting sovereign cloud mandates between Australia's TGA-equivalent frameworks, India's data localization rules, and China's cybersecurity law complicate regional service architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Government and Security Biometrics Market |
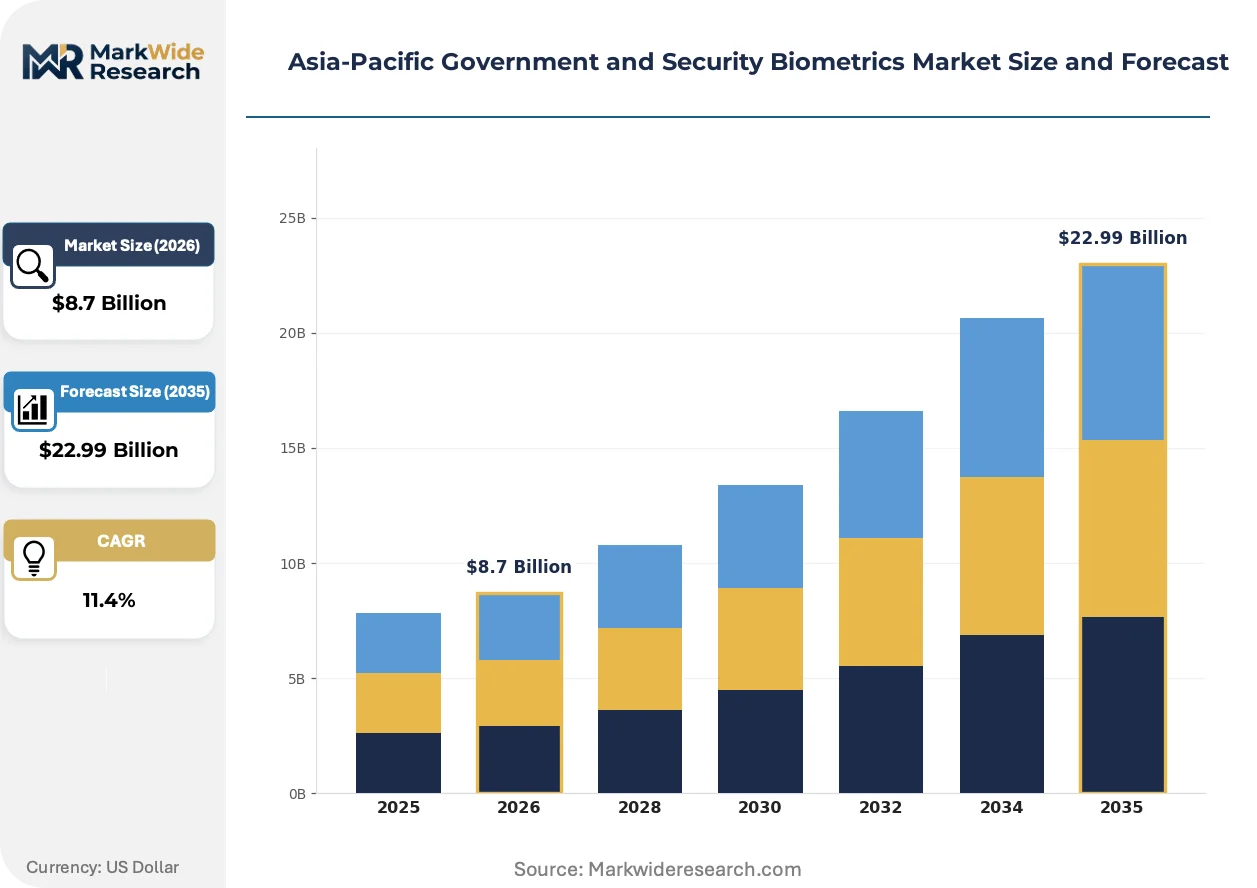
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Iris Recognition, Facial Recognition, Voice Recognition End User: Government Agencies, Defense Sector, Law Enforcement, Immigration Control Application: Access Control, Time & Attendance, Voter Verification, Identity Management Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | NEC Corporation, Fujitsu Ltd, IDEMIA, Suprema Inc., ZKTeco, Hitachi, Panasonic Corporation, Thales Group, HID Global, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Government and Security Biometrics Market Trends and Innovations
Edge AI inference is relocating biometric matching from centralized data centers to field-deployable terminals, altering hardware specifications and vendor margin structures across Asia-Pacific government procurement.
Multimodal fusion architectures combining facial, iris, and voice biometrics are digitizing identity verification workflows at land border crossings in Thailand and Malaysia. Immigration agencies in these markets are retiring fingerprint-only lanes within 24-month replacement cycles. This compression is digitizing vendor competitive advantage toward software-defined enrollment flexibility rather than hardware durability.
China's GB standards for biometric data protection and Australia's equivalent TGA-aligned privacy frameworks are mandating template encryption and decentralized storage architectures. Vendors must engineer separate product variants for each jurisdiction's certification pathway. Defense and homeland security buyers in both markets are prioritizing suppliers with established in-country engineering presence over offshore configuration support.
Subscription-based authentication service models are displacing perpetual license sales in mid-tier government agencies across Indonesia and the Philippines. Channel partners with managed security service capabilities are capturing recurring revenue streams previously retained by original equipment manufacturers. This shift concentrates most visibly in provincial government digitization programs where capital expenditure constraints favor operational expenditure accounting treatment.
Asia-Pacific Government and Security Biometrics Market Segmentation
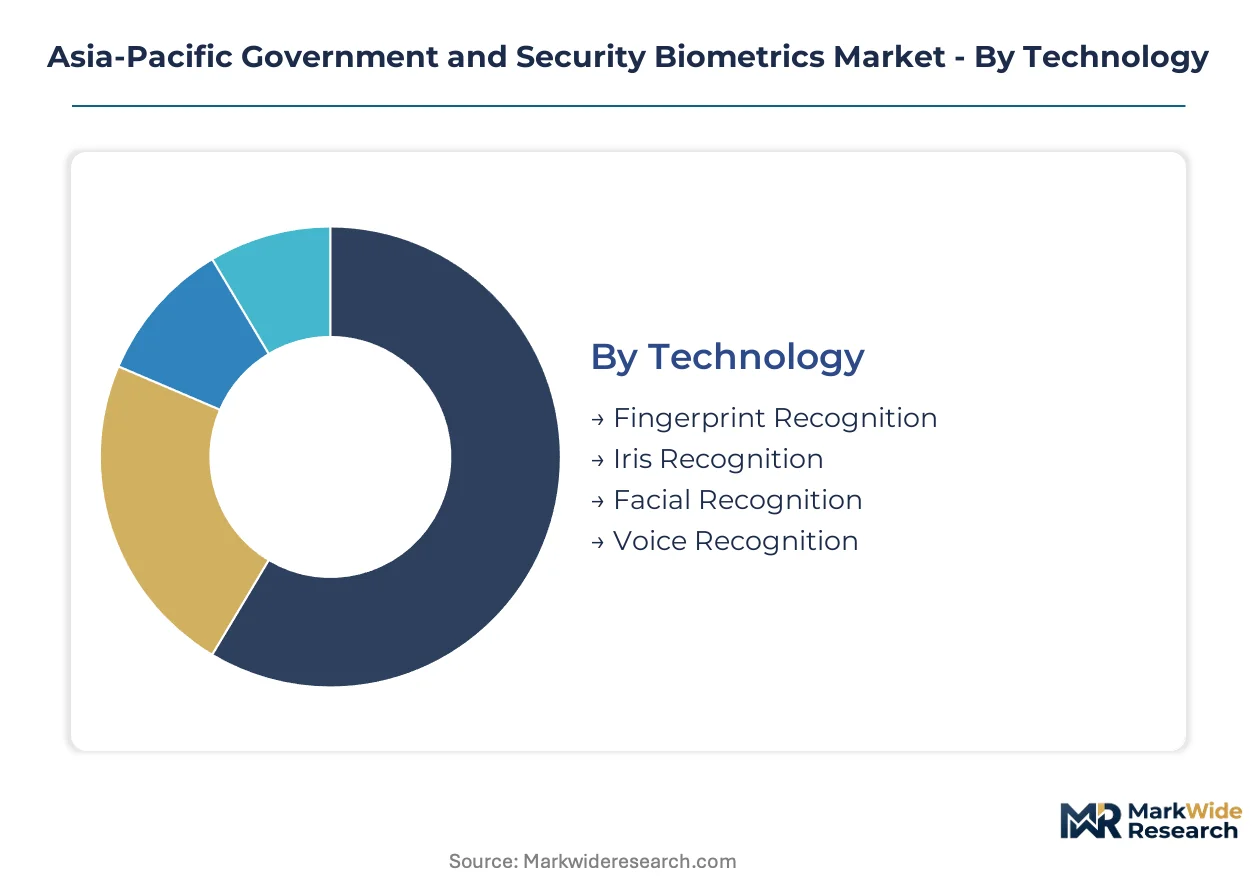
Technology refresh cycles vary dramatically across biometric modalities, with hardware replacement timelines stretching from three years for fingerprint terminals to eighteen months for facial recognition systems chasing algorithm improvements. Procurement officers in Asia-Pacific immigration agencies and defense ministries weight these depreciation schedules against sovereign cloud infrastructure constraints when allocating capital budgets across technology categories.
Technology:
Replacement velocity separates segments: fingerprint hardware endures longest in field conditions while facial recognition systems turn over fastest as liveness detection algorithms advance.
- Fingerprint Recognition:Optical and capacitive sensors capture ridge patterns with established interoperability across legacy AFIS databases. Immigration authorities in India and Australia favor this modality for indoor enrollment stations where contact-based collection remains operationally acceptable.
- Facial Recognition:Convolutional neural networks process visible and near-infrared spectrum imagery for one-to-many identification at outdoor border checkpoints. Southeast Asian agencies are expanding procurement of these contactless systems following pandemic-era hygiene mandates.
- Iris Recognition:Pattern matching from near-infrared ocular imaging delivers high accuracy for high-security defense facilities requiring low false acceptance rates.
- Voice Recognition:Spectral analysis of speech characteristics supports remote authentication for telephone-based government service delivery.
Fingerprint recognition dominates installed base. Facial recognition is where expansion concentrates.
End User:
Budget authority and procurement sophistication diverge sharply between centralized national programs and distributed provincial implementations.
- Government Agencies:National identity authorities in India and Vietnam drive volume procurement of enrollment kits and authentication infrastructure through centralized tender processes with multi-year frameworks.
- Defense Sector:Classified facility access control in Australia and Japan demands biometric systems with Tempest shielding and tamper-evident hardware meeting military-grade physical security specifications.
- Law Enforcement:Forensic identification units require rapid mobile biometric matching capabilities for field deployment during criminal investigations.
- Immigration Control:Border management agencies prioritize multimodal platforms capable of processing diverse demographic populations across environmental conditions ranging from tropical humidity to temperate coastal climates.
Immigration control commands premium pricing. Government agencies deliver volume scale.
Application:
Functional requirements dictate sensor specifications and integration complexity across use cases.
- Access Control:Physical perimeter security at defense installations and government data centers drives demand for multi-factor biometric authentication with audit trail logging.
- Time & Attendance:Civil service workforce management applications favor cost-optimized fingerprint terminals with offline capability for remote field offices.
- Voter Verification:Election commission deployments in Indonesia and the Philippines require ruggedized mobile biometric kits for polling station authentication with cellular backhaul.
- Identity Management:National ID program backends in India and Vietnam integrate multimodal biometric databases with deduplication algorithms preventing duplicate enrollments.
Identity management anchors backend infrastructure investment. Access control generates highest per-unit system value.
Deployment:
Data sovereignty regulations fragment cloud architecture choices across Asia-Pacific jurisdictions.
- On-Premises:Defense and intelligence agencies mandate air-gapped biometric matching systems with no external network connectivity for classified biometric template storage.
- Cloud-Based:Australia's TGA-equivalent privacy frameworks and India's data localization rules restrict cross-border biometric data flows, compelling vendors to establish in-country sovereign cloud instances.
- Hybrid:Enrollment occurs at distributed field stations with template encryption, while matching workloads shift between edge terminals and centralized infrastructure based on latency requirements.
- Mobile Solutions:Ruggedized smartphones with attached biometric peripherals enable law enforcement and election officials to capture and match identities outside fixed infrastructure.
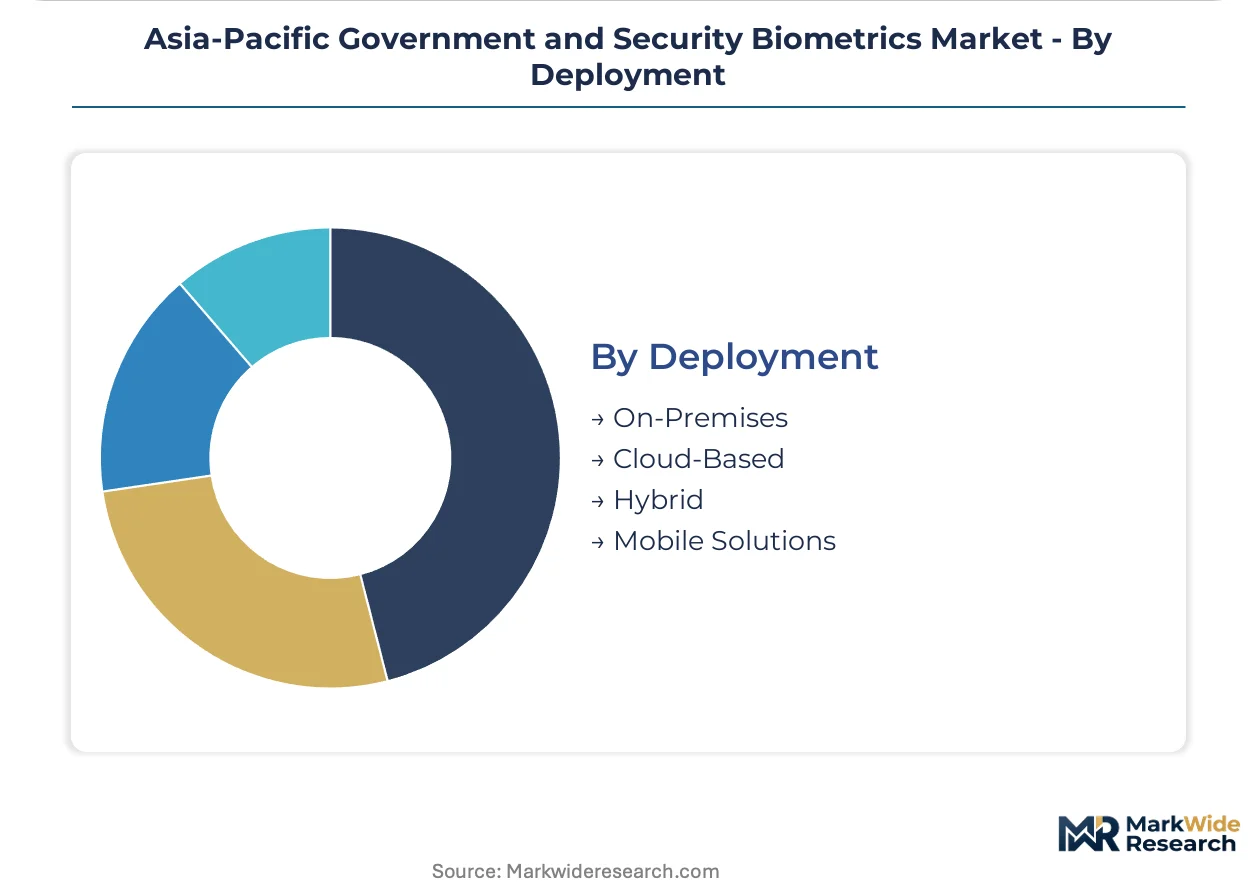
On-premises deployment retains defense sector preference. Hybrid architectures are climbing fastest among immigration agencies balancing flexibility with compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Australian defense procurement channels while Vietnamese national ID programs operate on compressed budgets that favor volume suppliers over premium-tier vendors.
India
UIDAI authentication transactions exceeding billions annually drive recurring hardware refresh cycles for fingerprint and iris matching infrastructure. The authority's operational standards mandate localized data storage and processing, compelling vendors to establish sovereign cloud instances within national borders. Bangalore and Hyderabad host the primary engineering clusters where system integrators customize multimodal platforms for state-level government deployments.
China
GB/T 26237 compliance testing for biometric data protection extends vendor onboarding timelines and elevates engineering costs for foreign suppliers seeking SAMR certification. The standard mandates template encryption and decentralized storage architectures that diverge from international frameworks. Shenzhen and Beijing concentrate domestic platform development, with local vendors capturing preference in government and security procurement tenders.
Australia
Canberra's defense modernization initiatives generate sustained demand for high-assurance biometric access control systems with Tempest shielding and tamper-evident hardware specifications. TGA-equivalent privacy frameworks restrict cross-border biometric data flows and mandate sovereign cloud infrastructure. The Australian Capital Territory and Victoria host the primary defense contracting clusters where procurement officers prioritize established in-country engineering presence.
Vietnam
The national chip-based identity card program creates volume opportunity for fingerprint enrollment kits and secure personalization equipment across provincial implementation tiers. Compressed capital budgets favor operational expenditure models and subscription-based authentication services over perpetual license structures. Ho Chi Minh City and Hanoi concentrate system integration capacity for nationwide rollout execution.
Japan
METI-led harmonization of JIS biometric specifications with international frameworks reduces export friction for compliant vendors and streamlines procurement for domestic agencies. Palm-vein authentication systems capture preference in high-security government facilities requiring low false acceptance rates. Tokyo and Osaka anchor the vendor engineering presence serving both domestic law enforcement and regional defense customers.
Asia-Pacific Government and Security Biometrics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, algorithms, and enrollment peripherals. The vendor base organizes around three strategic archetypes: multinational conglomerates with dedicated public sector divisions, specialized biometric pure-plays with modality-specific expertise, and regional system integrators with localized certification capabilities. Consolidation pressure operates through strategic partnerships between algorithm developers and hardware fabricators, plus technology licensing arrangements that accelerate time-to-certification across fragmented regulatory regimes.
Within the multinational tier, NEC Corporation and Fujitsu Ltd anchor positions through longstanding relationships with Japanese government agencies and law enforcement authorities. IDEMIA occupies a scale-driven position supplying enrollment infrastructure across multiple Asia-Pacific jurisdictions. These three entities exemplify the competitive pattern where established regulatory affairs capabilities and in-country engineering presence determine eligibility for premium-tier procurement channels.
| Leading Market Players |
|---|
| NEC Corporation |
| Fujitsu Ltd |
| IDEMIA |
| Suprema Inc. |
| ZKTeco |
| Hitachi |
| Panasonic Corporation |
| Thales Group |
| HID Global |
| Others |
Pricing and Supply Chain Analysis
Taiwan and South Korea fabrication capacity for specialized image sensors and edge AI processors concentrates upstream leverage with semiconductor foundries, pushing margin pools downstream toward system integrators with certification-ready multimodal platforms and established government procurement channels.
Pricing Analysis
Configured-to-order pricing for defense-grade biometric systems with Tempest shielding and tamper-evident hardware commands substantial premiums over standard fingerprint enrollment terminals. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in mid-tier government agencies intensifies because provincial digitization programs favor operational expenditure accounting. Immigration control buyers exhibit least price sensitivity due to mission-critical requirements, while Vietnamese national ID implementers demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms have become critical competitive tools for enrollment kit manufacturers serving budget-constrained Southeast Asian government agencies. Hardware assembly draws from China, Taiwan, and South Korea, while specialized near-infrared sensors and neural network accelerators rest on Japanese and American component suppliers. Single-source vulnerability in Taiwan-based foundry capacity for edge AI processors threatens procurement timelines. Distribution runs through authorized system integrators with localized regulatory affairs capabilities rather than direct vendor-to-government sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based authentication service models are expanding faster than hardware sales across Indonesia and Philippine provincial governments, creating substantial service-attach opportunities for vendors with managed security service capabilities.
For Market Incumbents: Harden sovereign cloud infrastructure partnerships against emerging pure-play SaaS competitors by deepening backward integration into edge AI processor supply chains. Fortify regulatory affairs teams to compress SAMR certification timelines in China and UIDAI compliance cycles in India. For New Entrants and Emerging Players: Mid-tier law enforcement agencies in Thailand and Malaysia represent the most penetrable entry point for mobile biometric solutions with rapid field-deployment capabilities. Vietnam's provincial national ID implementation tiers offer volume scale for cost-optimized fingerprint enrollment kits. Partner with established channel partners possessing managed security service credentials rather than building direct government sales capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biometric pure-plays holding modality-specific algorithm expertise but lacking in-country engineering presence. Five-to-ten-year viability hinges on successful navigation of fragmenting sovereign cloud mandates and cross-border data flow restrictions. Monitor procurement tender announcements from India's UIDAI and Australia's Department of Defence for volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Multimodal fusion architectures combining facial, iris, and voice biometrics digitize immigration workflows at Thai and Malaysian land borders. |
| Geographic Expansion | In-country engineering presence in Bangalore and Hyderabad satisfies UIDAI data localization mandates for authentication infrastructure. |
| Regulatory Certification Pathway | GB/T 26237 compliance testing investment unlocks SAMR certification and government procurement eligibility in China. |
| Strategic Partnership | Channel alliances with managed security service providers capture recurring revenue streams from Indonesian provincial digitization programs. |
| Product Launch | Edge AI inference terminals with decentralized matching capabilities address Australia's TGA-equivalent privacy framework requirements. |
Research Methodology
Desk research of customs trade data, government procurement databases, and regulatory filing repositories preceded structured interviews with biometric system procurement officers at immigration authorities, defense ministry contracting leads, and channel partners with managed security service operations. Primary fieldwork with technology integration specialists and regulatory affairs directors at multinational vendors combined with secondary validation against UIDAI operational standards, China's SAMR certification requirements, and Australia's TGA-equivalent privacy frameworks. Bottom-up enrollment kit shipment analysis and top-down government IT spending estimates underwent cross-triangulation.
Assumptions held fixed include prevailing data sovereignty regulations and current semiconductor fabrication capacity allocations, while variables included algorithm accuracy improvement trajectories and sovereign cloud infrastructure buildout timelines. Segmentation modeling spanned technology modality, end-user category, deployment architecture, and regional regulatory cluster across the analysis window. CAGRs derived from logistic adoption curves fitted to historical authentication transaction volumes and projected infrastructure refresh cycles. Forecast inputs incorporated UIDAI transaction growth rates and Australian defense capability investment announcements.
Practitioners should monitor cross-border data flow restriction announcements and sovereign cloud mandate implementations for early signals of supply chain bifurcation. Forecasts reflect documented assumptions regarding semiconductor supply stability and regulatory certification pathway durations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Biometric Authentication Solution Market