
 Healthcare Biometrics Market | 2026-2036
Healthcare Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Biometrics Market Intelligence
Hospital networks are expanding their biometric deployments faster than clinics or insurers. IDEMIA leverages its civil identity infrastructure to cross-sell healthcare authentication suites. NEC Corporation anchors its position through iris recognition R&D intensity in Japanese and North American hospital systems. Fujitsu Limited dominates palm-vein scanning for patient-matching workflows in large integrated delivery networks.
Healthcare biometrics encompasses physiological and behavioral measurement systems—fingerprint minutiae extraction at 500+ ppi, iris pattern encoding, voiceprint spectrogram analysis, and facial thermogram mapping—used to verify or identify individuals in clinical, administrative, and research settings. The technology prevents duplicate medical records, controls pharmaceutical dispensing, and secures electronic health record access. Fingerprint scanners still occupy the largest installed base, yet iris recognition is registering the fastest growth in surgical suites and neonatal units where contactless authentication matters. Facial recognition is extending into telehealth onboarding and remote clinical trial verification, though margin pools remain thinner due to algorithm commoditization.
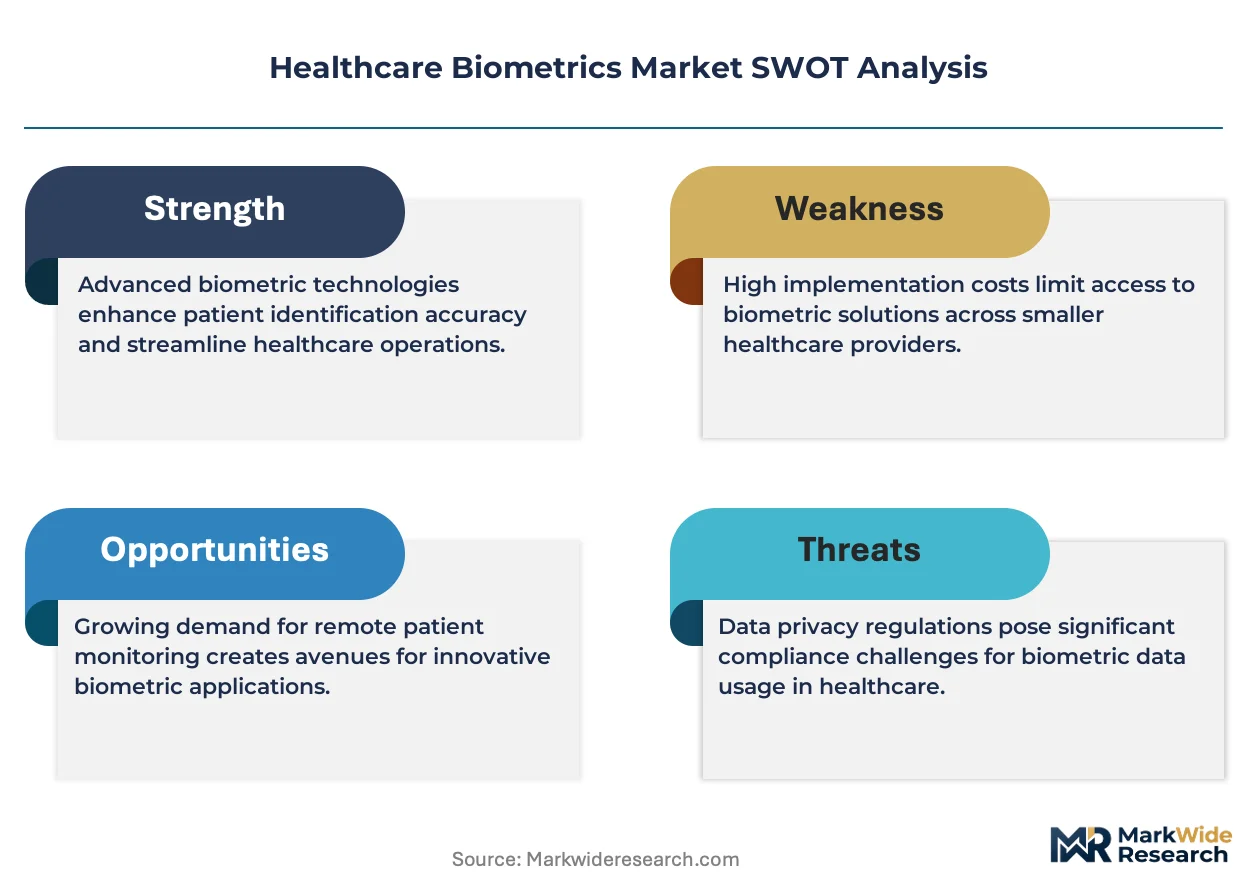
FDA digital health pre-certification, HIPAA security rule enforcement, and NIST biometric template protection standards collectively shape product development cycles and procurement criteria. The EU AI Act and GDPR biometric data processing restrictions are forcing vendors to redesign cloud architectures for regional data residency. Stakeholders must monitor evolving interoperability mandates between biometric identity platforms and federally certified health information exchanges.
Market Dynamics
Hospital procurement officers are consolidating vendor relationships around multimodal biometric suites that satisfy HIPAA security rule enforcement, FDA digital health pre-certification, and NIST biometric template protection standards simultaneously.
Growth Catalysts
- HIPAA Security Rule Enforcement:The Department of Health and Human Services Office for Civil Rights has intensified audit frequency for covered entities, forcing health systems to replace password-based access with fingerprint and iris authentication for electronic health record systems.
- Neonatal and Surgical Suite Demand:Contactless iris recognition is displacing fingerprint scanners in operating rooms and intensive care nurseries where sterility protocols prohibit physical contact with authentication devices.
- Telehealth Onboarding Requirements:Remote patient verification mandates from major US health insurers are driving facial recognition adoption for virtual care enrollment and prescription refill authentication.
Market Restraints
- GDPR Biometric Data Processing Restrictions:European Union member states impose strict consent requirements and data residency rules that force vendors to maintain separate cloud architectures, inflating operational costs for cross-border health information exchange deployments.
- Silicon Supply Concentration:Fingerprint sensor module production concentrates in East Asian foundries, exposing procurement timelines to geopolitical disruptions and foundry capacity constraints.
- Algorithm Commoditization:Open-source facial recognition libraries from academic institutions and technology conglomerates compress margin pools for proprietary facial thermogram mapping solutions.
Strategic Opportunities
- Rural Health Clinic Penetration:Federally qualified health centers in the United States remain underpenetrated by biometric patient identification, presenting white space for palm-vein scanning deployments in states with high Medicaid enrollment.
- Clinical Trial Remote Verification:Decentralized pharmaceutical research protocols create demand for voiceprint spectrogram analysis to authenticate participant identity during virtual study visits and electronic diary submissions.
- EU AI Act Compliance Services:Biometric vendors can capture value by bundling conformity assessment documentation and algorithmic audit trails with hardware sales to European hospital procurement departments.
Industry Challenges
- Interoperability with Legacy EHR Systems:Health information exchanges certified under federal programs require custom API development to integrate biometric identity platforms with decades-old electronic health record architectures.
- Biometric Template Protection Expertise:Vendors face acute shortages of cryptographers capable of implementing cancellable biometric transforms and homomorphic encryption for NIST-compliant template storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Biometrics Market |
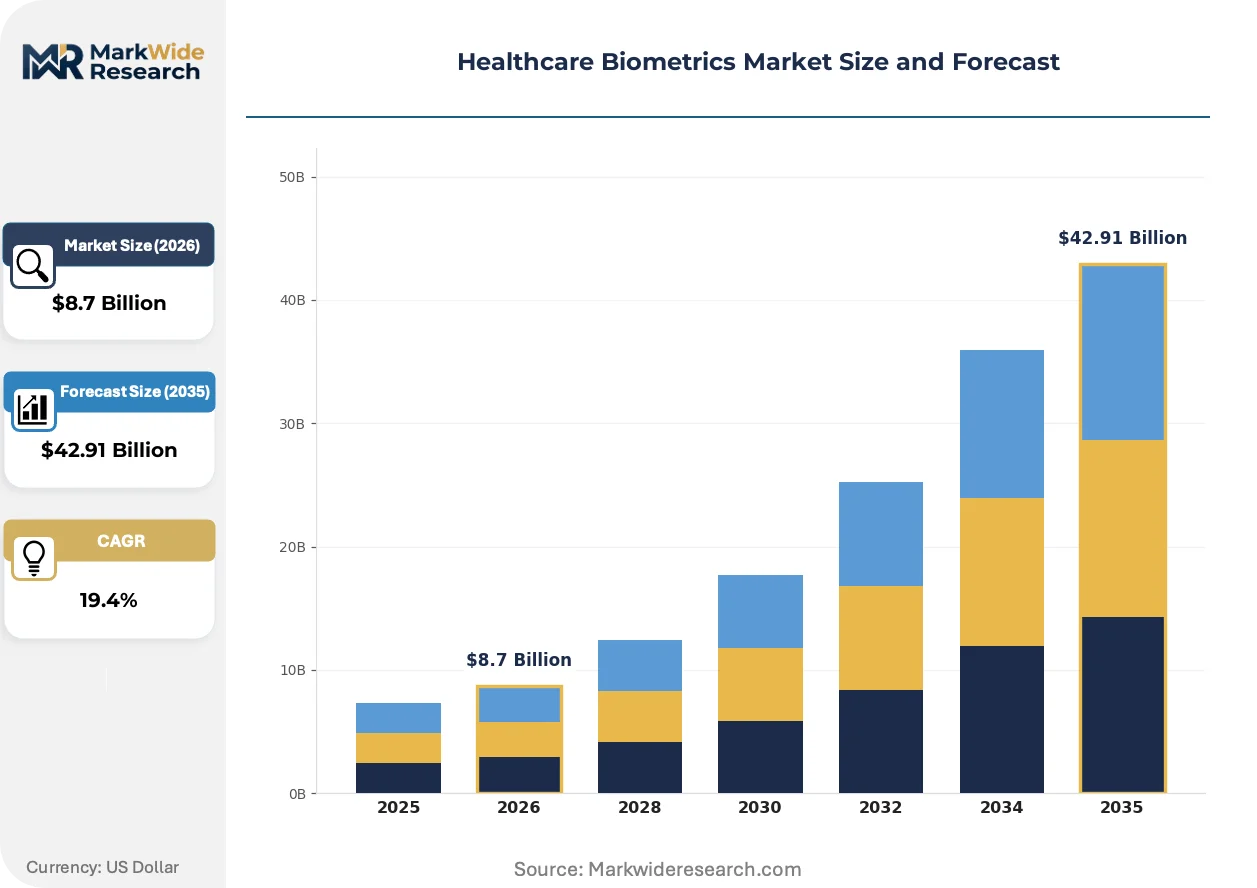
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Scanners, Iris Recognition, Voice Recognition, Facial Recognition Application: Patient Identification, Access Control, Clinical Trials, Data Security End User: Hospitals, Clinics, Research Laboratories, Health Insurance Providers Technology: Optical Recognition, Capacitive Sensing, Infrared Scanning, Thermal Imaging |
| Companies Covered | IDEMIA, BIO-key International, NEC Corporation, Aware Inc, HID Global Corporation, Thales Group, Imprivata Inc, Suprema Inc, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Biometrics Market Strategic Shifts & Innovations
Authentication modalities are converging around contactless physiological measurement systems that eliminate infection control risks while satisfying stringent identity assurance levels for clinical workflows.
Iris pattern encoding systems are absorbing market share from capacitive fingerprint sensors in surgical suites and neonatal intensive care units. Hospital infection control committees mandate non-contact authentication to eliminate fomite transmission vectors. This displacement is compressing the addressable market for traditional fingerprint scanner manufacturers while expanding R&D budgets for iris camera miniaturization.
The EU AI Act's risk classification framework for biometric identification systems is reshaping product development roadmaps for vendors serving European hospital networks. High-risk system designations trigger mandatory conformity assessments and human oversight requirements. German and French health systems are responding by demanding algorithmic audit documentation and bias testing certificates from procurement shortlists.
Health system chief information officers are consolidating vendor relationships around integrated identity platforms rather than point solutions for specific access control scenarios. Biometric authentication is bundling with physical security, medication dispensing, and patient registration workflows. This concentration is most visible in large integrated delivery networks across Texas, California, and Florida where procurement departments negotiate enterprise-wide biometric suite contracts.
Healthcare Biometrics Market Segmentation
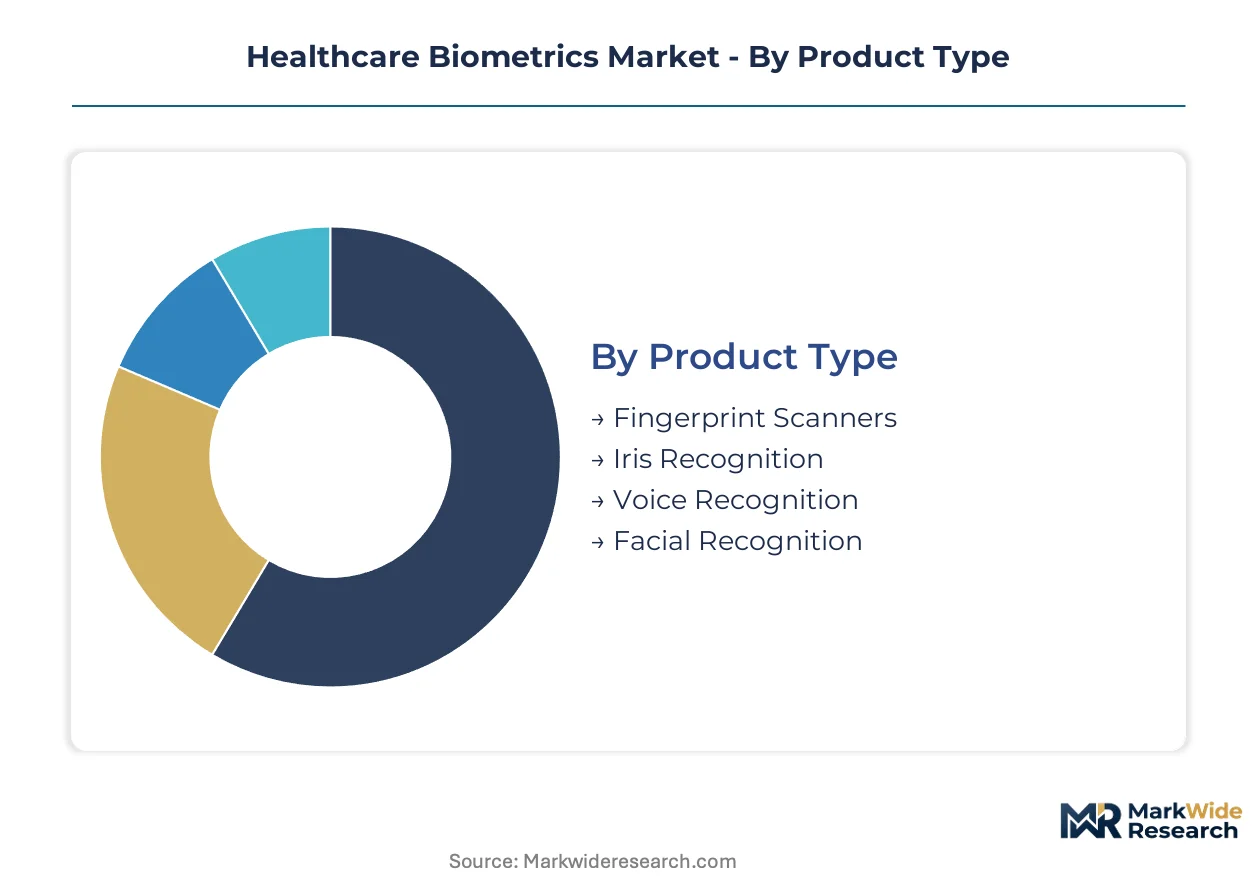
Biometric deployment patterns vary sharply by authentication modality, clinical workflow, and facility infrastructure maturity. Procurement decisions hinge on infection control protocols, legacy system interoperability, and regulatory compliance burdens specific to each segment combination.
Product Type:
Technology specifications determine sterility compatibility, template storage requirements, and integration complexity with hospital information systems.
- Iris Recognition:Contactless acquisition of unique iris patterns using near-infrared illumination enables authentication in sterile surgical environments. Demand concentrates in neonatal intensive care units and operating rooms across Texas and California hospital systems where infection control committees prohibit physical device contact.
- Facial Recognition:Thermogram mapping and 3D structural analysis support remote patient onboarding for telehealth platforms. Deployment is accelerating in virtual care enrollment workflows at large US health insurers replacing manual identity verification for prescription refills.
- Fingerprint Scanners:Capacitive and optical minutiae extraction systems retain the largest installed base for medication dispensing cabinets and EHR workstation access.
- Voice Recognition:Spectrogram analysis of vocal biometric markers enables hands-free authentication during clinical documentation and remote trial participation.
Mature deployment sits with fingerprint scanners. Newer deployment is concentrated in iris recognition.
Application:
Clinical workflow integration determines authentication frequency, user population scale, and failure-mode tolerance thresholds.
- Patient Identification:Biometric matching against master patient indices eliminates duplicate records and insurance fraud. Large integrated delivery networks in Florida and Ohio are replacing legacy wristband barcoding with palm-vein and iris modalities for registration throughput.
- Access Control:Multi-factor authentication for EHR systems, pharmaceutical vaults, and restricted clinical zones drives the highest transaction volume. HIPAA audit enforcement from the Department of Health and Human Services Office for Civil Rights is mandating biometric replacement of password-based clinician logins.
- Clinical Trials:Remote participant verification using facial and voice biometrics supports decentralized pharmaceutical research protocols.
- Data Security:Template-protected encryption keys secure health information exchange transmissions and backup archives.
Transaction density peaks in access control. Regulatory pressure is expanding fastest in patient identification.
End User:
Facility scale dictates procurement sophistication, vendor consolidation potential, and multimodal platform appetite.
- Hospitals:Enterprise identity platforms spanning thousands of users and multiple authentication scenarios command premium pricing. Texas Medical Center and Kaiser Permanente systems negotiate consolidated contracts bundling physical security, patient registration, and medication dispensing workflows.
- Clinics:Federally qualified health centers in high-Medicaid states present underpenetrated demand for cost-effective palm-vein patient matching without IT infrastructure overhead.
- Research Laboratories:Genomic and biobanking facilities require high-assurance access control for specimen chain-of-custody compliance.
- Health Insurance Providers:Remote member authentication for portal access and telehealth claims processing drives facial recognition adoption.
Procurement sophistication clusters in hospitals. Volume expansion is steepest in clinics.
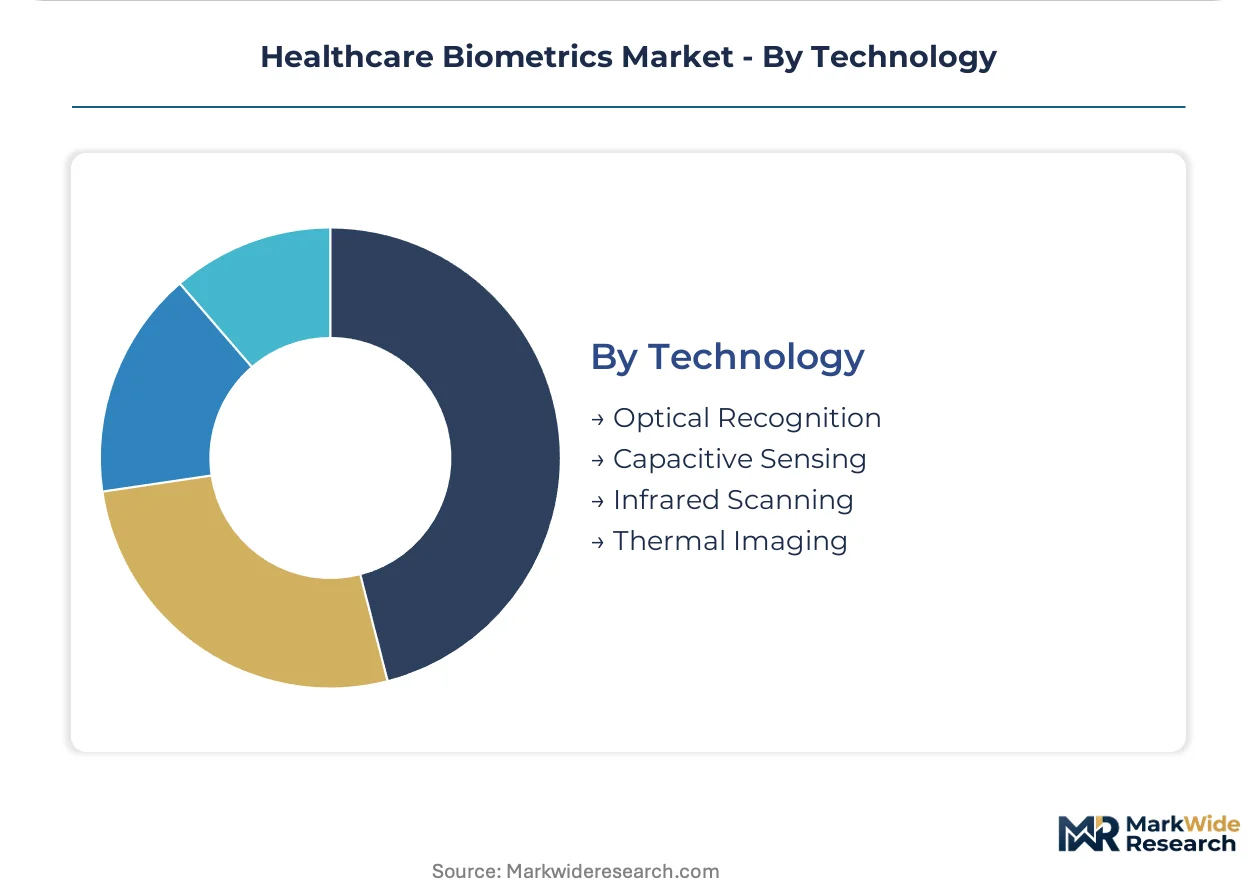
Technology:
Sensor architecture determines environmental tolerance, spoof resistance, and semiconductor supply exposure.
- Infrared Scanning:Near-infrared illumination penetrates eyeglasses and contact lenses for reliable iris acquisition in variable lighting. Japanese and German hospital systems prioritize this modality for surgical suite deployments where visible-light interference disrupts clinical equipment.
- Capacitive Sensing:Electrical field distortion mapping for fingerprint ridges dominates medication dispensing and EHR workstation markets despite vulnerability to moisture and skin condition variation.
- Optical Recognition:Visible-light fingerprint imaging persists in cost-sensitive deployments with controlled environmental conditions.
- Thermal Imaging:Facial thermogram analysis liveness detection counters presentation attacks for remote authentication scenarios.
Supply concentration sits with capacitive sensing. Technical migration is accelerating toward infrared scanning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dubai Healthcare City concentrate biometric R&D facilities through tax incentives and streamlined regulatory pathways. These zones attract vendors seeking proximity to hospital procurement decision-makers and regional certification bodies.
United States
Large integrated delivery networks in Texas and California are replacing legacy password systems with multimodal biometric platforms. HIPAA Security Rule enforcement from the Department of Health and Human Services Office for Civil Rights mandates biometric authentication for electronic health record access. The Texas Medical Center in Houston anchors enterprise-wide deployments bundling patient registration, medication dispensing, and physical security workflows.
Germany
German hospital systems prioritize near-infrared iris recognition for surgical suite deployments where visible-light interference disrupts clinical equipment. The EU AI Act's high-risk system designation triggers mandatory conformity assessments and human oversight requirements for biometric identification. Medical technology clusters in Baden-Württemberg and Bavaria demand algorithmic audit documentation and bias testing certificates from procurement shortlists.
Japan
Japanese hospital networks anchor iris recognition R&D intensity through partnerships with domestic semiconductor and optics manufacturers. METI funding programs support development of contactless authentication systems for sterile clinical environments. The Kanto region around Tokyo concentrates deployments in university hospitals and national medical centers with advanced infection control protocols.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi's health system modernization programs drive demand for palm-vein and facial recognition systems in luxury hospital settings. MOHAP regulations mandate biometric patient identification for health information exchange participation. Private hospital groups in Dubai anchor multimodal platform deployments integrating access control with premium patient experience workflows.
India
Federally qualified health centers in high-Medicaid states present underpenetrated demand for cost-effective palm-vein patient matching without IT infrastructure overhead. The Digital India program and BIS standards for biometric devices shape procurement criteria for public hospital networks. Medical device manufacturing clusters in Karnataka and Tamil Nadu assemble fingerprint and iris modules for domestic health system deployments.
Healthcare Biometrics Market Key Industry Players
Top-tier vendors anchor multimodal platform consolidation, while mid-tier specialists compete on modality-specific performance metrics. The vendor base stratifies across civil identity infrastructure providers, semiconductor-integrated hardware manufacturers, and clinical workflow software vendors. Two dominant competitive moves are evident: enterprise contract bundling across authentication scenarios and regional certification pre-qualification for EU AI Act and FDA digital health pathways.
Within the civil identity crossover tier, IDEMIA leverages its government infrastructure presence to anchor healthcare authentication suites. NEC Corporation and Fujitsu Limited occupy positions reflecting Japanese industrial concentration in iris optics and palm-vein sensor architectures respectively. These three exemplify how vendors with established biometric R&D programs in adjacent sectors capture hospital procurement attention through pre-validated template protection implementations.
| Leading Market Players |
|---|
| IDEMIA |
| BIO-key International |
| NEC Corporation |
| Aware Inc |
| HID Global Corporation |
| Thales Group |
| Imprivata Inc |
| Suprema Inc |
| Fujitsu Limited |
| Others |
Cost & Logistics Intelligence
Cryptographer talent pools in Israel and Estonia anchor labor-cost differentials that widen pricing-tier spreads between premium template-protected platforms and economy fingerprint modules lacking cancellable biometric transforms.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery windows for iris camera modules bound for surgical suite deployments. Three-tier pricing structure across premium, standard, and economy levels reflects FDA pre-certification status, NIST template protection compliance, and bundled conformity documentation. Cost compression in economy fingerprint tiers is intensifying because open-source algorithm libraries erode proprietary margin pools. Federally qualified health centers exhibit highest price sensitivity, while Texas Medical Center-scale integrated delivery networks absorb premium pricing for multimodal enterprise platforms.
Supply Chain Analysis
Near-infrared LED and CMOS sensor supply rests on Japanese optics manufacturers, Taiwanese semiconductor foundries, and German precision glass specialists. Fingerprint capacitive arrays draw from South Korean display-grade foundries, Chinese module assemblers, and Malaysian packaging facilities. Single-source vulnerability concentrates in specialty near-infrared illumination components for iris recognition systems. Distribution runs through medical device distributors with FDA 510(k) clearance pathways, direct hospital procurement committees, and GPO contracts managed by Vizient and Premier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: cryptographer shortages for cancellable biometric transform implementation prop pricing premiums for NIST-compliant vendors.
For Market Incumbents: Anchor enterprise-wide contract consolidation across patient registration, medication dispensing, and physical security workflows to deepen switching costs. Defend margin position by acquiring Israeli cryptography boutiques with proven homomorphic encryption implementations before EU AI Act audit documentation mandates harden procurement criteria. Prioritize backward integration into near-infrared LED sourcing to neutralize Japanese optics bottlenecks. For New Entrants and Emerging Players: Rural federally qualified health centers in high-Medicaid states present the most penetrable buyer archetype for cost-effective palm-vein platforms without IT infrastructure overhead. Target clinical trial remote verification workflows using voiceprint spectrogram analysis as the entry vector. Pursue partnership-first go-to-market models with decentralized pharmaceutical research organizations seeking virtual participant authentication. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier iris recognition specialists given EU AI Act high-risk system designations triggering mandatory conformity assessments and human oversight requirements. Long-term viability favors vendors with pre-validated template protection implementations spanning civil identity and healthcare verticals. Watch FDA digital health pre-certification pathway acceleration as the inflection signal for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates hospital procurement cycles for biometric authentication suites in Texas and California systems. |
| EU AI Act Conformity Bundling | Captures value from German and French hospital demand for algorithmic audit documentation and bias certificates. |
| Hospital System Partnership | Kaiser Permanente-scale enterprise contracts bundle patient registration, medication dispensing, and physical security workflows. |
| Backward Integration into Optics | Secures near-infrared LED supply from Japanese manufacturers for iris recognition surgical suite deployments. |
| Clinical Trial Remote Verification | Voiceprint spectrogram analysis serves decentralized pharmaceutical research protocols requiring virtual participant authentication. |
Research Approach
FDA 510(k) filings, hospital GPO contract databases, and NIST biometric template protection standards formed the secondary backbone, cross-referenced against primary interviews with hospital chief information officers, biomedical engineers, procurement committee chairs, and GPO contracts managers. Bottom-up and top-down triangulation validated modality-specific deployment counts against aggregate health system IT spending disclosures.
Bottom-up modeling projected installed base expansion across authentication modalities, clinical workflows, and facility infrastructure tiers over the projection horizon. Segmentation dimensions spanned product type, application, end user, and technology architecture. CAGRs derived from weighted average of historical procurement velocity and regulatory enforcement intensity trajectories. Forecast inputs incorporated HIPAA audit frequency data and EU AI Act implementation timelines.
Revisions become necessary when NIST template protection standards tighten, FDA digital health pre-certification pathways accelerate, or geopolitical disruptions constrain East Asian semiconductor foundry capacity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Password Management Market