
 Germany Agricultural Machinery Market | 2026-2036
Germany Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Agricultural Machinery Market Foresight
Software-defined feature subscriptions is hardening as a core revenue layer in German agricultural equipment, shifting capital expenditure toward recurring service contracts. CLAAS KGaA mbH leverages telemetry-enabled fleet management to sustain long-term customer lock-in. Deere & Company anchors precision agriculture revenues through its integrated operations center platform. Horsch Holding SE differentiates via specialized seed placement algorithms that command premium subscription tiers.
Germany agricultural machinery encompasses self-propelled and trailed equipment engineered for soil preparation, crop management, and harvest operations, with power ratings spanning 50 to 600 horsepower and compliance to Stage V emission thresholds. Its primary commercial purpose centers on yield optimization and labor reduction across diversified farming operations. Tractors retain the dominant revenue position while autonomous vehicles represent the fastest-expanding technology segment as German farms confront persistent skilled operator shortages. Precision farming applications in cereal crop farming concentrate the deepest margin pools due to scale economies and repeat input purchasing cycles.
The KBA enforces emission certification for engine-powered equipment under EU Stage V standards, while the EU Green Deal's Farm to Fork strategy mandates 50% pesticide reduction targets that reshape machinery specification requirements. CE marking and the F-Gas Regulation govern refrigerant systems in climate-controlled cabs and grain storage attachments. Stakeholders must monitor how evolving EU Common Agricultural Policy conditionality requirements will redirect equipment upgrade cycles across German federal states.
Market Dynamics
EU Green Deal conditionality is compressing equipment replacement cycles across German federal states, forcing cooperative enterprises to retire Stage III-compliant tractors ahead of depreciation schedules while accelerating capital deployment into telemetry-integrated fleets.
Growth Catalysts
- EU Green Deal Farm to Fork:The 50% pesticide reduction mandate is retrofitting sprayer specifications and expanding demand for precision application equipment among Lower Saxony cereal producers.
- Autonomous navigation:German farms facing persistent skilled operator shortages are accelerating procurement of self-steering tractors with RTK-GPS correction systems.
- Lower Saxony cooperative concentration:Large-scale arable enterprises in this northern cluster are consolidating fleet purchasing power and demanding integrated telemetry platforms.
Market Restraints
- Steel and rare earth input volatility:Permanent magnet supply concentration in processing facilities outside Europe is compressing electric drivetrain margins for domestic manufacturers.
- Stage V emission certification:KBA enforcement of particulate matter limits is extending type-approval timelines and freezing small-series specialty equipment introductions.
- Skilled technician scarcity:Mechatronics training pipeline gaps in rural Schleswig-Holstein are constraining after-sales service capacity for precision farming installations.
Strategic Opportunities
- Software-defined subscriptions:Telemetry-enabled feature unlocking is converting capital expenditure into recurring revenue streams among equipment finance providers.
- Bavarian livestock diversification:Dairy-to-arable pivots in southern federal states are creating first-time demand for soil preparation equipment in previously grazing-dominant regions.
- EU Common Agricultural Policy conditionality:Evolving cross-compliance requirements for nutrient management are mandating precision spreading technology adoption.
Industry Challenges
- CE marking and F-Gas compliance:Climate-controlled cab refrigerant system certification is adding 8-14 week delays to harvester delivery schedules.
- Legacy ISOBUS integration:Proprietary telemetry protocols from competing manufacturers are fragmenting fleet management software compatibility across mixed-brand operations.
- Telematics data sovereignty:Cross-border cloud storage restrictions under GDPR are complicating predictive maintenance algorithm training for multinational equipment lessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Agricultural Machinery Market |
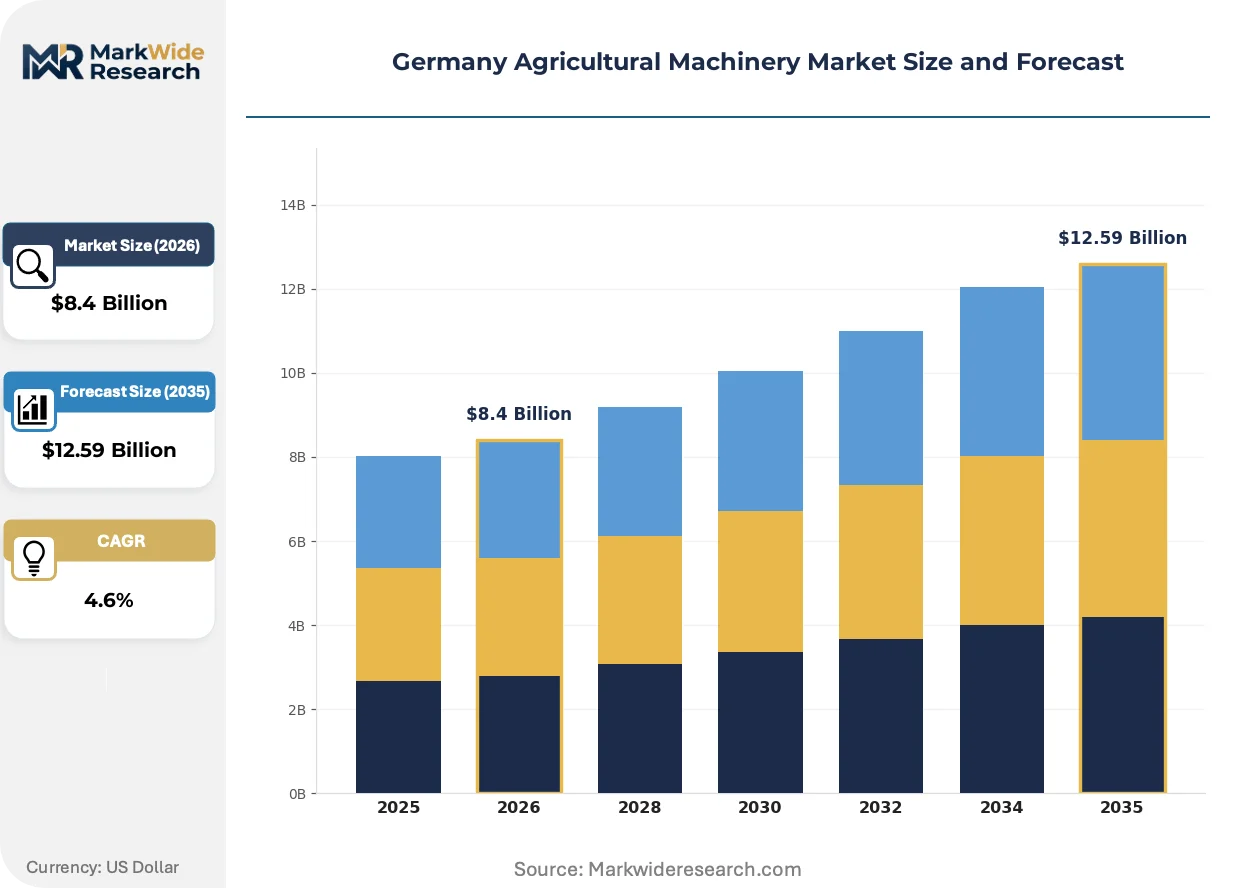
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Combine Harvesters, Seed Drills, Sprayers, Balers, Cultivators Technology: Precision Farming, GPS Guidance, Autonomous Vehicles, Telemetry, Variable Rate Technology, IoT Sensors Application: Cereal Crop Farming, Vegetable Cultivation, Livestock Feeding, Viticulture, Horticulture, Silviculture End User: Small-scale Farms, Cooperative Enterprises, Agricultural Contractors, Research Institutes, Organic Producers, Government Agencies |
| Companies Covered | CNH Industrial N.V., SDF S.p.A., AGCO Corporation, Maschinenfabrik Bernard KRONE GmbH & Co.KG, Lemken Beteiligungs-GmbH, Deere & Company, Kubota Corporation, Horsch Holding SE, CLAAS KGaA mbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Agricultural Machinery Market Shifts & Advancements
Telemetry integration is collapsing the boundary between hardware sales and service revenue, while regulatory pressure on input efficiency is hardening precision farming from optional upgrade to operational necessity.
Implement-mounted sensor arrays are modularizing agronomic data collection across German cereal operations. Lower Saxony cooperative enterprises are deploying nitrogen-sensing spectrometers on self-propelled spreaders at replacement-cycle velocity. This hardware-software convergence is modularizing equipment specification, allowing base chassis purchases with capability expansion through firmware activation.
EU F-Gas Regulation phase-down schedules are forcing refrigerant system redesigns in climate-controlled cabs and grain storage attachments. Equipment manufacturers are accelerating heat pump and CO2-based climate system development to maintain CE marking eligibility. German combine harvester producers face the steepest compliance cost concentration due to cab comfort specifications demanded by extended autumn operating windows.
Cooperative procurement consortia are consolidating fleet purchasing decisions across multiple family enterprises, displacing individual farm-level equipment selection. Machinery dealers in Schleswig-Holstein are responding with dedicated enterprise account teams and volume-based telemetry platform pricing. This buyer-side concentration is most visible in the 200-300 horsepower tractor segment where cooperative orders now dominate annual manufacturer allocation.
Germany Agricultural Machinery Market Segmentation
Equipment specification in Germany diverges sharply by operational scale and environmental compliance tier. Capital deployment patterns across Lower Saxony cooperatives versus Bavarian family farms create distinct demand clusters that reshape manufacturer product line priorities.
Product Type:
Capital intensity varies dramatically across equipment categories, with self-propelled harvesters and high-horsepower tractors demanding seven-figure euro outlays that strain depreciation schedules.
- Tractors:Power ratings from 50 to 600 horsepower anchor fleet economics across German arable operations. Lower Saxony cooperative enterprises concentrate procurement in the 200-300 horsepower band where telemetry integration and Stage V compliance command premium positioning.
- Combine Harvesters:Self-propelled grain platforms with 6 to 12 meter headers dominate cereal harvesting economics. Extended autumn operating windows in northern federal states drive specification toward climate-controlled cabs with heat pump climate systems to maintain CE marking eligibility.
- Seed Drills:Trailed and mounted units with pneumatic distribution systems.
- Sprayers:Self-propelled and trailed application equipment facing EU Green Deal pesticide reduction retrofit mandates.
- Balers:Round and square baling systems for forage operations.
- Cultivators:Soil preparation implements with minimum-tillage configurations.
Tractors absorb the bulk of installed capacity; autonomous navigation variants are expanding most quickly as skilled operator scarcity hardens.
Technology:
Technology adoption curves split between precision farming platforms that reduce input costs and autonomous systems that address labor availability constraints.
- Precision Farming:Integrated agronomic data platforms combining yield mapping, soil sensing, and prescription generation. Cereal crop farming in Lower Saxony deploys nitrogen-sensing spectrometers at replacement-cycle velocity to meet EU Farm to Fork conditionality.
- GPS Guidance:RTK-GPS correction systems enabling centimeter-level field navigation. Schleswig-Holstein contractors specify auto-steering to extend daily operating hours amid persistent skilled operator shortages.
- Autonomous Vehicles:Self-driving tractors without cab occupancy.
- Telemetry:Fleet management platforms converting hardware sales to recurring service contracts.
- Variable Rate Technology:Input application modulation based on real-time sensor feedback.
- IoT Sensors:Implement-mounted arrays for soil and crop condition monitoring.
Precision farming platforms capture the deepest margin pools; autonomous vehicles gain share fastest where labor scarcity bites hardest.
Application:
Application-specific equipment requirements reflect crop economics and EU subsidy conditionality across German federal states.
- Cereal Crop Farming:Large-scale wheat, barley, and rapeseed operations demanding high-capacity harvesters and precision spreading technology. Scale economies and repeat input purchasing cycles concentrate manufacturer attention on this segment.
- Vegetable Cultivation:Specialized planting and harvesting equipment for root and leafy crops.
- Livestock Feeding:Forage handling and ration preparation machinery.
- Viticulture:Narrow-track tractors and canopy management equipment for steep-slope vineyards.
- Horticulture:Protected-culture and open-field vegetable systems.
- Silviculture:Forestry planting and maintenance equipment.
Cereal crop farming commands the largest equipment installed base; vegetable cultivation shows the steepest technology upgrade trajectory as precision planting spreads.
End User:
Buyer concentration patterns reshape distribution economics and service capacity requirements across German machinery dealerships.
- Cooperative Enterprises:Multi-family consolidated operations with centralized fleet purchasing and dedicated enterprise account relationships. Volume-based telemetry platform pricing and integrated financing structures dominate procurement in Lower Saxony and Schleswig-Holstein.
- Agricultural Contractors:Service providers supplying tillage, planting, and harvesting to non-equity-owning farmers. Equipment utilization intensity drives specification toward durability and rapid service turnaround.
- Small-scale Farms:Family operations under 100 hectares with limited capital access.
- Research Institutes:Public and private agricultural research stations.
- Organic Producers:Certified operations with mechanical weed control requirements.
- Government Agencies:Federal and state-level demonstration and conservation program equipment.
Cooperative enterprises concentrate the heaviest capital deployment; agricultural contractors show the fastest fleet expansion as farm service outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German agricultural machinery production concentrates in southwestern industrial clusters, while demand intensity radiates from northern arable belts toward eastern livestock regions. This geographic split shapes equipment specification divergence across federal states.
Lower Saxony
Large-scale cereal cooperatives in this northern belt deploy precision farming fleets at replacement-cycle velocity. KBA Stage V enforcement accelerates tractor turnover among enterprises managing 2,000-plus hectare operations. The Oldenburg Münsterland cluster anchors Germany's densest concentration of telemetry-integrated spreaders and self-propelled sprayers.
Bavaria
Dairy-to-arable pivots in southern districts generate first-time demand for soil preparation equipment across previously grazing-dominant landscapes. EU Common Agricultural Policy cross-compliance requirements for nutrient management mandate precision spreading technology in the Danube valley. The Munich-Augsburg corridor hosts specialized dealerships serving diversified livestock-arable operations.
Schleswig-Holstein
Contractor-driven service outsourcing concentrates fleet purchasing power among agricultural service providers facing persistent skilled operator shortages. RTK-GPS auto-steering systems extend daily operating windows across the Schleswig-Holstein peninsula. The Kiel-Rendsburg district exhibits Germany's highest contractor fleet density per hectare of arable land.
North Rhine-Westphalia
Mixed farming operations in the Münsterland and Lower Rhine regions balance livestock feeding machinery with arable crop equipment. CE marking delays for F-Gas-compliant climate systems disrupt harvester delivery schedules to extended-autumn operators. The Cologne-Bonn machinery corridor distributes specialized viticulture equipment to steep-slope vineyards in the Ahr valley.
Baden-Württemberg
Precision viticulture and specialty crop cultivation drive narrow-track tractor specification in southwestern valleys. Heat pump climate system development accelerates among manufacturers serving premium wine producers. The Stuttgart metropolitan zone anchors Germany's agricultural machinery R&D concentration, with engineering talent pools supporting autonomous navigation development.
Germany Agricultural Machinery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across German agricultural equipment, with integrated manufacturers maintaining foundry-level control over powertrain assembly while specialized implement makers outsource chassis fabrication. The vendor base splits between diversified full-line corporations and focused implement specialists. Three archetypes dominate: telemetry-platform integrators, precision-application specialists, and regional cooperative-focused distributors. Strategic maneuvering concentrates on software-defined subscription layering and Stage V emission compliance acceleration.
Within the telemetry-platform tier, CLAAS KGaA mbH and Deere & Company exemplify integrated operations center architectures that convert hardware sales into recurring service contracts. Horsch Holding SE occupies a specialized position among precision-application designers, while Lemken Beteiligungs-GmbH represents the focused implement specialist archetype serving cooperative procurement consortia. SDF S.p.A. anchors southern European manufacturing presence among diversified full-line competitors.
| Leading Market Players |
|---|
| CNH Industrial N.V. |
| SDF S.p.A. |
| AGCO Corporation |
| Maschinenfabrik Bernard KRONE GmbH & Co.KG |
| Lemken Beteiligungs-GmbH |
| Deere & Company |
| Kubota Corporation |
| Horsch Holding SE |
| CLAAS KGaA mbH |
| Others |
Supply & Pricing Matrix
Telemetry platform integration is simultaneously compressing hardware margins and concentrating pricing power among software-capable manufacturers, as KBA Stage V compliance costs and rare earth magnet supply bottlenecks reshape procurement economics across German equipment tiers.
Pricing Analysis
Margin tightening in precision farming equipment reflects the shift from perpetual license sales to recurring telemetry subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fleet scale and data integration depth, with Lower Saxony cooperatives least price-sensitive due to volume-based telemetry platform contracting and small-scale Bavarian farms most exposed to upfront capital constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cooperative demand, while specialized implement makers rely on regional fabrication networks. Permanent magnet processing concentrates in China and Southeast Asian facilities, steel sheet supply draws from German and Polish mills, and precision sensor arrays source from South Korean and Taiwanese component houses. Single-source vulnerability in rare earth processing threatens electric drivetrain cost stability. Distribution runs through manufacturer-owned dealer networks with enterprise account teams serving consolidated procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
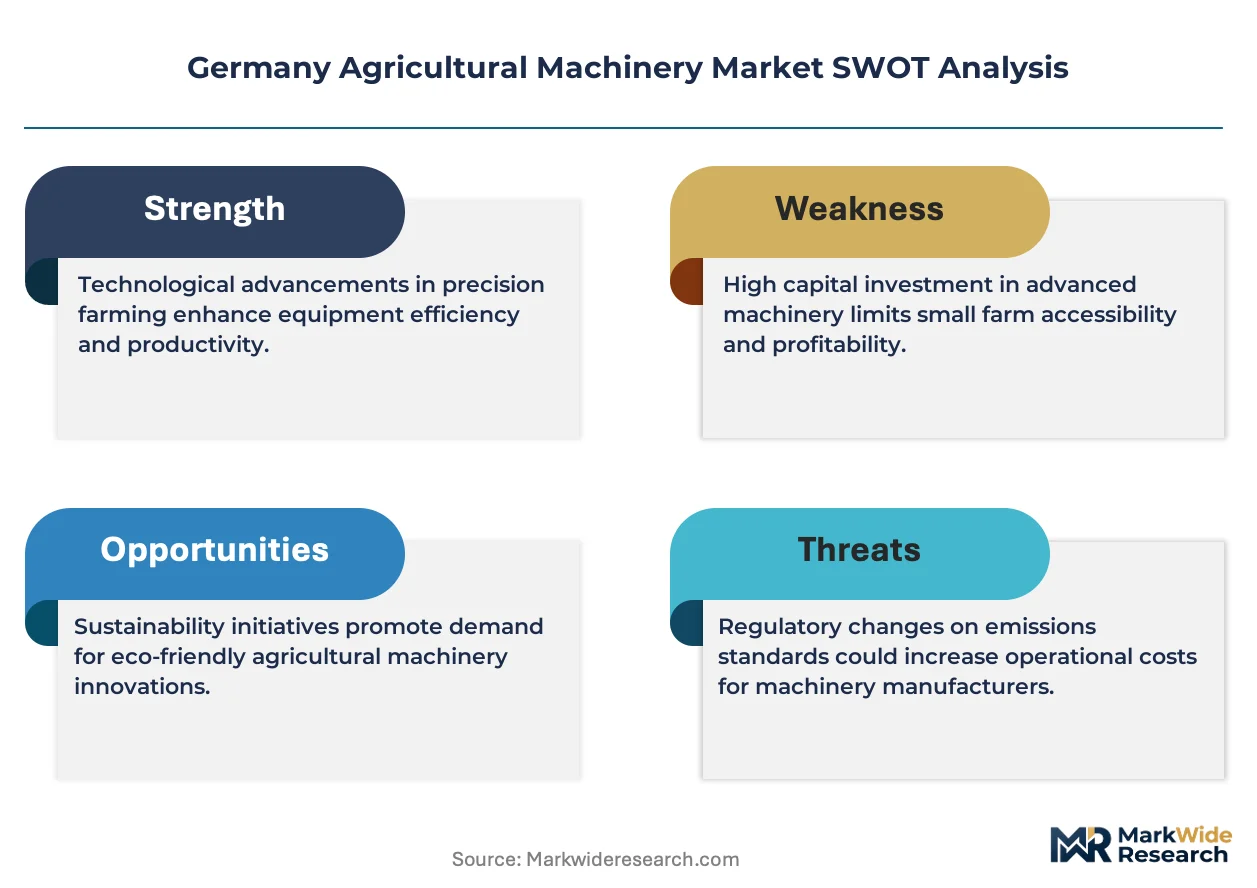
The Germany agricultural machinery market operates as a cost-of-compliance arena where EU Green Deal Farm to Fork mandates erect regulatory moats favoring Stage V-certified, telemetry-integrated incumbents with capital reserves for accelerated replacement-cycle financing.
For Market Incumbents: Anchor fleet renewal financing programs to KBA emission certification timelines, locking cooperative enterprises into multi-year telemetry subscription bundles before competitor platform penetration. Accelerate backward integration into permanent magnet supply through European processing partnerships to defend electric drivetrain margins against Asian supply concentration. Monitor autonomous navigation software entrants threatening hardware-attachment revenue streams.
For New Entrants and Emerging Players: Enter via precision application software specialization targeting Bavarian dairy-to-arable conversion zones with first-time soil preparation equipment demand. White-space concentration sits in nutrient management algorithm development for EU CAP cross-compliance, with lowest incumbent saturation in contractor-focused RTK-GPS auto-steering retrofits for aging tractor fleets. Deploy direct-to-contractor digital sales bypassing established dealer networks.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified full-line manufacturers seeking telemetry platform capabilities. Long-term viability hinges on software-defined revenue conversion rates and GDPR-compliant data sovereignty architecture. Acquisition target archetype: precision-application specialists with locked-in cooperative relationships and proven F-Gas Regulation compliance engineering. Watch Stage V enforcement acceleration across remaining federal states as inflection signal for replacement-cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Converts hardware sales to recurring revenue streams among Lower Saxony cooperative enterprises. |
| Stage V Compliance Acceleration | Compresses replacement cycles and freezes small-series competitor introductions under KBA enforcement. |
| Precision Spreading Technology Development | Captures EU CAP nutrient management mandates across Bavarian and northern federal state operations. |
| Autonomous Navigation Retrofit Programs | Addresses skilled operator scarcity in Schleswig-Holstein contractor fleets with RTK-GPS solutions. |
| Heat Pump Climate System Redesign | Maintains CE marking eligibility for combine harvesters under F-Gas Regulation phase-down schedules. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across equipment procurement managers at Lower Saxony cooperatives, precision farming specialists at Bavarian dealerships, KBA certification engineers, and aftermarket service heads in Schleswig-Holstein. VDMA agricultural machinery statistics, EU TARIC customs databases, and federal state agricultural ministry reports supplied demand-side validation. Bottom-up equipment shipment analysis triangulated against top-down agricultural GDP attribution.
Granularity-level modeling deployed horsepower tier, technology integration depth, and federal state regulatory cluster as core segmentation dimensions across the analysis window. CAGRs derived from replacement-cycle velocity assumptions tied to KBA Stage V enforcement timelines and EU Green Deal conditionality implementation. Forecast inputs incorporated cooperative consolidation rates, skilled operator scarcity indices, and rare earth magnet price trajectory scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU CAP conditionality revisions or prolonged rare earth supply disruptions. Projections reflect assumptions regarding telemetry adoption curves and emission regulation enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Europe Agricultural Machinery Market