
 Asia-Pacific Planting Machinery Market | 2026-2036
Asia-Pacific Planting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Planting Machinery Market Outlook
Precision-grade planting specifications is collapsing the gap between commodity drills and GPS-guided seeders across the Asia-Pacific. Deere & Company leverages its integrated precision agriculture platform to dominate high-horsepower automated seeder sales in Australia and New Zealand. Kubota Corporation anchors the mid-market with compact transplanters purpose-built for East Asian paddy fields. Mahindra & Mahindra Ltd. competes aggressively on tractor-attachment compatibility across India's dealer network.
Asia-Pacific planting machinery encompasses tractor-mounted and self-propelled equipment designed to place seeds, seedlings, or propagules at controlled depth, spacing, and population density, typically operating at 6-15 km/h with seed metering accuracy within 2-5% of target rates. These machines serve commercial crop production by reducing labor dependency and improving establishment uniformity across rice, wheat, maize, and vegetable systems. Drills retain the largest installed base due to decades of traction in cereal monocultures, though precision technology-enabled seeders capture expanding margin pools as variable-rate prescriptions penetrate Australian broadacre and Chinese state farms. Transplanters sustain double-digit expansion in East and Southeast Asia where rice mechanization lags behind harvest automation, while manual and conventional equipment still occupies substantial share among smallholder cooperatives in Bangladesh and Myanmar.
India's CEA and China's MEE enforce emission thresholds on diesel-powered farm equipment, pushing manufacturers toward electrified drivetrains and Stage V-equivalent engines. Australia's ACCC and Japan's METI coordinate safety and interoperability standards that shape import eligibility and aftermarket parts availability. India's BIS certification for agricultural machinery and China's GB standards for planting equipment performance create layered compliance costs that filter out low-spec imports. Stakeholders must weigh localization commitments against technology transfer requirements as subsidy eligibility tightens across the region's major procurement programs.
Market Dynamics
Subsidy conditionality is restructuring procurement eligibility across Asia-Pacific planting machinery markets, forcing manufacturers to localize production and certify to jurisdiction-specific emissions and safety standards before accessing state tender pools.
Growth Catalysts
- India's PLI scheme for farm mechanization:Production-linked incentives covering 20-50% of capital expenditure are accelerating domestic manufacturing scale and attracting component suppliers to establish captive facilities in Punjab and Haryana.
- Precision agriculture mandates:China's state farm consolidation directives require variable-rate seeding capability on equipment procured above threshold horsepower ratings, compressing upgrade cycles for legacy drill fleets.
- Rice mechanization gaps in Southeast Asia:Transplanter penetration rates below 15% in Vietnam's Mekong Delta and Indonesia's Java create immediate addressable demand as labor costs rise and seasonal migration patterns destabilize manual transplanting availability.
Market Restraints
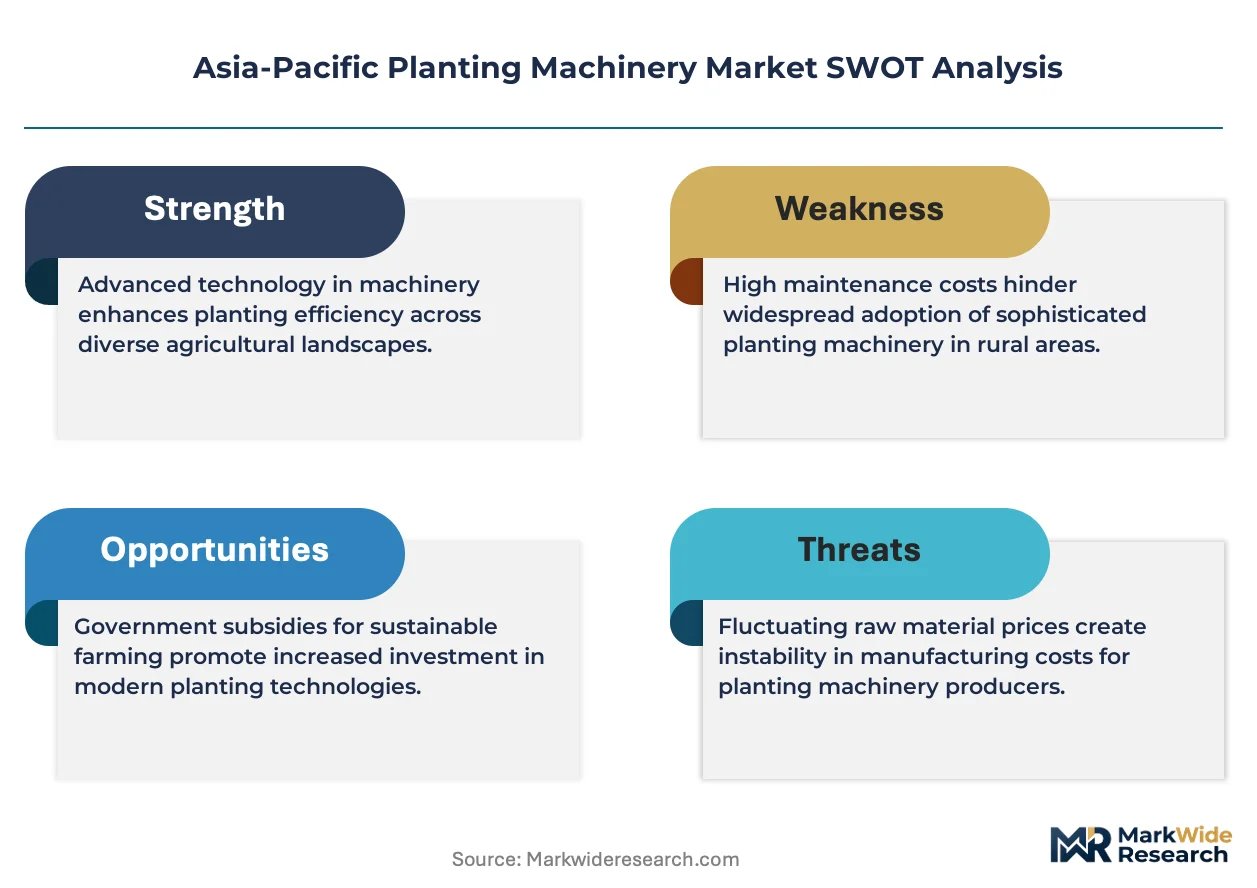
- Steel and hydraulic component volatility:Input cost swings of 12-18% on structural frames and precision metering systems compress OEM margins and destabilize distributor pricing agreements across the region.
- Import dependency for high-accuracy seed sensors:European and North American suppliers control 70% of optical and electromagnetic population sensing technology, creating supply concentration risk and extended lead times for precision seeder builds.
- Stage V-equivalent engine compliance costs:India's CEA and China's MEE emission thresholds add 15-25% to powertrain costs, pricing compact equipment beyond smallholder cooperative budgets in Bangladesh and Myanmar.
Strategic Opportunities
- Electrified drivetrain white space:Battery-electric and hybrid planting platforms under 75kW remain underdeveloped, with first-mover advantage available for systems integrating solar field charging in Australia's broadacre operations.
- Telematics-enabled outcome pricing:Equipment-as-a-service models tying lease payments to establishment uniformity metrics are penetrating New Zealand's contractor fleets, creating recurring revenue streams and locking in aftermarket parts demand.
- East Asian paddy field specialization:Compact automated transplanters with GPS-guided straight-line operation address Japan's agricultural labor shortage and South Korea's aging farmer demographics, commanding 40-60% price premiums over manual-equivalent output.
Industry Challenges
- Precision agriculture technician scarcity:Calibration and repair of GPS-guided seeders and variable-rate controllers requires skills absent from traditional agricultural machinery training pipelines in India and Southeast Asia.
- Multi-jurisdiction certification timelines:Parallel BIS, GB, and JIS approval processes for cross-border equipment launches extend product introduction cycles by 18-24 months and fragment engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Planting Machinery Market |
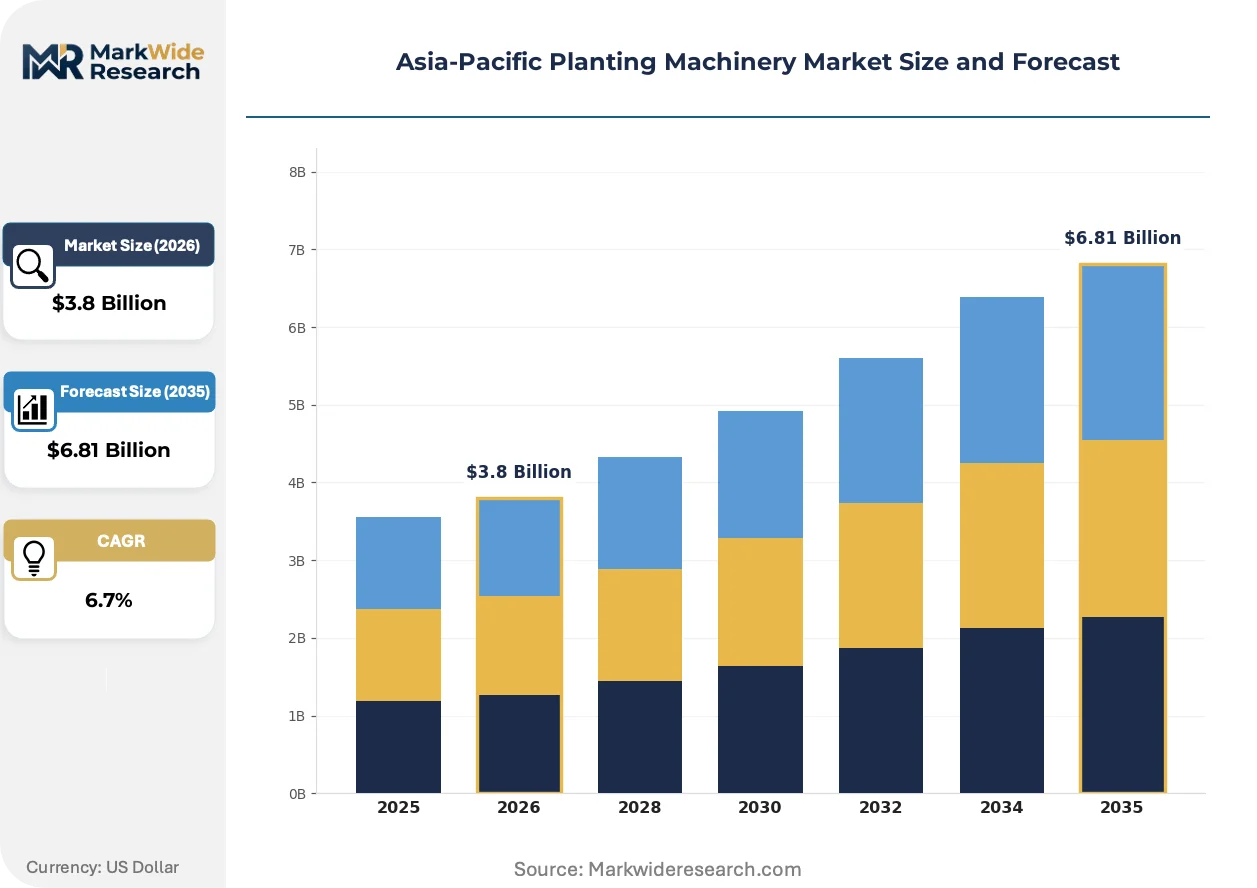
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Seeders, Transplanters, Broadcast Seeders End User: Agricultural Cooperatives, Farmers, Agribusinesses, Contractors Technology: Automated, Manual, Precision, Conventional Application: Crops, Vegetables, Herbs, Ornamental Plants |
| Companies Covered | Deere & Company, AGCO Corporation, Kuhn Group, Kverneland AS, YANMAR HOLDINGS CO., LTD, CNH Industrial N.V., Kubota Corporation, CLAAS KGaA mbH, Mahindra & Mahindra Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Planting Machinery Market Strategic Shifts
Sensor fusion and edge computing are compressing the cost-performance frontier for planting accuracy, enabling mid-market equipment to access capabilities previously restricted to premium-tier platforms in Australian and Chinese commercial operations.
Integrated seed-fertilizer micro-dosing systems are miniaturizing. These units combine pneumatic seed delivery with liquid or granular nutrient placement at 2-5cm precision, eliminating separate pass requirements. Australian broadacre contractors are retrofitting mid-life drills with these modules to capture variable-rate prescription revenue. The technology is miniaturizing the economic threshold for precision adoption, pushing capability down to 100-150 horsepower tractor classes previously served by commodity drills.
China's MEE enforcement of non-road mobile machinery emission standards is accelerating Stage V-equivalent engine adoption. Domestic engine manufacturers are licensing exhaust after-treatment technology from European suppliers to maintain market access. High-horsepower self-propelled transplanters and seeders in the Yangtze River Delta face the steepest compliance costs, driving consolidation toward state-owned equipment fleets with centralized procurement leverage.
Contractor-based service provision is displacing individual ownership in India's Indo-Gangetic Plains. Custom hiring centers aggregating 15-25 planters per village cluster are capturing 30-40% of seasonal planting demand, fragmenting end-user decision-making and shifting specification influence toward fleet operators optimizing utilization rates over individual feature preferences.
Asia-Pacific Planting Machinery Market Segmentation
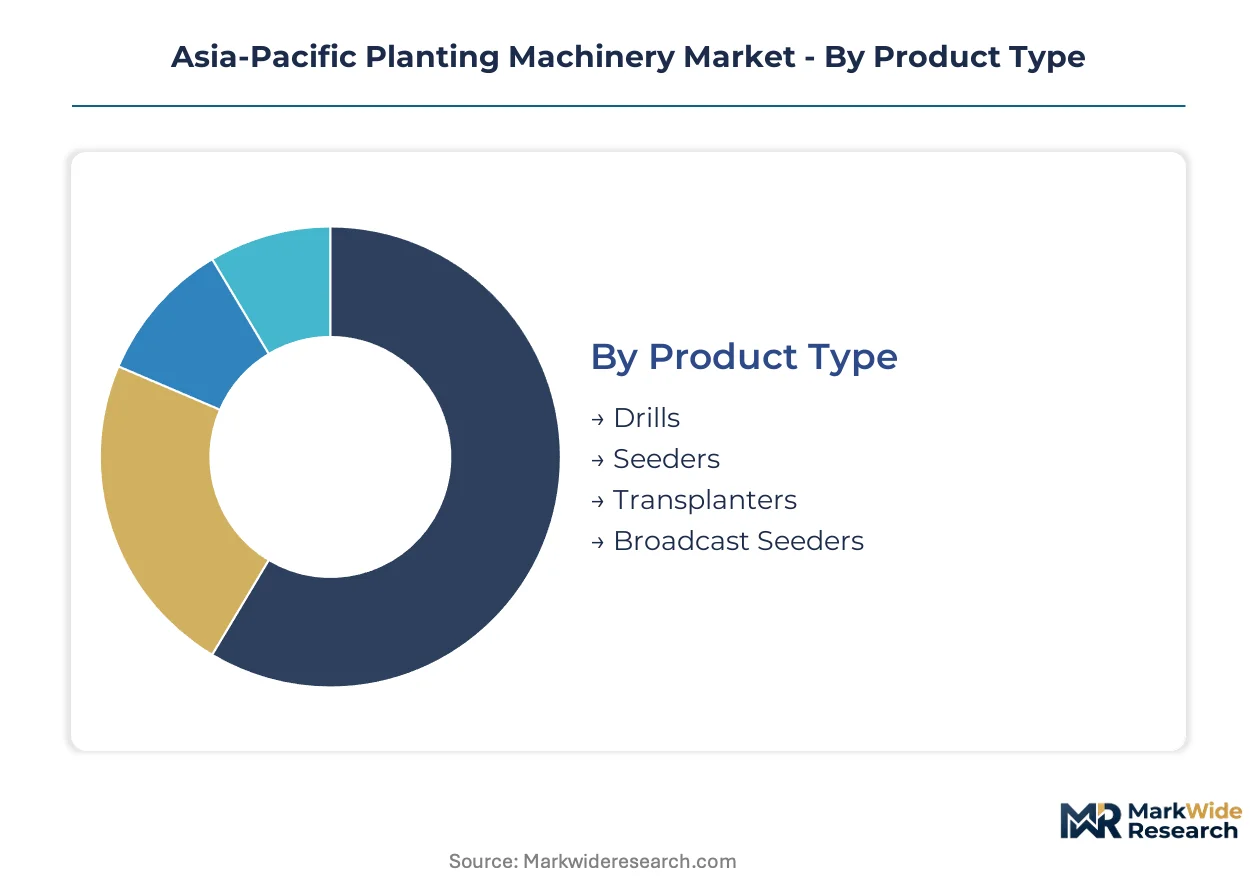
Planting machinery purchasing decisions across Asia-Pacific diverge sharply by operational scale and crop system, with subsidy eligibility and labor availability dictating technology tier selection. Equipment specifications must align with paddy field constraints in East Asia versus broadacre cereal production in Australia and the Indo-Gangetic Plains.
Product Type:
Substitution pressure from manual transplanting and animal-drawn implements weighs heaviest on low-specification drills, while precision-enabled seeders and automated transplanters face minimal direct competition from labor alternatives.
- Drills:Mechanisms place cereal seeds at controlled depth through disc or tine openers, typically tractor-mounted for wheat and barley establishment. India's Indo-Gangetic Plains concentrate demand as Punjab and Haryana cooperatives mechanize winter wheat sowing, though emission compliance costs under CEA regulations compress margins on diesel-powered units below 50 horsepower.
- Seeders:Pneumatic or mechanical metering systems achieve population accuracy within 2-5% of target rates, with GPS-guided variable-rate capability now mandatory for Chinese state farm procurement above threshold horsepower. Australian broadacre contractors prioritize these units for prescription agriculture revenue capture.
- Transplanters:Self-propelled or tractor-mounted systems place rice seedlings at precise spacing and depth, addressing acute labor shortages in Japan and South Korea. Compact models purpose-built for East Asian paddy fields command substantial price premiums over manual-equivalent output.
- Broadcast Seeders:Centrifugal or pneumatic distribution of seed without individual placement control, retained for forage and cover crop applications where establishment uniformity requirements are relaxed. Cost sensitivity among Bangladesh and Myanmar smallholders sustains residual demand despite inferior agronomic outcomes.
Drills anchor the volume base while seeders gain share at the steepest rate.
End User:
Customer type determines specification tier through capital access and utilization intensity, with fleet operators optimizing for depreciation recovery versus individual owners prioritizing feature preferences.
- Agricultural Cooperatives:Aggregated procurement pools across 15-25 machine village clusters in India's Uttar Pradesh and Bihar capture scale discounts and priority service access. Centralized decision-making shifts influence toward fleet managers prioritizing uptime metrics over individual comfort features.
- Farmers:Individual owner-operators dominate Australia's family broadacre holdings and Japan's shrinking rice farm population. Equipment selection balances immediate cash flow constraints against long-term precision agriculture upgrade pathways.
- Agribusinesses:Corporate farming enterprises in China's Heilongjiang and Xinjiang state farm systems deploy centralized procurement leverage to extract compliance cost absorption from OEMs. Standardized fleets simplify maintenance training and parts inventory.
- Contractors:Custom hiring service providers across Vietnam's Mekong Delta and Indonesia's Java island aggregate seasonal demand from smallholders unable to justify individual ownership. Utilization rate optimization drives preference for ruggedized, rapid-attachment systems compatible with multiple tractor brands.
Farmers retain the largest installed base while contractors expand most quickly as service models penetrate Southeast Asia.
Technology:
Cost tier stratification separates premium automation from economy manual systems, with mid-market precision equipment capturing subsidy-enabled upgrade demand.
- Automated:GPS-guided straight-line operation with implement control via ISOBUS protocols, penetrating New Zealand contractor fleets and Australian broadacre operations. Telematics integration enables outcome-based lease pricing tied to establishment uniformity metrics.
- Manual:Operator-dependent depth and spacing control without powered metering, concentrated among Bangladesh and Myanmar smallholder cooperatives where capital constraints and technical service scarcity preclude mechanized alternatives.
- Precision:Variable-rate seeding with real-time population sensing and prescription map execution, required for Chinese state farm procurement and penetrating India's commercial wheat zones. European and North American suppliers control 70% of optical sensing technology, creating supply concentration risk.
- Conventional:Fixed-rate mechanical metering without sensor feedback or prescription capability, dominant in legacy drill fleets across the region. Retrofit precision modules are compressing the economic threshold for upgrade decisions.
Conventional technology holds the volume base while precision systems climb the fastest.
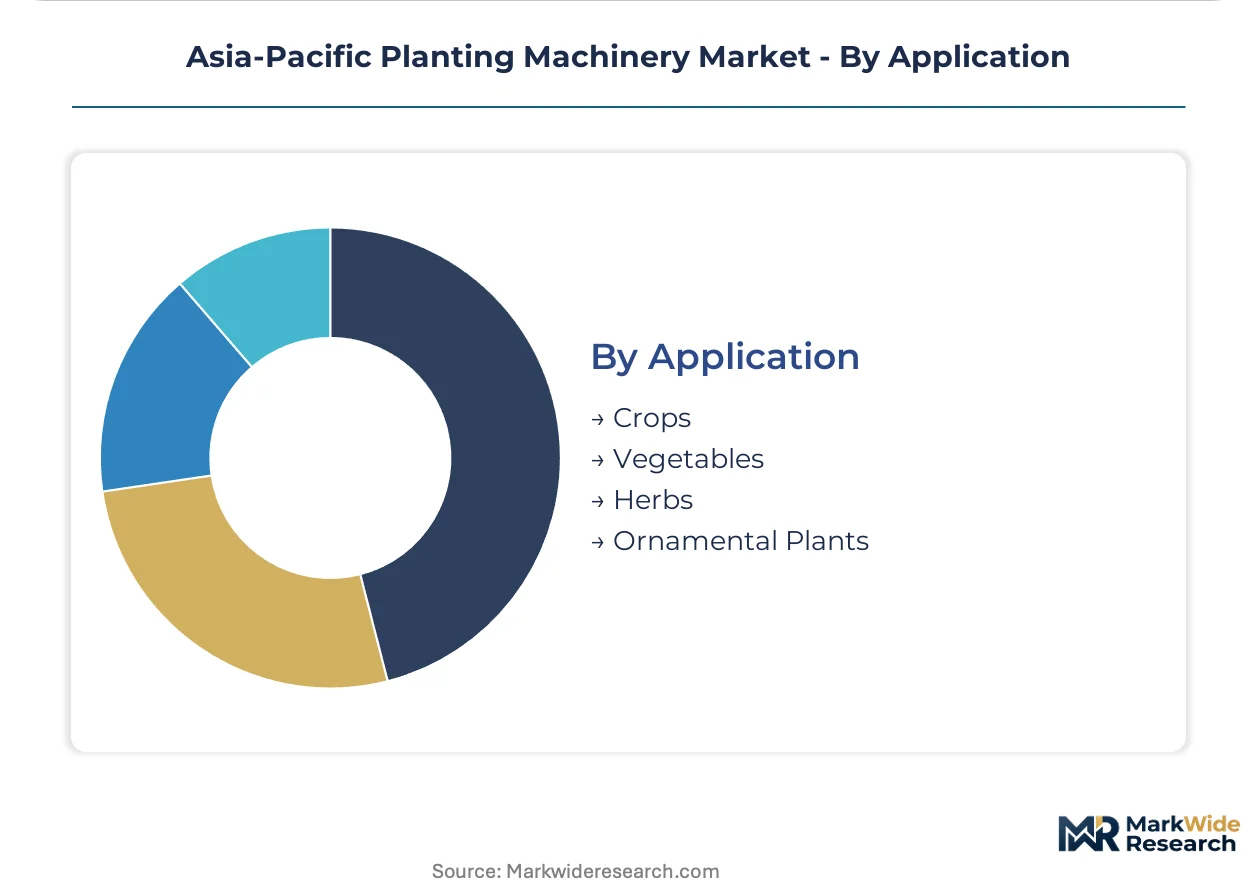
Application:
Geography and crop system dictate machinery specification, with rice paddy constraints in East Asia versus broadacre cereal requirements in South Asia and Australia.
- Crops:Cereal monocultures of wheat, rice, and maize drive the majority of unit demand, with establishment timing critical for yield optimization. India's PLI scheme for farm mechanization targets this segment for domestic manufacturing scale expansion.
- Vegetables:High-value brassicas and solanaceous crops in China's Shandong and Hebei provinces require precise spacing for mechanical cultivation compatibility. Transplanter specialization addresses labor availability constraints in these intensive systems.
- Herbs:Medicinal and aromatic plant establishment in India's Madhya Pradesh and Uttar Pradesh demands gentle handling of small-seeded species. Niche equipment specifications limit supplier competition.
- Ornamental Plants:Nursery stock and floriculture operations in Japan and South Korea utilize specialized plug transplanters. Aging farmer demographics accelerate automation adoption despite limited absolute volume.
Crops dominate the volume base while vegetables show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in India and China where government incentives anchor assembly scale, while demand fragmentation across Southeast Asia creates distinct procurement patterns shaped by subsidy eligibility and labor availability.
India
Punjab and Haryana cooperatives drive tractor-mounted seeder demand as the PLI scheme for farm mechanization subsidizes 20-50% of capital expenditure. India's CEA enforces emission thresholds on diesel-powered equipment below 50 horsepower, compressing margins on compact units. The Indo-Gangetic Plains cluster around Uttar Pradesh and Bihar hosts custom hiring centers aggregating 15-25 planters per village cluster.
China
State farm consolidation in Heilongjiang and Xinjiang mandates variable-rate seeding capability for procurement above threshold horsepower ratings. China's MEE enforces Stage V-equivalent emission standards on non-road mobile machinery, accelerating domestic engine manufacturer licensing of European after-treatment technology. The Yangtze River Delta faces steepest compliance costs for high-horsepower self-propelled transplanters.
Australia
Broadacre contractors prioritize GPS-guided seeders for prescription agriculture revenue capture across New South Wales and Victoria. Australia's ACCC coordinates safety and interoperability standards that shape import eligibility and aftermarket parts availability. Solar field charging integration for battery-electric planting platforms under 75kW remains underdeveloped in Western Australian operations.
Japan
Aging farmer demographics accelerate compact automated transplanter adoption with GPS-guided straight-line operation commanding 40-60% price premiums. Japan's METI shapes safety and interoperability standards alongside equipment performance certification. Kanto and Kansai regions concentrate specialized plug transplanter demand for nursery stock and floriculture operations.
Vietnam
Transplanter penetration rates below 15% in the Mekong Delta create immediate addressable demand as seasonal migration patterns destabilize manual transplanting availability. Rising labor costs push smallholders toward contractor-based service provision. Custom hiring service providers aggregate seasonal demand across Java-scale operations in the delta's intensive rice systems.
Asia-Pacific Planting Machinery Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific planting machinery market. Premium-tier precision agriculture platforms concentrate among integrated multinational equipment manufacturers, while mid-market compact transplanters and tractor-attachment systems fragment across regional specialists. Three archetypes dominate: precision-technology integrators leveraging ISOBUS protocols and telematics, mid-market specialists optimizing paddy-field specifications for East Asian constraints, and cost-focused fabricators exploiting tractor-attachment compatibility across distributed dealer networks. Competitive moves center on strategic partnerships for sensor technology access and geographic expansion through localization commitments tied to subsidy eligibility.
Among precision-technology integrators, Deere & Company and Kubota Corporation occupy positions exemplifying divergent strategic vectors. Deere represents the high-horsepower automated seeder archetype in Australia and New Zealand through integrated platform dominance. Kubota anchors the mid-market compact transplanter specialization purpose-built for East Asian paddy fields. Mahindra & Mahindra Ltd. sits within the cost-focused fabrication tier, competing on tractor-attachment compatibility across India's extensive dealer network. These three players illustrate how geographic origin and structural positioning shape competitive approach without requiring identical capability investment.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| Kuhn Group |
| Kverneland AS |
| YANMAR HOLDINGS CO., LTD |
| CNH Industrial N.V. |
| Kubota Corporation |
| CLAAS KGaA mbH |
| Mahindra & Mahindra Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Indian and Chinese assembly plants shapes regional price floors through scale economies, with emission-compliant powertrain sourcing tethering cost structures to European after-treatment licensing arrangements. India's PLI scheme for farm mechanization compresses domestic price bands by subsidizing 20-50% of capital expenditure, while import dependency for precision seed sensors insulates premium-tier pricing from local cost competition.
Pricing Analysis
India's CEA and China's MEE emission thresholds dictate the pricing tier structure across the Asia-Pacific planting machinery market. Three-tier pricing structure across premium, standard, and economy levels separates GPS-guided variable-rate seeders from conventional mechanical drills and manual equipment. Price differentiation rests on certification grade—BIS and GB standards compliance—and after-sales service bundling through dealer networks. Cost compression in compact diesel units below 50 horsepower is intensifying because Stage V-equivalent after-treatment adds 15-25% to powertrain costs. Smallholder cooperatives in Bangladesh and Myanmar exhibit highest price sensitivity, while Australian broadacre contractors prioritize prescription agriculture capability over upfront expenditure.
Supply Chain Analysis
Inventory cycles for optical seed sensors and electromagnetic population sensing technology extend lead times for precision seeder builds, with European and North American suppliers controlling 70% of high-accuracy component sourcing. Manufacturing concentration centers on India, China, and Japan, with Punjab and Haryana hosting expanding component supplier facilities under PLI incentives. Raw material dependencies span structural steel for frames, hydraulic systems for implement control, and exhaust after-treatment modules for emission compliance. Single-source vulnerability in seed metering technology creates supply concentration risk for precision equipment OEMs. Distribution runs through captive dealer networks in India, state procurement pools in China, and contractor fleet aggregators in Australia's broadacre zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISOBUS protocol standardization and telematics integration are shifting competitive advantage toward platform-ecosystem orchestrators, with equipment-as-a-service models redefining customer lock-in through outcome-based pricing tied to establishment uniformity metrics.
For Market Incumbents: Secure sensor technology supply agreements with European and North American component specialists to defend precision-tier margins against emerging Asian challengers. Deepen backward integration into hydraulic metering systems and exhaust after-treatment modules to absorb CEA and MEE compliance cost inflation. Capacity expansion in India's PLI-eligible zones anchors subsidy access while compressing lead times for Indo-Gangetic Plains cooperatives. For New Entrants and Emerging Players: BIS certification fast-tracks for tractor-mounted seeders below 50 horsepower unlock India's smallholder cooperative segment before emission thresholds tighten further. Battery-electric planting platforms under 75kW represent the most penetrable white space, with solar field charging integration addressing Australia's broadacre contractor demand for carbon-compliant fleet renewal. Telematics-enabled outcome pricing models offer differentiated go-to-market positioning against transactional equipment sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated precision agriculture platforms with aftermarket parts lock-in through proprietary ISOBUS implement control. Long-term viability over the projection horizon favors equipment-as-a-service providers with contractor fleet relationships and prescription agriculture data assets. Acquisition targets should demonstrate established BIS or GB certification pathways and captive distribution in India's custom hiring center networks. Telematics penetration rates in New Zealand contractor fleets signal inflection timing for outcome-based pricing adoption across Asia-Pacific.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | ISOBUS protocol standardization enables telematics-enabled outcome pricing across Australian contractor fleets. |
| Domestic Manufacturing Scale-Up | India's PLI scheme for farm mechanization subsidizes component supplier co-location in Punjab and Haryana. |
| Electrified Drivetrain Development | Battery-electric platforms under 75kW address Australia's solar field charging integration gap in broadacre operations. |
| Certification Fast-Track Investment | Parallel BIS and GB approval processes compress product introduction cycles for cross-border equipment launches. |
| Aftermarket Service Network Expansion | Custom hiring center aggregation in India's Uttar Pradesh and Bihar shifts specification influence toward fleet uptime optimization. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with precision agriculture platform engineers, OEM procurement leads, aftermarket service heads, and custom hiring center fleet managers; and secondary validation through customs and trade data, BIS certification registries, GB standards documentation, and SEC filings from listed equipment manufacturers. Bottom-up triangulation across equipment unit economics and top-down demand modeling from agricultural mechanization policy targets converged on segment-level outputs.
Across the analysis window, the quantitative framework modeled product type, technology tier, end-user archetype, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to equipment replacement cycles and subsidy program scaling trajectories. Forecast inputs incorporated India's PLI scheme disbursement schedules, China's state farm consolidation procurement mandates, and Southeast Asian labor cost migration patterns.
Decision-makers should treat outputs as directional under stable subsidy eligibility and emission threshold enforcement assumptions; material deviation in trade policy or precision agriculture technician training pipeline scaling would warrant model refresh. Specific risk factors include steel and hydraulic component price volatility, single-source seed sensor supply disruptions, and multi-jurisdiction certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market