
 Germany Furniture Market | 2026-2036
Germany Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Furniture Market Analysis
Specialty store networks in Germany is narrowing as e-commerce platforms capture urban consumer traffic. Hülsta-Werke Hüls GmbH anchors its position through vertically integrated manufacturing in North Rhine-Westphalia. IKEA competes on flat-pack logistics and price accessibility across metropolitan markets. Rolf Benz AG & Co. KG differentiates through premium upholstery craftsmanship and designer collaborations.
Germany furniture encompasses movable articles for seating, storage, and work surfaces, typically constructed from engineered wood panels, solid timber, metal frames, or foam-upholstered composites using CNC routing and automated edge-banding processes, serving residential and commercial interior fit-out needs. Wood material dominates volume shipments due to established forestry supply chains and consumer preference for natural finishes. Online retail channels represent the fastest-growing distribution pathway, though showroom-based purchases still command higher average transaction values. Upholstery product types carry concentrated margin pools tied to customization services and fabric grade differentiation.
The EU Green Deal and Germany's national circular economy framework shape timber sourcing certification requirements, while REACH restricts chemical treatments in upholstery foams and surface coatings. KBA building codes and state-level energy efficiency standards influence built-in furniture specifications for new residential construction. Stakeholders must monitor evolving Extended Producer Responsibility obligations for furniture take-back and recycling infrastructure.
Market Dynamics
The Germany furniture market is restructuring around the EU Green Deal's cascading certification demands, which are forcing timber suppliers, foam manufacturers, and upholstery finishers to requalify entire supply chains simultaneously.
Growth Catalysts
- EU Green Deal certification mandates:REACH restrictions on chemical treatments and the EU Timber Regulation are accelerating formaldehyde-free adhesive adoption and FSC-certified wood sourcing among domestic manufacturers.
- Hospitality renovation cycles:Hotel operators in Berlin and Munich are replacing guest room furnishings at compressed intervals, pulling upholstered seating and modular storage systems through specification channels.
- Engineered wood panel advances:Cross-laminated timber and high-density fiberboard with bio-based binders are displacing solid timber in residential shelving and cabinetry applications.
Market Restraints
- Timber input cost volatility:Baltic birch and beech lumber prices fluctuate with Russian supply exclusion, compressing margin buffers for mid-market dining and bedroom furniture producers.
- Regional supply concentration:Foam-upholstery chemical production clusters in the Rhine-Ruhr corridor create single-point vulnerability for seating manufacturers dependent on just-in-time TDI and polyol delivery.
- REACH compliance friction:Biocidal Product Regulation reauthorization delays for wood preservatives extend product launch timelines by eight to fourteen months.
Strategic Opportunities
- North Rhine-Westphalia urban density:Cologne and Düsseldorf's rental housing stock turnover generates replacement demand for compact, flat-pack dining sets and wall-mounted storage.
- Extended Producer Responsibility tailwinds:Germany's national circular economy framework mandates furniture take-back infrastructure, creating service revenue streams for reverse logistics and refurbishment operators.
- Digital-physical channel convergence:Augmented reality room visualization tools are compressing online purchase decision cycles for upholstered goods previously requiring showroom validation.
Industry Challenges
- Automation technician scarcity:CNC routing and robotic edge-banding equipment maintenance requires specialized mechatronics skills concentrated in Baden-Württemberg's automotive supplier belt.
- KBA code compliance complexity:State-level building energy standards for built-in residential furniture vary between Bavaria and Lower Saxony, fragmenting product specification databases.
- Legacy ERP integration friction:Mid-tier manufacturers operating on 1990s-era MRP systems face data migration costs when connecting to retailer EDI networks for real-time inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Furniture Market |
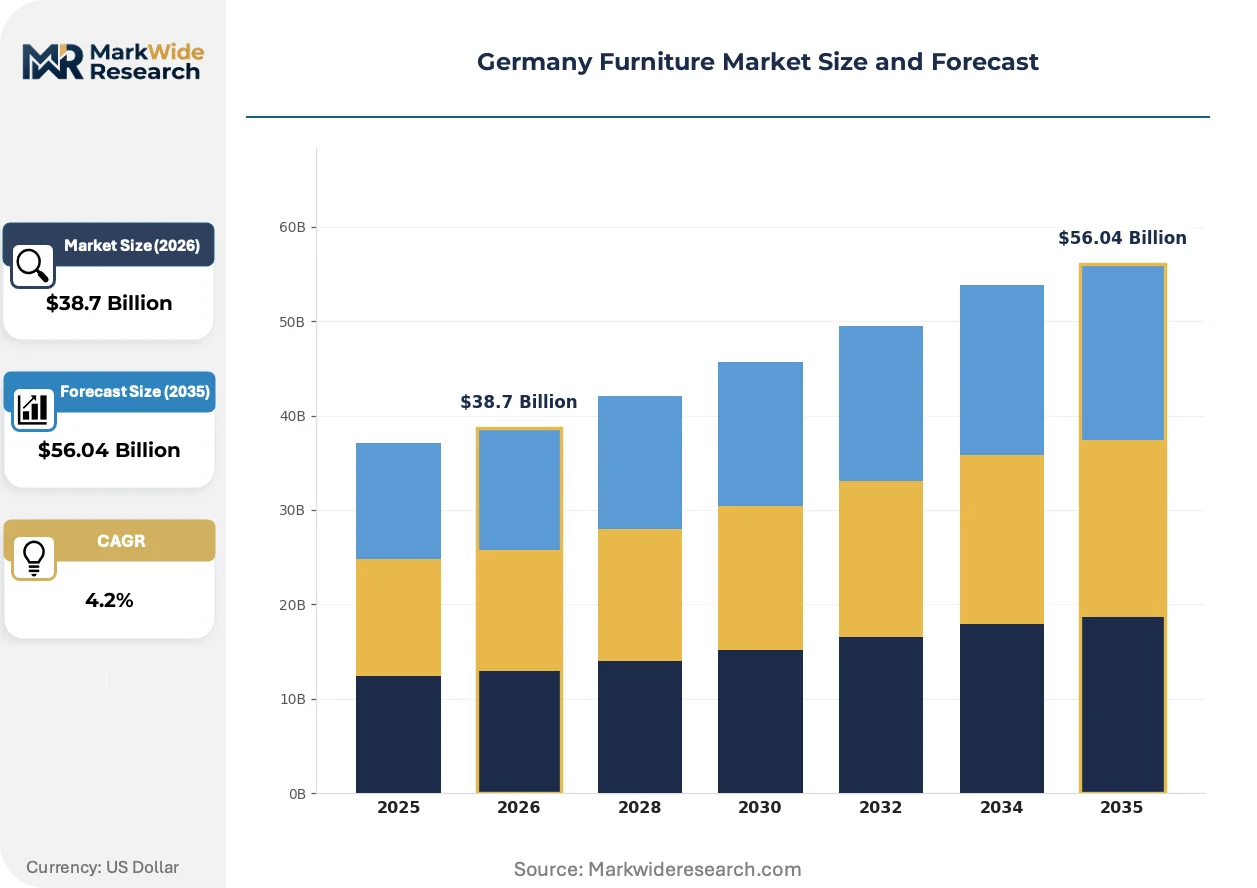
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Plastic, Upholstery Distribution Channel: Online Retail, Showrooms, Wholesalers, Specialty Stores End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Hülsta-Werke Hüls GmbH, Segmüller Polstermöbelfabrik GmbH & Co. KG, IKEA, Schmidt Küchen GmbH & Co. KG, Rolf Benz AG & Co. KG, XXXLutz KG, Rauch Möbelwerke GmbH, SieMatic, Nobilia AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Furniture Market Emerging Trajectories
Digital configuration tools and bio-based material substitutes are compressing traditional product development cycles while regulatory pressure on chemical inputs intensifies formulation R&D spending.
Augmented reality visualization software is virtualizing the furniture selection process for urban apartment renters. Younger buyers in Hamburg and Frankfurt now configure sectional sofas and dining sets through smartphone cameras before visiting showrooms for fabric tactile validation. This compression of consideration phases is reducing return rates for online upholstery orders.
The EU Green Deal's cascading due diligence requirements are reshaping timber procurement documentation. EUDR deforestation-free supply chain verification now demands geolocation data for harvested logs, forcing importers to restructure Baltic and Scandinavian supplier contracts. Bavarian case goods manufacturers are absorbing traceability system costs that smaller competitors cannot amortize.
Corporate furniture procurement through interior design studios is fragmenting as facility managers in Berlin's tech sector adopt direct-to-manufacturer sourcing for open-plan workstations. This disintermediation bypasses traditional specification layers, compressing project margins but accelerating delivery timelines for customized benching and storage systems.
Germany Furniture Market Segmentation
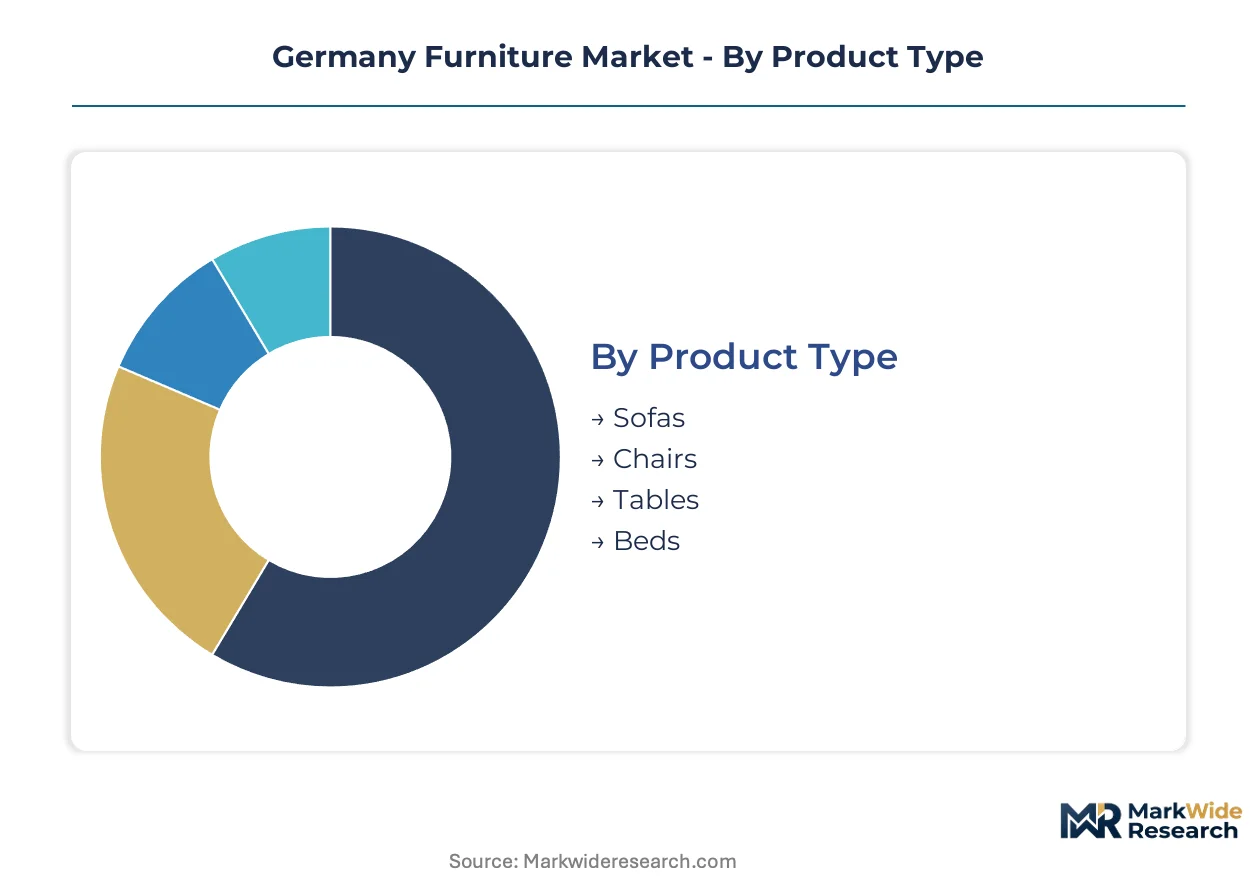
German furniture purchasing patterns diverge sharply across living contexts, from compact urban apartments demanding space-efficient solutions to hospitality properties requiring rapid refurbishment cycles. Segmentation reveals how material preferences, channel behaviors, and end-use specifications create distinct margin profiles and supply chain requirements for manufacturers.
Product Type:
Mature categories dominate residential spending while emerging formats respond to remote work and micro-living trends in North Rhine-Westphalia and Bavaria.
- Sofas:Modular sectional configurations with high-resilience foam cores and removable fabric covers command premium positioning in Berlin and Munich rental markets. Hospitality procurement concentrates on fire-retardant upholstery grades for hotel lobbies and guest rooms, with compressed replacement cycles driving specification volume.
- Chairs:Ergonomic task seating with adjustable lumbar support and mesh backs is displacing fixed-frame dining chairs in home office applications across Hamburg and Frankfurt. Corporate facility managers prioritize certified durability testing for 8-hour daily use.
- Tables:Extendable dining surfaces with ceramic or compact laminate tops address space constraints in Cologne's high-density housing stock.
- Beds:Storage-integrated platform frames with upholstered headboards capture share from traditional slatted bases in Düsseldorf's rental market.
Sofas retain volume leadership; chairs hold the steepest expansion curve.
Material:
Cost tier stratification separates premium solid timber from economy panel constructions, with bio-based alternatives creating new mid-market positioning.
- Wood:Cross-laminated timber and FSC-certified beech solids anchor premium residential cabinetry in Bavarian manufacturing clusters. EUDR traceability requirements now demand geolocation documentation for Baltic birch imports, raising compliance costs for mid-market dining furniture.
- Metal:Powder-coated steel frames with recycled aluminum content serve commercial workstation and outdoor furniture applications. REACH restrictions on hexavalent chromium plating accelerate water-based coating adoption.
- Plastic:Post-consumer polypropylene shells molded for stackable seating address institutional bulk procurement in Lower Saxony schools and municipal facilities.
- Upholstery:Bio-based polyurethane foams with natural latex layers differentiate premium seating in Stuttgart's design-conscious consumer base.
Wood commands the largest shipment volumes; upholstery materials climb the fastest on customization premiums.
Distribution Channel:
Customer type fragmentation separates digital-native renters from tactile-preference older buyers, reshaping last-mile logistics requirements.
- Online Retail:Augmented reality visualization tools now compress purchase cycles for upholstered goods previously requiring showroom validation. Flat-pack logistics networks enable next-day delivery across metropolitan zones.
- Showrooms:Tactile fabric libraries and configuration studios sustain higher average transaction values for premium leather and designer collaborations.
- Wholesalers:Project-based volume procurement for hospitality and institutional fit-outs runs through specification intermediaries with KBA code compliance expertise.
- Specialty Stores:Curated assortments in Cologne's Ehrenstraße and Munich's Sendlinger Straße concentrate high-margin designer furniture traffic.
Online retail gains share fastest; showrooms preserve margin concentration.
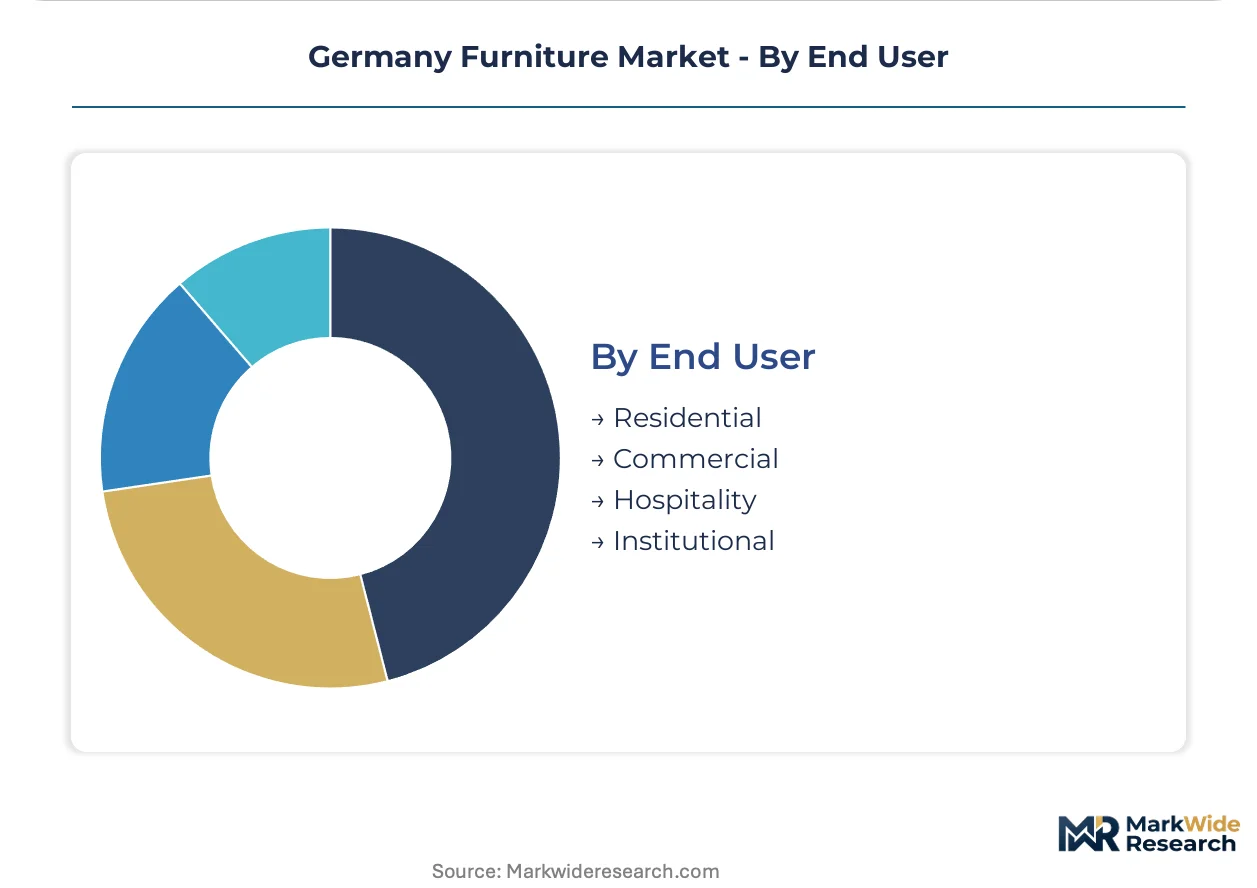
End User:
Application context determines specification intensity, with commercial and hospitality buyers imposing certification and durability standards absent in residential segments.
- Residential:Compact, multifunctional furniture for rental housing turnover in North Rhine-Westphalia drives replacement demand for wall-mounted storage and nesting tables.
- Commercial:Open-plan benching systems with acoustic privacy panels and cable management integrate with Berlin tech sector workplace designs.
- Hospitality:Berlin and Munich hotel renovation cycles pull upholstered seating and modular guest room systems through accelerated procurement timelines.
- Institutional:Extended Producer Responsibility mandates shape furniture take-back and refurbishment service contracts for public sector procurement.
Residential maintains volume dominance; hospitality exhibits the sharpest demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium upholstery manufacturers in Bavaria command pricing power that flat-pack producers in North Rhine-Westphalia cannot replicate, creating a structural margin asymmetry across German manufacturing clusters.
North Rhine-Westphalia
Cologne and Düsseldorf rental housing turnover drives replacement demand for compact dining sets and wall-mounted storage systems. KBA building codes for energy-efficient residential construction shape built-in furniture specifications across the state. The Rhine-Ruhr corridor concentrates foam-chemical production for seating manufacturers, creating supply vulnerability during TDI and polyol delivery disruptions.
Bavaria
Munich's hospitality renovation cycles accelerate procurement timelines for upholstered guest room furnishings and modular lobby systems. EUDR deforestation-free supply chain verification demands geolocation documentation for Baltic birch imports, raising compliance costs for case goods manufacturers. Nuremberg and Augsburg host precision woodworking clusters specializing in FSC-certified beech solids for premium cabinetry.
Baden-Württemberg
Stuttgart's design-conscious consumer base pulls bio-based polyurethane foams with natural latex layers into premium seating configurations. REACH restrictions on hexavalent chromium plating accelerate water-based coating adoption among metal frame fabricators. The state's automotive supplier belt concentrates mechatronics skills for CNC routing and robotic edge-banding equipment maintenance.
Lower Saxony
Institutional bulk procurement for schools and municipal facilities drives demand for post-consumer polypropylene stackable seating. Extended Producer Responsibility mandates under Germany's circular economy framework shape furniture take-back service contracts for public sector buyers. Hanover anchors distribution networks serving northern European export corridors.
Berlin-Brandenburg
Tech sector facility managers adopt direct-to-manufacturer sourcing for open-plan workstations, bypassing traditional interior design studio intermediaries. State-level energy efficiency standards for built-in residential furniture vary from Bavarian requirements, fragmenting product specification databases. The capital's showroom density sustains tactile fabric validation for online upholstery purchases.
Germany Furniture Market Vendor Landscape
Vertically integrated heritage manufacturers and flat-pack logistics specialists split the market along price-accessibility and customization-depth axes. The vendor base concentrates around three strategic archetypes: premium upholstery craftsmen with designer collaborations, mass-market retailers with captive supply chains, and mid-market specialists in engineered wood systems. Competitive positioning hardens through backward integration into timber sourcing and forward integration into augmented reality configuration tools.
Among vertically integrated heritage fabricators, Hülsta-Werke Hüls GmbH exemplifies the premium-systems archetype through its North Rhine-Westphalia manufacturing base. Rolf Benz AG & Co. KG occupies a parallel position in upholstered seating craftsmanship. IKEA anchors the mass-market vector with metropolitan flat-pack logistics networks. These three represent the structural poles around which smaller specialists organize their competitive responses.
| Leading Market Players |
|---|
| Hülsta-Werke Hüls GmbH |
| Segmüller Polstermöbelfabrik GmbH & Co. KG |
| IKEA |
| Schmidt Küchen GmbH & Co. KG |
| Rolf Benz AG & Co. KG |
| XXXLutz KG |
| Rauch Möbelwerke GmbH |
| SieMatic |
| Nobilia AB |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Baltic birch plywood mills is compressing input costs for mid-market case goods manufacturers while simultaneously eroding supplier pricing power, creating divergent margin trajectories between raw material converters and finished goods producers across German manufacturing clusters.
Pricing Analysis
Configured-to-order pricing for premium upholstery commands spreads of three to four multiples over standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and fabric origin. Cost compression in the standard tier intensifies because Baltic birch import volatility forces producers to absorb margin hits rather than pass through increases. Hospitality buyers exhibit the lowest price sensitivity due to compressed replacement cycles, while municipal procurement in Lower Saxony demonstrates acute budget discipline.
Supply Chain Analysis
Upstream feedstock flows for foam-chemical production draw from petroleum refineries concentrated in the Netherlands, Belgium, and the Rhine-Ruhr corridor. TDI and polyol inputs for polyurethane cushioning rest on naphtha cracking capacity that faces carbon-border adjustment exposure. Single-source vulnerability characterizes just-in-time chemical delivery to North Rhine-Westphalia seating plants. Distribution runs through flat-pack logistics networks anchored in Hanover and metropolitan fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture-as-a-service and take-back refurbishment contracts represent the fastest-expanding revenue layer, with circular economy mandates from Berlin accelerating adoption faster than traditional product sales across institutional procurement channels.
For Market Incumbents: Entrench market position through backward integration into FSC-certified timber sourcing and captive foam-chemical production in the Rhine-Ruhr corridor. Direct-to-manufacturer procurement by Berlin tech facility managers threatens specification-channel margins. Certification investment in EUDR traceability systems creates defensive moats that smaller competitors cannot replicate. For New Entrants and Emerging Players: Mid-market commercial workstations for Berlin tech sector facility managers represent the most penetrable entry point, bypassing entrenched specification intermediaries. Augmented reality configuration tools for upholstered goods offer a go-to-market angle that compresses customer acquisition costs versus showroom-dependent incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among refurbishment and take-back service operators with institutional contracts under Germany's Extended Producer Responsibility framework. Long-term viability over the next decade favors acquisition targets with circular economy infrastructure and reverse logistics capabilities. Monitor EUDR compliance cost absorption rates as an inflection indicator for competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber | FSC and EUDR-compliant sourcing secures supply continuity for Bavarian case goods manufacturers facing Baltic import volatility. |
| Augmented Reality Configuration Platform | Virtual upholstery visualization compresses purchase cycles for online buyers previously requiring showroom tactile validation. |
| Circular Economy Service Infrastructure | Take-back and refurbishment capabilities generate recurring revenue under Germany's Extended Producer Responsibility mandates. |
| Foam-Chemical Captive Production | In-house TDI and polyol manufacturing insulates seating producers from Rhine-Ruhr corridor delivery disruptions. |
| Direct-to-Facility-Manager Channel | Bypassing specification intermediaries accelerates procurement timelines for Berlin tech sector open-plan workstation deployments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with furniture manufacturing executives, procurement leads at hospitality operators, facility managers in Berlin's tech sector, and circular economy service providers; alongside secondary validation through EU Timber Regulation filings, KBA building code databases, REACH authorization records, and German customs trade statistics. Bottom-up shipment data from engineered wood panel and upholstery foam producers triangulated against top-down retail channel estimates.
Forecast inputs across the projection horizon incorporated product type segmentation by configuration complexity, material grade tiers, distribution channel digitalization rates, and end-use application durability requirements. CAGRs derived from regression analysis of historical replacement cycle data and regulatory compliance cost trajectories. Modeling specifically addressed EU Green Deal cascading certification timelines and EUDR geolocation documentation implementation phases.
Practitioners should monitor Baltic birch import quota adjustments and REACH biocidal reauthorization delays for early signals of forecast revision. Cross-checking against Eurostat furniture production indices and German Federal Statistical Office retail turnover data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
North America High-End Furniture Market
Furniture
North America Smart Furniture Market
Furniture
US School Furniture Market
Furniture
Kids Table and Chair Market
Furniture
Poland Home Furniture Market
Furniture
United Kingdom Home Furniture Market
Furniture
Global Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
India Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
Japan Home Furniture Market
Furniture
Europe Smart Furniture Market
Furniture
India Home Furniture Market
Furniture
Salon Chairs Market
Furniture
HORECA Furniture Market