
 North America High-End Furniture Market | 2026-2036
North America High-End Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America High-End Furniture Market Analytics
Custom upholstery with certified hardwood frames is unwinding a long cycle of mass-produced imports. Restoration Hardware (RH) leverages its vertically integrated supply chain to control leather finishing and timber provenance. Baker Furniture anchors its position through archival design licensing and made-to-order craftsmanship. Bernhardt competes on manufacturing scale across its North Carolina plants while sustaining quick-ship programs for interior designers.
North America high-end furniture comprises premium seating, case goods, and decorative accessories built with kiln-dried hardwoods, eight-way hand-tied springs, and artisan-applied finishes for residential estates, luxury hospitality properties, and executive commercial spaces. Living room and bedroom categories dominate current order books, with hospitality-driven upholstery posting the fastest expansion as boutique hotel chains refresh properties. Wood and upholstery materials command the deepest margin pools due to certified sourcing premiums and labor-intensive fabrication.
EPA TSCA Title VI regulates composite wood formaldehyde emissions, while California Air Resources Board (CARB) maintains stricter in-state thresholds that de facto shape national sourcing standards. The Consumer Product Safety Commission oversees flammability testing for upholstered products, adding compliance layers to foam and fabric selection. Stakeholders must monitor how state-level chemical disclosure laws proliferate beyond California and determine whether to centralize compliance or regionalize product lines.
Market Dynamics
EPA TSCA Title VI formaldehyde emission caps are compressing composite wood supply chains, forcing manufacturers to requalify overseas laminators and redirect procurement toward certified Appalachian and Great Lakes hardwood suppliers.
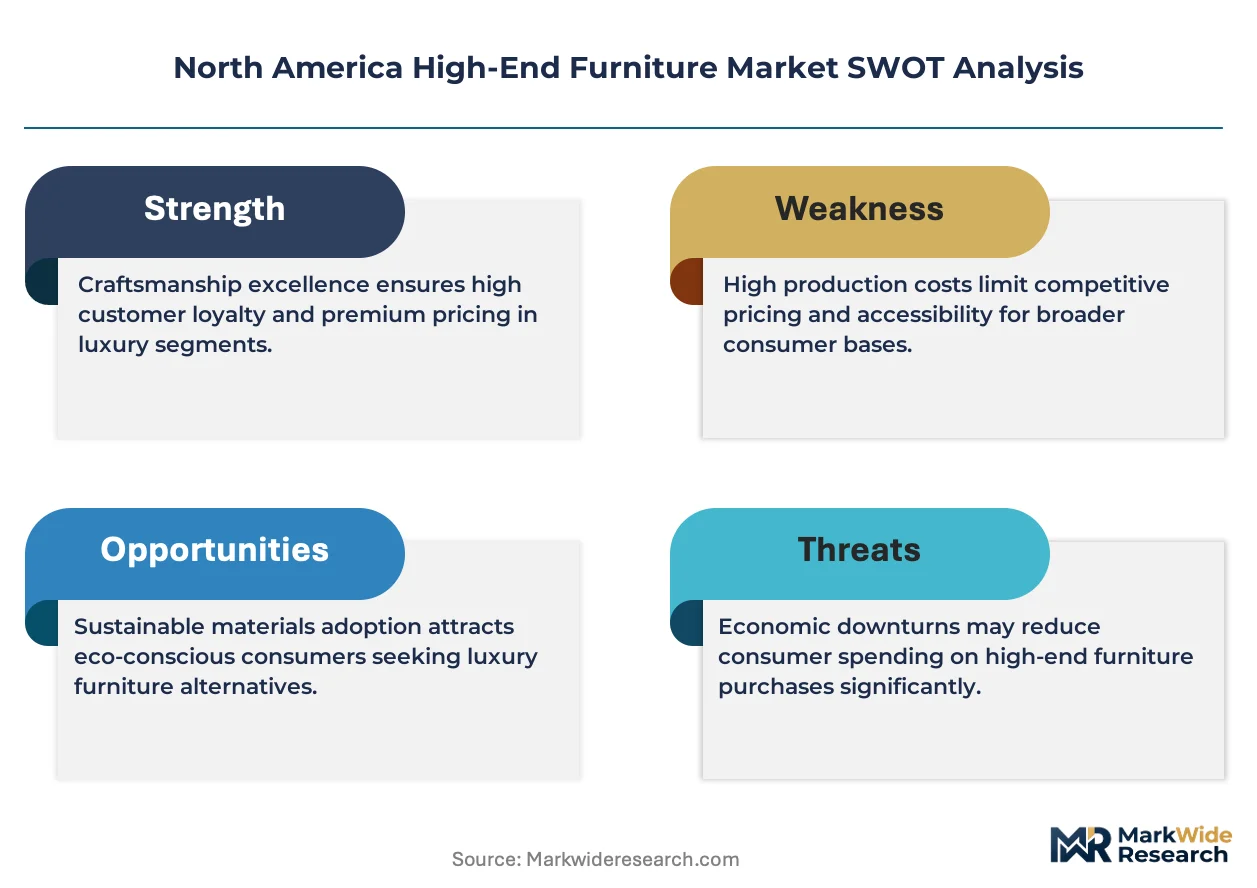
Growth Catalysts
- Luxury Hospitality Refresh Cycles:Boutique hotel chains in California and Texas are replacing upholstered seating every 36-48 months, creating recurring demand for fire-retardant foam and performance fabrics.
- CARB ATCM Phase 2:California's stricter composite wood standards have become the de facto national benchmark, compelling suppliers to upgrade adhesive formulations and capture premium positioning.
- Digital Fabric-to-Frame Visualization:Real-time rendering tools allow interior designers to approve custom upholstery specifications remotely, compressing order-to-production timelines.
Market Restraints
- Kiln-Dried Hardwood Concentration:Appalachian sawmill capacity limits create bottlenecks during peak construction seasons, exposing manufacturers to 8-14 week lead time volatility.
- Artisan Labor Pool Scarcity:Eight-way hand-tied spring installation requires 3-5 year apprenticeships; North Carolina training programs graduate fewer than 200 qualified upholsterers annually.
- Flammability Testing Burden:CPSC 16 CFR Part 1633 mattress and upholstery standards add $12,000-$18,000 per SKU certification, disproportionately burdening small-batch producers.
Strategic Opportunities
- Texas Urban Corridor Expansion:Dallas, Houston, and Austin luxury residential towers are specifying European-inspired case goods with domestic hardwood provenance, opening white space for regional manufacturers.
- Biobased Adhesive Convergence:Soy-protein and lignin-based resins meeting TSCA Title VI thresholds offer differentiation against petroleum-derived competitors.
- Designer Direct Channels:Bypassing traditional furniture galleries through trade-only showrooms in Miami Design District and Manhattan's Flatiron district captures 18-22 point margin improvement.
Industry Challenges
- Master Craftsman Succession:French polishing and hand-rubbed lacquer expertise concentrates among workers aged 55+; knowledge transfer programs lack standardized curricula.
- Multi-Jurisdiction Compliance:New York's chemical disclosure laws and Vermont's wood sourcing transparency requirements fragment product configuration management.
- Legacy ERP Integration:Made-to-order configurators struggle to synchronize with 1990s-era inventory systems, forcing parallel manual tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America High-End Furniture Market |
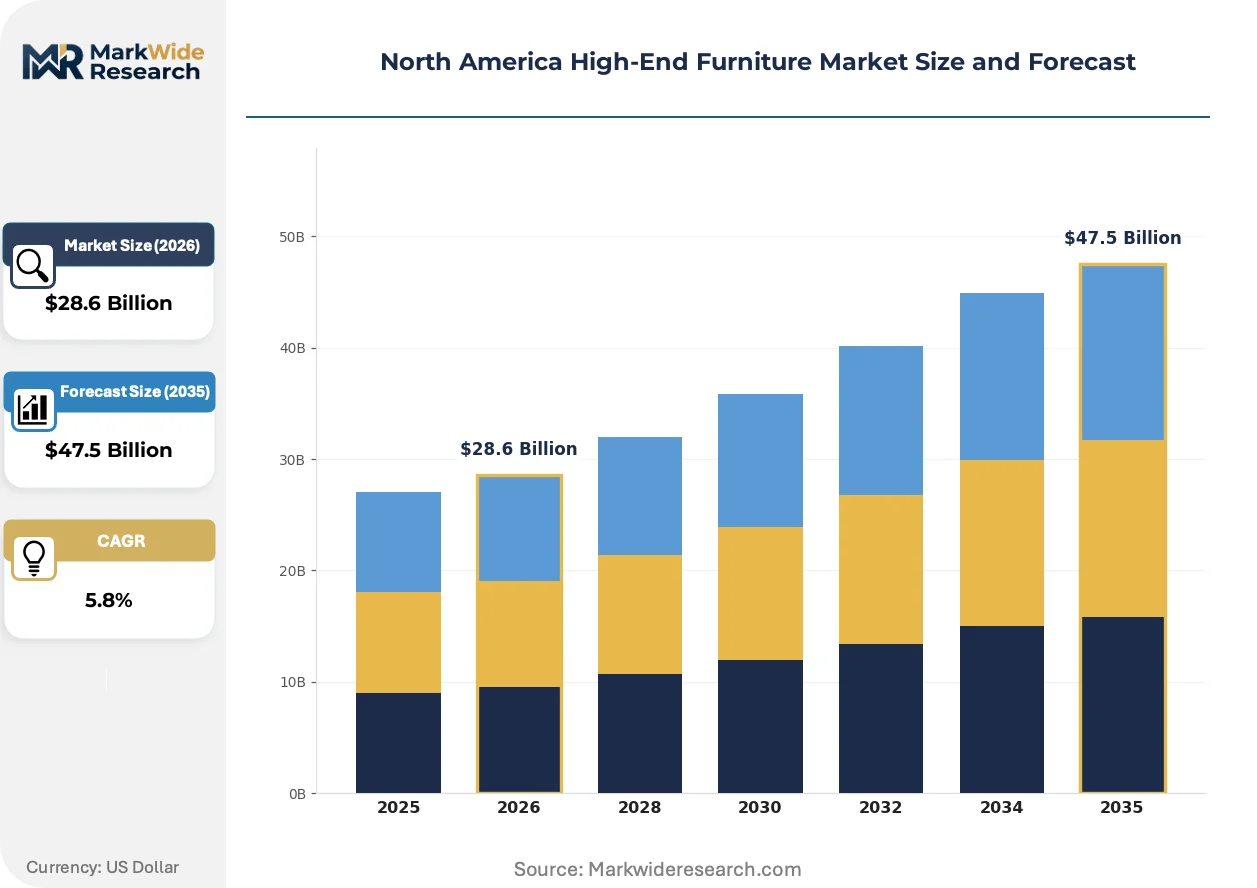
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Living Room, Bedroom, Dining Room, Office Material: Wood, Metal, Upholstery, Glass End User: Residential, Commercial, Hospitality, Retail Style: Modern, Traditional, Contemporary, Rustic |
| Companies Covered | Restoration Hardware (RH), Baker Furniture, Bernhardt, Century Furniture, Mitchell Gold + Bob Williams, Vermont Woods Studios, Copeland Furniture, Sherrill Furniture, Best Home Furnishings, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America High-End Furniture Market Evolving Landscape
Material science breakthroughs and regulatory stringency are converging to redefine how high-end furniture is specified, fabricated, and certified across residential and commercial channels.
Water-based UV-curable finishes are displacing solvent-based conversion varnishes in premium case goods manufacturing. Manhattan-based interior design studios now specify these coatings for 60% of new residential commissions. The shift eliminates volatile organic compound emissions during curing, enabling manufacturers to locate finishing operations closer to urban delivery hubs without air quality permitting delays.
EPA TSCA Title VI third-party certification requirements are reshaping wood procurement documentation. Manufacturers must now maintain chain-of-custody records from forest harvest through panel fabrication, adding administrative overhead but creating defensible positioning against uncertified imports. California's Air Resources Board maintains audit authority over out-of-state suppliers shipping into the state, effectively nationalizing compliance scope.
Designer procurement patterns are fragmenting away from traditional gallery representation toward direct mill relationships. Texas and Florida hospitality projects increasingly source upholstery frames from North Carolina plants and textiles from Belgian mills through unified digital platforms. This disintermediation compresses specification cycles from 12 weeks to 4 weeks but requires manufacturers to absorb credit risk and logistics coordination previously handled by intermediaries.
North America High-End Furniture Market Segmentation
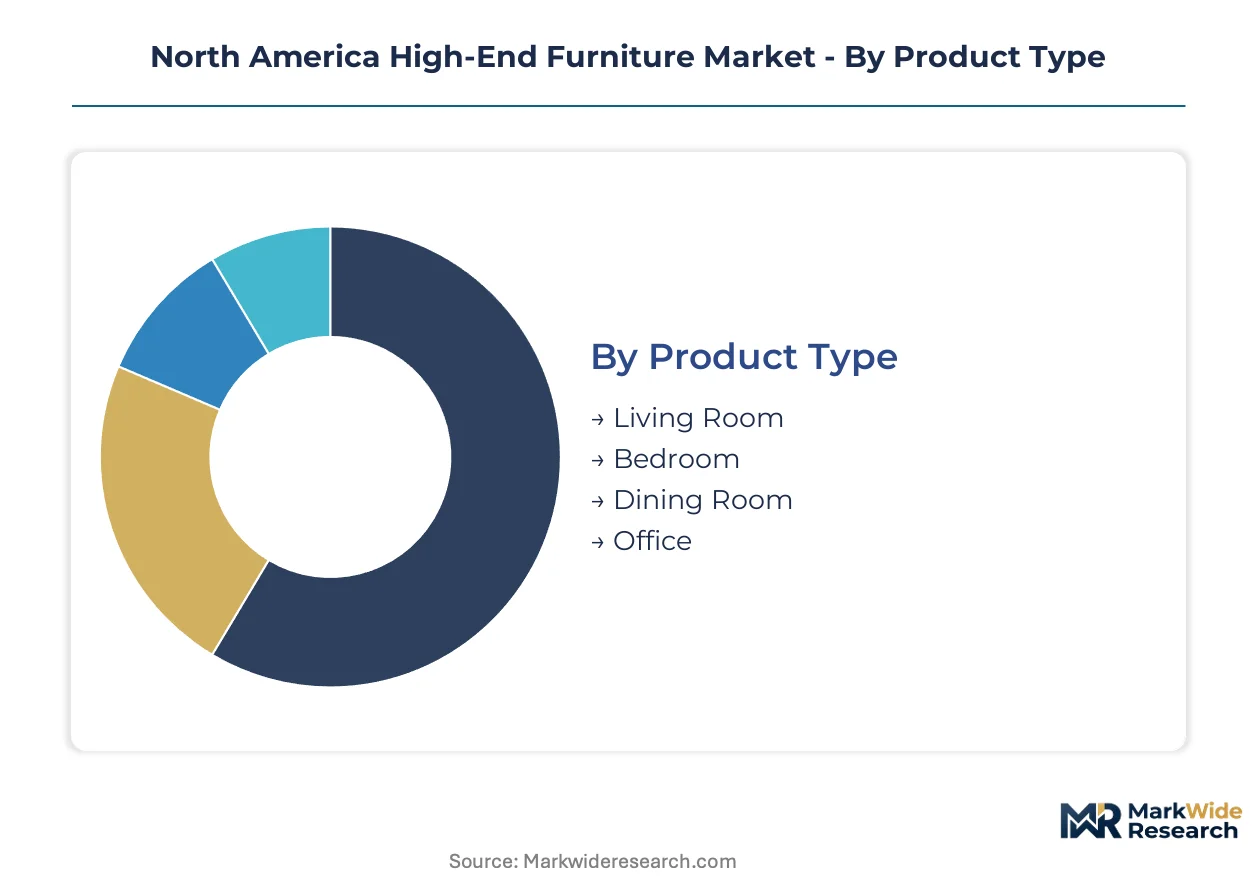
High-end furniture segmentation reveals how EPA compliance costs and artisan labor scarcity concentrate margin pressure unevenly across product categories. Material and end-use boundaries are blurring as hospitality clients specify residential-grade craftsmanship and residential buyers demand commercial-grade durability.
Product Type:
Living room and bedroom categories face the strongest substitution pressure from mass-market performance fabric alternatives, while dining and office segments defend position through irreplaceable hardwood craftsmanship.
- Living Room:Premium seating and case goods built with kiln-dried hardwood frames and eight-way hand-tied springs command the deepest specification involvement from Manhattan and Miami design studios. California's boutique hotel refresh cycles are expanding demand for fire-retardant foam configurations that meet CPSC 16 CFR Part 1633 without sacrificing residential aesthetic standards.
- Bedroom:Solid wood bed frames and artisan-finished dressers concentrate sourcing compliance burdens due to CARB ATCM Phase 2 panel requirements for case interiors. Texas urban residential towers are specifying European-inspired silhouettes with Appalachian hardwood provenance, creating specification tension between imported design references and domestic material mandates.
- Dining Room:Extension tables and credenzas require precision joinery that resists offshore replication; North Carolina plants sustain competitive position through quick-ship programs for interior designers.
- Office:Executive desks and conferencing systems are absorbing hospitality-derived performance fabric specifications as residential clients prioritize durability for home workspaces.
Living room anchors the volume base while bedroom gains share at the steepest rate.
Material:
Cost tier stratification runs sharpest across material categories, with certified wood commanding premium positioning and glass facing commoditization from architectural glazing suppliers.
- Wood:Appalachian and Great Lakes hardwood suppliers are capturing procurement redirection as EPA TSCA Title VI forces requalification away from overseas laminators. Chain-of-custody documentation from forest harvest through panel fabrication now determines supplier eligibility for California-bound shipments.
- Upholstery:Leather finishing and textile specification concentrate margin control among vertically integrated manufacturers; Belgian mills are gaining direct relationships with Texas and Florida hospitality projects through unified digital platforms.
- Metal:Powder-coated steel and brass accents serve structural and decorative functions with lower compliance overhead than composite wood substrates.
- Glass:Tempered tabletops and display shelving face pricing pressure from specialty architectural suppliers with scale advantages in raw material procurement.
Wood dominates revenue contribution while upholstery expands most quickly through hospitality specification.
End User:
Customer type segmentation reveals diverging procurement sophistication, with hospitality buyers compressing specification cycles and residential clients extending decision timelines for custom commissions.
- Residential:Luxury estate buyers in Manhattan and Miami are expanding custom upholstery orders with certified hardwood frame requirements that exceed mass-market durability standards. Digital fabric-to-frame visualization tools are compressing approval timelines for remote designer-client collaboration.
- Hospitality:Boutique hotel chains in California and Texas are replacing upholstered seating every 36-48 months, creating recurring demand for fire-retardant foam and performance fabrics with accelerated wear testing protocols.
- Commercial:Executive office and corporate lounge specifications are adopting hospitality-grade durability standards without corresponding budget expansion.
- Retail:High-end furniture galleries face disintermediation pressure as designer direct channels capture 18-22 point margin improvement through trade-only showrooms.
Residential anchors the volume base while hospitality climbs the fastest on refresh cycle recurrence.
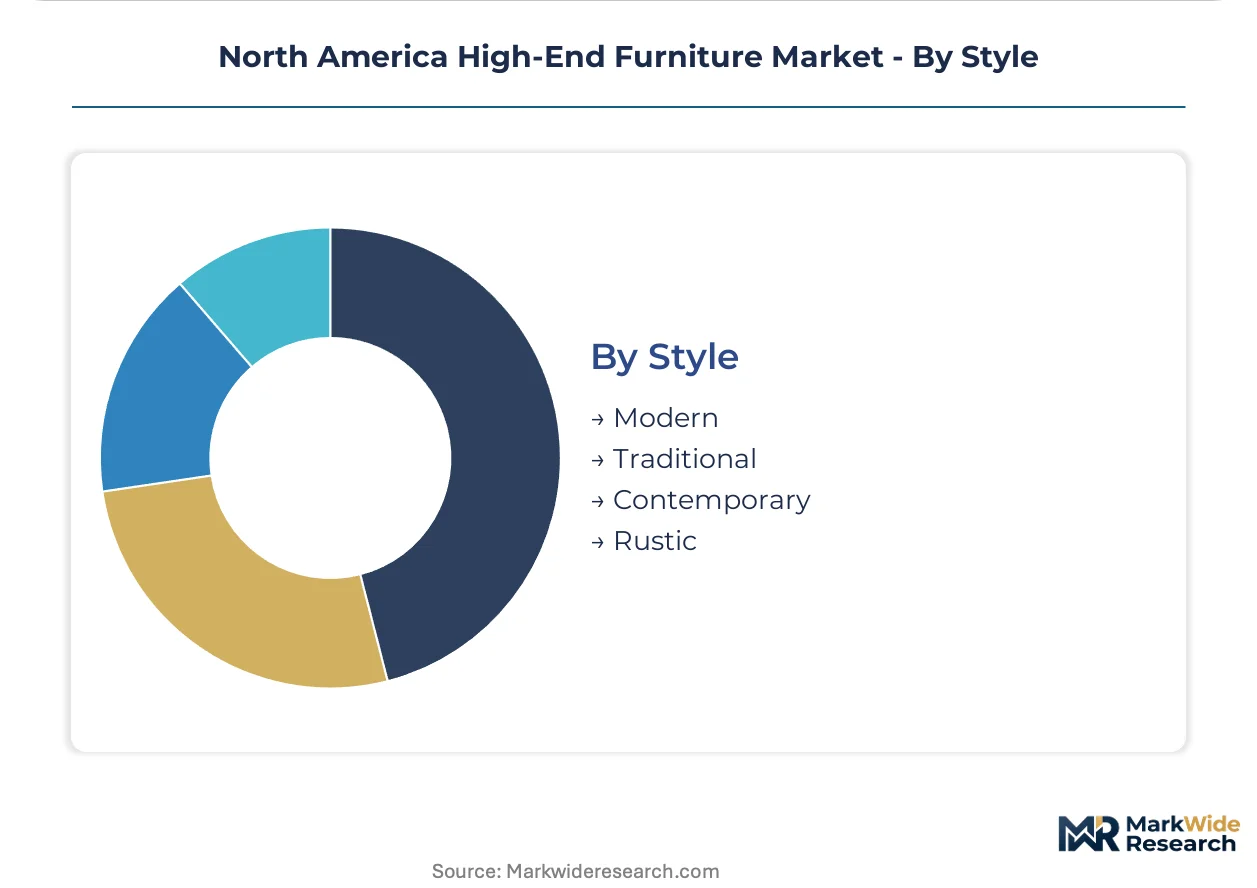
Style:
Maturity gradients separate established style categories from emerging positioning, with traditional craftsmanship defending margin through scarcity and modern lines facing replication pressure from contemporary competitors.
- Traditional:Archival design licensing and made-to-order craftsmanship sustain positioning through irreplicable artisan labor pools; French polishing expertise concentrates among workers aged 55+ with inadequate knowledge transfer infrastructure.
- Contemporary:Clean-lined silhouettes with domestic hardwood provenance are capturing Texas urban corridor specification as regional manufacturers exploit white space between European imports and mass-market alternatives.
- Modern:Minimalist forms face the strongest pressure from mid-market competitors with CNC machining capabilities that replicate geometric precision at lower cost tiers.
- Rustic:Reclaimed wood and hand-forged metal accents serve regional aesthetic preferences with variable compliance documentation for salvaged material provenance.
Traditional anchors the volume base while contemporary gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian sawmill capacity and Great Lakes hardwood suppliers anchor North American sourcing, with EPA TSCA Title VI compliance requirements forcing procurement redirection toward certified domestic producers.
United States
Manhattan and Miami design studios drive custom upholstery demand with certified hardwood frame specifications. EPA TSCA Title VI regulates composite wood formaldehyde emissions nationwide, while California's CARB ATCM Phase 2 sets de facto national benchmarks. North Carolina's furniture corridor sustains artisan craftsmanship through century-old training infrastructure.
California
Boutique hotel refresh cycles in Los Angeles and San Francisco generate recurring demand for fire-retardant foam configurations. CARB maintains audit authority over out-of-state suppliers shipping into the state, effectively nationalizing compliance documentation requirements. The state's design corridors concentrate specification authority for residential and hospitality projects.
Texas
Dallas, Houston, and Austin luxury residential towers specify European-inspired case goods with domestic hardwood provenance. State-level chemical disclosure laws remain less stringent than California's, creating specification tension between imported design references and domestic material mandates. Regional manufacturers exploit white space between European imports and mass-market alternatives.
Canada
Toronto and Vancouver design markets import North Carolina upholstery frames while sourcing textiles through unified digital platforms. Health Canada oversees flammability standards that generally align with CPSC requirements, reducing cross-border product configuration complexity. Quebec's woodworking heritage supports specialty case goods production for premium residential segments.
Mexico
Monterrey and Mexico City manufacturing clusters serve cross-border hospitality projects with assembly operations for U.S.-sourced hardwood components. The country's environmental regulator enforces emerging formaldehyde standards that increasingly converge with EPA thresholds. Baja California assembly plants specialize in quick-ship programs for Texas and California design channels.
North America High-End Furniture Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America high-end furniture market. Vertically integrated manufacturers control leather finishing and timber provenance, while scale-focused producers sustain quick-ship programs through distributed plant networks. Three strategic archetypes dominate: heritage craftsmanship specialists, vertically integrated premium brands, and regional scale manufacturers. Competitive moves concentrate on designer direct channel expansion and biobased adhesive differentiation.
Within the heritage craftsmanship tier, Baker Furniture and Century Furniture exemplify archival design licensing and made-to-order production models. Bernhardt occupies a position among scale-driven manufacturers with multi-plant North Carolina operations. Restoration Hardware (RH) anchors the vertically integrated premium segment through captive supply chain control over leather finishing and timber sourcing.
| Leading Market Players |
|---|
| Restoration Hardware (RH) |
| Baker Furniture |
| Bernhardt |
| Century Furniture |
| Mitchell Gold + Bob Williams |
| Vermont Woods Studios |
| Copeland Furniture |
| Sherrill Furniture |
| Best Home Furnishings |
| Others |
Value Network & Pricing Analysis
Eight-to-fourteen week lead time volatility during peak construction seasons exposes manufacturers to margin compression while reinforcing Appalachian suppliers' pricing power. This inventory dynamic concentrates cost pressure on small-batch producers while rewarding vertically integrated players with captive hardwood sourcing.
Pricing Analysis
EPA TSCA Title VI dictates the pricing tier structure across the North America high-end furniture market. Three-tier pricing structure across premium, standard, and economy levels separates certified domestic hardwood products from imported composite alternatives and mass-market substitutes. Price differentiation centers on certification grade and artisan labor intensity. Cost compression in the mid-tier is intensifying because overseas laminator requalification expenses are being passed through. Boutique hotel chains demonstrate lowest price sensitivity due to accelerated refresh cycles, while retail galleries face highest sensitivity from disintermediation pressure.
Supply Chain Analysis
Inventory cycles stretching beyond twelve weeks during Q2-Q3 construction peaks force manufacturers to absorb carrying costs or sacrifice order fulfillment. Geographic supply concentration centers on Appalachian and Great Lakes hardwood suppliers, with Belgian textile mills and North Carolina upholstery plants completing the triangle. Raw material dependencies rest on kiln-dried hardwoods, fire-retardant foam formulations, and performance fabric weaves. Single-source vulnerability concentrates among eight-way hand-tied spring installers with 3-5 year apprenticeship requirements. Distribution runs through designer direct channels in Miami Design District and Manhattan's Flatiron district, bypassing traditional furniture galleries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America high-end furniture market sits in a cyclical recovery phase driven by boutique hotel refresh cycles compressing from 60-month to 36-48-month intervals. This recurrence pattern creates predictable demand windows for prepared suppliers.
For Market Incumbents: Fortify artisan labor pipelines through structured apprenticeship programs addressing the 55+ concentration in French polishing expertise. Secure captive supply of Appalachian hardwood through long-term offtake agreements before EPA TSCA Title VI compliance costs escalate further. Channel control through trade-only showrooms captures 18-22 point margin improvement against gallery-dependent competitors.
For New Entrants and Emerging Players: Differentiate on biobased adhesive formulations meeting TSCA Title VI thresholds without petroleum-derived cost exposure. Texas urban corridor specification for European-inspired case goods with domestic hardwood provenance offers the most penetrable white space. Go-to-market through unified digital platforms connecting North Carolina frame production to Belgian textile sourcing compresses specification cycles from twelve weeks to four.
For Investors and Strategic Acquirers: Carve-out targets emerge from heritage furniture brands with archival design licensing portfolios but underutilized made-to-order capacity. Long-term viability over the next decade hinges on compliance infrastructure amortization across sufficient volume base. Monitor CARB audit enforcement patterns as the inflection signal—accelerated out-of-state supplier scrutiny would compress margins for non-compliant competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Adhesive Certification | Soy-protein and lignin-based resins meeting EPA TSCA Title VI thresholds differentiate against petroleum competitors. |
| Designer Direct Channel Expansion | Trade-only showrooms in Miami Design District and Manhattan's Flatiron district bypass gallery intermediaries. |
| Artisan Apprenticeship Programs | Structured training infrastructure addresses eight-way hand-tied spring installer scarcity concentrated among workers aged 55+. |
| Hardwood Provenance Documentation | Chain-of-custody records from forest harvest through panel fabrication satisfy CARB audit authority over out-of-state shipments. |
| Digital Fabric-to-Frame Platforms | Real-time rendering tools compress order-to-production timelines for remote designer-client collaboration. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation. Primary interviews encompassed furniture manufacturing executives, interior design studio principals, hospitality procurement directors, North Carolina upholstery plant managers, and California-based CARB compliance officers. Secondary sources included EPA TSCA Title VI certification databases, CARB ATCM Phase 2 audit records, customs documentation of hardwood imports, SEC filings from publicly traded furniture retailers, and hospitality industry capital expenditure disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, material, end user, and style dimensions.
Across the analysis window, forecasts employed a segmented growth framework calibrated to hospitality refresh cycle recurrence, residential construction permit flows, and regulatory compliance cost pass-through rates. Segmentation dimensions modeled include product category, material certification tier, end-user procurement sophistication, and geographic design corridor concentration. CAGRs derived from historical trajectory analysis adjusted for structural shifts in sourcing patterns and channel structure. Industry-specific inputs incorporated Appalachian sawmill capacity utilization rates and Belgian textile mill lead time observations.
Material uncertainties — tariff escalation on European case good imports, artisan labor pipeline collapse, and state-level chemical disclosure law proliferation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EPA enforcement intensity and hospitality capital allocation stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Sustainable Furniture Market
Furniture
Piano Stools Market
Furniture
Australia Smart Furniture Market
Furniture
North America Home Furniture Market
Furniture
Global Furniture Market
Furniture
Laminated Door Market
Furniture
Armchair on Casters Market
Furniture
Contract Furniture and Furnishing Market
Furniture
France Furniture Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
Poland Home Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Wood Furniture Market
Furniture
Pool Tables Market
Furniture
Luxury Furniture Market
Furniture
UK Sustainable Home Furniture Market