
 Salon Chairs Market | 2026-2036
Salon Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Salon Chairs Market Analysis
China's Guangdong province is tilting toward integrated salon furniture manufacturing, combining steel tube forming, hydraulic pump assembly, and synthetic leather upholstery within single industrial zones. Takara Belmont Corporation leverages its Osaka engineering heritage to dominate premium hydraulic base technology for adjustment chairs. Maletti Group anchors European design leadership through classic and modern styling chair collections manufactured in Bologna. Collins Manufacturing Co. sustains North American distribution control via Made-in-USA barber chair lines serving independent barbershops.
A salon chair constitutes a height-adjustable seating apparatus combining a steel or aluminum frame, polyurethane or memory foam cushioning, and a hydraulic or electric lifting mechanism, engineered to position clients for hair cutting, chemical processing, or shaving services while supporting loads typically between 150 and 200 kilograms. Barber chairs command durable frame construction and full-recline capability for shaving applications, whereas adjustment chairs with electric base mechanisms capture expanding margin pools in high-service spas. Leather and vinyl materials split the premium and mass-market tiers, with ergonomic design types gaining traction in wellness centers prioritizing therapist musculoskeletal health.
REACH restrictions on chromium VI in leather tanning and the EU F-Gas Regulation governing foam-blowing agents compel European suppliers to reformulate upholstery materials and certify supply chain compliance. The US Consumer Product Safety Commission and California Proposition 65 impose phthalate disclosure requirements on vinyl-covered seating sold in American salons. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions while evaluating whether regional certification investments outweigh centralized manufacturing economies.
Market Dynamics
Integrated manufacturing clusters in China's Guangdong province are compressing lead times for hydraulic base assemblies and synthetic leather upholstery, forcing European and North American suppliers to defend margin positions through regulatory compliance differentiation rather than cost parity.
Growth Catalysts
- REACH chromium VI restrictions:European tanneries reformulate chrome-free leather finishing processes, creating certified premium material streams that command price premiums in German and French salon equipment procurement.
- Heavy-duty hydraulic chair demand from tattoo studios:Body art establishments require 200-kilogram load capacity seating with full-recline mechanisms, expanding addressable market beyond traditional barbershop and salon channels.
- Foshan metalworking integration:Guangdong's consolidated steel tube forming and pump assembly operations enable OEMs to deliver complete chair systems with compressed production cycles for export markets.
Market Restraints
- Polyurethane foam input volatility:Petrochemical feedstock price swings compress upholstery margin predictability for manufacturers dependent on petroleum-based cushioning materials.
- Guangdong supplier concentration:Overreliance on single-province Chinese manufacturing creates geopolitical and logistics risk exposure for brands without secondary sourcing footprints.
- Manual hydraulic base technical ceiling:Mechanical lifting mechanisms face performance limitations above 180-kilogram dynamic loads, restricting expansion into bariatric wellness applications.
Strategic Opportunities
- Electric base mechanism convergence:Integration of brushless motor systems with memory-position programming opens spa and medical-aesthetic channels requiring precise height recall.
- EU F-Gas Regulation low-VOC foam mandate:Early compliance with blowing-agent restrictions positions suppliers for preferred-vendor status in public-sector salon procurement tenders.
- India salon sector formalization:Organized retail expansion in Mumbai and Delhi creates demand for branded equipment lines as independent operators upgrade from unbranded local fabrication.
Industry Challenges
- Ergonomic certification complexity:ISO 9241 workstation standards and regional workplace safety codes require specialized testing protocols that extend product launch timelines by 8-14 months.
- Legacy vinyl upholstery replacement:Phthalate disclosure requirements under California Proposition 65 force reformulation of existing product lines without guaranteed cost pass-through to price-sensitive independent barbershop buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salon Chairs Market |
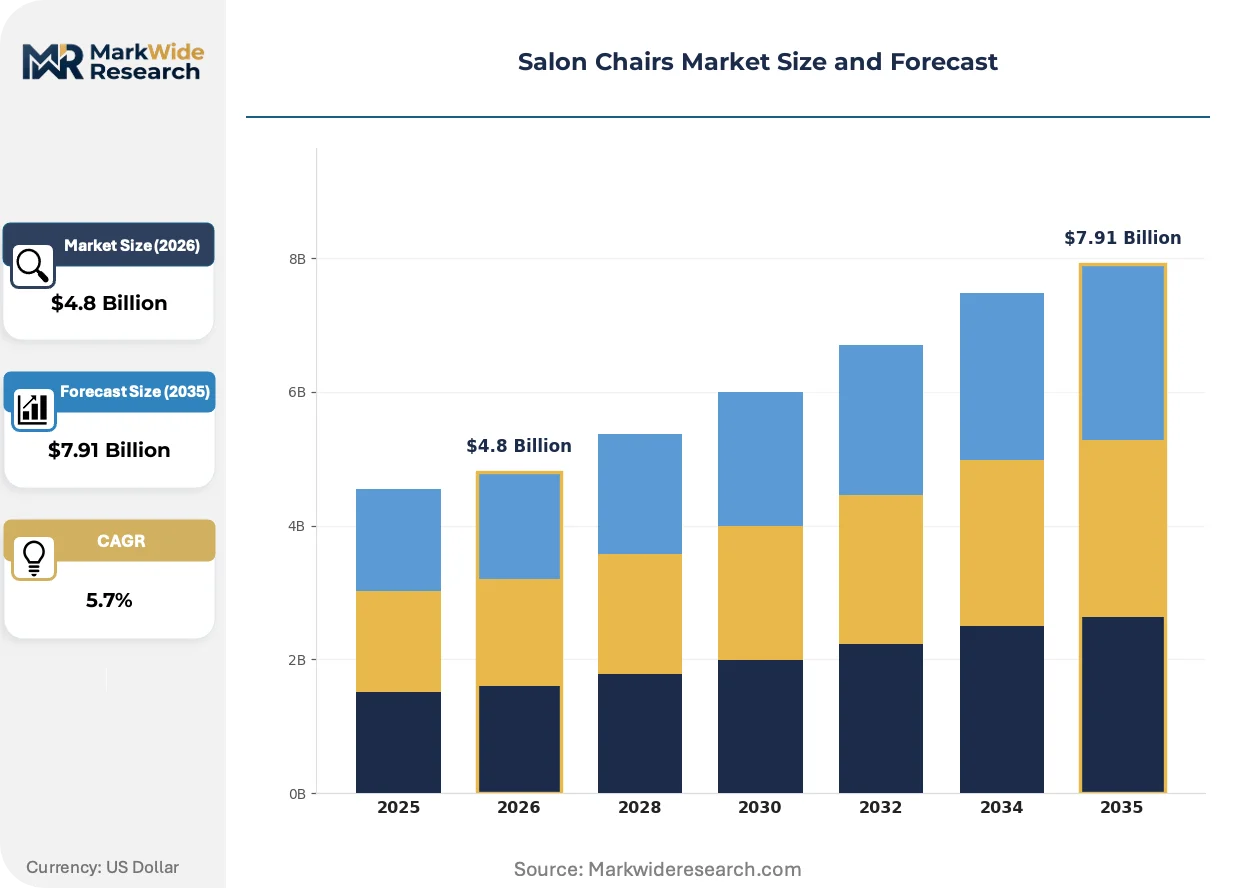
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustment Chairs, Styling Chairs, Barber Chairs, Shampoo Chairs Material: Leather, Vinyl, Fabric, Metal End User: Hair Salons, Barbershops, Spas, Wellness Centers Design Type: Modern, Classic, Vintage, Ergonomic |
| Companies Covered | Takara Belmont Corporation, Maletti Group, Collins Manufacturing Co., Foshan Yoocell Furniture Co., Ltd, Pietranera Srl, Keller International, EarthLite, LLC, HBA Salon Equipment Pty Ltd, Marc Salon & Beauty Equipments Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salon Chairs Market Emerging Trajectories
Electrification of base mechanisms and regulatory pressure on chemical inputs are bifurcating the supplier landscape between premium certified players and cost-optimized commodity manufacturers.
Memory-foam cushioning with open-cell ventilation structures is rendering obsolete traditional closed-cell polyurethane padding in high-service spa environments. Wellness centers in California and New York specify temperature-regulating upholstery to reduce therapist fatigue during extended treatment sessions. This material shift compresses margin for manufacturers without in-house foam formulation capabilities or partnerships with specialized chemical suppliers.
The EU F-Gas Regulation restricts hydrofluorocarbon use in foam-blowing agents, compelling European upholstery suppliers to adopt water-blown or hydrocarbon alternatives. Italian and German manufacturers absorb higher material costs while positioning certified low-emission chairs for green public procurement frameworks. Salon chains in France and the Netherlands now mandate F-Gas-compliant seating in their equipment specifications.
Independent barbershops increasingly source chairs through direct-to-salon e-commerce platforms rather than traditional beauty supply distributors. This channel compression disintermediates regional wholesalers who previously provided financing and assembly services. The shift is most pronounced in Texas, Florida, and Ontario, where owner-operators prioritize transparent pricing and video-guided self-assembly over local dealer relationships.
Salon Chairs Market Segmentation
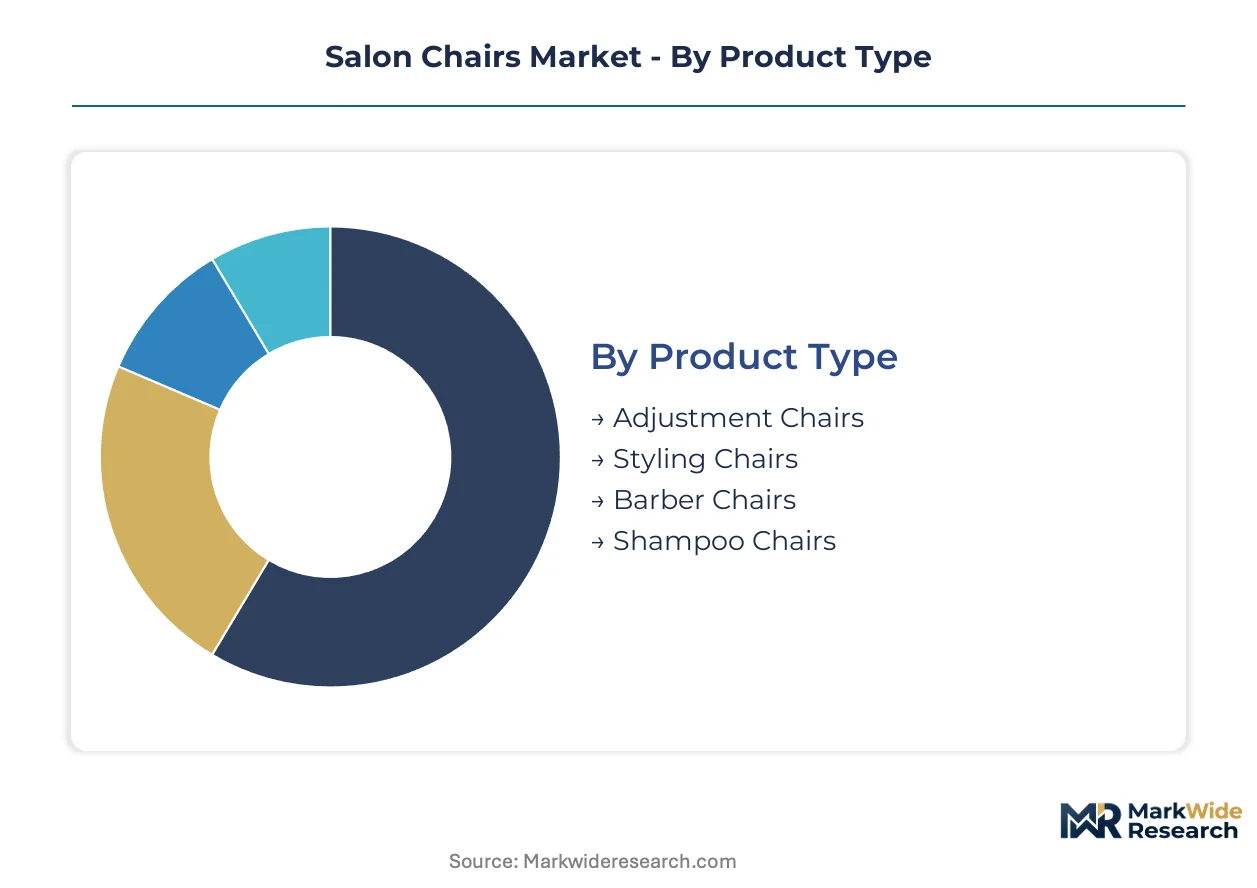
Salon chair procurement varies sharply by operational intensity and client dwell time, dictating divergent service requirements and replacement cycles across equipment categories. Understanding these segment boundaries enables suppliers to align hydraulic system specifications and upholstery durability ratings with actual use-case stress profiles.
Product Type:
After-sales service intensity escalates dramatically with mechanism complexity, as hydraulic pump rebuilds and electric motor replacements demand specialized technician networks that reshape regional distribution strategies.
- Adjustment Chairs:Electric or hydraulic base mechanisms enable precise height positioning for chemical processing and cutting services. Spas in Germany and France specify memory-position programming for treatment protocol standardization, driving premium procurement despite higher capital outlay.
- Barber Chairs:Heavy-duty steel frames support 200-kilogram loads with full-recline capability for straight-razor shaving applications. Tattoo studios across Texas and Florida now specify barber-grade recline mechanisms, expanding addressable channels beyond traditional male grooming establishments.
- Styling Chairs:Fixed-height or limited-adjustment seating prioritizes aesthetic customization and footprint efficiency. Independent salons favor these units for color processing stations where client positioning remains relatively constant.
- Shampoo Chairs:Integrated bowl configurations with neck support geometry dominate backbar installations. These units require the lowest service intervention due to minimal moving parts.
Barber chairs hold the largest share; momentum sits with adjustment chairs.
Material:
Raw material cost tiers separate certified premium supply from commodity upholstery, with regulatory compliance investments creating defensible margin positions for European tanneries.
- Leather:Chrome-free tanning processes certified under REACH restrictions command price premiums in French and Italian salon procurement. Bologna-based manufacturers leverage this material stream for design-house collections targeting luxury hospitality-spa hybrids.
- Vinyl:Low-VOC formulations compliant with EU F-Gas Regulation and California Proposition 65 phthalate disclosure requirements now dominate mass-market specifications. Guangdong OEMs reformulate PVC compounds to maintain export access despite higher chemical input costs.
- Fabric:Breathable woven upholstery gains traction in wellness centers prioritizing temperature regulation for extended massage sessions. These materials require more frequent replacement cycles than synthetic alternatives.
- Metal:Powder-coated steel and aluminum frame components constitute structural elements rather than client contact surfaces. Foshan metalworking clusters integrate tube forming with hydraulic pump assembly for complete chair system delivery.
Vinyl commands volume leadership; leather climbs the fastest on certification-driven premium positioning.
End User:
Customer procurement sophistication varies by establishment scale, with chain operators standardizing specifications across locations while independents prioritize visible differentiation.
- Hair Salons:Chemical processing stations demand stain-resistant upholstery and corrosion-resistant base mechanisms. These operators represent the most price-sensitive segment, pressuring suppliers on replacement cycle economics.
- Barbershops:Male-focused grooming establishments prioritize recline functionality and durable vinyl for shaving services. Premium barbershops in New York and London specify heritage-styled leather upholstery for brand differentiation.
- Spas:Extended treatment sessions require memory-foam cushioning and electric height adjustment for therapist ergonomics. These specifications carry the highest per-unit value in the end-user matrix.
- Wellness Centers:Integrated health and beauty facilities specify ISO 9241 workstation compliance for employee injury prevention. Procurement decisions increasingly incorporate total cost of ownership calculations spanning equipment lifespan and maintenance burden.
Hair salons anchor volume demand; spas generate steepest expansion trajectory on electrification and ergonomic specification upgrades.
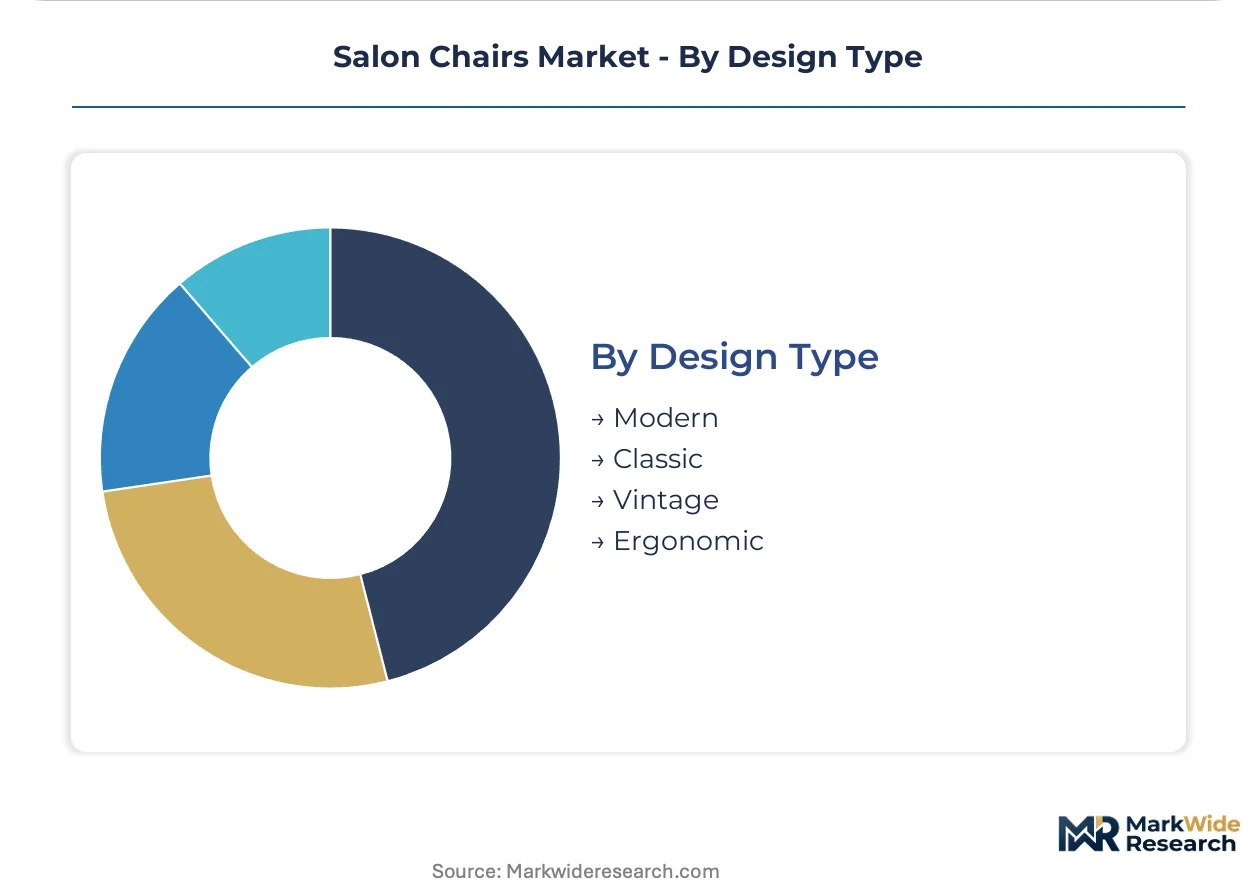
Design Type:
Aesthetic positioning strategies split between heritage authenticity and contemporary minimalism, with regional taste patterns driving specification divergence.
- Modern:Clean lines and neutral color palettes dominate urban salon fit-outs in Milan and Copenhagen. These specifications align with electric base mechanisms and synthetic upholstery for cohesive contemporary presentation.
- Classic:Tufted leather and polished metal accents target traditional barbershop environments. Bologna manufacturing heritage supports European demand for this aesthetic category.
- Vintage:Restored or reproduction antique styling commands niche premiums in heritage districts. Limited production runs and specialized upholstery techniques constrain scalability.
- Ergonomic:Biomechanically optimized contours prioritize therapist musculoskeletal health over client-facing aesthetics. Wellness centers in California mandate these specifications for workplace safety compliance.
Modern styling leads current procurement; ergonomic design gains share fastest on occupational health regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European salon equipment import flows, while China's Ningbo-Zhoushan port complex anchors Pacific export volumes for hydraulic base assemblies and synthetic leather upholstery.
United States
Premium barbershops in Brooklyn and Austin drive heavy-duty recliner procurement for straight-razor services. The US Consumer Product Safety Commission enforces phthalate disclosure requirements under California Proposition 65 for vinyl-covered seating. Dallas-Fort Worth distribution hubs consolidate final-mile delivery to independent barbershops across Texas and the Southeast.
Germany
Wellness centers in Berlin and Munich specify ISO 9241 workstation compliance for therapist injury prevention. REACH restrictions on chromium VI compel tanneries to reformulate chrome-free leather finishing processes. The Stuttgart industrial corridor hosts precision hydraulic component fabricators serving salon OEMs.
China
Guangdong's Foshan furniture cluster integrates steel tube forming, hydraulic pump assembly, and synthetic leather upholstery within single industrial zones. The Ministry of Ecology and Environment enforces dual carbon goals that reshape foam-blowing agent selection. Shenzhen port terminals handle bulk export consolidation for North American and European salon chains.
India
Organized retail expansion in Mumbai and Delhi creates demand for branded equipment lines as independent operators upgrade from unbranded local fabrication. The Bureau of Indian Standards mandates safety testing for imported hydraulic mechanisms. Tamil Nadu's Coimbatore engineering belt supplies precision metal components to domestic chair assemblers.
Italy
Luxury hospitality-spa hybrids in Milan and Rome procure design-house collections with heritage-styled leather upholstery. The EU F-Gas Regulation restricts hydrofluorocarbon use in foam-blowing agents, compelling water-blown alternatives. Bologna manufacturing heritage anchors European demand for classic aesthetic categories.
Salon Chairs Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hydraulic pumps, steel frames, and synthetic leather to finished goods assemblers. The supplier landscape fragments across three tiers: premium certified players defending margin through regulatory compliance, mid-scale regional fabricators serving domestic salon chains, and Guangdong-based OEMs competing on compressed production cycles. Dominant competitive moves include backward integration into foam formulation capabilities and strategic partnerships with specialized chemical suppliers for low-VOC vinyl compounds.
Within the heritage engineering tier, Takara Belmont Corporation and Maletti Group exemplify premium positioning through Osaka and Bologna manufacturing heritage respectively. Foshan Yoocell Furniture Co., Ltd anchors the integrated OEM archetype, occupying a position within Guangdong's consolidated metalworking and upholstery cluster that enables complete chair system delivery for export markets.
| Leading Market Players |
|---|
| Takara Belmont Corporation |
| Maletti Group |
| Collins Manufacturing Co. |
| Foshan Yoocell Furniture Co., Ltd |
| Pietranera Srl |
| Keller International |
| EarthLite, LLC |
| HBA Salon Equipment Pty Ltd |
| Marc Salon & Beauty Equipments Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Guangdong supplier concentration creates tariff exposure that widens pricing tier spreads between REACH-certified European upholstery and mass-market vinyl from Foshan OEMs. This geographic chokepoint simultaneously compresses standard-tier margins and inflates premium-tier premiums as buyers pay for regulatory compliance documentation.
Pricing Analysis
Volume-discount tiering structures separate single-unit salon procurement from chain-scale contracts spanning fifty-plus locations. Premium-mid-economy pricing differentiation rests on REACH chrome-free certification and electric base mechanism inclusion, with certified leather upholstery commanding substantial premiums over reformulated vinyl. Cost compression in standard-tier hydraulic chairs intensifies as Guangdong OEMs absorb petrochemical foam volatility without guaranteed pass-through. Independent barbershops exhibit highest price sensitivity, while luxury hospitality-spa hybrids prioritize specification compliance over unit economics.
Supply Chain Analysis
Export-control regime friction around steel alloy classifications constrains hydraulic pump sourcing from certain jurisdictions, forcing brands to diversify metalworking partnerships. Manufacturing gravity centers on China's Guangdong province, Italy's Bologna corridor, and Osaka's precision engineering belt. Raw material flows draw from petrochemical feedstocks for polyurethane foam, chrome-free tanning streams for European leather, and powder-coated steel tube from Foshan metalworking clusters. Single-province concentration in Guangdong creates geopolitical vulnerability for brands lacking secondary sourcing. Distribution runs through direct-to-salon e-commerce platforms and regional beauty supply distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as tattoo studios and wellness centers diverge from traditional salon procurement patterns, creating distinct specification niches that reward specialized positioning over broad-line coverage.
For Market Incumbents: Entrench regulatory compliance differentiation by deepening captive supply of REACH-certified leather finishing and low-VOC foam formulation capabilities. Defend against Guangdong cost compression through exclusive channel partnerships with premium barbershop chains and spa operators requiring ISO 9241 workstation documentation. For New Entrants and Emerging Players: Pursue white-space positioning in India's organized retail expansion, where Mumbai and Delhi salon chains seek branded alternatives to unbranded local fabrication. Target electric base mechanism retrofit kits for existing hydraulic chair installations as a low-capital entry vector with recurring service revenue potential. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors component specialists with in-house chemical formulation capabilities. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than pure manufacturing scale. Monitor EU F-Gas Regulation enforcement intensity as the inflection signal for premium-tier margin expansion versus commodity-tier compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Formulation | Captive supply of low-VOC polyurethane cushions secures EU F-Gas compliance for export markets. |
| Electric Base Mechanism Platform Launch | Memory-position programming opens medical-aesthetic channels requiring precise height recall protocols. |
| REACH Certification Investment | Chrome-free leather documentation commands preferred-vendor status in French and German public procurement. |
| Direct-to-Salon E-Commerce Expansion | Channel compression disintermediates regional wholesalers in Texas, Florida, and Ontario barbershop markets. |
| India Distribution Partnership | Bureau of Indian Standards navigation support accelerates branded equipment penetration in Mumbai and Delhi. |
Methodological Framework
A standing panel of salon equipment procurement managers, hydraulic component engineers, upholstery chemical formulators, and wellness center facility directors provided ongoing calibration throughout the study period. Primary interview streams combined with secondary validation from customs trade records, EU ECHA substance restriction databases, and SEC filings from publicly traded furniture manufacturers. Bottom-up unit economics triangulated against top-down category spending estimates from beauty industry associations.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning product type, material certification tier, end-user establishment scale, and regional regulatory cluster. CAGRs derived from weighted-average growth trajectories applied to base-year market sizing, incorporating electric mechanism adoption curves and REACH compliance penetration rates as industry-specific forecast inputs.
Sensitivities concentrate around petrochemical feedstock volatility, EU F-Gas Regulation enforcement timing, and Guangdong logistics disruption scenarios. Forecasts reflect documented assumptions regarding certification cost pass-through elasticity and independent barbershop channel migration velocity. Material shifts in EU chemical substance restriction scope or India import duty structure would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
US Contract Furniture and Furnishing Market
Furniture
Germany Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Poland Home Furniture Market
Furniture
Mexico Home Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
Vietnam Furniture Market
Furniture
Japan Furniture Market
Furniture
UK Sustainable Office Furniture Market
Furniture
India Luxury Furniture Market
Furniture
Armchairs with Footrest Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Europe Luxury Furniture Market