
 India Furniture Market | 2026-2036
India Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
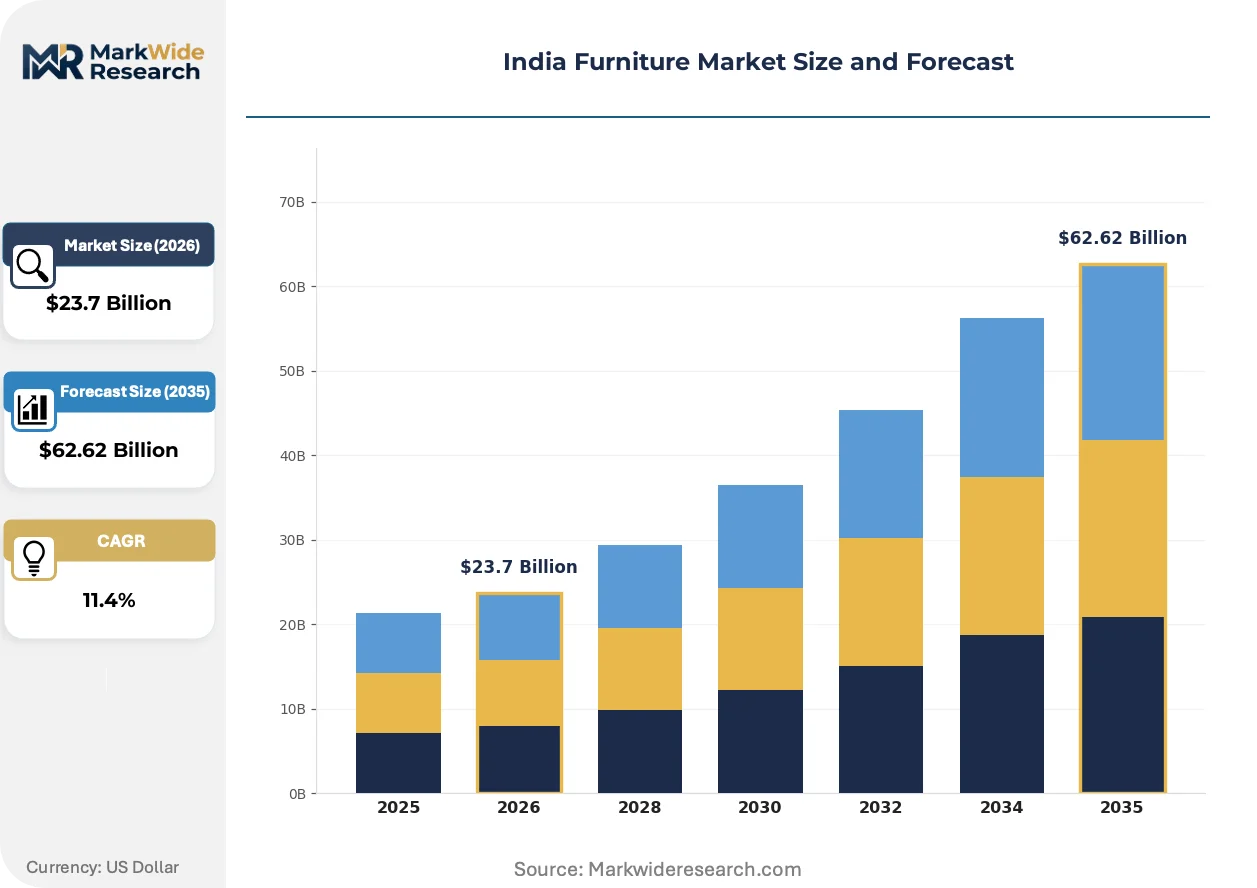
India Furniture Market Outlook
Gujarat is rewriting India's furniture production map through dedicated manufacturing zones near Ahmedabad and Surat. Godrej Interio leverages its integrated supply chain spanning timber processing to retail showrooms across tier-1 and tier-2 cities. Pepperfry anchors the online distribution channel with asset-light marketplace operations that connect regional carpentry clusters to metropolitan buyers. IKEA India competes through its Hyderabad and Mumbai store network, combining global design templates with local sourcing mandates under government retail regulations.
India furniture encompasses movable articles for seating, storage, and work surfaces, typically fabricated from solid wood, engineered panels, metal tubing, or polymer composites with surface finishes meeting BIS durability standards. The primary purpose spans residential dwelling outfitting, commercial workspace configuration, and institutional accommodation across hospitality and educational settings. Wood material segments dominate value contribution due to cultural preference and artisan heritage, though metal frames gain traction in commercial applications demanding stackability and fire compliance. Online distribution channels represent the fastest-growing access route, particularly for mattresses and modular sofas where standardized dimensions reduce return friction.
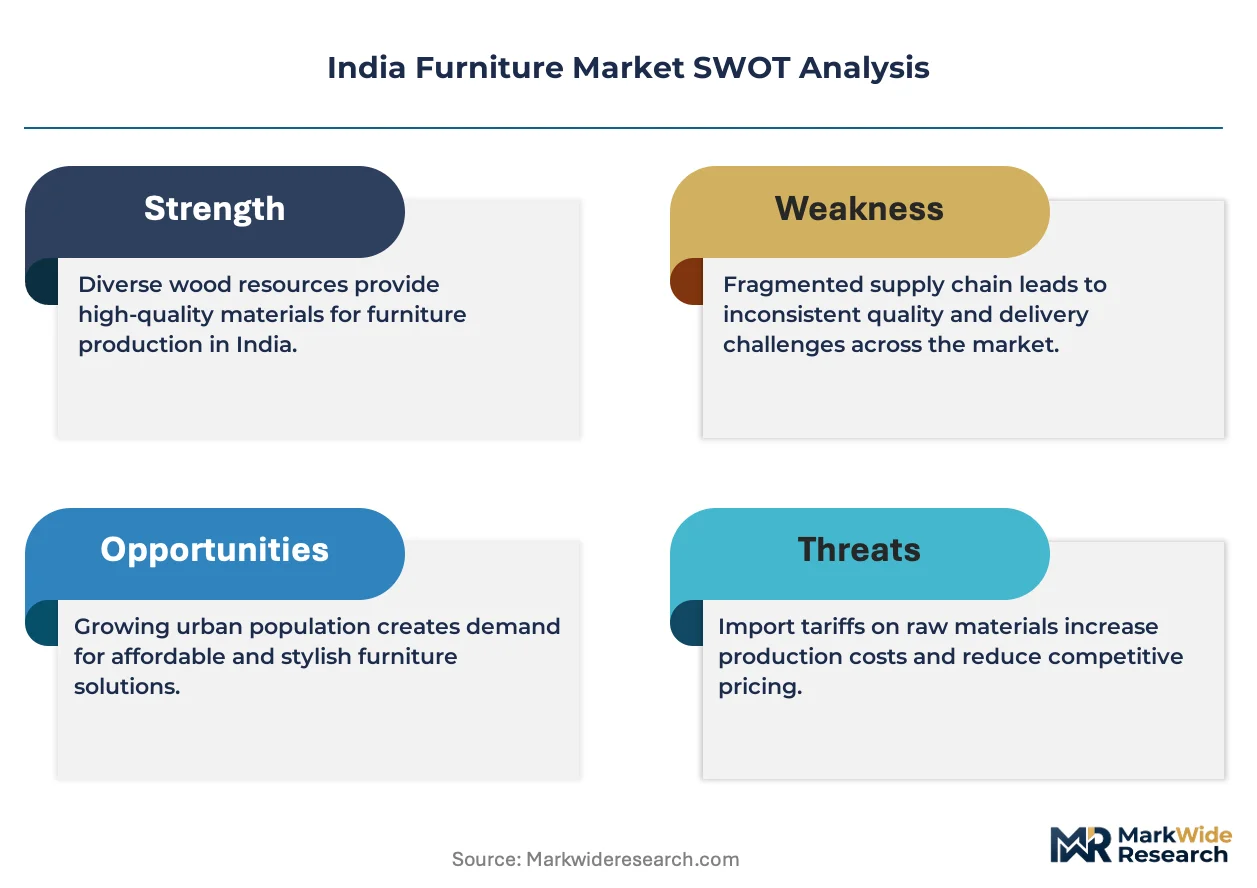
BIS standards for plywood and particleboard, the PLI scheme for furniture manufacturing, and state-level MSME incentives collectively determine product quality thresholds and capital availability for domestic producers. CEA energy-efficiency guidelines for commercial buildings indirectly shape demand for LED-integrated storage and smart furniture systems in corporate fit-outs. Stakeholders must monitor how evolving ESG disclosure requirements under SEBI mandates influence procurement criteria for institutional buyers and real estate developers.
Market Dynamics
Urban co-living operators and flexible workspace providers are consolidating procurement power, forcing domestic manufacturers to retool for bulk modular production rather than custom carpentry.
Growth Catalysts
- PLI scheme for furniture manufacturing:Production-linked incentives attract capital toward automated panel processing and metal fabrication lines, expanding domestic engineered wood capacity.
- Flexible workspace expansion:WeWork India and local competitors drive recurring orders for stackable seating and reconfigurable desking systems.
- BIS certification mandates:Mandatory standards for plywood durability and formaldehyde emissions elevate quality floors, squeezing informal suppliers out of institutional channels.
Market Restraints
- Timber input cost volatility:Domestic rubberwood and imported beech face price swings from Kerala plantation cycles and Baltic supply disruptions.
- Artisan labor concentration:Jodhpur and Saharanpur clusters depend on generational carpentry skills that resist mechanization, capping output scalability.
- Particleboard substitution ceiling:Cultural preference for solid wood in residential bridal furniture limits engineered panel penetration in tier-2 and tier-3 cities.
Strategic Opportunities
- CEA energy-efficiency guidelines:Commercial building mandates for LED integration create demand for smart storage units with embedded lighting controls.
- Assam and Northeast underpenetration:Sparse organized retail presence offers first-mover positioning for modular kitchen and wardrobe specialists.
- Online mattress standardization:Uniform sizing reduces return friction, enabling direct-to-consumer brands to bypass showroom infrastructure entirely.
Industry Challenges
- CNC programming talent scarcity:Automated cutting and edge-banding lines require operators trained in CAD-CAM workflows that vocational institutes have not scaled.
- BIS certification timeline compression:Laboratory testing queues for engineered wood products extend go-to-market schedules by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Furniture Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Tables, Chairs, Beds Material: Wood, Metal, Plastic, Upholstery End User: Residential, Commercial, Hospitality, Educational Distribution Channel: Online, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | WoodenStreet, Wakefit, Godrej Interio, IKEA India, Durian, Urban Ladder, Nilkamal, Featherlite Furniture, Pepperfry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Furniture Market Strategic Shifts
Digital tools are compressing the design-to-delivery cycle while regulatory pressure and buyer behavior shifts restructure how furniture reaches end-users.
Augmented reality configurators are virtualizing the showroom experience. Urban millennials and co-living operators now preview modular sofas and storage systems through smartphone overlays before committing. This compression of evaluation risk is reducing return rates for standardized dimensions while eroding the location premium of physical retail.
BIS standards for formaldehyde emissions in particleboard and medium-density fiberboard are tightening material sourcing requirements. Manufacturers must reformulate resin binders or switch to imported low-emission substrates, raising unit costs by eight to twelve percent. Institutional buyers in hospitality and education are now demanding E1-grade certification as a procurement prerequisite.
Asset-light marketplace platforms are disintermediating regional carpentry clusters from metropolitan demand. These platforms aggregate small workshops in Jodhpur, Mysore, and Channapatna into unified catalogs with quality guarantees and logistics orchestration. Maharashtra and Karnataka buyers increasingly prefer this channel for customized solid-wood pieces that resist standardization.
India Furniture Market Segmentation
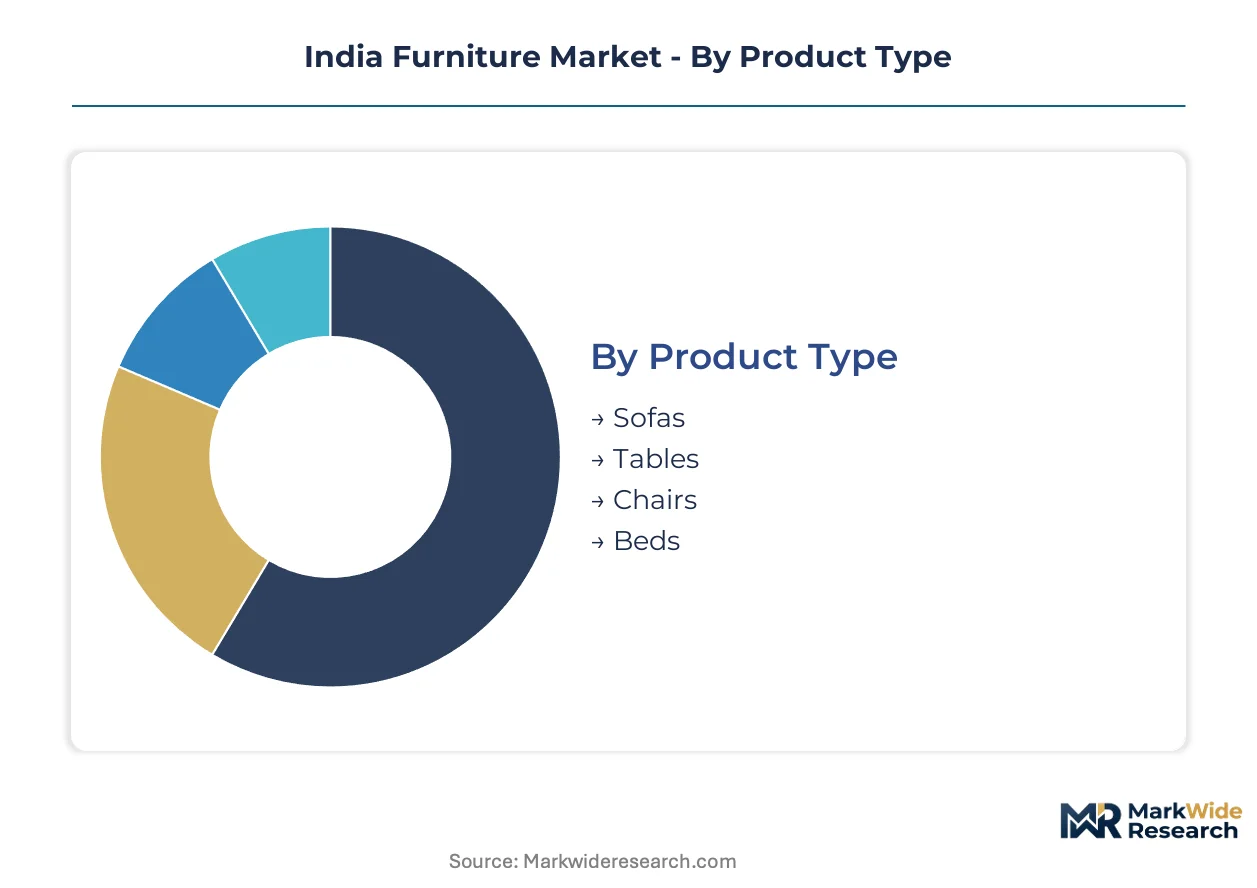
Furniture procurement cycles vary dramatically across product categories, with seating and storage systems turning over every three to five years in commercial settings while residential bedroom furniture persists for fifteen years or more. Understanding these velocity differentials helps manufacturers align inventory strategies and capital deployment against predictable replacement waves.
Product Type:
Replacement cycles compress toward seating and surface products as wear accelerates in high-traffic environments, while sleeping systems endure longer depreciation schedules.
- Sofas:Modular configurations with removable upholstery covers dominate co-living and flexible workspace procurement in Maharashtra and Karnataka. WeWork India and local competitors refresh these assets every thirty-six months, creating recurring revenue pools for domestic manufacturers with rapid fulfillment capabilities.
- Tables:Work-from-home normalization has bifurcated demand between compact laptop desks for urban apartments and collaborative benching systems for returning office populations. Gujarat manufacturers have captured bulk orders for the latter through dedicated manufacturing zones near Ahmedabad.
- Chairs:Ergonomic task seating with mesh backs and adjustable lumbar support is penetrating corporate procurement channels as CEA energy-efficiency guidelines elevate fit-out standards.
- Beds:Solid wood frames with carved headboards remain concentrated in bridal furniture purchases across tier-2 and tier-3 cities, resisting the modular standardization that has transformed other categories.
Beds dominate installed base by unit count across Indian households. Sofas are where expansion concentrates as urban household formation accelerates.
Material:
Cost tiers separate heritage craftsmanship from industrial scale, with premium solid wood commanding three to five times the unit economics of engineered alternatives.
- Wood:Rubberwood from Kerala plantations and imported beech supply Jodhpur and Saharanpur carpentry clusters, though BIS certification mandates for plywood durability are elevating quality floors and squeezing informal suppliers from institutional channels.
- Metal:Tubular steel frames with powder-coated finishes are displacing wood in commercial stackable seating and fire-compliant hospitality applications, particularly in Gujarat's automated fabrication corridors.
- Plastic:Polymer composites with reinforced polypropylene cores serve educational and mass-market residential segments where cost minimization outweighs longevity expectations.
- Upholstery:Fabric and leather coverings with foam cushioning layers represent the highest-margin material tier, with replacement demand cycling faster than frame substrates across all end-use categories.
Wood commands the largest share of residential value. Metal is climbing fastest as commercial buyers prioritize durability and compliance.
End User:
Application context determines specification intensity, with institutional buyers enforcing certification regimes that residential purchasers ignore.
- Residential:Cultural preference for solid wood in bridal furniture limits engineered panel penetration in tier-2 and tier-3 cities, though online mattress standardization is bypassing showroom infrastructure entirely.
- Commercial:Flexible workspace providers consolidate procurement power, forcing domestic manufacturers to retool for bulk modular production rather than custom carpentry.
- Hospitality:Hotel and restaurant operators now demand E1-grade formaldehyde certification as a procurement prerequisite, filtering supply toward BIS-compliant manufacturers.
- Educational:Institutional tenders for stackable desks and storage units favor metal-frame construction with polymer surfaces that withstand abrasion and moisture exposure.
Residential absorbs the greatest volume. Commercial is where specification standards are tightening most aggressively.
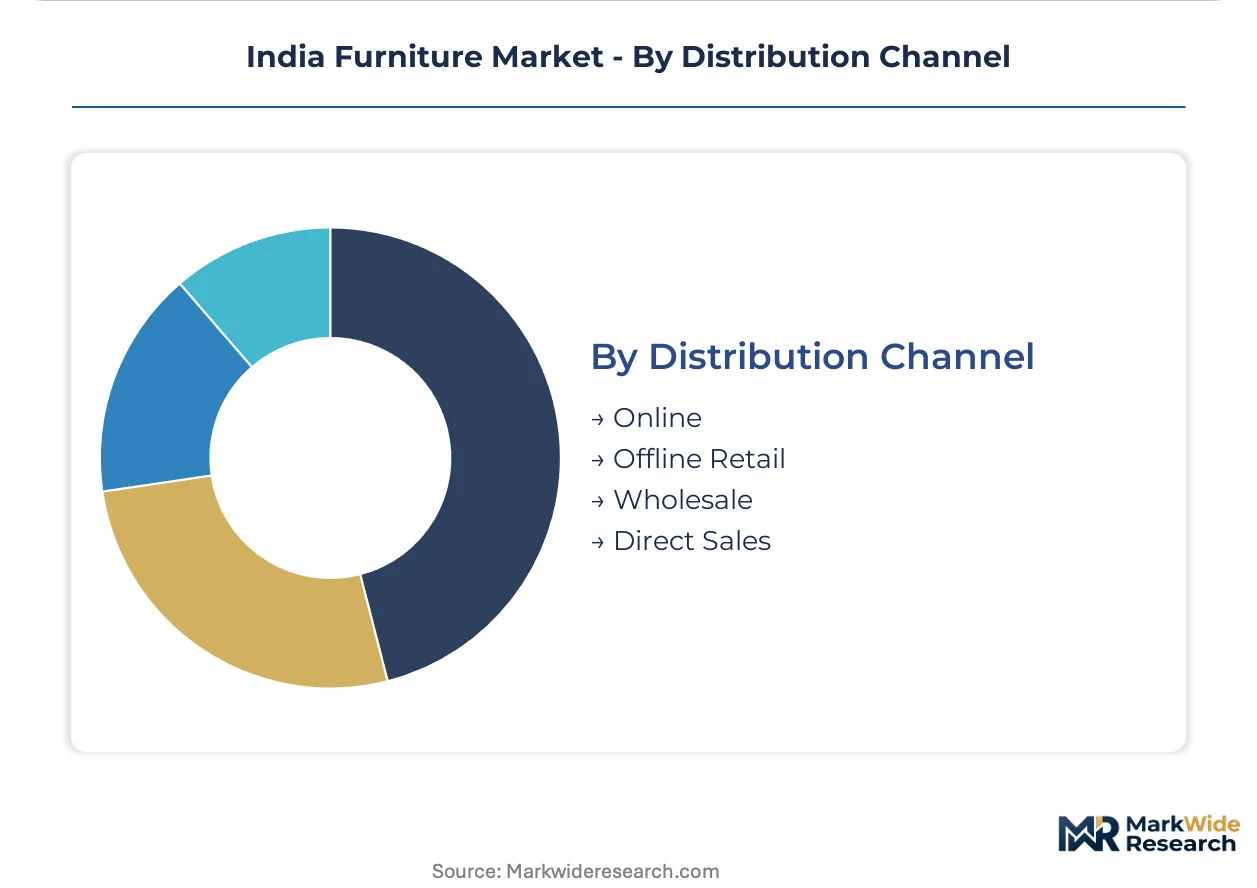
Distribution Channel:
Customer type fragments between convenience-seeking urban millennials and relationship-dependent traditional buyers in smaller cities.
- Online:Asset-light marketplace platforms aggregate regional carpentry clusters into unified catalogs with quality guarantees, with Pepperfry anchoring this channel for metropolitan buyers seeking standardized dimensions.
- Offline Retail:Godrej Interio operates integrated showrooms across tier-1 and tier-2 cities, leveraging captive timber processing to control margin capture.
- Wholesale:Bulk procurement by co-living operators and real estate developers flows through specialized distributors with project logistics capabilities.
- Direct Sales:IKEA India competes through company-owned stores in Hyderabad and Mumbai, combining global design templates with local sourcing mandates under government retail regulations.
Offline retail retains the deepest penetration in tier-2 and tier-3 cities. Online is expanding most quickly as return friction diminishes for standardized products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Indian states diverge sharply between solid-wood bridal furniture in northern and western tier-2 cities and modular engineered-wood systems in southern and western metropolitan corridors. This geographic split shapes manufacturer location decisions and distribution infrastructure investments.
Maharashtra
Mumbai and Pune drive demand for compact, modular seating as urban household formation accelerates in high-rise developments. The state's MSME incentive schemes support furniture clusters in Thane and Nashik. BIS-certified plywood manufacturers near Nagpur supply engineered panels to institutional buyers in hospitality and education sectors.
Gujarat
Ahmedabad and Surat anchor dedicated manufacturing zones where automated panel processing lines serve bulk procurement from flexible workspace providers. The PLI scheme for furniture manufacturing has attracted capital toward metal fabrication corridors. Godrej Interio leverages captive timber processing and integrated retail showrooms across tier-1 and tier-2 cities.
Karnataka
Bengaluru's co-living operators and IT park developers consolidate orders for reconfigurable desking and stackable seating systems. The state's industrial policy supports furniture parks near Mysore and Channapatna. Regional carpentry clusters feed into asset-light marketplace platforms connecting artisan producers to metropolitan buyers.
Tamil Nadu
Chennai's commercial real estate expansion drives fit-out demand for fire-compliant metal-frame furniture in corporate and hospitality settings. State-level skill development programs address CNC programming talent scarcity in automated cutting operations. Coimbatore's engineering base supports precision component supply to seating manufacturers.
Delhi-NCR
The National Capital Region concentrates premium residential demand for imported beech and teak furniture alongside mass-market engineered-wood products. DGFT regulations on timber imports shape raw material sourcing strategies for Jodhpur and Saharanpur suppliers serving this market. Online distribution channels achieve highest penetration here due to dense digital infrastructure.
India Furniture Market Competitive Environment
Capability concentration sits with integrated manufacturers commanding captive timber processing and retail networks; scale advantage sits with asset-light platforms aggregating dispersed production capacity. The market structures around three tiers: heritage carpentry clusters serving customized solid-wood demand, automated manufacturers supplying institutional bulk orders, and digital marketplaces bridging geographic fragmentation. Dominant competitive moves include backward integration into timber processing and strategic partnerships between manufacturers and co-living operators for recurring procurement contracts.
Among integrated domestic manufacturers, Godrej Interio anchors the heritage-plus-scale archetype through captive supply chains spanning timber to showroom. Pepperfry exemplifies the asset-light marketplace model, connecting regional carpentry clusters to metropolitan buyers without fixed retail infrastructure. IKEA India occupies the global-template-local-sourcing position, adapting international design systems to domestic sourcing mandates under government retail regulations.
| Leading Market Players |
|---|
| WoodenStreet |
| Wakefit |
| Godrej Interio |
| IKEA India |
| Durian |
| Urban Ladder |
| Nilkamal |
| Featherlite Furniture |
| Pepperfry |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in automated panel processing near Ahmedabad and Surat drives divergent supplier behavior: integrated manufacturers extract pricing power through captive timber conversion, while artisan clusters absorb margin compression from volatile Kerala rubberwood auctions. This utilization gap forces buyers to navigate a bifurcated market where BIS-certified engineered wood commands substantial premiums over informal solid-wood alternatives.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement from co-living operators and flexible workspace providers, locking in volume commitments that insulate manufacturers from Kerala plantation price swings. Price differentiation hinges on BIS certification tier and vertical integration depth, with captive timber processors capturing wider margins than marketplace-dependent assemblers. Pricing pressure intensifies in the solid-wood bridal furniture segment as imported beech costs fluctuate with Baltic supply disruptions. Commercial buyers exhibit lowest price sensitivity due to specification mandates, while tier-2 residential purchasers drive aggressive negotiation for unbranded engineered alternatives.
Supply Chain Analysis
Kerala rubberwood plantations, Baltic beech forests, and Gujarat automated fabrication corridors anchor upstream feedstock flows for domestic furniture production. The supply chain draws from tropical hardwoods, low-emission particleboard substrates, and powder-coated steel tubing as core inputs. Single-source vulnerability concentrates in Kerala plantation cycles, where weather disruptions and replanting lags cascade through Jodhpur and Saharanpur carpentry clusters. Distribution runs through asset-light marketplace platforms for metropolitan millennials, integrated retail showrooms for tier-2 relationship buyers, and specialized project distributors for bulk commercial fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of CNC-CAM trained operators and BIS-certified laboratory capacity constrains output expansion for domestic manufacturers seeking to serve institutional procurement channels. Bridging this capability gap determines competitive survival across the projection horizon.
For Market Incumbents: Insulate margin structures through backward integration into captive timber processing and accelerated certification investment for E1-grade formaldehyde compliance. Threat substitution from metal-frame commercial seating demands rapid retooling of Gujarat fabrication lines. Channel control through dedicated co-living procurement partnerships represents the critical defensive lever against asset-light marketplace disintermediation. For New Entrants and Emerging Players: Assam and Northeast India present the most penetrable geographic white-space, with sparse organized retail presence and rising urban household formation. Modular kitchen and wardrobe specialization offers application-level entry with lower artisan labor dependence than bridal furniture. Direct-to-consumer online positioning with standardized mattress dimensions bypasses showroom infrastructure entirely, enabling capital-efficient scaling before physical retail expansion. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with co-living operator contracts and flexible workspace provider relationships, offering visibility through replacement cycle predictability. Long-term viability across the analysis window favors automated panel processors with BIS certification pipelines over artisan-dependent carpentry clusters. Acquisition targets should demonstrate captive timber supply or established marketplace logistics integration. The signal to watch is BIS certification queue compression, which would indicate regulatory capacity expansion and accelerated go-to-market timelines for compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Processing | Captive Kerala rubberwood supply insulates Godrej Interio from plantation price volatility and margin erosion. |
| BIS E1-Grade Certification Investment | Formaldehyde compliance unlocks hospitality and education procurement channels that filter informal suppliers. |
| Co-Living Operator Partnership | WeWork India contracts provide thirty-six month replacement cycle visibility and recurring revenue anchoring. |
| Asset-Light Marketplace Expansion | Pepperfry's regional carpentry aggregation model bridges Jodhpur artisan capacity to Maharashtra metropolitan demand. |
| CNC-CAM Workforce Development | Tamil Nadu skill programs address automated cutting operator scarcity constraining Gujarat and Karnataka fabrication scale. |
Study Parameters
The analysis maps residential, commercial, hospitality, and educational furniture segments, each validated through primary interviews with plant managers at automated fabrication facilities, procurement leads at co-living operators, BIS certification laboratory directors, and retail category buyers. Secondary sources include customs and trade data on timber imports, BIS standard documentation, CEA energy-efficiency guidelines, PLI scheme filings, and SEC disclosures from listed manufacturers. Bottom-up production capacity estimates triangulate against top-down consumption surveys across Maharashtra, Gujarat, Karnataka, and Tamil Nadu.
Assumptions held fixed include BIS certification timeline compression rates, PLI scheme capital deployment schedules, and CEA commercial building mandate enforcement intensity across the analysis window. The forecast framework varies flexible workspace expansion velocity, online channel penetration rates, and artisan labor mechanization willingness. Segmentation dimensions modeled encompass product type, material grade, end-user application, and distribution channel. CAGRs derive from replacement cycle analysis and urban household formation projections, with Kerala plantation yield cycles and Baltic beech supply stability as key volatility inputs.
Practitioners should monitor BIS laboratory queue lengths, Kerala rubberwood auction prices, and co-living operator consolidation announcements for early signals of forecast revision. Cross-checking against customs timber import volumes and state-level MSME incentive disbursement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Massive Wood Slabs Market
Furniture
United States Upholstered Furniture Market
Furniture
Armchair on Casters Market
Furniture
Entryway Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
GCC Luxury Furniture Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Bar Stools Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
UAE Home Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
Plastic Furniture Market
Furniture
GCC Multifunctional Furniture Market
Furniture
North America High-End Furniture Market
Furniture
Global Folding Furniture Market