
 Saudi Arabia Kitchen Furniture Market | 2026-2036
Saudi Arabia Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Kitchen Furniture Market Analytics
Luxury villa developments across Riyadh and Jeddah are restructuring residential procurement patterns for premium kitchen systems. KAFCO Kitchens & Furniture leverages its domestic manufacturing base to anchor supply for high-end residential towers. IKEA (Alsulaiman Group) competes through flat-pack distribution networks penetrating secondary cities. Saudi Modern Factory specializes in modular cabinetry calibrated to local humidity conditions and rapid installation cycles.
Saudi Arabia kitchen furniture encompasses fixed and movable storage, work surfaces, and organizational systems engineered from moisture-resistant substrates, typically melamine-faced particleboard or solid timber, designed for food preparation and residential or hospitality service workflows. Cabinets dominate current volume flows, while islands capture expanding margin pools as open-plan layouts proliferate in new-build apartments. Wood materials sustain premium positioning among heritage-conscious consumers, though laminates extend market access across mass-market segments through cost-efficient durability.
SFDA oversees surface material safety for food-contact applications, while SASO enforces conformity assessment protocols for imported furniture components, effectively filtering substandard supply from Asian export channels. The Saudi Building Code, administered by the National Housing Company, prescribes spatial minimums that directly shape cabinet dimensioning and island feasibility in compact units. Stakeholders must monitor Riyadh's municipal infrastructure buildout and evolving hospitality licensing rules to align capacity planning with demand timing.
Market Dynamics
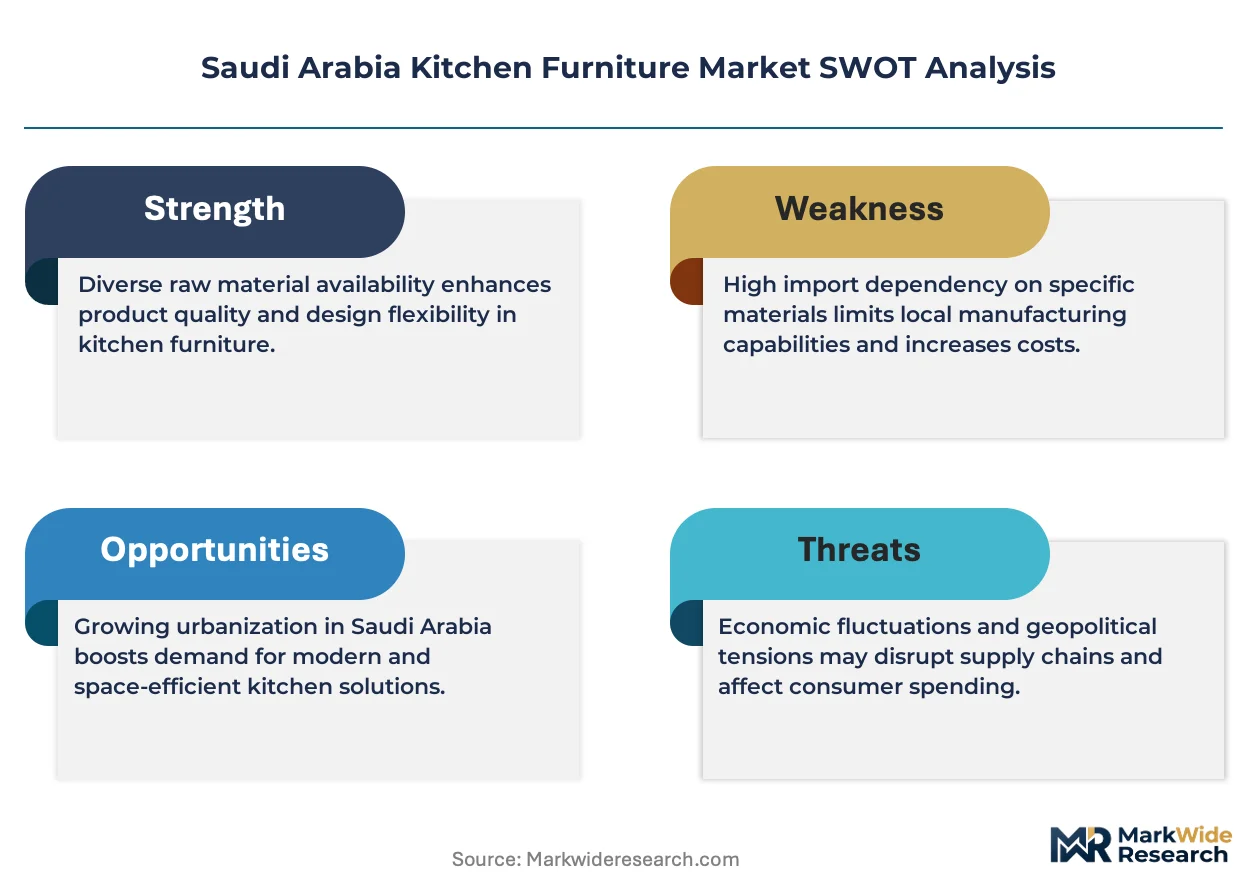
SFDA material safety standards and SASO quality certifications are tightening compliance requirements for imported laminates and engineered wood, forcing supply chain restructuring among Asian exporters and domestic distributors serving Riyadh's megaproject pipeline.
Growth Catalysts
- Luxury villa developments:Riyadh and Jeddah residential towers are accelerating procurement of premium kitchen systems with integrated islands and custom storage configurations.
- SFDA surface material protocols:Food-contact safety mandates are filtering substandard Asian imports and creating certified-supplier premiums for compliant domestic manufacturers.
- Humidity-calibrated substrates:Engineered wood treatments adapted to Gulf climate conditions are extending product lifecycles in coastal Jeddah and high-temperature Central Region installations.
Market Restraints
- Imported laminate cost volatility:Engineered wood and melamine-faced particleboard shipments from Southeast Asia face freight rate swings and currency exposure.
- SASO conformity assessment timelines:Certification delays for imported components compress installation scheduling windows for hospitality developers.
- Technical workforce scarcity:Certified installers for modular island systems and precision cabinetry alignment remain concentrated in Riyadh and Jeddah metro areas.
Strategic Opportunities
- Secondary city flat-pack penetration:Dammam and Tabuk retail corridors show underdeveloped kitchen furniture distribution relative to population growth and housing starts.
- NEOM hospitality licensing pipeline:New-build hotel and serviced apartment rules are mandating commercial-grade kitchen specifications that favor modular, rapid-install suppliers.
- Smart storage convergence:Sensor-integrated organizational systems and app-connected inventory management are creating premium pricing tiers in high-end residential segments.
Industry Challenges
- SFDA-SASO dual certification timelines:Surface material safety and furniture component conformity assessments run on parallel tracks, extending product approval cycles.
- Legacy carpenter integration:Traditional joinery workshops lack training pathways for CNC machining and modular system installation required by large developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Kitchen Furniture Market |
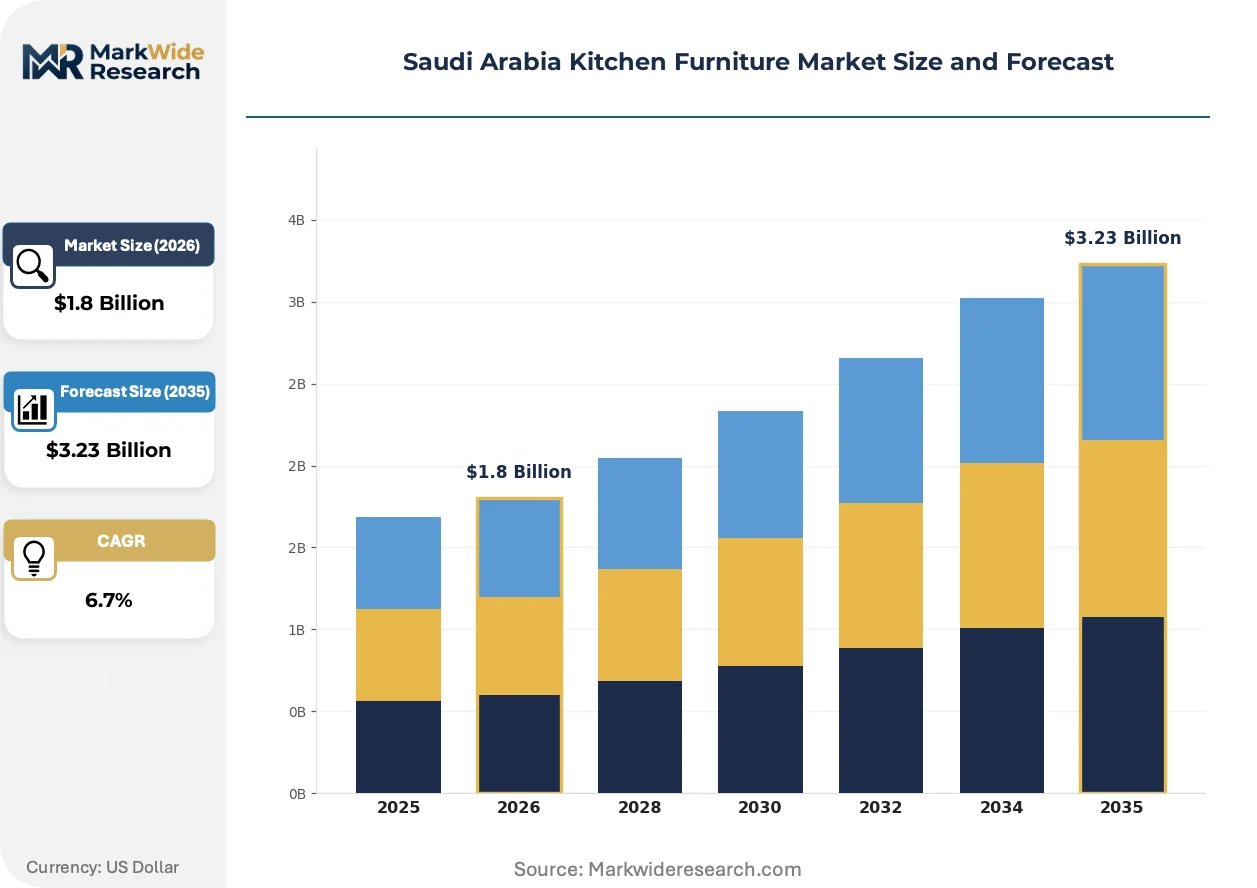
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Islands, Shelving Material: Wood, Metal, Glass, Laminates Design Style: Modern, Traditional, Rustic, Minimalist End User: Households, Restaurants, Hotels, Cafes |
| Companies Covered | KAFCO Kitchens & Furniture, Oakcraft Kitchen Cabinets, IKEA (Alsulaiman Group), Saudi Modern Factory, Al Kuhaimi Wood Industries, Saudi Kitchen Line, Al-Olayan Kitchens, AL Joaib Furniture Factory, Adada & Kabbani, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Kitchen Furniture Market Evolving Landscape
Moisture-resistant substrate engineering and smart organizational systems are converging with regulatory pressure on material safety to reshape competitive positioning in Saudi Arabia's kitchen furniture sector.
Antimicrobial surface treatments for food-contact applications are converging with melamine-faced particleboard manufacturing to create certified kitchen worktops. Hospitality developers in Riyadh's hotel pipeline are specifying these substrates for commercial kitchen durability. This convergence is compressing the supplier base toward integrated manufacturers capable of delivering both material certification and precision fabrication.
SASO's expanded conformity assessment protocols for imported furniture components are extending inspection timelines and documentation requirements. Asian laminate exporters are restructuring shipment schedules to accommodate pre-arrival testing mandates. Mass-market cabinet distributors serving secondary Saudi cities are absorbing compliance costs or switching to domestic engineered wood sources.
Developer-direct specification models are displacing traditional retail showroom selection for premium residential towers. Saudi Modern Factory and KAFCO Kitchens & Furniture are securing anchor supplier status through project-level contracts with National Housing Company developments. This channel compression is most visible in Riyadh's megaproject corridors where volume procurement overrides individual consumer choice.
Saudi Arabia Kitchen Furniture Market Segmentation
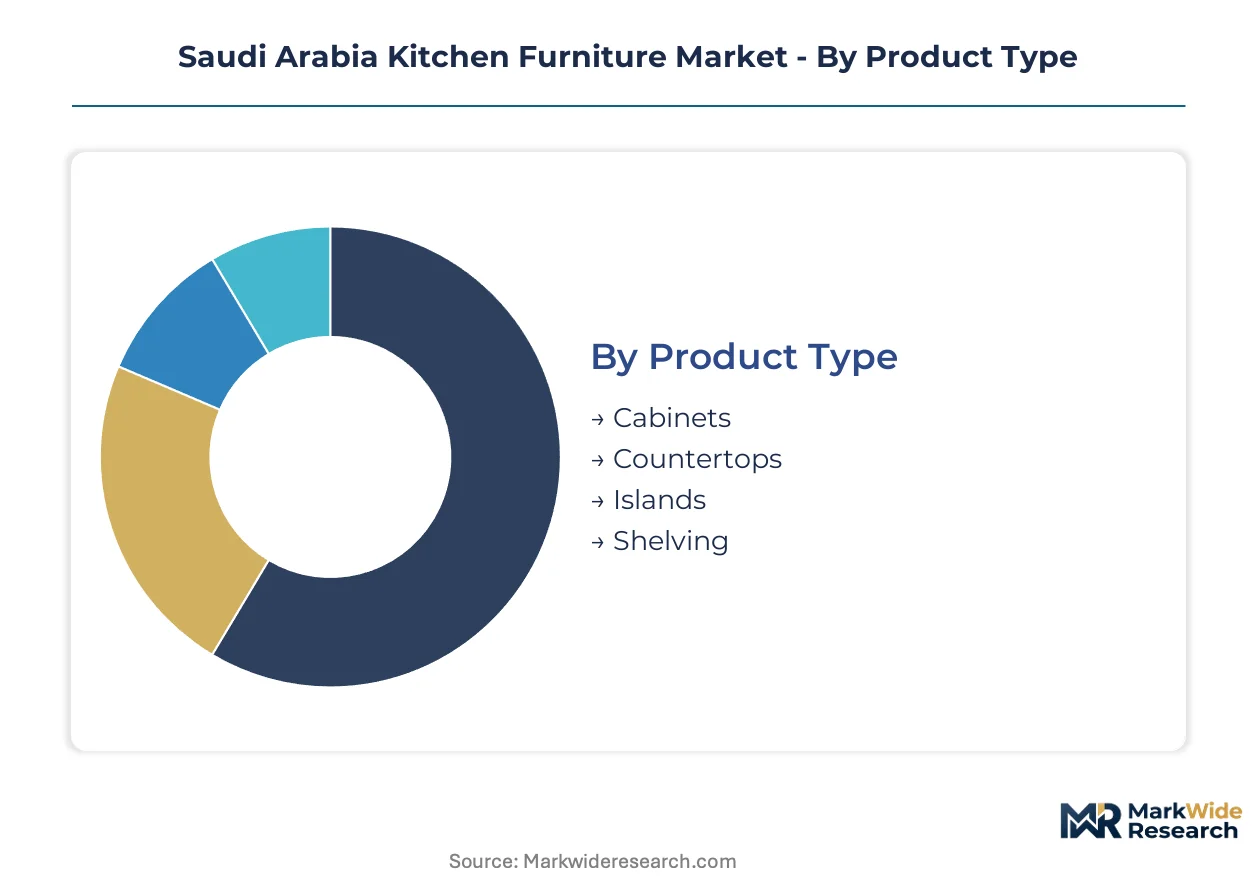
Kitchen furniture procurement patterns in Saudi Arabia diverge sharply between mass-market housing developments and luxury villa specifications. Segmentation reveals how material certification requirements and climate-adapted engineering reshape competitive positioning across price tiers and end-use applications.
Product Type:
Replacement cycles for kitchen systems accelerate as Riyadh's megaproject pipeline delivers new-build inventory with integrated specifications rather than retrofit markets.
- Cabinets:Fixed and base storage units fabricated from moisture-resistant particleboard or solid timber, engineered for Gulf humidity conditions. Demand concentrates in Central Region residential towers where National Housing Company developments specify modular, rapid-install configurations to compress construction timelines.
- Countertops:Work surfaces integrating antimicrobial treatments for food-contact compliance under SFDA protocols. Procurement is shifting toward developer-direct specification in Jeddah luxury villas, where surface material certification creates supplier premiums for integrated manufacturers.
- Islands:Freestanding units capturing margin expansion in open-plan layouts.
- Shelving:Wall-mounted and pull-out organizational systems.
Cabinets sit at the top of the volume ranking, with islands climbing the fastest as premium residential specifications proliferate.
Material:
Cost tier differentiation separates heritage-conscious premium buyers from mass-market segments prioritizing durability-to-price ratios.
- Wood:Solid timber and engineered variants sustaining premium positioning among consumers prioritizing traditional craftsmanship. Demand concentrates in Jeddah coastal developments where humidity-calibrated treatments extend product lifecycles despite salt-air exposure.
- Laminates:Melamine-faced particleboard extending market access through cost-efficient durability and SASO-compliant surface certifications. Procurement concentrates in secondary cities where freight cost volatility on Asian imports pressures distributor margins.
- Metal:Stainless steel and aluminum framing for commercial applications.
- Glass:Tempered and frosted surfaces for contemporary aesthetic specifications.
Laminates dominate unit volumes, with wood gaining share fastest in luxury residential segments.
Design Style:
Customer type segmentation separates expatriate professional households from heritage-conscious Saudi family buyers.
- Modern:Clean lines and integrated appliance housing dominating new-build apartment specifications. Demand concentrates in Riyadh's megaproject corridors where developer-direct contracts override individual consumer selection.
- Traditional:Ornate detailing and solid wood construction anchoring villa developments in Jeddah's established neighborhoods. Procurement is shifting toward certified domestic manufacturers capable of delivering both heritage aesthetics and SFDA surface compliance.
- Rustic:Distressed finishes and reclaimed material aesthetics.
- Minimalist:Reduced visual weight and hidden storage systems.
Modern specifications lead current volume flows, with traditional styles expanding most quickly in heritage-conscious luxury segments.
End User:
Application-based segmentation reveals diverging certification intensity between residential and commercial procurement channels.
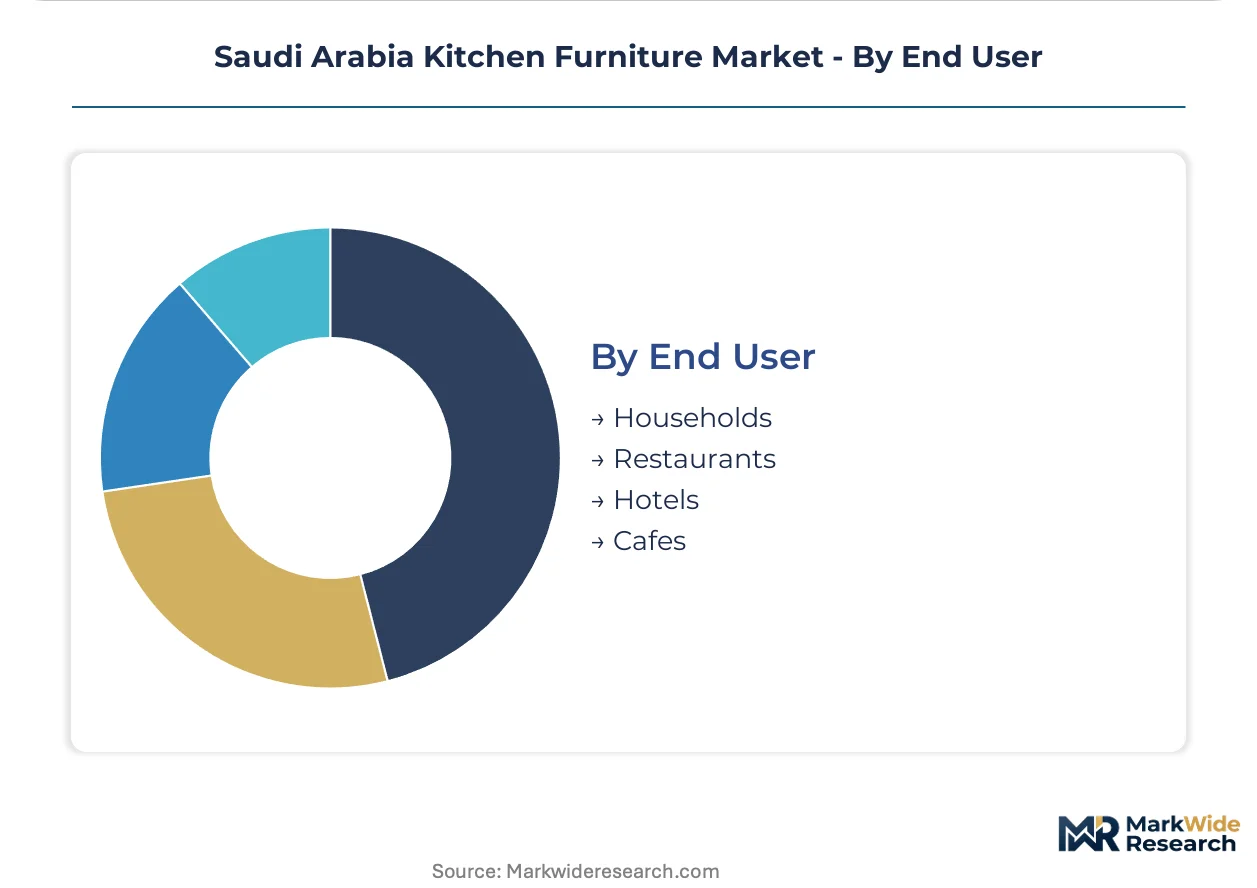
- Households:Residential kitchen systems spanning mass-market apartments to luxury villas. Demand concentrates in Central Region housing starts where rapid-install modular systems align with compressed construction schedules.
- Hotels:Commercial-grade specifications under NEOM hospitality licensing rules mandating durability and food-safety compliance. Procurement is shifting toward suppliers with integrated material certification and precision fabrication capabilities.
- Restaurants:High-cycle durability requirements for professional food service.
- Cafes:Compact footprint solutions for beverage-focused operations.
Households anchor volume rankings, with hotels on the steepest expansion trajectory as hospitality licensing rules tighten commercial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturers exploit compliance cost gaps as SFDA and SASO certification requirements filter Asian imports, redirecting procurement toward Riyadh-based fabricators with integrated testing capabilities.
Riyadh
National Housing Company megaprojects drive modular cabinet demand through compressed construction schedules. SFDA surface material protocols favor certified domestic suppliers over import-dependent distributors. Industrial zones south of the capital host KAFCO Kitchens & Furniture and Saudi Modern Factory production facilities serving developer-direct contracts.
Eastern Province
Aramco-affiliated residential compounds and Dammam housing starts sustain steady procurement of humidity-resistant laminates. SASO conformity assessment delays on Asian shipments push distributors toward Saudi Kitchen Line and Al Kuhaimi Wood Industries for faster turnaround. Dhahran's corporate housing pipeline favors rapid-install configurations over custom specifications.
Western Region
Jeddah luxury villa developments anchor premium solid wood demand despite salt-air exposure challenges. Coastal humidity regulations under the Saudi Building Code mandate treated substrates, benefiting Oakcraft Kitchen Cabinets and Al-Olayan Kitchens with climate-calibrated engineering. The city's established neighborhoods maintain heritage-conscious procurement patterns distinct from Riyadh's modern specifications.
NEOM Northwest
Hospitality licensing rules for new-build hotels mandate commercial-grade kitchen specifications with integrated food-safety compliance. NEOM's modular construction protocols favor suppliers capable of precision fabrication alongside material certification. The project's scale creates anchor-contract opportunities distinct from retail showroom channels.
Saudi Arabia Kitchen Furniture Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic manufacturers scale CNC machining lines to capture developer-direct contracts. The vendor base stratifies across three tiers: integrated manufacturers with certification capabilities, import-dependent distributors serving secondary cities, and legacy joinery workshops lacking modular system expertise. Strategic archetypes include certification-integrated fabricators, flat-pack logistics specialists, and climate-engineering specialists. M&A activity and backward integration into engineered wood production represent the dominant competitive moves.
Among certification-integrated fabricators, KAFCO Kitchens & Furniture and Saudi Modern Factory exemplify the archetype of domestic manufacturers leveraging SFDA-compliant surface treatments and SASO-aligned supply chains to secure National Housing Company anchor contracts. IKEA (Alsulaiman Group) occupies a distinct position as the flat-pack logistics specialist, penetrating secondary cities through retail network density rather than project-level relationships.
| Leading Market Players |
|---|
| KAFCO Kitchens & Furniture |
| Oakcraft Kitchen Cabinets |
| IKEA (Alsulaiman Group) |
| Saudi Modern Factory |
| Al Kuhaimi Wood Industries |
| Saudi Kitchen Line |
| Al-Olayan Kitchens |
| AL Joaib Furniture Factory |
| Adada & Kabbani |
| Others |
Value Network & Pricing Analysis
Melamine resin price indices from Southeast Asian petrochemical hubs cascade through Saudi Arabia's kitchen furniture supply chain, compressing distributor margins on imported laminates while amplifying premiums for domestic engineered wood producers with captive substrate capabilities. This input-cost volatility stratifies end-market pricing across certification-integrated manufacturers, import-dependent distributors, and legacy joinery workshops lacking scale economies.
Pricing Analysis
Developer-direct discounts for National Housing Company anchor contracts compress channel margins below retail showroom markups serving individual villa buyers. Pricing stratifies across premium, standard, and economy tiers based on SFDA certification status and humidity-calibrated substrate engineering. Cost compression in the mass-market laminate segment intensifies as Asian import freight rates fluctuate. Retail consumers in Riyadh's secondary districts exhibit highest price sensitivity, while Jeddah luxury villa buyers prioritize climate durability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle megaproject developer demand through project-level contracts with KAFCO Kitchens & Furniture and Saudi Modern Factory, while retail distributors serve fragmented household procurement. Manufacturing concentration rests on Malaysia, China, and Thailand for melamine-faced particleboard and decorative laminates. Raw material dependencies include urea-formaldehyde resins, tropical hardwood veneers, and aluminum edge-banding. Single-source vulnerability permeates the Southeast Asian laminate supply base as SASO pre-arrival testing mandates extend lead times. Distribution runs through Riyadh-based fabricators with integrated certification labs, bypassing import-dependent intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's kitchen furniture market compounds steadily as National Housing Company megaproject pipelines institutionalize developer-direct procurement at scale. This structural demand driver insulates domestic manufacturers from retail cyclicality.
For Market Incumbents: Cement anchor supplier status with National Housing Company through dedicated CNC capacity expansion in Riyadh industrial zones. Deepen backward integration into engineered wood production to offset Asian laminate cost volatility. Certification investment in SFDA-compliant surface treatments creates switching costs against emerging domestic competitors. Channel control through project-level contracting insulates margin pools from retail price erosion. For New Entrants and Emerging Players: Secondary city flat-pack distributors represent the most penetrable buyer archetype as Dammam and Tabuk retail corridors remain underserved relative to housing starts. Climate-engineered substrate specialization for Jeddah's salt-air exposure creates differentiation against Riyadh-focused incumbents. Smart storage convergence offers a go-to-market angle through sensor-integrated organizational systems targeting premium residential segments. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented legacy joinery workshops lack CNC machining capabilities and modular system expertise required by large developers. Long-term viability favors vertically integrated manufacturers with captive certification labs and engineered wood production. Acquisition target archetypes include humidity-calibration specialists and hospitality-grade fabricators with NEOM commercial references. Watch NEOM hospitality licensing rule finalization as an inflection signal for commercial-grade kitchen demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Wood | Captive substrate production insulates KAFCO and Saudi Modern Factory from Asian import cost volatility. |
| SFDA Certification Laboratory Investment | In-house surface material testing compresses approval timelines for food-contact worktop specifications. |
| Secondary City Distribution Expansion | Flat-pack logistics networks in Dammam and Tabuk capture housing start growth outside Riyadh-Jeddah corridor. |
| Smart Storage Technology Partnership | Sensor-integrated inventory systems create premium pricing tiers in high-end residential segments. |
| NEOM Commercial Kitchen Specification | Hospitality licensing compliance positions suppliers for modular rapid-install contracts at project scale. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with kitchen furniture manufacturers, procurement managers at National Housing Company developments, SFDA compliance officers, hospitality developers, and retail channel distributors with secondary validation. Secondary sources included SASO conformity assessment databases, Saudi Building Code technical specifications, National Housing Company project announcements, customs import records for laminates and engineered wood, and hospitality licensing rule drafts. Bottom-up demand modeling triangulated against top-down construction spend forecasts.
Segment-weighting applied product type, material grade, design style, and end-user application dimensions across the projection horizon. CAGRs derived from fitted growth curves calibrated to housing start pipelines, megaproject delivery schedules, and regulatory implementation timelines. Industry-specific forecast inputs incorporated humidity-corrosion coefficients for coastal installations and SFDA certification adoption rates among domestic manufacturers.
Underlying measurement precision varies by segment; developer-direct contract volumes carry tighter precision than fragmented retail household procurement. Forecasts reflect assumptions around megaproject completion schedules, regulatory enforcement intensity, and Southeast Asian supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Italy Cookware Market