
 Taiwan Home Furniture Market | 2026-2036
Taiwan Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Home Furniture Market Analytics
Smart manufacturing integration is tilting production workflows toward CNC-enabled mass customization across Taiwan's furniture belt. Nitori Taiwan Co., Ltd. leverages its Japan-parent logistics architecture to anchor inventory turnover in suburban retail nodes. Cheng Shing Wooden Industrial Company Limited specializes in solid-wood craftsmanship that commands premium positioning in domestic showrooms. Test-Rite International Co., Ltd. extends its OEM heritage into private-label distribution for international housewares chains.
Taiwan home furniture encompasses movable articles for domestic interior spaces, typically fabricated from engineered panels, solid timber, steel tubing, or woven textiles with dimensional tolerances governed by CNS national standards for stability and surface finish. The primary purpose spans ergonomic support, storage organization, and aesthetic enclosure within living environments. Sofas and beds capture the largest margin pools as upholstered categories with the highest replacement frequency and brand attachment. Metal-framed tables and chairs compete on price in the rental end-user channel where durability thresholds override design premiums. Wood material classifications retain structural importance for export certification under Taiwan's forestry traceability protocols.
Bureau of Standards, Metrology and Inspection (BSMI) mandates CNS 11227 compliance for furniture stability, while the Environmental Protection Administration enforces volatile organic compound limits on surface coatings that reshape supplier qualification criteria. The Ministry of Economic Affairs administers product safety labeling that gates market access for imported flat-pack assemblies. Stakeholders must monitor evolving carbon-footprint disclosure obligations under Taiwan's 2050 net-zero pathway as these will restructure material sourcing decisions and factory energy profiles without explicit regulatory deadlines.
Market Dynamics
Taiwan's home furniture sector is compressing under the dual squeeze of tighter formaldehyde emission standards and condominium-dweller demand for space-efficient modular systems. The Bureau of Standards, Metrology and Inspection's CNS 11227 enforcement is forcing adhesive substitution across the western manufacturing corridor.
Growth Catalysts
- Water-based adhesive substitution:BSMI's tightened formaldehyde limits for composite wood products are accelerating factory-level reformulation across Taichung and Tainan production clusters.
- Urban condominium density:Taipei and Kaohsiung high-rise dwellers prioritize modular storage systems that maximize cubic efficiency within fixed floorplates.
- CNC-enabled mass customization:Smart manufacturing integration allows batch-size-one production at cost structures previously reserved for standardized runs.
Market Restraints
- Imported timber supply concentration:Taiwan's forestry traceability protocols limit certified hardwood sourcing to a narrow band of approved Southeast Asian and North American suppliers.
- Volatile organic compound compliance costs:Environmental Protection Administration surface coating limits require solvent-to-water conversion investments that compress margin at smaller fabricators.
- Steel tubing price volatility:Metal-framed rental-channel furniture faces input cost swings that resist passing through to price-sensitive landlords.
Strategic Opportunities
- Kaohsiung suburban retail nodes:Logistics-anchored inventory positioning captures replacement-cycle demand outside saturated Taipei core markets.
- Carbon-footprint disclosure readiness:Early alignment with Taiwan's 2050 net-zero pathway creates supplier qualification advantages as mandatory reporting crystallizes.
- Flat-pack assembly channel expansion:Ministry of Economic Affairs product safety labeling compliance opens private-label distribution to international housewares chains seeking Taiwan-origin goods.
Industry Challenges
- Solid-wood craftsmanship skill scarcity:Master joiner pipelines have narrowed as vocational training gravitates toward CNC operation over hand-finished construction.
- Legacy ERP-to-IoT integration friction:Factory-floor sensor deployment for predictive maintenance conflicts with decades-old production scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Home Furniture Market |
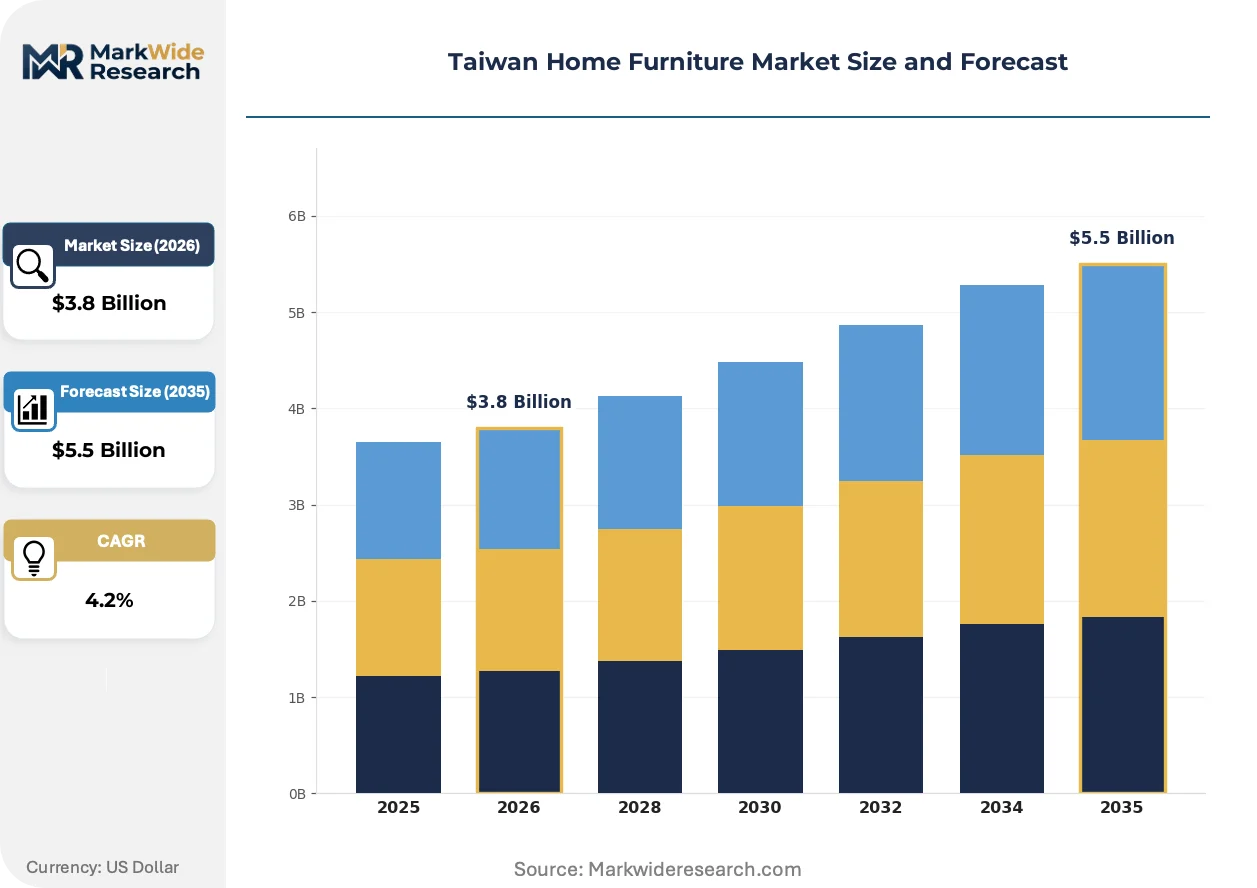
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Fabric, Plastic Style: Modern, Traditional, Rustic, Minimalist End User: Residential, Commercial, Rental, Hospitality |
| Companies Covered | Nitori Taiwan Co., Ltd., Chyuan Chern Furniture Company Limited, IKEA Taiwan, Original-I, Cheng Shing Wooden Industrial Company Limited, Scan-D Corporation, Aurora Corporation Furniture, Royce, Test-Rite International Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Home Furniture Market Evolving Landscape
Digital twin technology is virtualizing how Taiwanese manufacturers prototype, stress-test, and market-configure furniture lines before physical production commitment. This shift compresses development cycles and reduces material waste across the western corridor.
Parametric design software is virtualizing the traditional showroom-to-factory workflow. Younger condominium buyers in Taipei configure modular systems via web-based configurators that feed directly into CNC cutting paths. This collapsing of design-to-production latency is squeezing inventory-carrying requirements for mid-market retailers.
BSMI's incremental tightening of CNS 11227 stability and emission standards is redefining supplier qualification criteria. Composite panel fabricators must now document chain-of-custody from adhesive formulation through finished goods testing. Upholstered furniture segments face the steepest compliance timeline compression as foam and fabric treatments fall under expanded volatile organic compound scrutiny.
Rental-channel procurement is consolidating around durability-specified bulk contracts. Landlords in Taichung and Tainan university districts now source metal-framed tables and chairs through direct factory relationships that bypass traditional distributor markups. This disintermediation is visible most acutely in the student housing vertical where replacement frequency and damage tolerance override aesthetic premiums.
Taiwan Home Furniture Market Segmentation
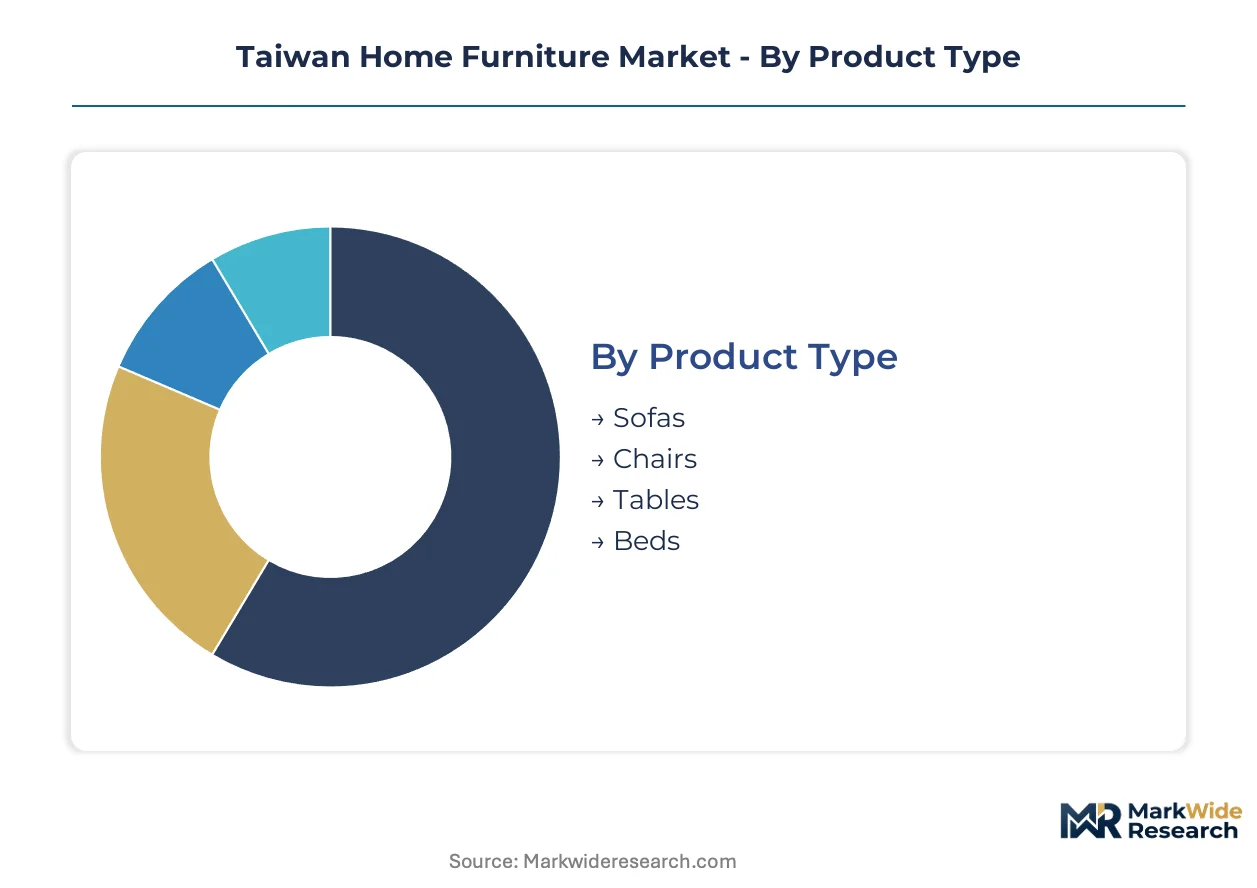
Taiwan's home furniture market fragments across four distinct axes that determine procurement patterns, margin structures, and regulatory exposure. Cycle times vary dramatically by segment, with upholstered categories turning inventory fastest and solid-wood heirloom pieces anchoring the slowest replacement cadences.
Product Type:
Replacement frequency diverges sharply across this category, with upholstered seating demanding refresh cycles measured in single-digit years against case goods that persist across decades.
- Sofas:Multi-density foam construction with CNS 11227 stability compliance dominates production specifications. Taipei condominium dwellers drive demand for compact two-seat configurations with washable slipcovers that accommodate frequent relocation. BSMI formaldehyde limits have compressed supplier qualification timelines for frame adhesives.
- Beds:Platform and storage-integrated designs command premium positioning through Taichung-to-Tainan retail corridors. Metal-framed rental-channel variants compete on durability thresholds rather than aesthetic differentiation, with landlords in university districts prioritizing damage tolerance over design premiums.
- Chairs:Dining and accent categories span molded plastic stackables to solid-wood master-crafted pieces with narrow vocational training pipelines.
- Tables:CNC-enabled mass customization allows batch-size-one production for dining and workspace configurations, collapsing design-to-delivery latency.
Beds anchor the volume base while sofas gain share at the steepest rate as urban density elevates replacement frequency and brand attachment.
Material:
Cost tier stratification separates premium solid-wood heirloom positioning from commodity metal and plastic rental-channel procurement.
- Wood:Engineered panels face BSMI emission compliance costs that squeeze margin at smaller fabricators, while solid-wood craftsmanship commands showroom premiums through documented chain-of-custody certification. Forestry traceability protocols limit certified hardwood sourcing to approved Southeast Asian and North American suppliers.
- Metal:Steel tubing input cost volatility resists passing through to price-sensitive landlords in Taichung and Tainan student housing verticals. Factory-direct procurement relationships bypass traditional distributor markups.
- Fabric:Upholstery textiles fall under expanded volatile organic compound scrutiny from the Environmental Protection Administration.
- Plastic:Injection-molded stackables serve institutional and outdoor applications with minimal finishing requirements.
Wood materials concentrate the highest margin pools while metal-framed alternatives expand most quickly in rental-channel procurement consolidation.
Style:
Customer type alignment determines channel placement, with younger condominium buyers gravitating toward parametric-configurable modern lines against established homeowners sustaining traditional craftsmanship demand.
- Modern:Clean-line geometries integrate with modular storage systems favored by Taipei and Kaohsiung high-rise dwellers maximizing cubic efficiency. Web-based configurators feed directly into CNC cutting paths, collapsing inventory-carrying requirements.
- Minimalist:Reduced-component designs align with space-constrained floorplates and lower formaldehyde exposure preferences.
- Traditional:Ornamented solid-wood construction depends on narrowing master joiner pipelines as vocational training shifts toward CNC operation.
- Rustic:Distressed finishes and reclaimed material claims appeal to sustainability-positioned segments under emerging carbon-footprint disclosure obligations.
Modern styling anchors the volume base while minimalist variants gain share at the steepest rate as urban density and health-conscious material selection converge.
End User:
Application context dictates durability specifications, aesthetic premiums, and procurement channel structure across divergent use intensities.
- Residential:Owner-occupied segments sustain premium upholstery and solid-wood replacement cycles with highest brand attachment and showroom involvement. Kaohsiung suburban retail nodes capture replacement-cycle demand outside saturated Taipei core markets.
- Rental:Landlord procurement prioritizes damage tolerance and factory-direct pricing over design differentiation, with metal-framed tables and chairs dominating university district sourcing.
- Commercial:Office and co-working configurations demand ergonomic certification and bulk contract durability specifications.
- Hospitality:Hotel and serviced apartment fit-outs balance aesthetic differentiation with commercial-grade wear resistance and rapid refresh capability.
Residential demand anchors the volume base while rental procurement gains share at the steepest rate as institutional investor presence expands across Taiwan's western corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban condominium dwellers in Taipei and Kaohsiung concentrate demand for space-efficient modular systems, while manufacturing clusters across the western corridor from Taichung to Tainan anchor production capacity. BSMI formaldehyde regulations and net-zero disclosure obligations reshape supplier qualification across all sub-regions.
Taipei Metropolitan Area
High-rise density drives replacement-frequency demand for compact sofas and platform beds with washable slipcovers. BSMI CNS 11227 stability enforcement compresses adhesive supplier timelines for frame manufacturers. Retail nodes in Xinyi and Neihu districts capture premium showroom traffic for solid-wood craftsmanship.
Kaohsiung
Suburban logistics-anchored inventory positioning captures replacement-cycle demand outside saturated northern markets. Environmental Protection Administration volatile organic compound limits on surface coatings reshape finishing facility compliance investments. The Cianjhen and Nanzih industrial zones concentrate CNC-enabled mass customization workshops.
Taichung
Mid-market procurement consolidation favors metal-framed rental-channel furniture for university district landlords. Forestry traceability protocols limit certified hardwood sourcing to approved Southeast Asian suppliers for solid-wood fabricators. The Taiping and Dali districts host engineered panel production clusters facing margin compression from water-based adhesive conversion costs.
Tainan
Factory-direct procurement relationships bypass traditional distributor markups for institutional rental-channel buyers. Ministry of Economic Affairs product safety labeling gates market access for flat-pack assembly exports. The Yongkang and Rende manufacturing belts specialize in batch-size-one CNC production for parametric-configurable modern lines.
Taiwan Home Furniture Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where logistics scale and craftsmanship heritage define positioning boundaries. The vendor base fragments across three strategic archetypes: Japan-parent retail networks with suburban inventory nodes, solid-wood craftsmanship specialists with documented chain-of-custody certification, and OEM heritage operators extending into private-label distribution. Dominant competitive moves include logistics architecture anchoring in high-turnover suburban nodes and CNC-enabled mass customization capability deployment.
Among Taiwan-based fabricators, Cheng Shing Wooden Industrial Company Limited and Test-Rite International Co., Ltd. exemplify divergent archetypes within the competitive set. Cheng Shing occupies a position representing solid-wood craftsmanship heritage with premium showroom positioning. Test-Rite anchors the OEM-to-private-label transition vector for international housewares chain supply. Nitori Taiwan Co., Ltd. represents the Japan-parent logistics architecture archetype with suburban retail node penetration.
| Leading Market Players |
|---|
| Nitori Taiwan Co., Ltd. |
| Chyuan Chern Furniture Company Limited |
| IKEA Taiwan |
| Original-I |
| Cheng Shing Wooden Industrial Company Limited |
| Scan-D Corporation |
| Aurora Corporation Furniture |
| Royce |
| Test-Rite International Co., Ltd. |
| Others |
Value Network & Pricing Analysis
The Kaohsiung-Taichung freight corridor anchors cost dynamics across Taiwan's western manufacturing belt, concentrating supply-side leverage among engineered panel fabricators while downstream pricing stratifies across premium solid-wood craftsmanship and economy metal-framed rental-channel procurement.
Pricing Analysis
Cost-plus contracts with steel tubing indexation dominate procurement between rental-channel landlords and metal-framed furniture fabricators. Three-tier pricing structure across premium, standard, and economy levels separates solid-wood heirloom positioning from commodity metal and plastic alternatives. Price differentiation hinges on CNS 11227 certification grade and volume scale, with Taipei condominium buyers least sensitive and Taichung university-district landlords most sensitive. Cost compression in the metal-framed tier is intensifying because steel input volatility resists pass-through to price-sensitive institutional buyers.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier-financing arrangements between Taichung engineered panel fabricators and downstream assemblers. Raw material sourcing draws from Malaysia, Vietnam, and the United States for certified hardwood under Taiwan's forestry traceability protocols. Adhesive formulations, steel tubing, and upholstery textiles constitute critical input dependencies. Single-source vulnerability concentrates in Southeast Asian hardwood suppliers approved under chain-of-custody certification. Distribution runs through suburban retail nodes in Kaohsiung and showroom corridors from Taichung to Tainan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's home furniture market represents an early-cycle expansion story, with CNC-enabled mass customization penetrating the condominium-dweller segment faster than legacy craft production can adapt.
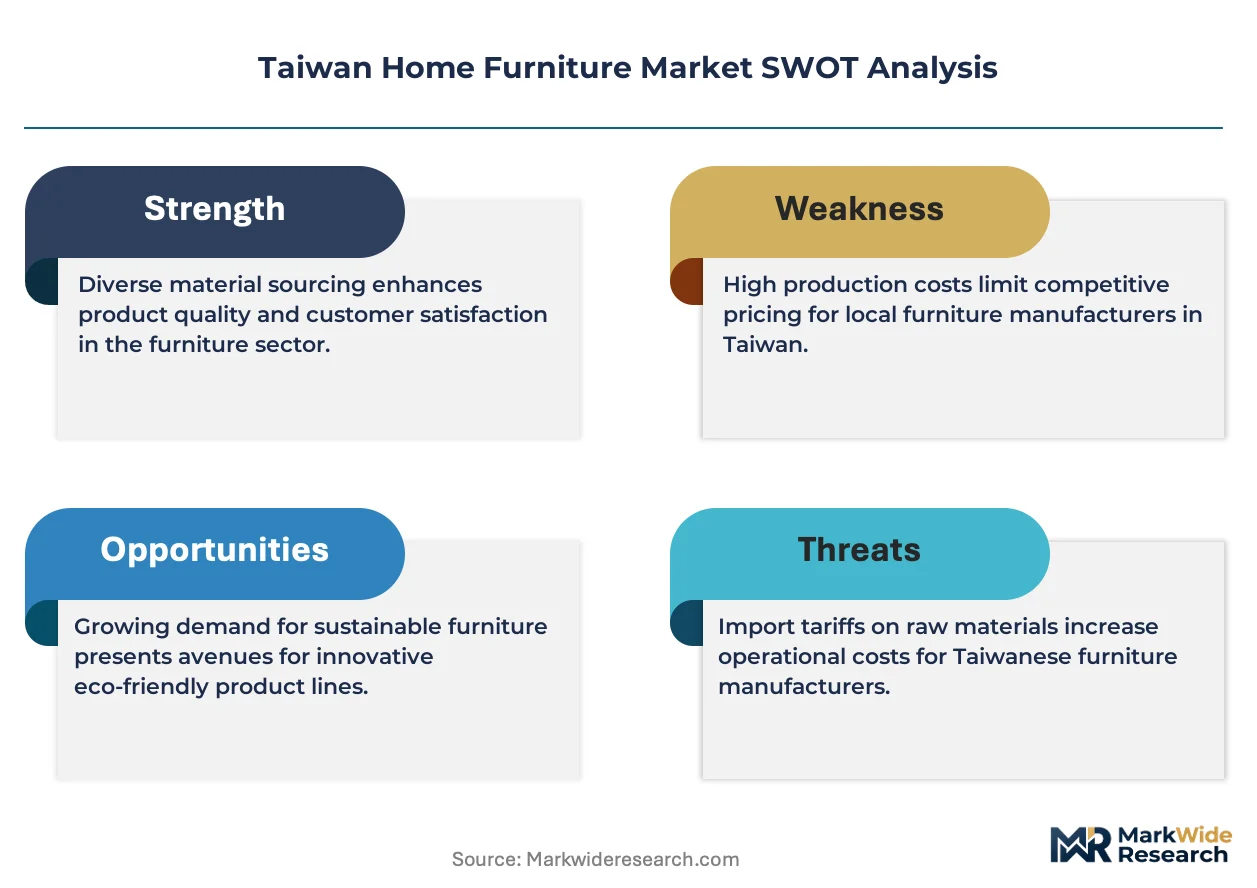
For Market Incumbents: Insulate premium positioning by deepening backward integration into certified hardwood sourcing and accelerating water-based adhesive conversion ahead of BSMI's incremental CNS 11227 tightening. Secure master joiner pipelines through vocational training partnerships before CNC-focused curricula fully displace hand-finished construction expertise.
For New Entrants and Emerging Players: Kaohsiung suburban retail nodes outside saturated Taipei core markets represent the most penetrable entry point for logistics-anchored inventory positioning. Factory-direct procurement relationships with Taichung and Tainan university-district landlords bypass traditional distributor markups. Web-based parametric configurators feeding directly into CNC cutting paths collapse design-to-delivery latency for modular storage systems.
For Investors and Strategic Acquirers: Carve-out targets emerge from Japan-parent retail networks seeking to monetize non-core suburban real estate holdings in Taiwan. Long-term viability over a multi-year horizon rests on carbon-footprint disclosure readiness as Taiwan's 2050 net-zero pathway crystallizes mandatory reporting. The signal to watch is Ministry of Economic Affairs product safety labeling enforcement tightening for flat-pack assembly exports.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Conversion | BSMI formaldehyde limits force factory-level reformulation across Taichung and Tainan production clusters. |
| CNC-Enabled Mass Customization | Batch-size-one production at standardized-run cost structures collapses inventory-carrying requirements for mid-market retailers. |
| Suburban Retail Node Expansion | Kaohsiung logistics-anchored positioning captures replacement-cycle demand outside saturated Taipei core markets. |
| Carbon-Footprint Disclosure Readiness | Early alignment with Taiwan's 2050 net-zero pathway creates supplier qualification advantages as mandatory reporting crystallizes. |
| Flat-Pack Assembly Channel Expansion | Ministry of Economic Affairs product safety labeling compliance opens private-label distribution to international housewares chains. |
Research Methodology
Operator-level perspectives from furniture factory managers, retail category buyers, adhesive formulation specialists, and CNC equipment operators anchored the qualitative base. Primary interviews combined with secondary validation from customs records, Bureau of Standards Metrology and Inspection regulatory filings, Environmental Protection Administration emission databases, and forestry traceability protocol documentation. Bottom-up production cluster assessments and top-down retail channel sizing triangulated volume estimates across the analysis window.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories by product type, material classification, styling preference, and end-user application. Segmentation dimensions incorporated residential versus rental versus commercial procurement patterns, with CAGRs derived from replacement-cycle frequency differentials and urban density penetration curves. Forecast inputs included condominium completion rates along Taiwan's western corridor and vocational training pipeline outputs for master joiner versus CNC operator specializations.
Macroeconomic conditions sit as an overlay; deviation in construction lending rates, steel commodity indices, or cross-strait logistics costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Multifunctional Furniture Market
Furniture
Italy Home Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Portering Chair Market
Furniture
Poland Home Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Vietnam Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Sanded Plywood Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
UAE Home Furniture Market
Furniture
Metal Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
Ergonomic Chair for Children Market
Furniture
Indonesia Home Furniture Market