
 Prep Tables Market | 2026-2036
Prep Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Prep Tables Market Analytics
The U.S. Department of Energy's commercial refrigeration efficiency standards is decoupling legacy equipment from new build specifications across the North American foodservice sector. Ali Group leverages its broad brand portfolio to sustain refrigeration-to-fabrication integration across multiple price tiers. True Manufacturing anchors its position through domestic manufacturing scale and extensive distributor relationships. Hoshizaki Corporation differentiates through specialized ice-making and refrigeration technology leadership in compact footprint designs.
Prep tables are flat-surface workstations, typically constructed from 16- to 18-gauge stainless steel with integrated under-counter refrigeration maintaining temperatures between 33°F and 41°F, designed to combine ingredient storage with immediate food assembly access in commercial kitchens. Stainless steel dominates product type demand due to durability standards and NSF International sanitation certification requirements, while plastic surfaces gain traction in educational and laboratory end-user segments where chemical resistance and lower capital outlay matter. The food preparation application commands the largest share, though display-oriented configurations for open-kitchen restaurants represent the fastest-growing sub-segment as front-of-house visibility becomes a design priority.
NSF International standards, the U.S. Department of Energy compliance framework, and state-level California Title 24 building efficiency codes collectively shape equipment specifications, energy consumption thresholds, and market access conditions for prep table manufacturers. The FDA Food Code provisions governing temperature control and surface sanitation further constrain product design choices, particularly for units serving high-risk food categories. Stakeholders must monitor evolving state-level efficiency mandates and material disclosure requirements as regulatory fragmentation between jurisdictions intensifies compliance complexity.
Market Dynamics
The U.S. Department of Energy's commercial refrigeration efficiency standards is forcing a wholesale equipment replacement cycle across quick-service and fast-casual foodservice operations, compressing the functional lifespan of legacy prep tables and redirecting capital toward compliant systems.
Growth Catalysts
- California Title 24 Building Efficiency Codes:These state-level mandates accelerate adoption of high-efficiency refrigeration systems in commercial kitchen construction and renovation projects across the western United States.
- Ghost Kitchen Proliferation:Delivery-only food preparation facilities in Texas, Florida, and California are driving concentrated demand for compact, high-throughput refrigerated workstations.
- NSF International Sanitation Certification:Food safety protocols in institutional foodservice and healthcare sectors mandate certified stainless steel surfaces, creating non-negotiable specification requirements.
Market Restraints
- Stainless Steel Input Volatility:16- to 18-gauge 304-grade stainless steel pricing fluctuations compress manufacturer margins and complicate long-term contract pricing.
- Domestic Manufacturing Concentration:Heavy reliance on U.S.-based fabrication capacity limits supply flexibility and exposes buyers to regional labor market tightness.
- Refrigerant Phase-Down Constraints:EPA SNAP program restrictions on hydrofluorocarbon refrigerants complicate service infrastructure and extend replacement timelines.
Strategic Opportunities
- Educational Institution Modernization:K-12 and university foodservice programs present underpenetrated demand for chemical-resistant plastic-surface prep tables with lower capital requirements.
- Open-Kitchen Display Configurations:Front-of-house visibility requirements in fast-casual dining are creating specification demand for aesthetic refrigeration-to-fabrication integration.
- Infrastructure Investment and Jobs Act Energy Provisions:Federal commercial building efficiency incentives are expanding accessible financing for equipment replacement in independent restaurant operations.
Industry Challenges
- Refrigeration Technician Shortage:Specialized HVAC-R service capacity constraints extend equipment downtime and elevate total cost of ownership for complex under-counter systems.
- Multi-Jurisdiction Compliance Fragmentation:Divergent state-level efficiency mandates and material disclosure requirements multiply certification burdens for national distribution strategies.
- Legacy System Integration Complexity:New DOE-compliant refrigeration units often require electrical and spatial modifications incompatible with existing kitchen footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prep Tables Market |
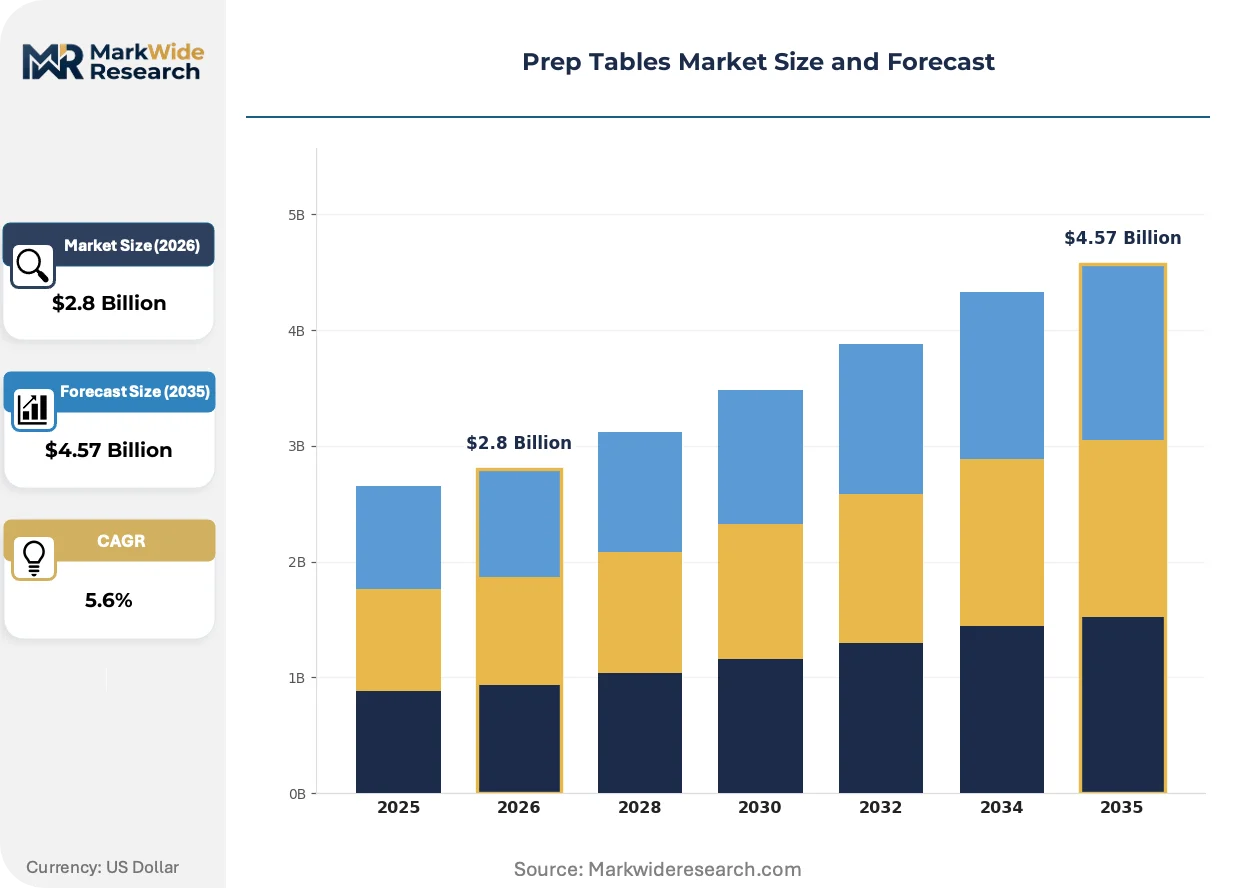
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Wood, Plastic, Aluminum End User: Restaurants, Catering Services, Laboratories, Home Kitchens Size: Small, Medium, Large, Extra Large Application: Food Preparation, Storage, Serving, Display |
| Companies Covered | Ali Group, Electrolux Professional, True Manufacturing, Everest Refrigeration, Delfield, Hoshizaki Corporation, Traulsen, Duke Manufacturing, Turbo Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prep Tables Market Evolving Landscape
Connected refrigeration systems and alternative surface materials are actively reshaping specification priorities across commercial foodservice procurement, compressing traditional equipment lifecycles and opening new competitive positioning vectors.
Variable-speed compressor technology is expanding into mid-tier prep table configurations previously dominated by fixed-speed systems. Fast-casual chains with 50-200 unit footprints are adopting these units at accelerating rates to manage demand charges and peak load constraints. This diffusion is expanding into price-sensitive buyer segments and compressing the premium tier's technology exclusivity window.
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is restructuring equipment service ecosystems and refrigerant supply chains. Manufacturers are redesigning sealed systems around hydrofluoroolefin alternatives, with California and Washington state regulations accelerating compliance timelines ahead of federal mandates. This regulatory compression most affects independent operators with limited capital reserves for premature equipment retirement.
Equipment-as-a-service financing models are displacing traditional capital purchase structures in multi-unit restaurant operations. Third-party fleet management providers are bundling maintenance, compliance monitoring, and replacement scheduling into per-unit monthly fees. This shift is most visible in Texas and Florida ghost kitchen clusters where operator turnover and capital constraints favor operational expenditure structures.
Prep Tables Market Segmentation
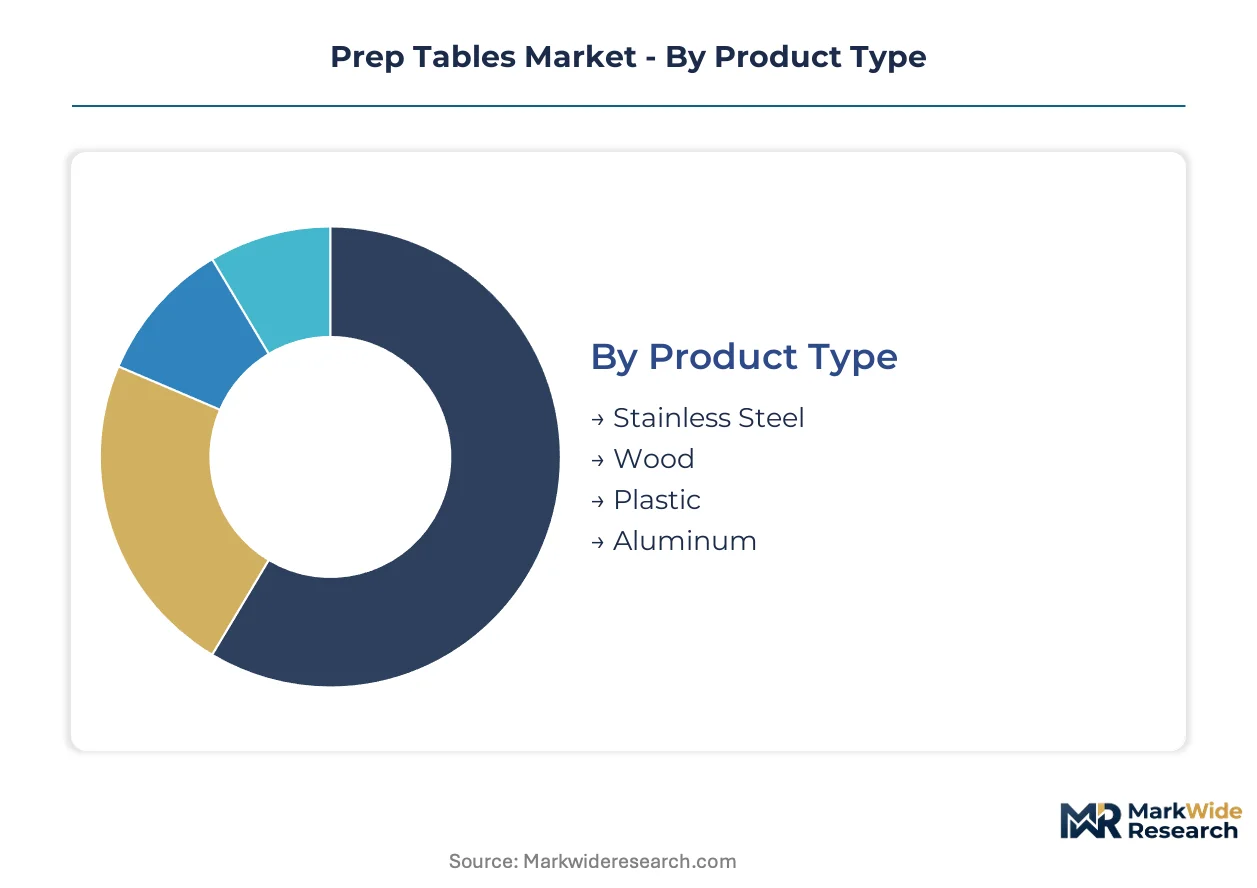
Segmentation in the prep tables market reveals how material specifications, end-use requirements, and dimensional constraints drive procurement decisions across distinct operational environments. Understanding these divides helps manufacturers align production capacity with the diverging needs of high-volume foodservice chains versus specialized institutional buyers.
Product Type:
Integration depth varies sharply across material categories, with standalone refrigeration-integrated units commanding premium positioning while surface-only configurations serve cost-constrained retrofit projects.
- Stainless Steel:Fabricated from 16- to 18-gauge 304-grade alloy with NSF International certification for food contact surfaces. Demand concentrates in quick-service restaurant chains across Texas, California, and Florida where durability standards and sanitation protocols are non-negotiable. The material's thermal conductivity supports under-counter refrigeration integration without structural compromise.
- Plastic:High-density polyethylene and polypropylene formulations offering chemical resistance and lower capital outlay. Educational institutions and laboratory end-users in California Title 24 renovation projects are driving specification growth where stainless steel's cost premium cannot be justified. The segment benefits from lighter weight and modular replacement economics.
- Wood:Hard maple and composite surfaces treated with food-safe sealants for front-of-house display applications. Artisanal bakeries and open-kitchen fast-casual concepts specify these for aesthetic warmth in customer-visible installations.
- Aluminum:Anodized or powder-coated lightweight alternatives for mobile catering equipment and temporary kitchen installations where transport weight constraints dominate material selection.
Stainless Steel leads volumes today; Plastic is gaining share fastest.
End User:
Cost tier stratification separates capital-rich multi-unit operators from budget-constrained independent establishments and non-commercial institutions.
- Restaurants:Full-service and fast-casual operations with dedicated refrigeration-to-fabrication workflows. Ghost kitchen proliferation in Texas and Florida is compressing equipment footprints while elevating throughput requirements per linear foot of prep surface.
- Catering Services:Mobile and event-based food preparation requiring rapid deployment and breakdown capabilities. Equipment specifications prioritize caster mobility, electrical flexibility, and NSF certification for temporary foodservice permits.
- Laboratories:Research and testing facilities requiring chemical-resistant surfaces and precision temperature control for sample handling protocols. Plastic and specialty-coated surfaces dominate this specification tier.
- Home Kitchens:Residential and light commercial applications where aesthetic integration with cabinetry outweighs durability specifications. Smaller scale and lower duty cycles permit material compromises unacceptable in professional environments.
Restaurants dominate procurement volumes; Catering Services are climbing the fastest as event-based dining recovery accelerates equipment refresh cycles.
Size:
Application context and kitchen footprint constraints dictate dimensional selection, with urban real estate compression favoring compact configurations.
- Small:Under 36-inch widths for food trucks, compact ghost kitchens, and front-of-house assembly stations. California and Texas operators specify these for high-rent urban locations where square footage commands premium pricing.
- Medium:36- to 60-inch configurations balancing throughput capacity with spatial economy. Fast-casual chains with 50-200 unit footprints standardize on this tier for kitchen template consistency.
- Large:60- to 96-inch surfaces for high-volume quick-service production lines. Central commissary operations and institutional foodservice facilities deploy these for batch preparation workflows.
- Extra Large:Custom-configured 96-inch-plus installations for casino, stadium, and hospital central kitchens with continuous production requirements.
Medium sizes anchor current procurement; Small configurations are expanding most quickly as delivery-only kitchen formats proliferate.
Application:
Functional role determines refrigeration integration depth, with temperature-critical uses mandating sealed systems while ambient applications permit surface-only specifications.
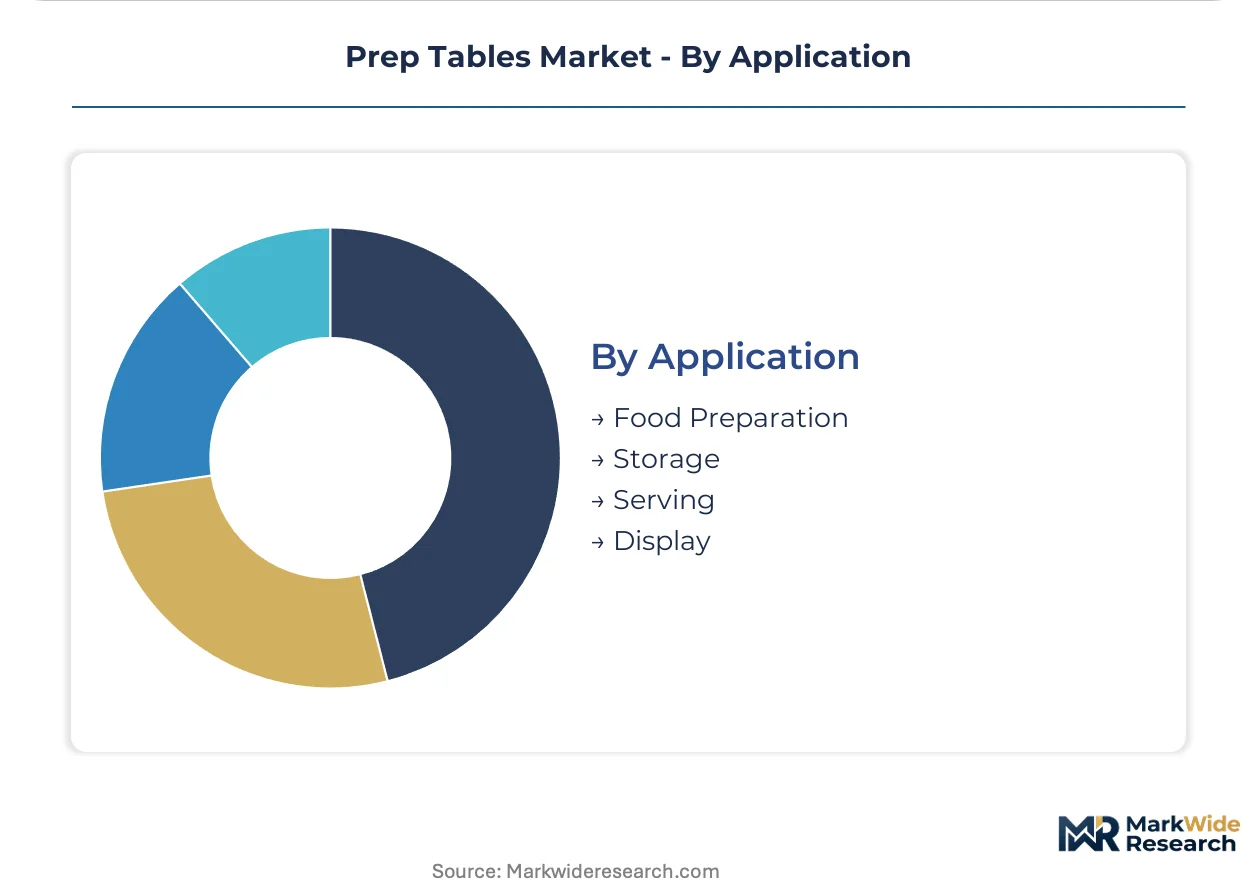
- Food Preparation:Integrated under-counter refrigeration maintaining 33°F to 41°F for ingredient accessibility during assembly. The U.S. Department of Energy efficiency standards are accelerating replacement of legacy units in this core application.
- Storage:Ambient or passively cooled configurations for dry goods and non-temperature-sensitive equipment. Lower specification requirements permit cost-tier compression and extended replacement cycles.
- Serving:Front-of-house configurations combining food safety compliance with customer-facing aesthetics. Open-kitchen restaurant designs in Florida and California are elevating specification priority for this hybrid function.
- Display:Refrigerated or ambient cases with enhanced visibility for ingredient transparency marketing. Fast-casual salad and bowl concepts specify these for brand differentiation in competitive urban markets.
Food Preparation commands the largest installed base; Display applications are on the steepest expansion trajectory as front-of-house visibility becomes a design priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial prep table industry traces its modern scaling to post-war American foodservice industrialization, when stainless steel fabrication standardized around NSF sanitation protocols and integrated refrigeration became kitchen infrastructure.
United States
Ghost kitchen proliferation in Texas, Florida, and California drives concentrated demand for compact refrigerated workstations. The U.S. Department of Energy's commercial refrigeration efficiency standards compress replacement cycles for legacy equipment. Dallas-Fort Worth and Miami metropolitan clusters see accelerated deployment of delivery-only kitchen formats.
Germany
Precision engineering traditions anchor commercial kitchen equipment manufacturing in Baden-Württemberg and Bavaria. The EU F-Gas Regulation accelerates hydrofluorocarbon phase-down timelines ahead of federal mandates. Stuttgart industrial corridor manufacturers emphasize energy-optimized sealed systems for export markets.
Japan
Compact footprint design priorities align with urban real estate constraints in Tokyo and Osaka metropolitan kitchens. METI energy efficiency labeling programs elevate specification thresholds for imported and domestic equipment. Nagoya manufacturing clusters specialize in high-density refrigeration-to-fabrication integration.
China
Foodservice infrastructure expansion in tier-one cities drives specification demand for Western-standard sanitation certification. GB standards for commercial refrigeration equipment tighten energy consumption thresholds annually. Yangtze River Delta manufacturing bases scale stainless steel fabrication capacity for domestic and export markets.
Italy
Artisanal foodservice traditions sustain demand for aesthetic front-of-house display configurations in Milan and Rome. EU Green Deal provisions accelerate building efficiency renovation cycles in commercial kitchen installations. Emilia-Romagna equipment fabricators integrate traditional metalworking with modern refrigeration technology.
Prep Tables Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and refrigeration integration sophistication. The vendor base stratifies between full-system integrators with sealed refrigeration expertise and surface-only fabricators serving retrofit markets. Three archetypes dominate: diversified foodservice conglomerates with brand portfolio breadth, specialized refrigeration technology houses with compact system leadership, and regional stainless steel fabricators with distributor relationship density. Competitive moves concentrate on M&A-driven brand consolidation and geographic expansion through distribution partnership networks.
Within the diversified conglomerate tier, Ali Group exemplifies multi-brand portfolio strategy across price segments. True Manufacturing anchors domestic manufacturing scale archetype through Missouri-based fabrication. Hoshizaki Corporation occupies specialized refrigeration technology position with compact footprint design leadership. These three represent distinct competitive positioning vectors rather than direct substitution alternatives.
| Leading Market Players |
|---|
| Ali Group |
| Electrolux Professional |
| True Manufacturing |
| Everest Refrigeration |
| Delfield |
| Hoshizaki Corporation |
| Traulsen |
| Duke Manufacturing |
| Turbo Air |
| Others |
Value Network & Pricing Analysis
Variable-speed compressor technology diffusion into mid-tier prep table configurations is simultaneously compressing premium-tier exclusivity windows and concentrating manufacturing scale among sealed-system specialists with R&D depth. This technological shift redirects procurement economics toward operational expenditure models while amplifying price competition across equipment-as-a-service financing structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by NSF International certification grade and after-sales service bundling. Price erosion runs through economy tiers as Chinese manufacturers scale stainless steel fabrication capacity for export markets. Quick-service restaurant chains with 50-200 unit footprints exhibit lowest price sensitivity due to standardized kitchen templates, while independent ghost kitchen operators in Texas and Florida face acute capital constraints.
Supply Chain Analysis
Regional distribution centers in Missouri, California, and Texas anchor hub-and-spoke patterns serving quick-service and fast-casual chains. Manufacturing draws from U.S.-based stainless steel fabrication, Chinese component sourcing for compressors and electronic controls, and Mexican assembly for price-sensitive export tiers. Single-source vulnerability concentrates in specialized HVAC-R service capacity for sealed refrigeration systems. Distribution runs through foodservice equipment dealers with NSF certification expertise and direct OEM relationships for multi-unit accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as DOE efficiency mandates and refrigerant phase-down regulations elevate specification thresholds toward premium refrigeration-integrated systems. Ghost kitchen proliferation and fast-casual front-of-house visibility requirements concentrate demand growth in certified, compact-footprint configurations.
For Market Incumbents: Anchor market position through backward integration into compressor and control system manufacturing to defend margins against refrigerant transition costs. Prioritize certification investment in California Title 24 compliance ahead of federal mandate timelines. Consolidate distributor relationships in Texas and Florida ghost kitchen clusters to preempt emerging regional fabricators.
For New Entrants and Emerging Players: Enter via educational institution modernization segments where plastic-surface specifications and lower capital requirements reduce incumbent brand loyalty barriers. Target K-12 and university foodservice programs in California Title 24 renovation corridors. Pursue equipment-as-a-service financing partnerships to bypass capital purchase preference gaps against established OEMs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional stainless steel fabricators with distributor density but limited refrigeration integration capabilities. Long-term viability hinges on sealed-system expertise as regulatory compression accelerates. Monitor EPA SNAP program enforcement intensity as inflection indicator for premature replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigeration Technology Licensing | Sealed-system expertise transfers compress DOE compliance timelines for independent fabricators. |
| Backward Integration into Compressors | In-house production of variable-speed systems captures margin from refrigerant transition costs. |
| Equipment-as-a-Service Launch | Monthly fee structures align with ghost kitchen operator turnover and capital constraints in Texas clusters. |
| NSF Certification Acceleration | Fast-tracked sanitation approval opens institutional procurement channels ahead of competitor filings. |
| Distribution Partnership Expansion | Dealer network density in Florida and California metros secures specification priority in renovation cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice equipment procurement directors, commercial kitchen design consultants, NSF certification specialists, and HVAC-R service contractors with secondary validation against DOE efficiency standard filings, EPA SNAP program updates, California Title 24 code revisions, and foodservice operator capex disclosures. Bottom-up shipment data triangulated against top-down construction permit analysis for commercial kitchen installations.
Segment-weighting approaches applied across material type, end-user category, dimensional configuration, and application function to distribute volume and value estimates. CAGRs derived from equipment replacement cycle modeling incorporating regulatory compliance deadlines and refrigerant phase-down timelines. Forecast inputs included ghost kitchen square footage expansion in Dallas-Fort Worth and Miami metros, plus fast-casual chain unit growth trajectories.
Inputs from regulatory filings and equipment manufacturer disclosures were available through the study window; gaps in independent operator capital expenditure intentions introduce uncertainty bands around replacement timing assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Serveware Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Rainbow Flatware Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market