
 India Home Furniture Market | 2026-2036
India Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Furniture Market Outlook
BIS certification for engineered wood products is hardening the cost-of-entry calculus for unorganized manufacturers. Godrej Interio leverages its captive manufacturing network across multiple states to sustain price competitiveness. Wakefit anchors its growth through direct-to-consumer digital channels that bypass traditional distributor markups. Pepperfry competes by operating large-format experience centers in metro clusters where tactile evaluation still drives purchase decisions.
India home furniture encompasses movable articles designed for residential interior spaces, typically constructed from solid wood, engineered panels, metal frames, or upholstered composites using CNC routing, edge-banding, and powder-coating processes. These products serve functional, ergonomic, and aesthetic purposes within living, sleeping, dining, and storage environments. The wood material segment dominates revenue owing to cultural preference for teak and sheesham, though metal frames are gaining traction in urban apartments where durability and lighter weight matter. Residential end users command the largest volume share, while hospitality applications generate superior per-unit margins due to customized procurement contracts and bulk replacement cycles.
BIS standards, CDSCO guidelines for furniture finishes with chemical contact, and state-level municipal zoning regulations collectively shape product compliance and retail footprint expansion across India. The PLI scheme for furniture manufacturing is attracting capital toward domestic component production, reducing import dependence for hardware and fittings. Stakeholders must monitor how evolving e-commerce FDI rules and state-level GST enforcement affect omnichannel cost structures and last-mile delivery economics.
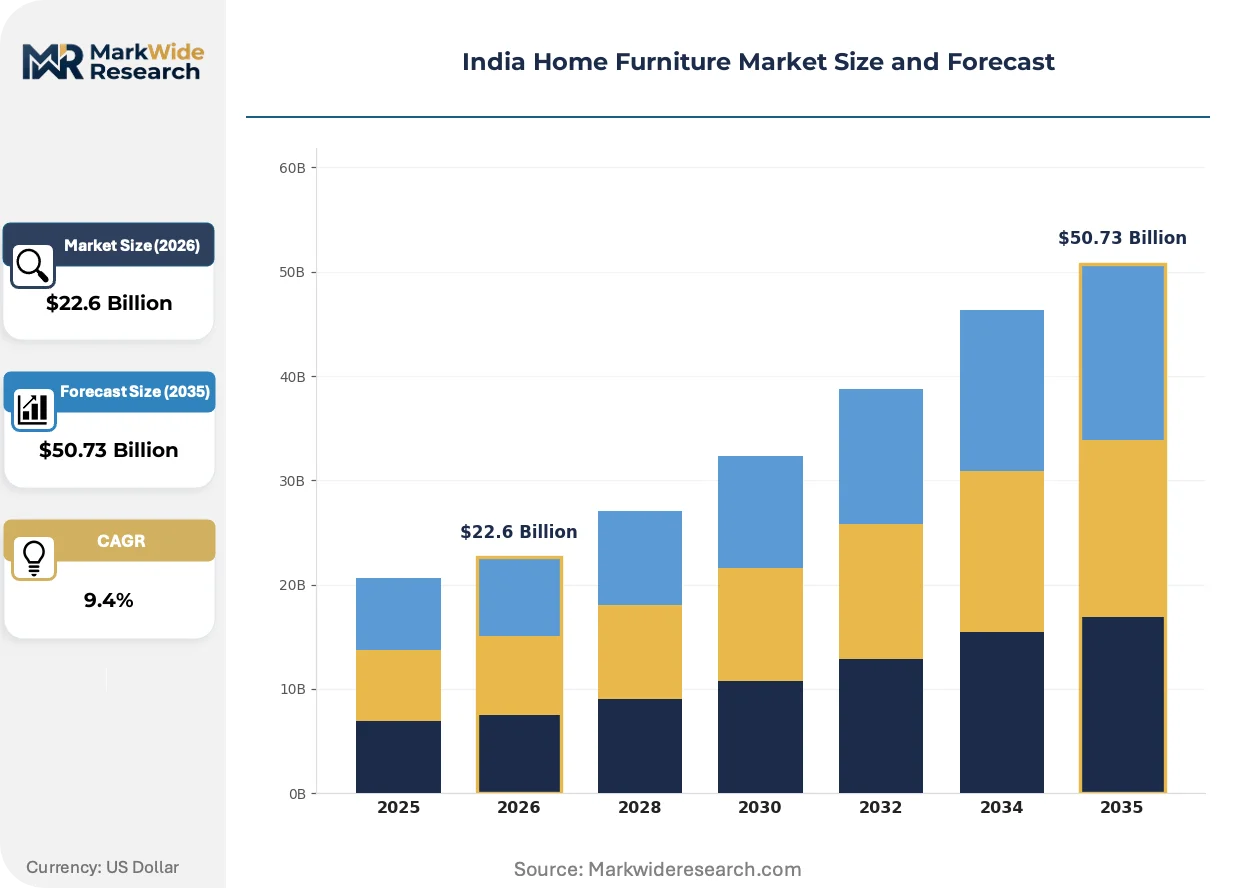
Market Dynamics
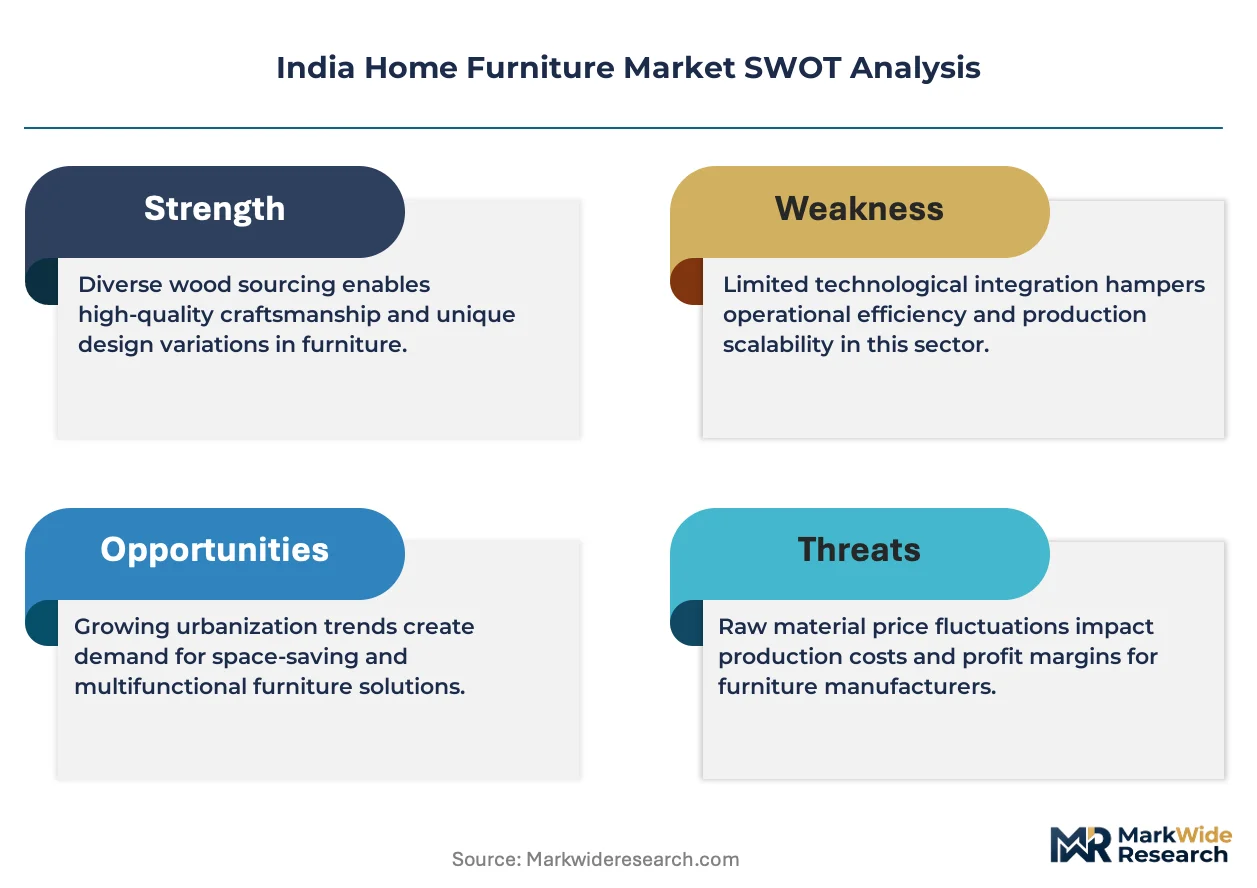
The PLI scheme for furniture manufacturing is redirecting capital toward domestic component ecosystems, compressing import dependence for hardware while reshaping competitive economics across Maharashtra, Karnataka, and Telangana production clusters.
Growth Catalysts
- Urban millennial demand in tier-2 cities:Young professionals in cities like Pune, Kochi, and Jaipur are accelerating adoption of ready-to-assemble furniture that balances aesthetics with apartment mobility constraints.
- BIS certification mandate:The Bureau of Indian Standards certification for engineered wood products is elevating quality benchmarks and filtering substandard imports from unorganized suppliers.
- Organized retail penetration:Deepening modern trade networks in western and southern states are extending credit facilities and installation services to first-time homebuyers.
Market Restraints
- Teak and sheesham price volatility:Domestic solid wood supply faces cyclical cost pressure from restricted logging permits and competing industrial demand.
- Unorganized sector fragmentation:Local carpenters and small workshops in northern and eastern states absorb volume through undifferentiated pricing and cash transactions.
- Import dependence for premium hardware:High-grade hinges, drawer systems, and soft-close mechanisms still originate primarily from German and Chinese suppliers.
Strategic Opportunities
- Underpenetrated eastern and northeastern states:West Bengal, Odisha, and Assam present whitespace where organized players can establish distribution before local competitors consolidate.
- Direct-to-consumer digital channels:Virtual room configuration tools and augmented reality visualization are compressing the purchase decision cycle for metropolitan apartment buyers.
- PLI scheme capital attraction:Domestic production incentives for furniture manufacturing are enabling backward integration into component fabrication and hardware assembly.
Industry Challenges
- Skilled CNC operator scarcity:Precision cutting and edge-banding automation requires trained technicians that vocational institutes in tier-2 manufacturing towns currently undersupply.
- BIS certification timeline compression:Engineered wood product testing and laboratory validation cycles delay new product launches by six to twelve months.
- Omnichannel inventory synchronization:Experience center display stock conflicts with warehouse fulfillment commitments, creating availability mismatches across digital and physical touchpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Furniture Market |
| Market Size in 2026 | $22.6 Billion |
| Market Size in 2035 | $50.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Tables, Chairs Material: Wood, Metal, Glass, Fabric End User: Residential, Commercial, Hospitality, Institutions Style: Modern, Traditional, Vintage, Contemporary |
| Companies Covered | Durian Industries, Wakefit, Godrej Interio, Pepperfry, Urban Ladder, IKEA, Zuari Furniture, Featherlite, Nilkamal Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Furniture Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine product specifications and procurement patterns across residential and hospitality verticals.
Engineered wood substrates incorporating moisture-resistant resins and low-emission binders are rewriting durability standards for Indian humidity conditions. Apartment developers in Mumbai and Bengaluru specify these panels for built-in wardrobes and kitchen cabinetry. The shift is compressing demand for untreated solid wood in urban mass housing projects.
BIS certification protocols for formaldehyde emission limits and structural load testing are tightening compliance windows for imported engineered panels. Manufacturers in Gujarat and Tamil Nadu are reconfiguring production lines to capture certification advantages. Hospitality procurement teams now mandate BIS-marked products for franchise property fit-outs.
Ready-to-assemble flat-pack distribution is displacing traditional carpenter-dependent delivery in metropolitan and tier-2 markets. Young professionals relocating for employment prefer furniture that disassembles for inter-city moves. This pattern concentrates in technology sector hubs where rental turnover runs highest.
India Home Furniture Market Segmentation
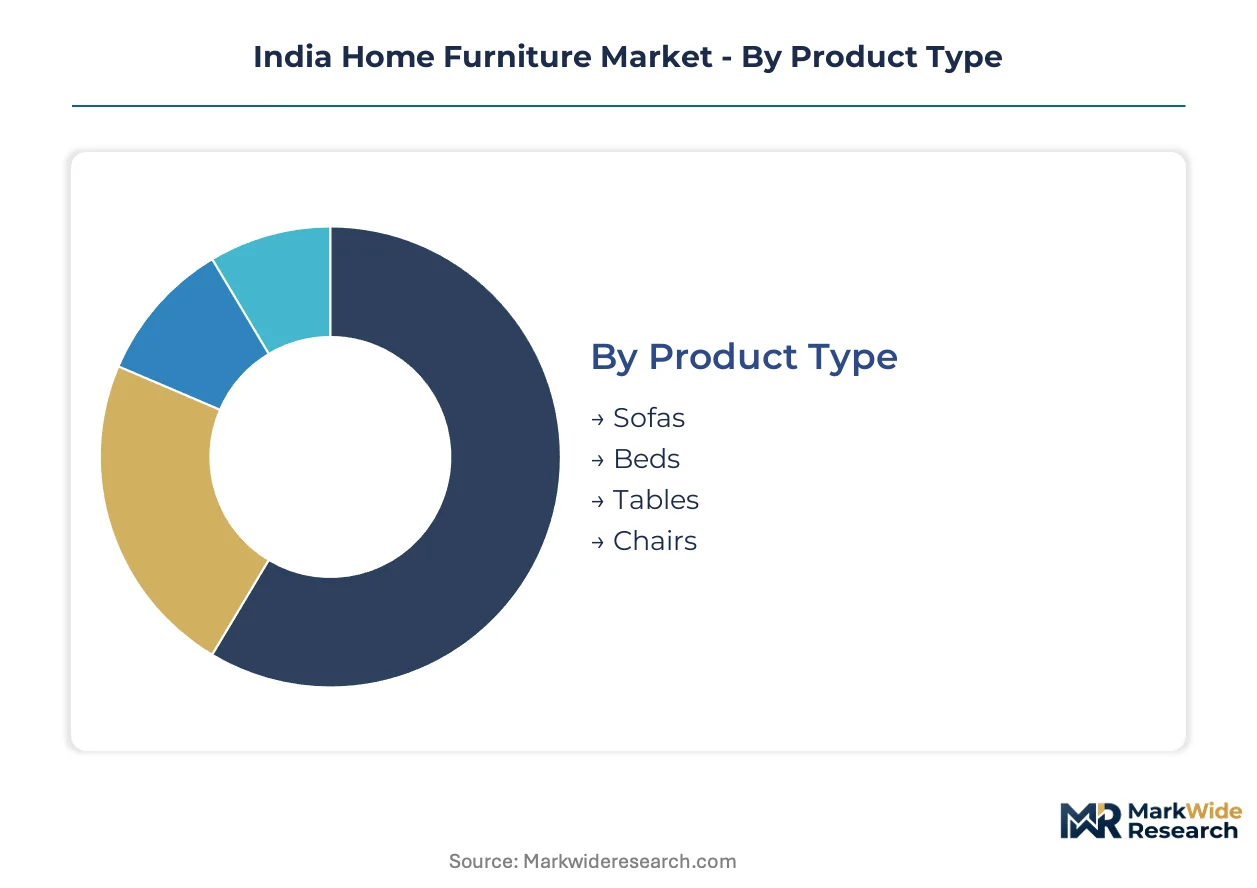
Segmentation reveals how purchasing decisions fragment across price sensitivity, durability expectations, and aesthetic preferences in India's home furniture market. Material choices and end-use applications create distinct margin profiles that reshape manufacturer priorities across production clusters.
Product Type:
Room functionality dictates replacement cycles and margin capture for Indian households upgrading from carpenter-built to branded furniture.
- Sofas:Upholstered seating systems using high-density foam, spring mechanisms, and hardwood frames dominate living room refurbishment spending. Demand clusters in Mumbai and Bengaluru apartment complexes where developers specify modular units for compact layouts, though leather price volatility compresses margin stability for premium variants.
- Beds:Platform and storage-integrated designs using engineered wood substrates and hydraulic lift systems capture master bedroom renovation budgets. Maharashtra and Karnataka lead volume absorption as nuclear family formats displace joint households, shrinking king-size demand while queen and single variants expand.
- Tables:Dining and work-surface units span laminate-topped engineered panels to solid wood heirloom pieces. Urban professionals in Hyderabad and Pune drive ready-to-assemble adoption for home office configurations.
- Chairs:Ergonomic task seating and accent pieces range from molded polypropylene to teak and cane constructions. Institutional procurement in educational and healthcare facilities sustains bulk order flows.
Volume sits with beds; growth tilts toward sofas as apartment living shrinks room counts and concentrates leisure spending.
Material:
Cost tiers and climate durability separate mass-market adoption from premium positioning in Indian households.
- Wood:Solid teak and sheesham retain cultural prestige for living and dining furniture, though BIS-certified engineered panels with moisture-resistant resins displace untreated timber in Bengaluru and Chennai humidity conditions. Price volatility from restricted logging permits pressures margin structures for heritage-grade manufacturers.
- Metal:Powder-coated steel and aluminum frames gain traction in urban rental markets where frequent relocation demands lightweight, disassemblable construction. Mumbai and Delhi NCR apartment complexes specify metal bed frames for durability in high-turnover tenant environments.
- Glass:Tempered and laminated surfaces accent coffee tables and display units, constrained by safety concerns in households with young children.
- Fabric:Performance textiles and leatherette upholsteries enable color customization and stain resistance for sofa and headboard applications. Hospitality procurement in Goa and Rajasthan resort properties drives commercial-grade specifications.
Wood commands the revenue base; metal is expanding most quickly among millennial renters prioritizing portability over permanence.
End User:
Customer type determines specification complexity, payment terms, and replacement cadence across the value chain.
- Residential:Individual households purchasing for owned or rental properties constitute the volume foundation, with first-time homebuyers in tier-2 cities accelerating organized brand adoption through EMI financing and installation bundling.
- Commercial:Corporate offices and coworking operators in Bengaluru and Hyderabad procure ergonomic workstations and meeting furniture on three-to-five-year refresh cycles.
- Hospitality:Hotels and resorts generate superior per-unit margins through customized procurement contracts, bulk replacement schedules, and franchise-mandated specification compliance.
- Institutions:Educational facilities, healthcare centers, and government hostels issue tenders prioritizing durability certifications and lowest-compliant-bid pricing.
Residential absorbs the unit volume; hospitality delivers the steepest expansion trajectory as branded hotel development accelerates in tier-2 tourism circuits.
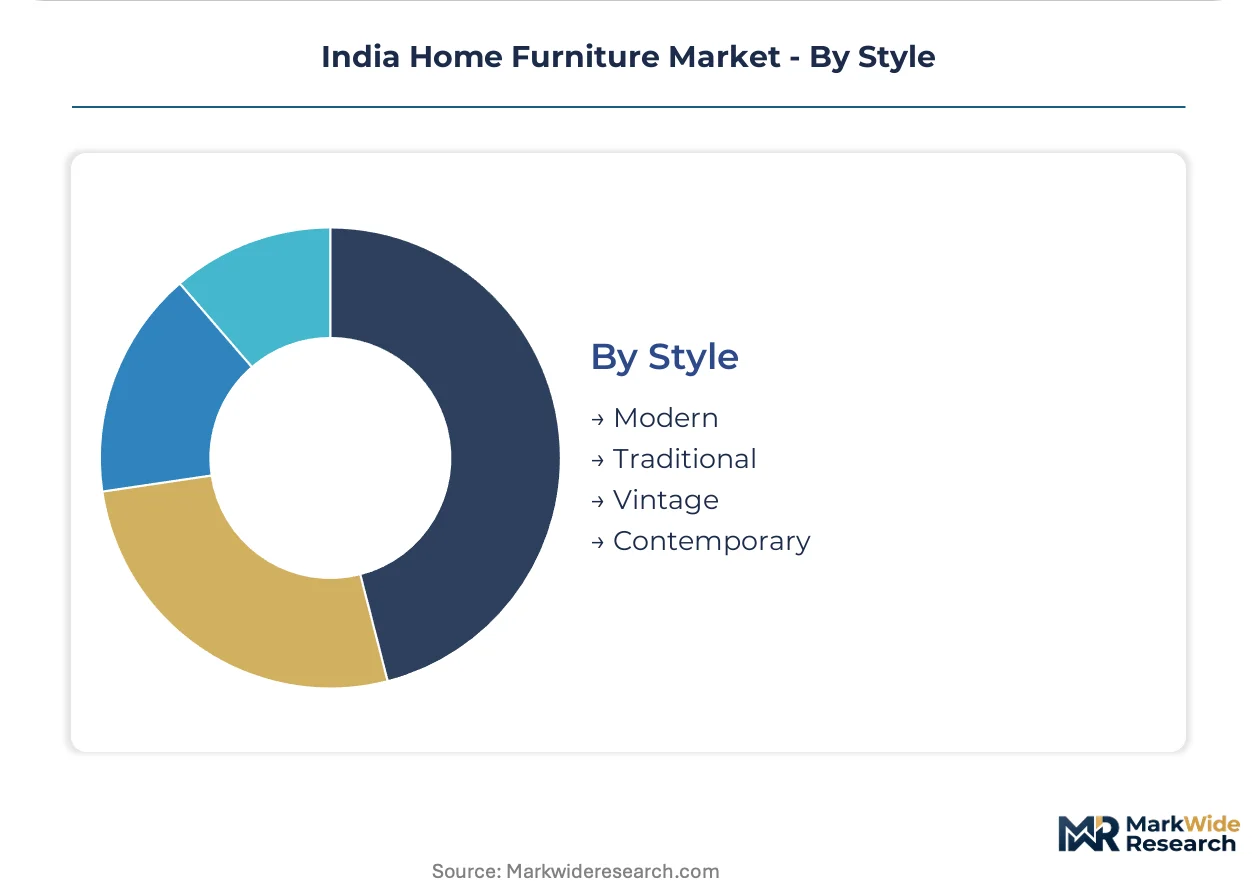
Style:
Aesthetic positioning separates heritage craftsmanship appeal from contemporary minimalism in urban and semi-urban markets.
- Modern:Clean lines, neutral palettes, and minimal ornamentation align with compact apartment dimensions and Scandinavian-influenced design publishing. Bengaluru and Pune technology professionals drive adoption through digital-native furniture platforms.
- Traditional:Carved teak, brass fittings, and regional craft motifs retain preference in Gujarat and Rajasthan household formation rituals, though production timelines stretch delivery commitments.
- Vintage:Distressed finishes and reclaimed wood aesthetics attract boutique hospitality and design-conscious residential buyers seeking differentiation.
- Contemporary:Transitional blends of modern silhouettes with traditional materials capture emerging affluent households unwilling to commit to pure heritage or minimal expression.
Traditional styling holds the established base; modern configurations are gaining share fastest among under-35 purchasers in western and southern metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Maharashtra, Karnataka, and Telangana, where organized retail networks penetrate deepest and urban millennial homebuyers drive ready-to-assemble furniture adoption.
Maharashtra
Mumbai and Pune apartment complexes generate substantial volume for modular storage and compact seating solutions. The state's municipal zoning regulations govern large-format retail footprint expansion in metropolitan clusters. Manufacturing facilities in Thane and Nashik districts supply western India while navigating BIS certification timelines for engineered wood exports.
Karnataka
Bengaluru technology professionals accelerate modern furniture adoption through digital-native platforms with augmented reality visualization tools. State-level GST enforcement mechanisms affect omnichannel inventory synchronization for retailers operating experience centers. Production units in Hosur and Mysuru industrial corridors specialize in CNC-routed panel processing for residential and hospitality contracts.
Telangana
Hyderabad's nuclear family household formation patterns expand demand for queen-size beds and space-optimized dining configurations. The PLI scheme for furniture manufacturing attracts component fabrication investment to the state's hardware assembly ecosystem. Manufacturing clusters around Shamshabad leverage proximity to Rajiv Gandhi International Airport for expedited last-mile delivery logistics.
Tamil Nadu
Chennai humidity conditions drive specification shifts toward moisture-resistant engineered panels with low-emission binders. CDSCO guidelines for furniture finishes influence procurement standards in healthcare facility tenders. Coimbatore and Ambattur industrial zones host edge-banding and powder-coating operations serving southern regional distribution networks.
Gujarat
Surat and Ahmedabad residential developments specify BIS-certified engineered wood for built-in wardrobes and kitchen cabinetry. State industrial incentive programs complement central PLI scheme benefits for domestic hardware production. Vadodara manufacturing units reconfigure production lines to capture certification advantages for hospitality franchise fit-out contracts.
India Home Furniture Market Competitive Environment
Western India producers anchor one tier; southern specialists hold differentiated positions in engineered panel processing and hospitality supply. The vendor base spans captive manufacturing networks, direct-to-consumer digital platforms, and large-format experience center operators. Three archetypes dominate: integrated manufacturers with multi-state production footprints, digitally native brands bypassing distributor markups, and omnichannel retailers blending tactile evaluation with warehouse fulfillment. Competitive moves concentrate on backward integration into component fabrication and geographic preemption in underpenetrated eastern states.
Among established manufacturers, Godrej Interio exemplifies the integrated archetype with captive production networks across multiple states. Wakefit occupies a position within the direct-to-consumer tier, leveraging digital channels that compress purchase decision cycles for metropolitan apartment buyers. Pepperfry anchors the omnichannel vector, operating large-format experience centers where tactile evaluation still drives purchase decisions in metro clusters. These three represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Durian Industries |
| Wakefit |
| Godrej Interio |
| Pepperfry |
| Urban Ladder |
| IKEA |
| Zuari Furniture |
| Featherlite |
| Nilkamal Limited |
| Others |
Value Chain & Pricing Dynamics
First-time homebuyers in tier-2 cities anchor volume demand and compress pricing power toward EMI-financed, installation-bundled offerings. This buyer concentration forces manufacturers to absorb distributor markups through captive logistics networks while competing with cash-based unorganized carpentry.
Pricing Analysis
Spot inventory from unorganized workshops commands discounts against certified lead times from organized brands. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified engineered wood from untreated timber and metal-frame alternatives. Pricing pressure stems from teak and sheesham volatility as restricted logging permits tighten raw material access. Residential renovators in rental markets exhibit highest price sensitivity; hospitality procurement teams show lowest sensitivity due to franchise-mandated specifications.
Supply Chain Analysis
Direct-to-consumer digital channels handle metropolitan apartment demand while experience centers manage tactile evaluation requirements. Manufacturing concentrates in India, China, and Germany for hardware components. Domestic production draws from engineered panel substrates, powder-coated metal frames, and imported soft-close mechanisms. Single-source vulnerability runs through German hinge and drawer system suppliers. Distribution runs through omnichannel fulfillment networks balancing warehouse stock with display inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India home furniture market reads as a cost-of-compliance story where BIS certification for engineered wood products erects barrier-to-entry moats favoring capitalized incumbents over fragmented unorganized competitors.
For Market Incumbents: Anticipate margin compression from PLI scheme beneficiaries achieving hardware backward integration. Defend position by accelerating captive component fabrication in Maharashtra and Karnataka clusters while locking hospitality procurement through BIS-marked franchise contracts. For New Entrants and Emerging Players: Launch via direct-to-consumer digital channels targeting underpenetrated eastern states. West Bengal and Odisha present whitespace before local competitors consolidate. Prioritize ready-to-assemble flat-pack distribution for millennial renters in technology hubs. For Investors and Strategic Acquirers: Distressed-cycle entries favor digitally native brands with installed manufacturing capacity in Telangana and Tamil Nadu. Five-to-ten year viability hinges on PLI scheme utilization rates. Monitor BIS certification timeline compression as inflection signal for compliant player margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardware | PLI scheme incentives enable captive production of hinges and drawer systems reducing German import dependence. |
| BIS Certification Acceleration | Compressed laboratory validation cycles differentiate compliant manufacturers in hospitality franchise procurement. |
| Direct-to-Consumer Platform Launch | Virtual room configuration tools compress purchase cycles for Bengaluru and Pune apartment buyers. |
| Eastern State Distribution Preemption | Early entry into West Bengal and Assam secures whitespace before unorganized competitor consolidation. |
| Experience Center Network Expansion | Tactile evaluation requirements in Mumbai and Delhi NCR sustain omnichannel advantage over pure digital rivals. |
Study Parameters
Trade association filings, BIS certification registries, and state-level GST enforcement records formed the secondary backbone. Primary interviews with furniture manufacturing plant managers, organized retail category heads, hospitality procurement directors, and CNC equipment suppliers validated production capacity claims. Bottom-up and top-down triangulation reconciled channel inventory estimates with customs data on hardware imports.
Bottom-up modeling aggregated segment-level demand across material, product type, and end-user dimensions. Top-down cross-checks applied macro housing formation and mortgage disbursement trends. CAGRs derived from fitted growth curves across the projection horizon. Industry-specific inputs included apartment developer specification surveys and hospitality franchise fit-out schedules.
The model assumes a particular technology adoption path; alternative pathways for CNC automation and flat-pack distribution would alter the outlook. Forecasts reflect assumptions regarding PLI scheme participation rates and BIS enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
France Furniture Market
Furniture
Wooden Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
High End Furnitures Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
United States Upholstered Furniture Market
Furniture
Fireplace Mantels Market
Furniture
Saudi Arabia Furniture Market
Furniture
Germany Home Furniture Market
Furniture
Brazil Furniture Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
United States Home Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
Plastic Furniture Market