
 US School Furniture Market | 2026-2036
US School Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
US School Furniture Market Intelligence
The Consumer Product Safety Improvement Act (CPSIA) is repositioning the cost-of-entry for manufacturers by mandating stricter limits on lead and phthalates in children's products. Virco Mfg. Corporation leverages its extensive domestic manufacturing scale to ensure compliance and manage supply chain stability. Steelcase Inc. competes through ergonomic research and design-led solutions, primarily targeting higher education and private school environments. KI Furniture specializes in modular systems and mobile furniture catering to active and collaborative learning models.
US school furniture encompasses durable, purpose-built furnishings designed for educational institutions from pre-K to university levels. Products are engineered for high-use environments, often featuring high-pressure laminate surfaces for cleanability and robust steel frames for longevity. While chairs and desks constitute the core product segments by volume, public schools represent the dominant end-user category. Procurement in this segment is directly tied to government budget cycles and long-term enrollment trends.
Product standards are heavily influenced by the Business and Institutional Furniture Manufacturers Association (BIFMA), setting rigorous performance and safety criteria. The Americans with Disabilities Act (ADA) mandates accessibility features, impacting product design for public institutions. EPA guidelines on indoor air quality also promote low-VOC materials. Suppliers must balance meeting strict institutional bid requirements on cost with incorporating features that support flexible pedagogy.

Market Dynamics
The primary dynamic in the US school furniture market is the tension between fixed institutional budgets and the pedagogical shift toward active learning. This conflict shapes procurement decisions, forcing schools to balance long-term flexibility and ergonomic benefits with the immediate cost constraints inherent in public purchasing cycles.
Growth Catalysts
- School Construction Bonds:State-level funding initiatives in high-growth regions finance new school construction and modernization, creating predictable, large-scale demand for classroom furnishings.
- Active Learning Pedagogy:The shift to collaborative learning models requires investment in mobile, modular furniture to support flexible classroom layouts in K-12 and higher education.
- ADA Compliance:The Americans with Disabilities Act mandates accessible product designs, driving replacement cycles for furniture like adjustable-height desks and specialized seating in public institutions.
Market Restraints
- Public Procurement Cycles:Demand is tied to government budget allocations and enrollment trends, creating cyclical purchasing patterns vulnerable to public funding cuts.
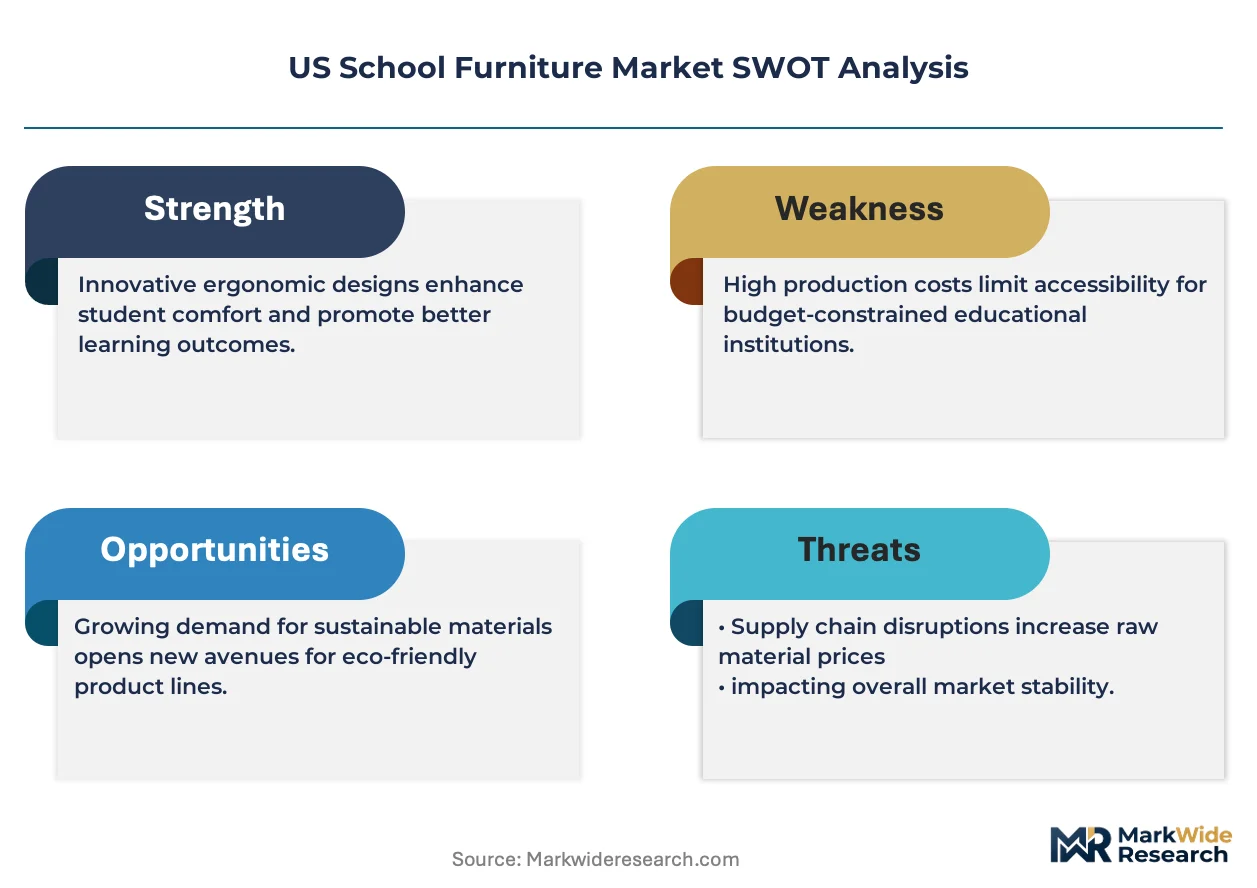
- Input Cost Volatility:Price fluctuations in raw materials like steel and high-pressure laminates directly compress manufacturer margins due to fixed-price institutional contracts.
- Extended Replacement Cycles:Budget-constrained districts often refurbish existing furniture instead of purchasing new units, suppressing sales volume and extending asset lifecycles.
Strategic Opportunities
- Smart Furniture Integration:Embedding power and data ports into desks and seating addresses the device-heavy needs of modern universities and private K-12 schools.
- Sustainable Materials:Growing demand for low-VOC and recycled-content products is driven by EPA indoor air quality guidelines and green building certifications like LEED.
- Higher Education Renovations:Universities are remodeling libraries and student centers, creating demand for design-led lounge and study furniture outside of traditional classroom procurement channels.
Industry Challenges
- Logistical Complexity:Coordinating last-mile delivery, assembly, and installation for large-scale projects within tight, summer-based timelines presents significant operational hurdles and labor costs.
- Navigating Layered Compliance:Manufacturers must meet overlapping requirements from BIFMA for performance, CPSIA for material safety, and the ADA for accessibility, increasing design and testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US School Furniture Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units Material: Wood, Metal, Plastic, Upholstery End User: Public Schools, Private Schools, Colleges, Universities Distribution Channel: Direct Sales, Online Retail, Wholesalers, Showrooms |
| Companies Covered | KI Furniture, HNI Corporation, Steelcase Inc., Paragon Furniture Inc., Hertz Furniture, MillerKnoll, Inc., Fleetwood Group, VS America, Inc., Virco Mfg. Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US School Furniture Market Strategic Shifts & Innovations
A fundamental shift from static, single-purpose furniture toward dynamic, user-centric systems is redefining classroom environments. This evolution prioritizes student well-being and supports varied pedagogical approaches, influencing material choice and product design across the US market.
Ergonomic design, focused on supporting student movement and focus, now integrates features like wobble stools and standing-height desks. Elementary and middle school districts are increasingly adopting these products to improve student engagement and physical well-being. This wellness-centric approach is expanding into the design of entire classroom furniture systems, influencing tables, storage, and space dividers.
The Consumer Product Safety Improvement Act (CPSIA) imposes strict limits on lead and phthalates in children's products, directly impacting pre-K and elementary school furniture. This federal regulation forces manufacturers to implement rigorous material testing and supply chain verification protocols to ensure compliance. Consequently, the early childhood education segment shows a preference for suppliers with transparent, often domestic, supply chains to mitigate compliance risks.
Purchasing decisions are evolving from purely price-driven, transactional bids toward more consultative, long-term partnerships between schools and suppliers. This model often displaces the traditional low-bid procurement process by bundling design services, space planning, and professional development with furniture sales. This shift is most prominent within affluent public school districts and the private K-12 sector.
US School Furniture Market Segmentation

Understanding the US school furniture market through detailed segmentation is crucial for stakeholders to identify specific demand drivers and procurement dynamics. This analysis highlights how different product types, materials, end-users, and distribution channels shape the competitive landscape and strategic opportunities within the educational sector.
Product Type:
The US school furniture market's product segmentation reflects the ongoing cycle of modernization and replacement within educational institutions.
- Desks:Comprising individual student workstations and teacher desks, these products feature robust construction, often with high-pressure laminate tops for durability. Demand for desks is concentrating in K-12 public schools, driven by replacement cycles and new construction bond initiatives.
- Chairs:This segment includes task chairs, classroom seating, and lab stools, engineered for ergonomic support and heavy use in educational settings. Procurement of chairs is heavily influenced by ADA compliance mandates, particularly for adjustable-height and specialized seating in public institutions.
- Tables:Collaborative tables, activity tables, and cafeteria tables form this category, designed for flexibility and group work across various learning environments.
- Storage Units:Cabinets, lockers, and shelving systems provide organizational solutions for classrooms, libraries, and common areas, supporting efficient space utilization.
Desks and chairs sit at the top of the volume ranking, with modular tables climbing the fastest.
Material:
Material choices in school furniture directly influence product longevity and institutional budget allocation, impacting long-term value for educational buyers.
- Metal:Steel and aluminum frames offer exceptional durability and structural integrity, crucial for high-traffic school environments. Demand for metal components is concentrated in public school districts, prioritizing longevity and resistance to wear.
- Plastic:High-density polyethylene and polypropylene are commonly used for chair shells and desk surfaces, providing lightweight, cleanable, and impact-resistant properties. Plastic materials are gaining traction in elementary and middle school environments due to their cost-effectiveness and vibrant color options.
- Wood:Solid wood and engineered wood products are utilized for aesthetic appeal and stability in certain furniture applications, particularly in administrative offices or private school settings.
- Upholstery:Fabric and vinyl coverings are applied to seating in lounge areas and collaborative spaces, enhancing comfort and contributing to modern design aesthetics.
Metal and plastic materials dominate procurement due to their resilience, while upholstery gains traction in collaborative learning spaces.
End User:
End-user segmentation reveals distinct procurement patterns and funding mechanisms across different educational environments, influencing product specifications and sales strategies.
- Public Schools:This segment encompasses K-12 public institutions funded by state and local governments, representing the largest volume purchaser of school furniture. Procurement in public schools is directly tied to government budget cycles and long-term enrollment trends, influencing large-scale bids.
- Universities:Higher education institutions, including public and private universities, drive demand for modern, flexible, and technology-integrated furniture solutions. Universities are investing in ergonomic and smart furniture for collaborative learning spaces and library renovations.
- Private Schools:Independent K-12 schools often prioritize design-led solutions and ergonomic features, with procurement less constrained by public budget cycles.
- Colleges:Community colleges and vocational schools focus on durable, functional furniture that supports diverse learning modalities and career training programs.
Public institutions represent the largest volume segment, while higher education drives innovation in design and technology.
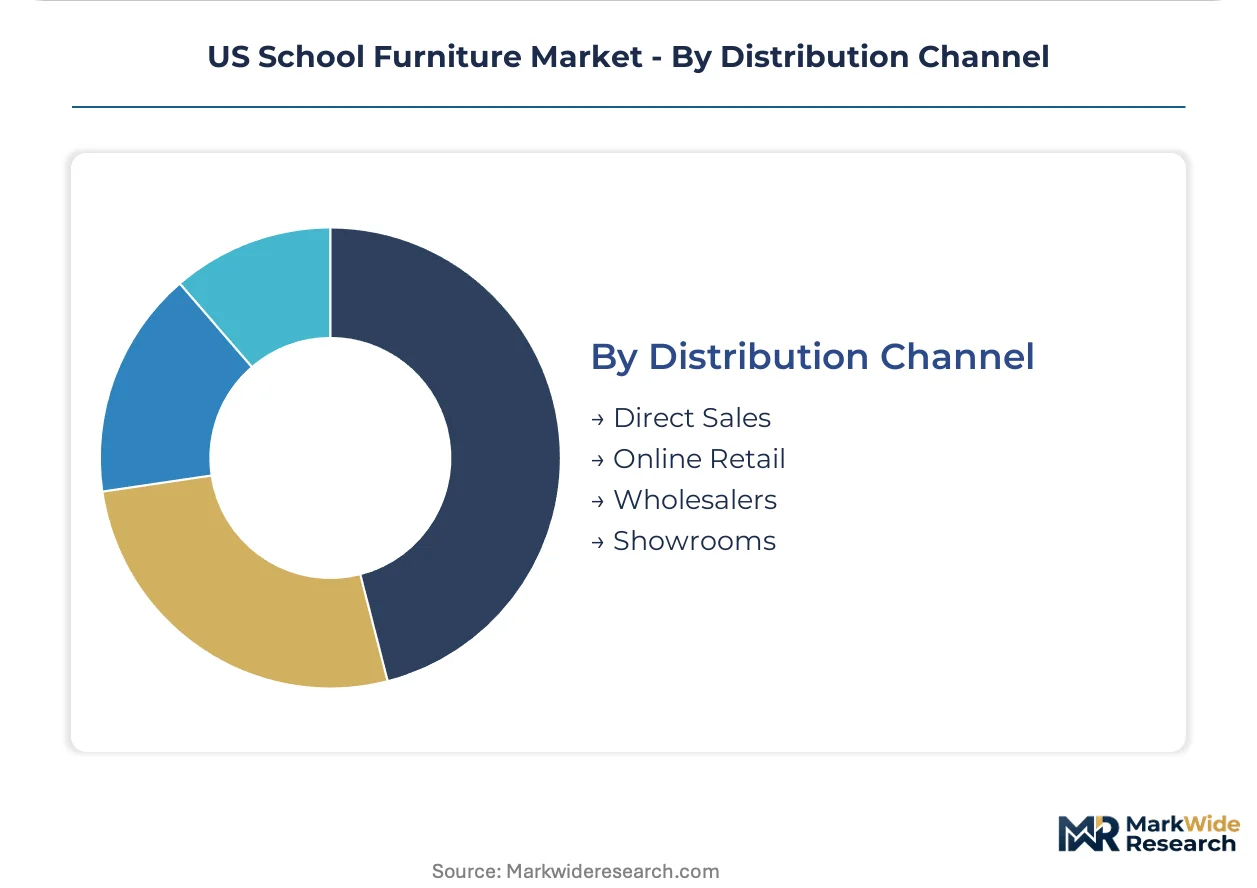
Distribution Channel:
Distribution channels reflect the varied purchasing scales and logistical requirements of educational institutions, from large district-wide contracts to individual classroom needs.
- Direct Sales:Manufacturers engage directly with large institutional buyers, including school districts and universities, often through competitive bidding processes. This channel is critical for complex projects requiring customization and installation services within tight timelines.
- Wholesalers:These intermediaries purchase in bulk from manufacturers and distribute to smaller school districts or private institutions, providing logistical efficiency. Wholesalers play a significant role in reaching a broad base of K-12 schools, managing inventory and delivery.
- Online Retail:E-commerce platforms offer a convenient purchasing option for smaller orders, replacement parts, or specialized furniture items, catering to individual school needs.
- Showrooms:Physical showrooms allow educational buyers to experience products firsthand, particularly for design-centric or ergonomic furniture solutions, facilitating informed purchasing decisions.
Direct sales channels remain critical for large project bids, while online platforms streamline procurement for smaller, recurring orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US school furniture market's dynamics are anchored by regional student populations and educational infrastructure investments. These factors drive varied procurement patterns across states. Significant demand originates from both K-12 and higher education segments, influencing product specifications and sales strategies.
Texas
Texas experiences strong demand from school construction bonds and a rapidly growing student population. ADA compliance mandates influence product specifications for new facilities, particularly for inclusive learning environments. Houston and Dallas metros lead large-scale school construction projects, creating predictable demand for core classroom furnishings. State-funded initiatives often prioritize durable, long-lasting products.
California
California's market benefits from modernization initiatives and a focus on active learning pedagogy. EPA guidelines on indoor air quality influence material choices for new builds and renovations. Los Angeles and Bay Area districts prioritize sustainable and ergonomic designs for their campuses, often seeking low-VOC products. Universities in the state also drive demand for technology-integrated solutions.
New York Metro
New York Metro's demand originates from higher education renovations and private school investments. The CPSIA impacts material safety for pre-K furniture procurement, requiring rigorous testing protocols. New York City and surrounding suburban districts invest in flexible learning spaces and technology integration, particularly for collaborative setups. This region often seeks design-led solutions for its diverse educational institutions.
Southeast (Florida/Georgia)
Enrollment growth drives consistent demand across the Southeast, particularly for K-12 replacement cycles. State-level procurement policies influence bid requirements for public institutions, often emphasizing cost-effectiveness. Atlanta and Miami areas experience steady demand from new school openings and facility upgrades. These states also see investment in furniture supporting active learning models.
US School Furniture Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the US school furniture market. The market structure exhibits a tiered consolidation, with several large manufacturers alongside numerous regional and niche providers. Archetypes include full-service solution providers, value-oriented suppliers focused on public procurement, and design-led innovators targeting specific learning environments. Dominant competitive moves involve strategic partnerships to expand service offerings and continuous product innovation to meet evolving pedagogical needs, often integrating technology.
Within the established players tier, Steelcase Inc. exemplifies a design-led approach, focusing on ergonomic research and advanced solutions for higher education and private schools. Virco Mfg. Corporation anchors the scale-driven segment, leveraging extensive domestic manufacturing to ensure compliance with regulations like CPSIA and maintain supply chain stability for public schools. KI Furniture occupies a position as a specialist in modular systems and mobile furniture, catering to active and collaborative learning models across various educational levels. These companies collectively shape product development and market trends.
| Leading Market Players |
|---|
| KI Furniture |
| HNI Corporation |
| Steelcase Inc. |
| Paragon Furniture Inc. |
| Hertz Furniture |
| MillerKnoll, Inc. |
| Fleetwood Group |
| VS America, Inc. |
| Virco Mfg. Corporation |
| Others |
Cost & Logistics Intelligence
ADA compliance mandates for accessible product designs significantly influence procurement, forcing manufacturers to adapt product lines and absorb redesign costs, which in turn impacts final pricing structures. This demand-side pressure requires suppliers to invest in retooling and certification, ultimately shaping the cost of goods sold and market pricing.
Pricing Analysis
The market's pricing model splits between bundled design services and unbundled transactional bids. Project-based pricing dominates for complex installations in higher education, often incorporating consultative design and installation. Price differentiation stems from customization levels and integrated after-sales support. Pricing pressure stems from input cost volatility for raw materials like steel, particularly within public procurement cycles. Public schools remain the most price-sensitive segment due to fixed government budgets, while private institutions and universities prioritize value over lowest cost.
Supply Chain Analysis
Single-source vulnerability sits with specific raw material suppliers for steel and high-pressure laminates, impacting production stability for US manufacturers. The supply chain draws from global sources for these key inputs, with China and Southeast Asian countries prominent for base materials. Commodity price volatility for steel presents a significant structural risk. Distribution runs through direct sales channels for large school districts and universities, complemented by wholesalers serving smaller K-12 institutions, managing inventory and last-mile logistics effectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US school furniture market operates as a regulatory compounder, with ADA compliance mandates consistently driving replacement cycles and product innovation across public institutions.
For Market Incumbents: Lock in long-term contracts with major school districts by offering bundled service packages that include design, installation, and maintenance. Invest further in domestic manufacturing capabilities to mitigate input cost volatility and ensure compliance with regulations like CPSIA, addressing the threat of supply chain disruptions. Enhance R&D into ergonomic and smart furniture solutions to capture higher education and private school demand.
For New Entrants and Emerging Players: Online retail platforms offer a direct route to market for specialized products, bypassing traditional procurement hurdles. Target the elementary and middle school segments with wellness-centric designs, such as wobble stools and standing desks, which represent a white space. Focus on supporting flexible pedagogy through modular and mobile furniture systems, appealing to affluent public school districts and the private K-12 sector.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche manufacturers specializing in smart furniture integration or sustainable material solutions. The long-term viability of this market is strong, driven by ongoing modernization and pedagogical shifts toward active learning. Seek acquisition targets with robust intellectual property in technology-integrated or low-VOC products. The signal to watch is the increasing allocation of construction bonds specifically for flexible learning space renovations.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Smart Furniture with Integrated Tech | Addresses device-heavy learning needs in higher education and private schools. |
| Strengthen Domestic Manufacturing Capacity | Ensures compliance with CPSIA and enhances supply chain stability for public procurement. |
| Integrate Design and Space Planning Services | Transforms transactional bids into consultative, long-term partnerships with institutions. |
| Invest in Sustainable and Low-VOC Materials | Meets EPA guidelines and growing demand for green building certifications like LEED. |
| Expand Modular and Mobile Furniture Lines | Supports the pedagogical shift towards active and collaborative learning environments. |
Research Approach
Coverage spans key US states including Texas, California, and New York Metro, with primary inputs from each region validating market dynamics. This study combines in-depth primary interviews with school district procurement officers, university facility managers, and furniture manufacturers' product development leads. Secondary validation draws from BIFMA standards, government budget reports, construction bond initiative documents, and academic studies on pedagogical trends, employing both bottom-up and top-down triangulation.
The analytical framework decomposes the rate-of-change across the analysis window, modeling market evolution through various segmentation dimensions. These include product type, material, end-user, distribution channel, and pedagogical approach, which define market segments. Compound Annual Growth Rates were derived from historical data extrapolation and forward-looking market drivers. Key industry-specific forecast inputs include school enrollment projections and state-level construction bond allocations.
The model assumes a particular technology adoption path; alternative pathways for smart furniture integration would alter the outlook. Forecasts reflect assumptions regarding government funding stability and raw material price trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Poland Home Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Europe Sustainable Mattress Market
Furniture
North America Slide Rails Market
Furniture
Entryway Furniture Market
Furniture
Europe School Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Indonesia Furniture Market
Furniture
Europe Bamboo Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Global Organic Furniture Market
Furniture
North America Smart Furniture Market