
 Poland Home Furniture Market | 2026-2036
Poland Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Home Furniture Market Analytics
Capital-intensity divergence between automated CNC production lines and manual assembly benches is bifurcating competitive tiers among Polish furniture makers. Szynaka-Meble Sp. z o.o. leverages its integrated particleboard mills to control raw material costs across the Silesian manufacturing corridor. Black Red White SA anchors its position through a dense franchise network spanning secondary Polish cities. Fabryki Mebli "Forte" SA differentiates via robotic finishing cells that reduce lacquer waste and cycle times.
Poland home furniture comprises movable domestic fixtures—seating, sleeping, storage, and surface units—fabricated from engineered wood panels, solid timber, metal hardware, and textile or leather coverings, typically finished with solvent-based or waterborne coatings to meet residential durability standards. Wood dominates material flows, with oak and beech commanding premium positioning while MDF and chipboard saturate mass-market cabinets and tables. Sofas and upholstered beds capture expanding margin pools as Polish consumers prioritize comfort upgrades, whereas metal-frame dining sets face stagnation amid shifting aesthetic preferences toward warmer residential palettes.
Poland's State Forests (Lasy Państwowe) supply chain oversight intersects with EU Timber Regulation due diligence and national BIS-equivalent conformity assessment for product safety, compressing market access for uncertified imports. The Polish Committee for Standardization (PKN) and EU REACH chemical restrictions jointly govern adhesive formaldehyde limits and textile flame-retardant composition, forcing reformulation investments across upholstery suppliers. Stakeholders must weigh backward integration into sustainable forestry assets against outsourcing to Baltic or Ukrainian sawmills as carbon-border adjustments reshape landed cost structures.
Market Dynamics
Poland's home furniture sector faces intense pressure from EU Ecodesign Directive mandates that force manufacturers to retool finishing processes and raw material sourcing. Warsaw apartment dwellers drive modular system adoption while Silesian producers absorb capital costs of robotic automation to maintain export competitiveness.
Growth Catalysts
- FSC Certification Requirements:Poland's State Forests chain-of-custody standards create competitive moats for domestic producers against uncertified Baltic imports. Masovian Voivodeship retailers now demand full timber traceability.
- Urban Density Shifts:Warsaw metropolitan area housing stock concentrates in sub-50 square meter units. Space-efficient storage beds and wall-mounted desk systems capture replacement cycles.
- Waterborne Coating Chemistry:Reformulated polyurethane dispersions reduce solvent emissions while maintaining scratch resistance. Polish finishers adopt these systems to preempt REACH restrictions.
Market Restraints
- Ukrainian Hardwood Supply Volatility:Beech and oak log flows through Brest corridor remain disrupted. Polish sawmills face 15-20 week lead time extensions for premium solid timber.
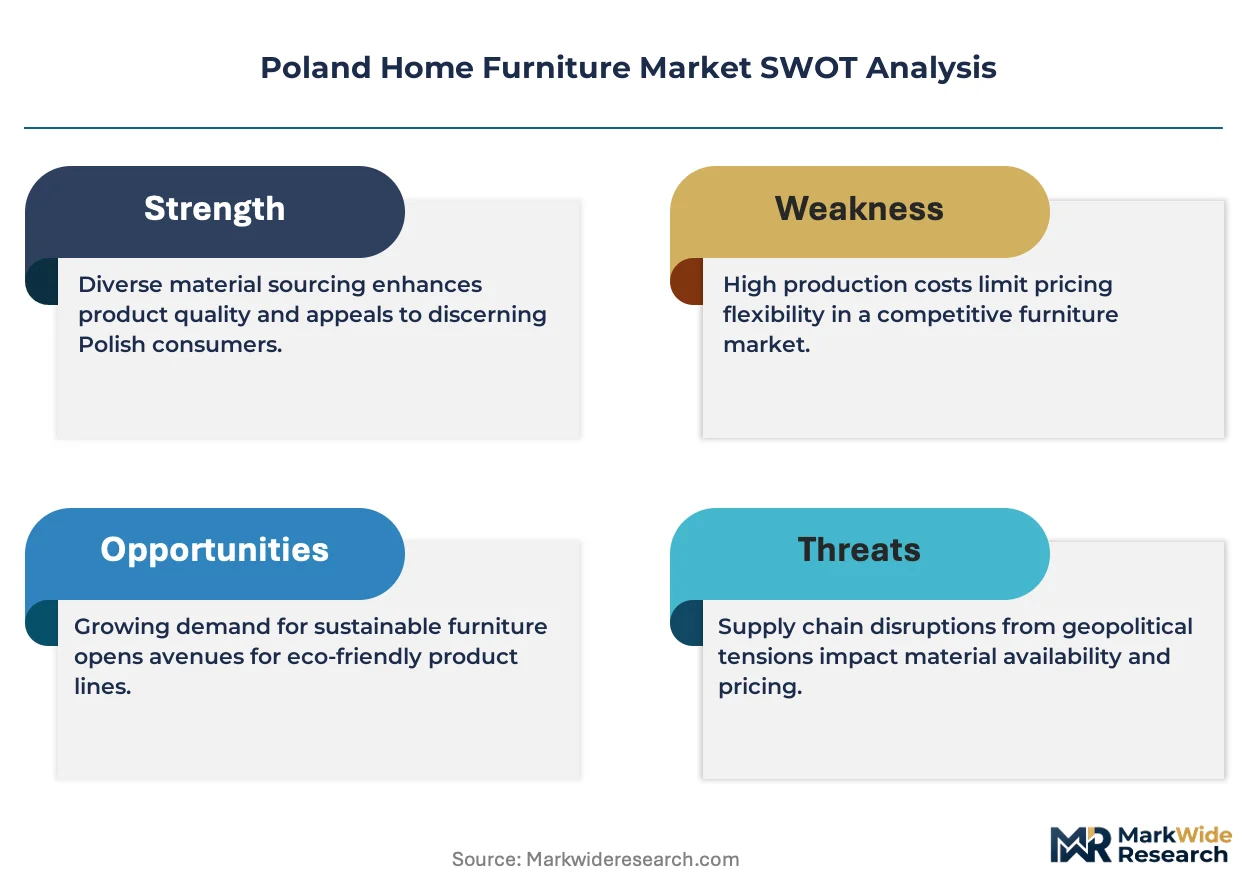
- Particleboard Input Cost Concentration:Three integrated mills control 70% of domestic MDF supply. Szynaka-Meble's captive production locks out mid-tier assemblers from margin-competitive sourcing.
- Formaldehyde Emission Caps:PKN's E1-E0 grade distinctions force adhesive reformulation. Small upholstery workshops lack capital for resin system upgrades.
Strategic Opportunities
- Łódź Manufacturing Corridor:Underutilized textile infrastructure from the 1990s apparel collapse offers conversion potential. Fabric cutting and sewing clusters await furniture sector activation.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in from 2026 penalizes high-emission imports. Polish producers with certified sustainable forestry assets gain landed cost advantages over Chinese competitors.
- Direct-to-Consumer Platforms:Black Red White's franchise density leaves gaps in digital-native purchasing. Configurator-driven sofa sales bypass showroom overhead.
Industry Challenges
- CNC Programming Talent Scarcity:Silesian vocational pipelines graduate manual machinists, not G-code specialists. Automated finishing cell utilization rates suffer from operator gaps.
- REACH Pre-Registration Backlogs:Upholstery flame-retardant chemistry requires substance-by-substance dossier filing. Mid-size suppliers face 18-month compliance timelines.
- Legacy ERP Integration:Polish furniture makers run on 1990s-era MRP systems. Real-time production scheduling for robotic cells demands wholesale platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Home Furniture Market |
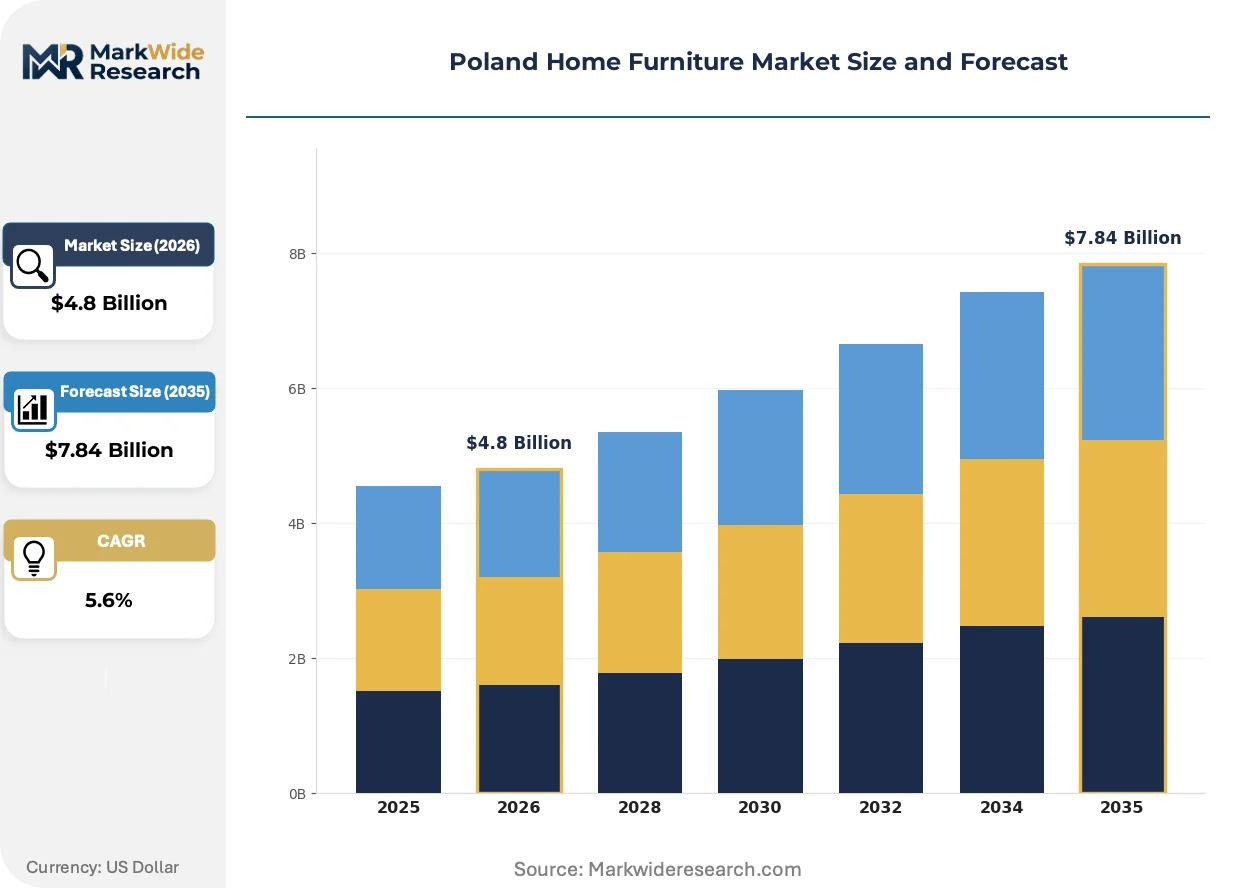
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Cabinets, Tables Material: Wood, Metal, Plastic, Upholstery End User: Households, Offices, Hotels, Retail Stores Distribution Channel: Online, Furniture Stores, Wholesale, Showrooms |
| Companies Covered | Szynaka-Meble Sp. z o.o., Nowy Styl, Black Red White SA, Gala Collezione Sp. z o.o., Lenart Meble Sp. z o.o., IKEA, Paged Meble SA, Meble Wojcik, Fabryki Mebli "Forte" SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Home Furniture Market Evolving Landscape
Digital fabrication and material chemistry advances are compressing production cycles while EU environmental mandates reconfigure competitive positioning. Polish manufacturers must simultaneously automate and decarbonize to defend export market access.
Robotic sanding and spraying cells are displacing manual finishing benches across Silesian production floors. Forte's adoption of six-axis lacquer application systems cuts cycle times by 40% while reducing overspray waste. Export-oriented producers now treat automation as a compliance prerequisite rather than cost option.
EU Ecodesign Directive 2009/125/EC implementation through 2027 mandates repairability indexing and recycled content disclosure. Polish cabinet makers must redesign joinery for disassembly and source post-industrial wood fiber. Warsaw-based retailers are already screening suppliers against preliminary durability scorecards.
Warsaw apartment renters increasingly purchase through augmented reality configurators rather than showroom visits. Black Red White's franchise network faces disintermediation pressure from direct-ship modular specialists. Masovian Voivodeship consumers under 35 complete 60% of furniture research via mobile visualization tools before contact.
Poland Home Furniture Market Segmentation
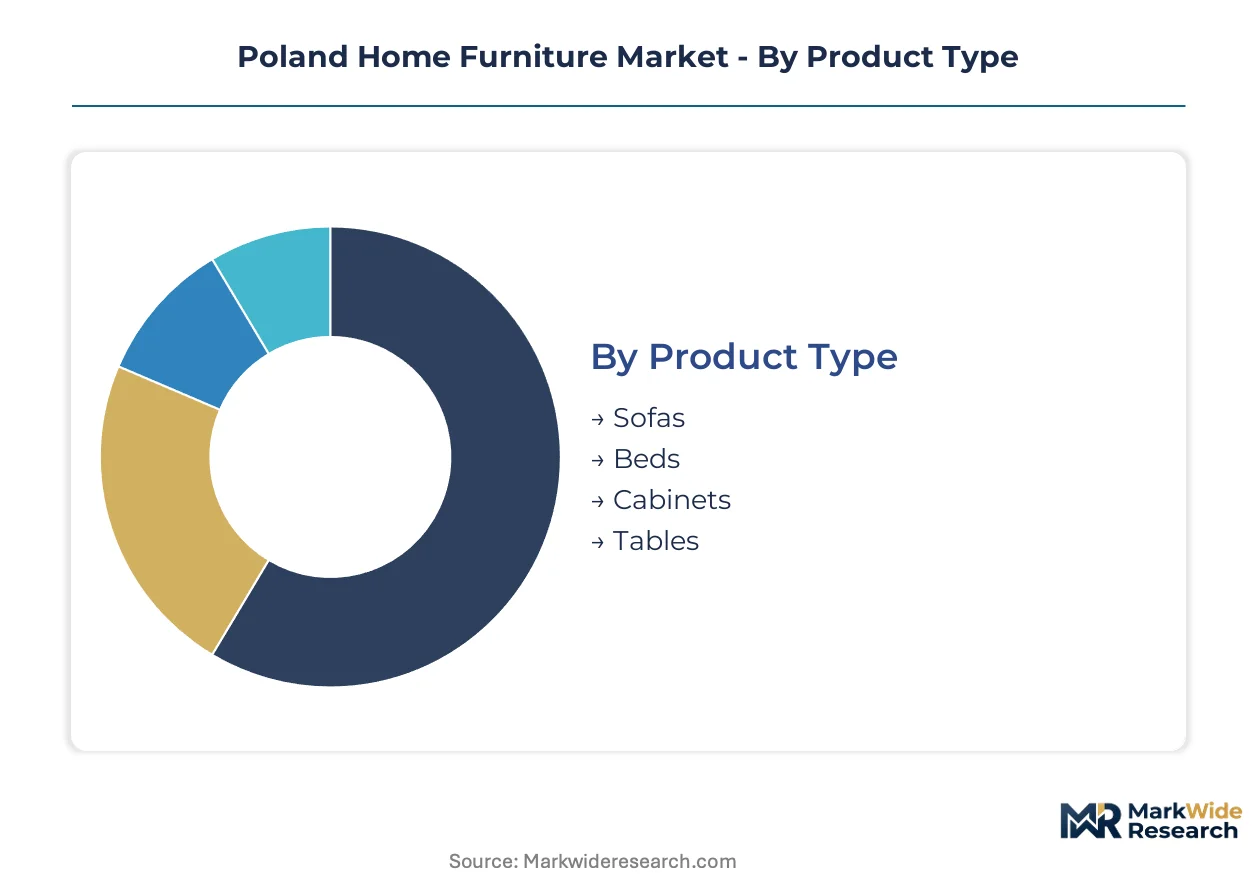
Poland's home furniture market segments reflect divergent compliance burdens and sourcing economics. Manufacturers must align product portfolios with FSC certification tiers, REACH chemical restrictions, and distribution channel-specific durability standards.
Product Type:
PKN's E1-E0 formaldehyde distinctions and EU Ecodesign repairability mandates create divergent reformulation costs across furniture categories.
- Sofas:Multi-component assemblies combining engineered wood frames, steel suspension systems, and polyurethane foam cushioning with textile or leather coverings. Warsaw apartment dwellers under 35 prioritize modular sectional configurations with removable covers to accommodate space constraints and replacement cycles. REACH flame-retardant compliance drives upholstery supplier consolidation.
- Beds:Platform and storage-integrated designs dominate Masovian Voivodeship demand, with MDF and particleboard frames commanding mass-market positioning against solid oak and beech premium tiers. Space-efficient lift-up storage mechanisms capture sub-50 square meter unit requirements.
- Cabinets:Kitchen and wardrobe systems fabricated from melamine-faced chipboard with ABS edge banding.
- Tables:Dining and occasional furniture spanning extendable mechanisms to fixed slab designs.
Sofas handle the majority of throughput; beds are climbing the fastest on share.
Material:
Raw material selection determines carbon-border exposure and State Forests chain-of-custody compliance depth.
- Wood:Engineered panels (MDF, particleboard, OSB) and solid timber (oak, beech, pine) processed through Polish sawmills. Silesian producers with captive particleboard mills control input costs; uncertified Baltic imports face Masovian retailer rejection.
- Metal:Powder-coated steel and aluminum framing for dining sets and bed support structures.
- Plastic:Polypropylene and polycarbonate components for seating shells and hardware housings.
- Upholstery:Woven and knitted textiles, leather hides, and synthetic coverings requiring REACH pre-registration for flame-retardant chemistry.
Wood dominates volume flows; upholstery is expanding most quickly on margin contribution.
End User:
Customer-type segmentation aligns with durability specification tiers and replacement cycle frequency.
- Households:Residential purchasers across Warsaw metropolitan area and secondary Polish cities, driving replacement demand for modular systems and comfort upgrades. Consumer research via mobile configurators now precedes 60% of purchase decisions among under-35 demographics.
- Offices:Corporate workspace fit-outs requiring ergonomic seating and collaborative furniture.
- Hotels:Hospitality procurement with accelerated depreciation schedules and standardized room packages.
- Retail Stores:Commercial display and storage fixtures with high-cycle durability requirements.
Households absorb the dominant share of production; hotels are gaining share fastest on contract renewal velocity.
Distribution Channel:
Channel economics separate inventory-heavy franchise operations from direct-ship digital models.
- Online:Configurator-driven platforms with augmented reality visualization tools bypassing showroom overhead. Masovian consumers complete pre-purchase research through mobile interfaces before order confirmation.
- Furniture Stores:Franchise and company-owned retail networks with local delivery and assembly services.
- Wholesale:Bulk procurement for property developers and hospitality chains.
- Showrooms:Experience-focused display spaces in Warsaw and regional capitals.
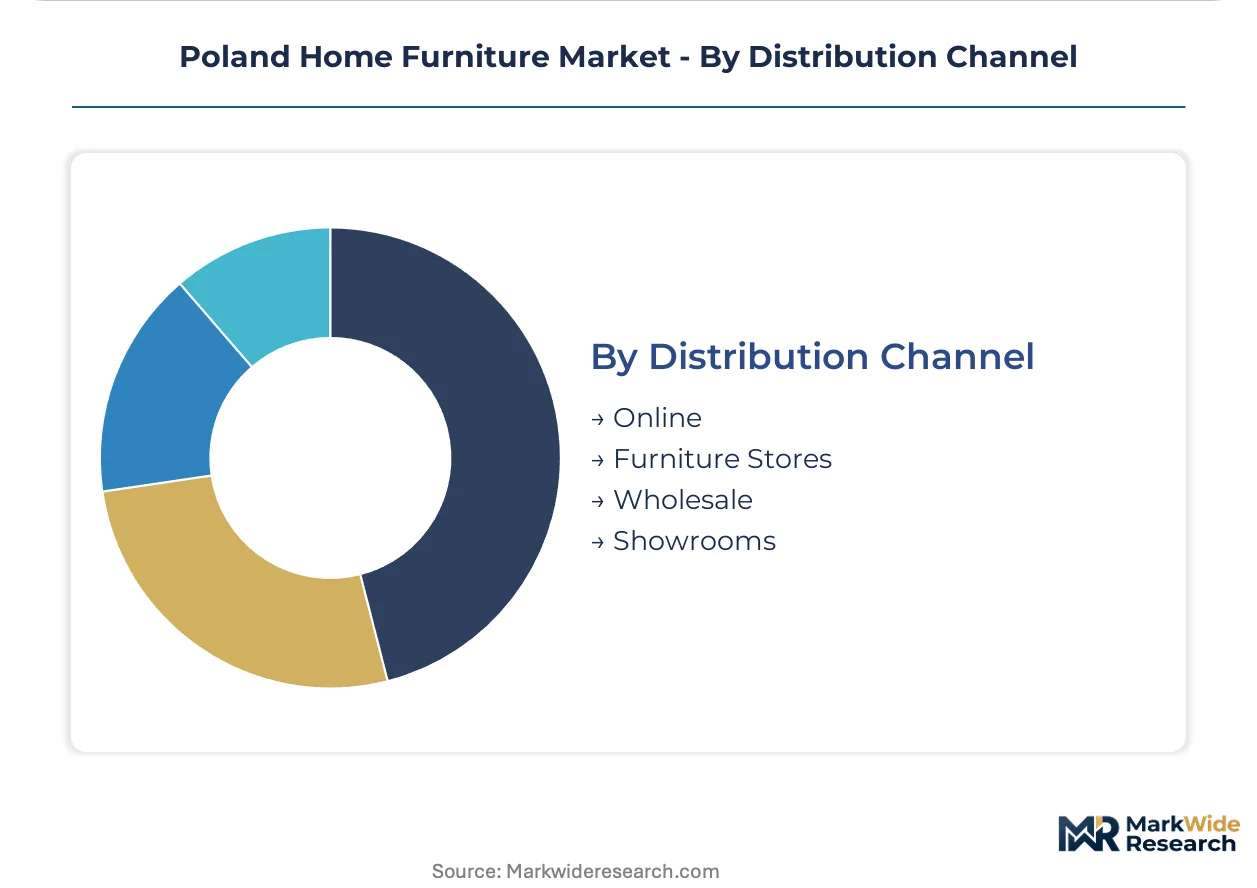
Furniture stores maintain the largest throughput position; online is accelerating fastest on customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish furniture producers command pricing premiums in Warsaw against Baltic assemblers, while Silesian manufacturers absorb automation costs to defend export competitiveness against Czech and Slovak rivals.
Masovian Voivodeship
Warsaw apartment dwellers under 35 drive modular system demand through sub-50 square meter housing stock. EU Ecodesign Directive mandates force local retailers to screen suppliers against preliminary durability scorecards. The Warsaw metropolitan area concentrates configurator-driven purchasing platforms that bypass traditional showroom networks.
Silesian Voivodeship
Robotic finishing cells and automated CNC production lines dominate capital allocation decisions among export-oriented fabricators. Poland's State Forests chain-of-custody standards intersect with EU Timber Regulation due diligence requirements. The Katowice-Gliwice corridor hosts integrated particleboard mills that control raw material cost structures for captive furniture production.
Łódź Voivodeship
Underutilized textile infrastructure from 1990s apparel sector collapse awaits furniture sector conversion for upholstery cutting and sewing clusters. REACH chemical restrictions on adhesive formaldehyde limits force reformulation investments among regional suppliers. The city of Łódź anchors dormant fabric processing capacity that mid-tier sofa assemblers could activate.
Greater Poland Voivodeship
Poznań-based distributors face margin compression from direct-to-consumer digital platforms penetrating secondary Polish cities. PKN standardization requirements for E1-E0 grade distinctions create compliance barriers for small workshops. The Poznań-Śrem axis concentrates wholesale procurement networks serving hospitality and retail fit-out segments.
Pomeranian Voivodeship
Gdańsk port logistics facilitate Baltic timber imports that compete with domestic State Forests certified supply. Carbon Border Adjustment Mechanism phase-in from 2026 reshapes landed cost calculations for Chinese competitor imports. The Tricity metropolitan area tests augmented reality visualization tools for furniture pre-purchase research among younger demographics.
Poland Home Furniture Market Competitive Landscape
Concentration sits with integrated mill operators and franchise network owners while mid-tier assemblers face raw material cost disadvantages. Three strategic archetypes define competitive positioning: captive particleboard producers controlling upstream supply, dense retail franchise operators capturing secondary city demand, and robotic automation adopters reducing finishing cycle times. M&A activity targets distressed textile infrastructure for upholstery conversion, while strategic partnerships with digital configurator platforms disintermediate traditional showroom economics.
Among Polish-registered fabricators, Szynaka-Meble Sp. z o.o., Black Red White SA, and Fabryki Mebli "Forte" SA occupy distinct archetype positions. Szynaka-Meble exemplifies the integrated mill operator with captive particleboard production. Black Red White represents the franchise density model spanning secondary urban markets. Forte sits within the automation-adopter tier with robotic finishing cell deployment. These three anchors illustrate how capital structure and distribution choices separate competitive tiers rather than product differentiation alone.
| Leading Market Players |
|---|
| Szynaka-Meble Sp. z o.o. |
| Nowy Styl |
| Black Red White SA |
| Gala Collezione Sp. z o.o. |
| Lenart Meble Sp. z o.o. |
| IKEA |
| Paged Meble SA |
| Meble Wojcik |
| Fabryki Mebli "Forte" SA |
| Others |
Value Network & Pricing Analysis
Waterborne coating chemistry replacing solvent-based systems simultaneously relocates finishing capacity toward Silesian robotic clusters and compresses margin structures for manual bench operators. Polish manufacturers absorbing EU REACH pre-registration costs for reformulated polyurethane dispersions face divergent pricing power depending on automation depth and captive raw material control.
Pricing Analysis
The customization-premium spread separates configurator-driven modular sofa orders from standard catalog SKUs stocked through Black Red White franchise networks. Three-tier pricing structure across FSC-certified premium, PKN E1-grade standard, and uncertified economy levels reflects chain-of-custody investment depth. Cost compression in particleboard-framed storage beds is intensifying because three integrated mills control domestic MDF supply. Warsaw apartment renters under 35 exhibit highest price sensitivity, while hospitality procurement in Masovian Voivodeship prioritizes durability specifications over unit economics.
Supply Chain Analysis
Poland and Ukraine anchor solid timber flows through the Brest corridor, while Baltic states supply uncertified beech and oak alternatives facing Masovian retailer rejection. Engineered wood panels, steel suspension hardware, and REACH-compliant upholstery textiles constitute core input dependencies. Single-source vulnerability concentrates in Ukrainian hardwood supply disrupted by corridor instability. Distribution runs through dense franchise networks in secondary cities alongside direct-to-consumer platforms bypassing showroom overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polish furniture manufacturing suffers acute scarcity of G-code programming talent and robotic cell operation skills, constraining automation adoption among mid-tier assemblers. This capability gap separates integrated mill operators from capital-starved workshops unable to absorb REACH compliance investments.
For Market Incumbents: Fortify market position by deepening captive particleboard production and securing State Forests chain-of-custody certification ahead of EU Carbon Border Adjustment Mechanism phase-in. Accelerate robotic finishing cell deployment to preempt margin erosion from Czech and Slovak export competitors. Prioritize ERP platform replacement to enable real-time production scheduling for automated lines. For New Entrants and Emerging Players: Differentiate on digital-native distribution by activating Łódź dormant textile infrastructure for upholstery cutting and sewing clusters. Target the configurator-driven sofa segment where Black Red White franchise density leaves coverage gaps. Pursue direct-to-consumer augmented reality platforms bypassing traditional showroom economics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier assemblers lacking capital for adhesive reformulation and resin system upgrades. Long-term viability favors producers with backward integration into sustainable forestry assets and certified waterborne coating capabilities. Monitor Ukrainian hardwood corridor stability as inflection indicator for solid timber input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Finishing Cell Deployment | Six-axis lacquer application cuts cycle times and reduces overspray waste for Silesian exporters. |
| FSC Chain-of-Custody Certification | State Forests traceability creates competitive moats against uncertified Baltic imports under EU Timber Regulation. |
| ERP Platform Modernization | Real-time scheduling integration enables automated cell utilization rates that 1990s-era MRP systems cannot support. |
| Direct-to-Consumer Platform Launch | Configurator-driven sales bypass franchise overhead and capture Warsaw apartment renter research behavior. |
| Łódź Textile Infrastructure Conversion | Dormant apparel cutting and sewing capacity awaits activation for upholstery supplier consolidation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Polish Committee for Standardization technical documentation, EU Ecodesign Directive implementation guidance, and State Forests chain-of-custody audit records. Primary interviews engaged furniture manufacturing plant managers, procurement leads at Masovian retail networks, upholstery chemical suppliers, and CNC automation specialists. Secondary validation drew from customs trade data, PKN regulatory filings, and REACH pre-registration databases. Bottom-up production volume estimates triangulated against top-down consumer expenditure patterns across the analysis window.
Segmentation dimensions modeled include product category, material certification tier, end-user type, and distribution channel structure across the projection horizon. CAGRs derived from historical shipment data, replacement cycle frequencies, and housing stock formation rates in Warsaw metropolitan area. Industry-specific inputs incorporated EU Carbon Border Adjustment Mechanism phase-in assumptions and waterborne coating adoption curves.
Material uncertainties — Ukrainian hardwood supply disruption, REACH enforcement intensity, and robotic programming talent pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and automation capital availability. Recalibration cycles align with material shifts in EU Ecodesign Directive implementation timelines and Baltic timber import certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
US Secondary Wood Products Market
Furniture
Indonesia Furniture Market
Furniture
Massive Wood Slabs Market
Furniture
US School Furniture Market
Furniture
HORECA Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Bean Bag Chairs Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Italy Office Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
United States Home Furniture Market
Furniture
Rattan Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
United States Luxury Furniture Market
Furniture
China Furniture Market